
 Intracardiac Echocardiography (ICE) Market | 2026-2036
Intracardiac Echocardiography (ICE) Market Size, Share, and Industry Trends Forecast 2026-2036
Intracardiac Echocardiography (ICE) Market Foresight
The pool of certified cardiac electrophysiologists is collapsing across multiple healthcare systems, forcing device manufacturers to design simpler catheter interfaces and automated imaging workflows. Siemens Healthineers leverages integrated imaging platforms to reduce operator training burden in complex ablation cases. Abbott Laboratories anchors its position through dedicated ICE catheter portfolios optimized for structural heart navigation.
Intracardiac echocardiography deploys ultrasound-emitting catheters positioned directly within cardiac chambers to generate real-time two-dimensional or three-dimensional images at frequencies typically ranging from 5 to 10 MHz, primarily serving electrophysiology and interventional cardiology procedures requiring direct visualization without transesophageal probe placement. The product type dimension shows 3D ICE systems capturing disproportionate investment as hospitals seek volumetric renderings for structural heart interventions, while electromechanical technology dominates current installed bases though hybrid architectures represent the fastest-expanding engineering category. Application demand clusters heavily in electrophysiology, where atrial fibrillation ablation volumes sustain recurring catheter consumption, whereas structural heart procedures command premium pricing tiers due to procedural complexity.
FDA premarket notification requirements govern ICE catheter safety validations in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence standards for reusable and single-use intracardiac probes entering European markets. Japan's PMDA maintains distinct biocompatibility testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for intraprocedural imaging across Medicare, national health systems, and private payers to anticipate volume shifts.
Market Dynamics
The collapse of certified cardiac electrophysiologist pools is forcing catheter manufacturers to automate imaging workflows and simplify operator interfaces, fundamentally restructuring how ICE systems penetrate hospital systems.
Growth Catalysts
- Electrophysiology lab expansion:Hospital systems in Germany are building dedicated cardiac centers that mandate real-time intracardiac imaging for complex ablation procedures.
- FDA 510(k) streamlining:The FDA's premarket notification pathway for novel catheter designs accelerates product introductions in the United States without requiring full PMA submissions.
- Atrial fibrillation procedural volumes:Sustained AF ablation case growth in specialized cardiac units drives recurring single-use catheter consumption.
Market Restraints
- Single-use catheter cost structure:Premium pricing for disposable ICE probes creates budget pressure on hospital cath lab procurement committees.
- EU MDR clinical evidence requirements:The EU Medical Device Regulation imposes enhanced biocompatibility and performance documentation standards that extend registration timelines for reusable intracardiac probes.
- Transesophageal echocardiography substitution:Established TEE imaging protocols in non-specialized centers limit ICE adoption for routine structural heart assessments.
Strategic Opportunities
- Japan PMDA registration pathway:Distinct biocompatibility testing protocols create first-mover advantages for manufacturers investing in localized regulatory infrastructure.
- Hybrid electromechanical architectures:Convergence of traditional electromechanical ICE with solid-state phased array technology opens premium pricing tiers for volumetric cardiac rendering.
- Structural heart navigation:Left atrial appendage closure and mitral valve repair procedures command premium catheter pricing due to procedural complexity.
Industry Challenges
- Electrophysiologist certification timelines:Fellowship program bottlenecks restrict the pipeline of operators qualified to interpret real-time intracardiac ultrasound.
- Reimbursement code fragmentation:Divergent intraprocedural imaging coverage policies across Medicare, commercial payers, and national health systems create pricing uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intracardiac Echocardiography (ICE) Market |
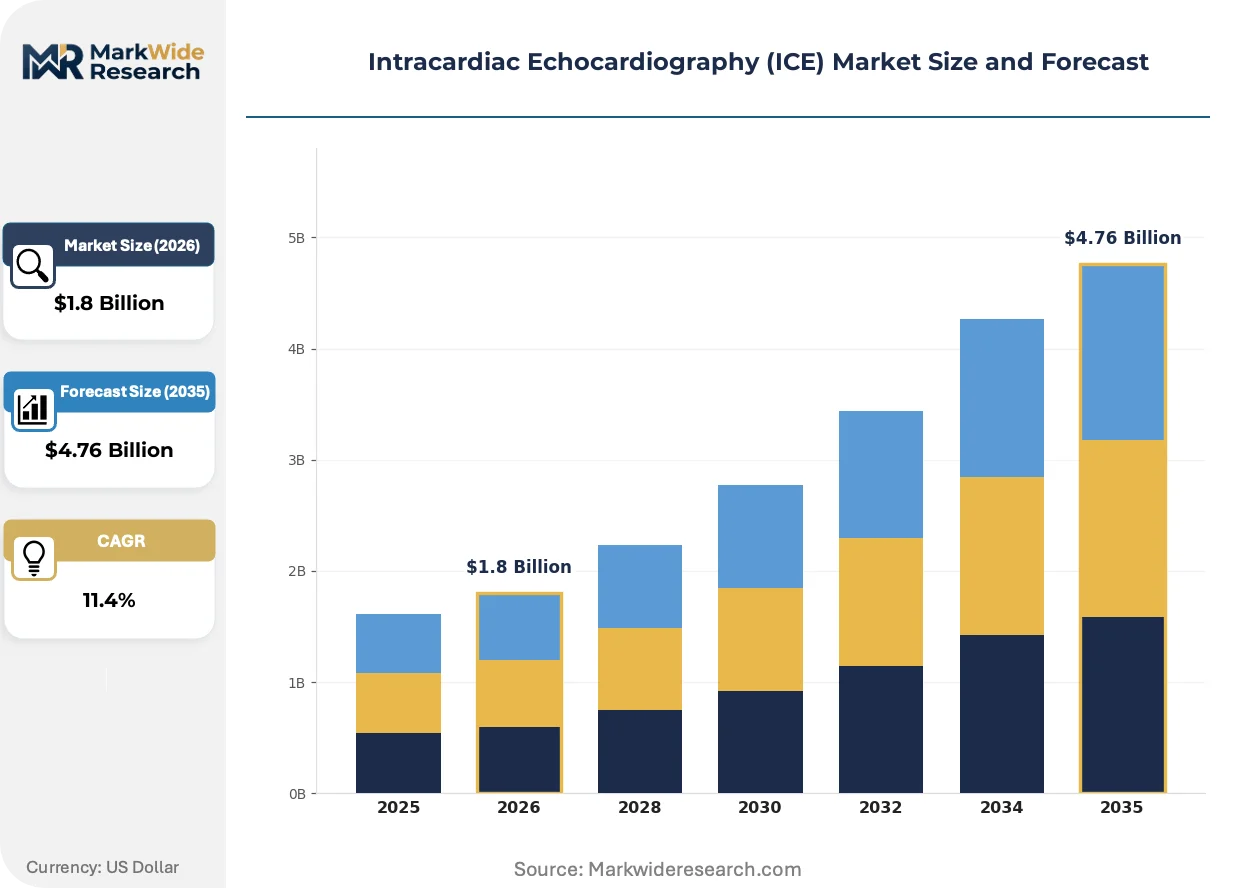
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D ICE, 3D ICE, Transesophageal, Intracardiac Catheter Technology: Electromechanical, Optical, Hybrid, Ultrasound End User: Cardiology Clinics, Hospitals, Research Institutions, Diagnostic Centers Application: Structural Heart Procedures, Electrophysiology, Congenital Heart Disease, Valve Repair |
| Companies Covered | Siemens Healthineers, Boston Scientific Corporation, Abbott Laboratories, Johnson and Johnson Medtech, Mindray Medical International, GE Healthcare, Philips Healthcare, Edwards Lifesciences Corporation, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intracardiac Echocardiography (ICE) Market Shifts & Advancements
Real-time volumetric imaging capabilities are reshaping catheter design priorities as hospitals demand three-dimensional cardiac chamber visualization without transesophageal probe placement.
Three-dimensional ICE systems with phased-array transducers are displacing conventional two-dimensional electromechanical platforms in structural heart programs. Academic medical centers in the United States and Germany are adopting volumetric rendering for left atrial appendage closure guidance. This displacement is compressing the addressable market for legacy 2D-only catheter portfolios and forcing manufacturers to accelerate R&D timelines for hybrid architectures.
The EU Medical Device Regulation's enhanced clinical evidence standards for reusable intracardiac probes are extending European market entry timelines. Foreign manufacturers must now submit comprehensive biocompatibility and performance validation data that previously satisfied notified bodies under the MDD framework. Single-use catheter portfolios are capturing disproportionate investment as companies route around MDR complexity through disposable product strategies.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases. Cath lab directors in Germany and the United States are negotiating separate maintenance agreements and software upgrade pathways. This behavioral shift is most visible in electrophysiology lab expansions where capital budgets and operational expenditures face distinct approval thresholds.
Intracardiac Echocardiography (ICE) Market Segmentation
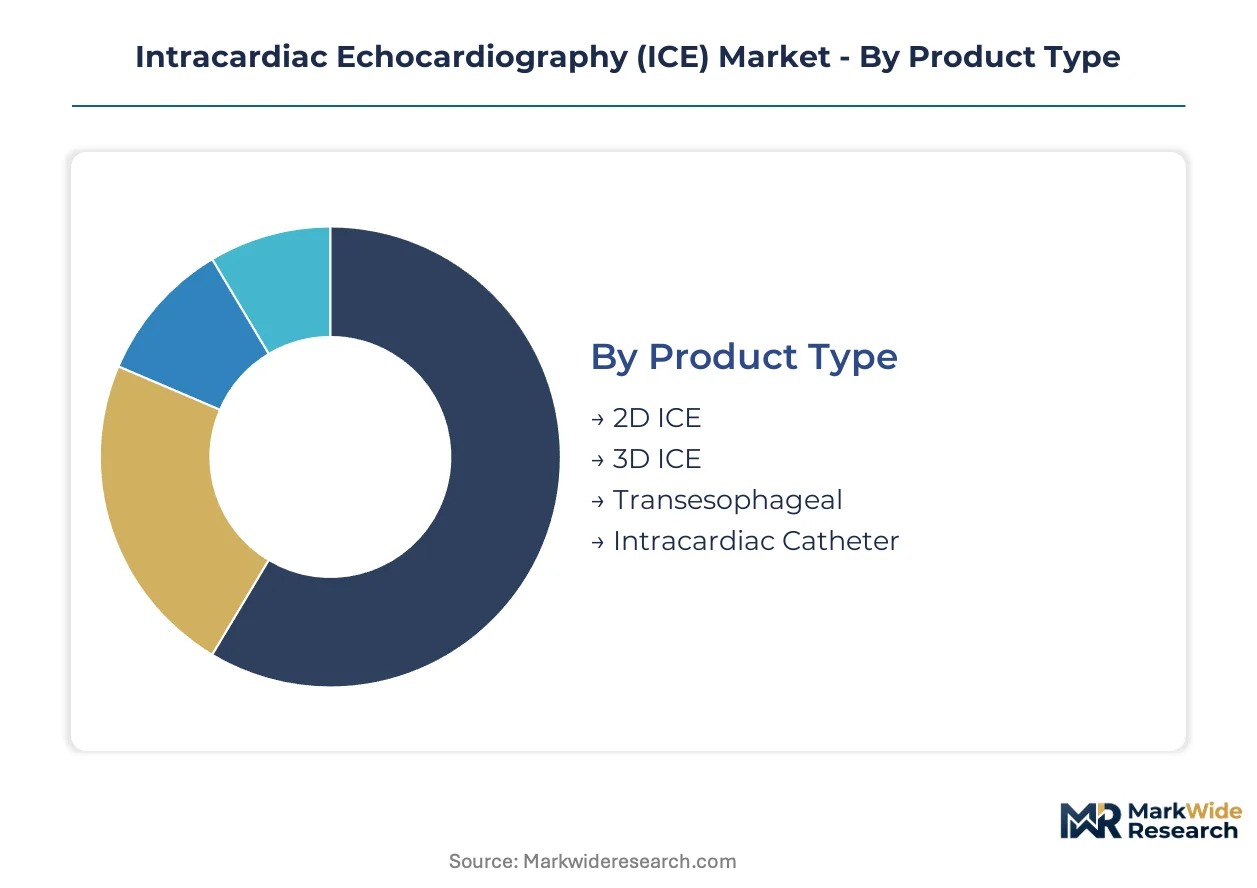
ICE market segmentation reveals distinct procurement patterns across product tiers and clinical settings. Channel strategies diverge sharply between capital-intensive 3D systems and disposable catheter consumables.
Product Type:
Capital equipment flows through integrated health system tenders, while single-use catheters move via specialized cardiac distributor networks.
- 3D ICE:Volumetric phased-array systems generate real-time cardiac chamber renderings at 5-10 MHz frequencies. German specialized cardiac centers and US academic medical centers drive demand as left atrial appendage closure volumes expand.
- 2D ICE:Conventional electromechanical platforms remain the workhorse for routine electrophysiology labs. Budget-constrained hospital cath labs in secondary markets sustain this segment through refurbished equipment channels.
- Transesophageal:External probe alternatives serve non-specialized centers without intracardiac catheter expertise.
- Intracardiac Catheter:Single-use disposable probes dominate recurring revenue streams in high-volume ablation centers.
2D ICE dominates installed base. 3D ICE is where expansion concentrates.
Technology:
Cost tier stratification separates premium hybrid architectures from mature electromechanical platforms.
- Hybrid:Convergence of electromechanical positioning with solid-state phased arrays enables volumetric imaging without mechanical steering. Research institutions in Germany and the United States pilot these systems for structural heart navigation.
- Electromechanical:Rotating single-element transducers constitute the current installed base majority. Cardiology clinics with established electrophysiology programs represent the core replacement market.
- Optical:Fiber-optic ultrasound transmission reduces catheter diameter for pediatric applications.
- Ultrasound:Standard piezoelectric imaging cores serve baseline diagnostic functions.
Electromechanical technology captures current volume. Hybrid architectures are climbing the fastest.
End User:
Customer type determines pricing elasticity and service contract bundling intensity.
- Hospitals:Integrated health systems negotiate enterprise-wide ICE platform standardization with bundled maintenance agreements. Electrophysiology lab expansion in Germany and the United States concentrates demand in tertiary cardiac centers.
- Cardiology Clinics:Independent specialty practices prioritize portable 2D systems with per-procedure catheter economics. Outpatient ablation volume growth in US metropolitan markets sustains this channel.
- Diagnostic Centers:Imaging-focused facilities without interventional capabilities represent a limited addressable market.
- Research Institutions:Academic medical centers pilot next-generation hybrid architectures for preclinical validation.
Hospitals command procurement volume. Cardiology clinics represent the steepest expansion trajectory.
Application:
Procedure complexity dictates catheter consumption rates and imaging system specifications.
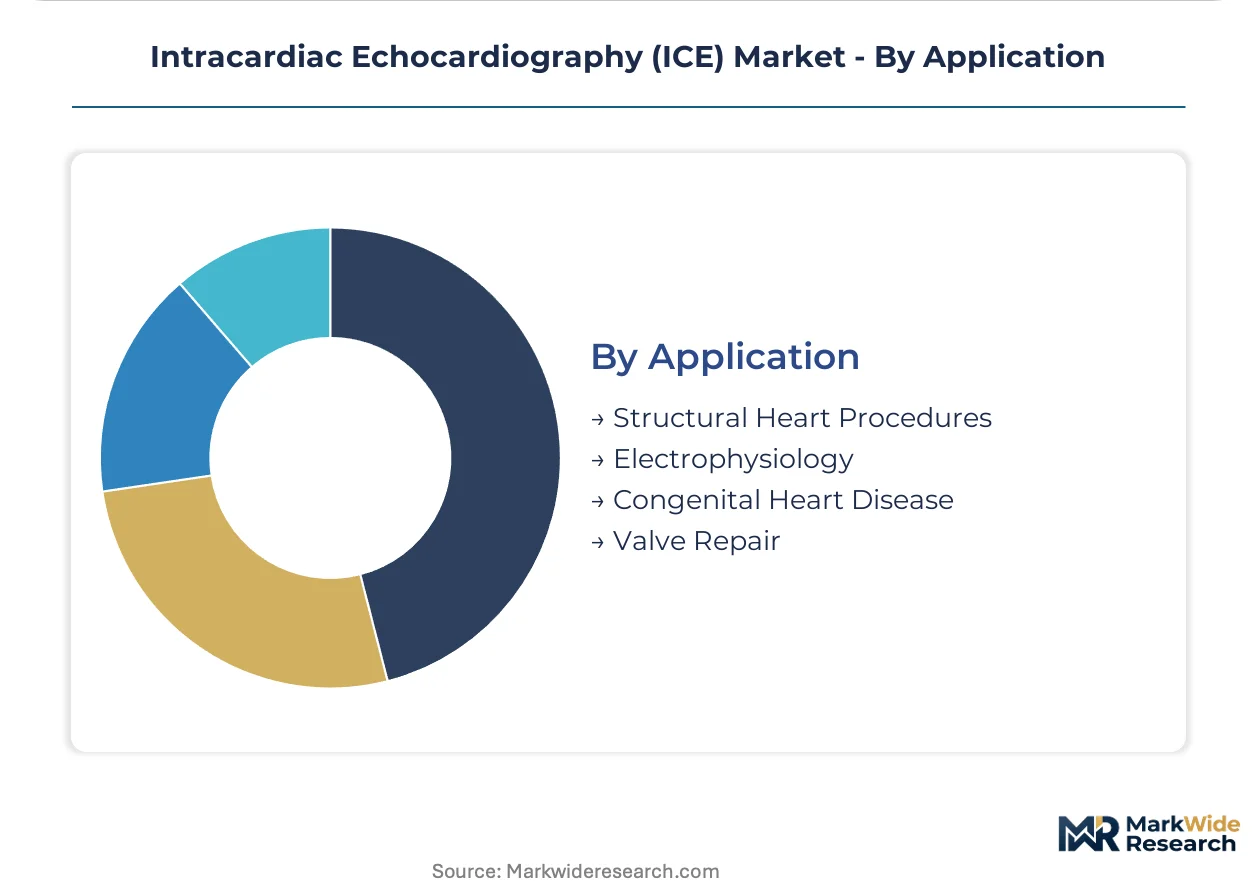
- Electrophysiology:Atrial fibrillation ablation sustains the highest single-use catheter consumption rates. Specialized cardiac units in Germany mandate real-time intracardiac guidance for complex substrate mapping.
- Structural Heart Procedures:Left atrial appendage closure and mitral valve interventions command premium 3D system utilization. US academic medical centers drive adoption for transseptal puncture guidance.
- Valve Repair:Percutaneous mitral and tricuspid interventions require volumetric rendering capabilities.
- Congenital Heart Disease:Pediatric applications demand smaller catheter profiles with specialized acoustic windows.
Electrophysiology anchors recurring revenue. Structural heart procedures concentrate premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States deploy ICE systems at the highest per-procedure intensity worldwide, while Japan and emerging Asian markets restrict utilization through divergent reimbursement frameworks and operator certification requirements.
United States
Academic medical centers in Boston and Cleveland drive 3D ICE adoption for structural heart navigation. FDA 510(k) pathways accelerate catheter introductions without full PMA submissions. Electrophysiology lab expansions at Cleveland Clinic and Mayo Clinic anchor premium system procurement.
Germany
Specialized cardiac centers in Munich and Heidelberg mandate real-time intracardiac imaging for complex ablation workflows. EU MDR enhanced clinical evidence standards extend registration timelines for reusable probes. The Baden-Württemberg cluster concentrates hybrid architecture pilot programs.
Japan
PMDA biocompatibility testing protocols create extended registration timelines for foreign manufacturers. Tokyo and Osaka academic hospitals pilot next-generation phased-array systems. METI funding for advanced medical devices supports localized regulatory infrastructure investment.
China
NMPA streamlined pathways for innovative medical devices accelerate domestic catheter approvals. Shanghai and Beijing tertiary hospitals expand electrophysiology capacity. NMPA distinct technical documentation requirements favor manufacturers with localized clinical trial networks.
United Kingdom
NHS specialized commissioning frameworks concentrate ICE utilization in designated cardiac centers. London and Manchester academic hospitals drive structural heart procedure volumes. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment pathways for catheter manufacturers.
Intracardiac Echocardiography (ICE) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling imaging platform ecosystems and the lower tier competing on catheter consumables and regional service density. Siemens Healthineers and GE Healthcare anchor the integrated imaging platform segment, while Abbott Laboratories and Boston Scientific Corporation occupy the interventional catheter specialist tier. Competitive moves concentrate on automated imaging workflow development and strategic partnerships with electrophysiology lab networks.
Within the integrated imaging tier, Siemens Healthineers and GE Healthcare exemplify platform consolidation strategies that bundle ICE capability with broader cardiovascular imaging portfolios. Abbott Laboratories and Boston Scientific Corporation represent the interventional specialist archetype, focusing on catheter design optimization for structural heart navigation. These four companies collectively span German, American, and Irish corporate origins, reflecting the geographic concentration of cardiovascular device innovation.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Johnson and Johnson Medtech |
| Mindray Medical International |
| GE Healthcare |
| Philips Healthcare |
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
Ninety-to-120-day lead times for phased-array transducer components concentrate procurement leverage among German and Japanese precision manufacturers, amplifying pricing power for hybrid ICE systems while compressing margins on legacy electromechanical platforms. This inventory dynamic intersects with FDA 510(k) clearance timelines to create tiered cost structures across catheter portfolios.
Pricing Analysis
Long-term service contracts dominate hospital system procurement, with bundled maintenance agreements spanning capital equipment and disposable catheter offtake. Price differentiation hinges on volumetric imaging certification tiers and after-sales service bundling intensity. Cost compression in 2D electromechanical segments intensifies as refurbished equipment channels expand in secondary US markets. Cardiology clinics exhibit highest price sensitivity due to per-procedure economics, while academic medical centers absorb premium 3D system pricing for structural heart navigation capabilities.
Supply Chain Analysis
Just-in-time inventory strategies prevail for single-use catheter consumables, whereas strategic stockpiling characterizes phased-array transducer procurement given sole-source dependencies. Manufacturing concentration centers on Germany, Japan, and the United States for precision electromechanical components and solid-state acoustic arrays. Supply chains draw from piezoelectric ceramic substrates, specialized catheter sheathing polymers, and miniaturized steering mechanisms. Single-source vulnerability in phased-array transducer fabrication creates structural risk exposure. Distribution runs through specialized cardiac device distributors serving hospital cath lab networks and integrated health system tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA 510(k) clearance databases and EU MDR technical documentation create asymmetric barriers against unproven entrants.
For Market Incumbents: Shield installed base positions by deepening backward integration into phased-array transducer manufacturing and accelerating hybrid architecture R&D pipelines. Transesophageal echocardiography substitution in non-specialized centers represents the primary substitution threat. Channel control through exclusive hospital system partnerships constitutes the critical defensive lever against emerging Asian manufacturers. For New Entrants and Emerging Players: Lead with disposable catheter portfolios routed around EU MDR complexity through single-use product strategies rather than competing on capital equipment. Pediatric congenital heart applications present the most penetrable white space given unmet demand for smaller catheter profiles. Reimbursement strategy alignment with emerging Medicare intraprocedural imaging codes offers the clearest go-to-market pathway. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and PMDA clearance databases compound competitive insulation over extended product lifecycles. Acquisition targets should display hybrid electromechanical-solid-state patent portfolios and established notified body relationships. The signal to watch is fellowship program expansion rates, as electrophysiologist supply recovery would decompress automation urgency and shift value capture toward premium imaging platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification pathways compress time-to-revenue for novel catheter geometries in US electrophysiology labs. |
| CE Marking Pathway Investment | EU MDR technical documentation capabilities differentiate compliant manufacturers from competitors facing extended notified body timelines. |
| Hospital System Partnership | Enterprise-wide standardization agreements with Cleveland Clinic and Mayo Clinic anchor premium 3D system deployment. |
| Software Companion Development | Automated imaging workflow integration reduces operator training burden and addresses collapsing electrophysiologist certification pipelines. |
| Reimbursement Strategy | Medicare intraprocedural imaging code alignment determines volume accessibility across US hospital cath lab procurement committees. |
Research Methodology
A spread of perspectives from electrophysiology lab directors, hospital purchasing committee members, biomedical engineers, and catheter manufacturing executives converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement records, and CMS reimbursement code filings. Bottom-up catheter volume estimates and top-down health system capital expenditure patterns were triangulated to anchor market sizing.
Segmentation dimensions modeled include product type tier, technology architecture, end-user facility category, and application procedure complexity across the projection horizon. CAGRs were derived from procedural volume trajectories and per-procedure catheter consumption rates, with electrophysiology ablation case growth and structural heart intervention adoption curves serving as primary forecast inputs.
Underlying assumptions cover electrophysiologist certification pipeline recovery, EU MDR implementation stability, and Medicare reimbursement continuity, with deviation risk concentrated in fellowship program expansion shortfalls and transesophageal echocardiography substitution acceleration. Revision becomes warranted when electrophysiologist supply constraints cross thresholds that fundamentally alter automation investment calculus.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
North America Cardiac Rhythm Management Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Global Cardiac Restoration Systems Market