
 Peripheral Vascular Stents Market | 2026-2036
Peripheral Vascular Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Vascular Stents Market Outlook
Hospital procurement of peripheral vascular stents is hardening as cardiovascular service lines consolidate purchasing authority across integrated delivery networks. Abbott Laboratories sustains technology leadership in drug-eluting platforms through deep clinical trial investment. Medtronic Plc anchors global manufacturing scale with broad bare-metal and covered stent portfolios. Boston Scientific Corp differentiates via specialized endovascular expertise in complex lesion applications.
Peripheral vascular stents are tubular mesh implants typically fabricated from cobalt-chromium, nitinol, or biodegradable polymers, designed to scaffold arterial walls and restore patency in femoropopliteal, iliac, and renal vessels following angioplasty. Drug-eluting stents command premium positioning due to superior restenosis outcomes in long-segment peripheral artery disease, while bare-metal stents retain volume in cost-constrained settings and shorter lesions. Covered stents occupy a specialized niche for aneurysmal or perforated vessel indications where exclusion of blood flow from the arterial wall proves critical.
FDA premarket approval pathways and EU MDR conformity assessments shape competitive access by demanding robust randomized trial evidence for novel stent platforms. The FDA's device recall authority and EMA post-market surveillance requirements enforce sustained quality systems across manufacturing operations. Stakeholders must monitor evolving CMS national coverage determinations and NICE technology appraisals as these reimbursement gatekeepers increasingly tie payment to comparative effectiveness data against alternative revascularization strategies.
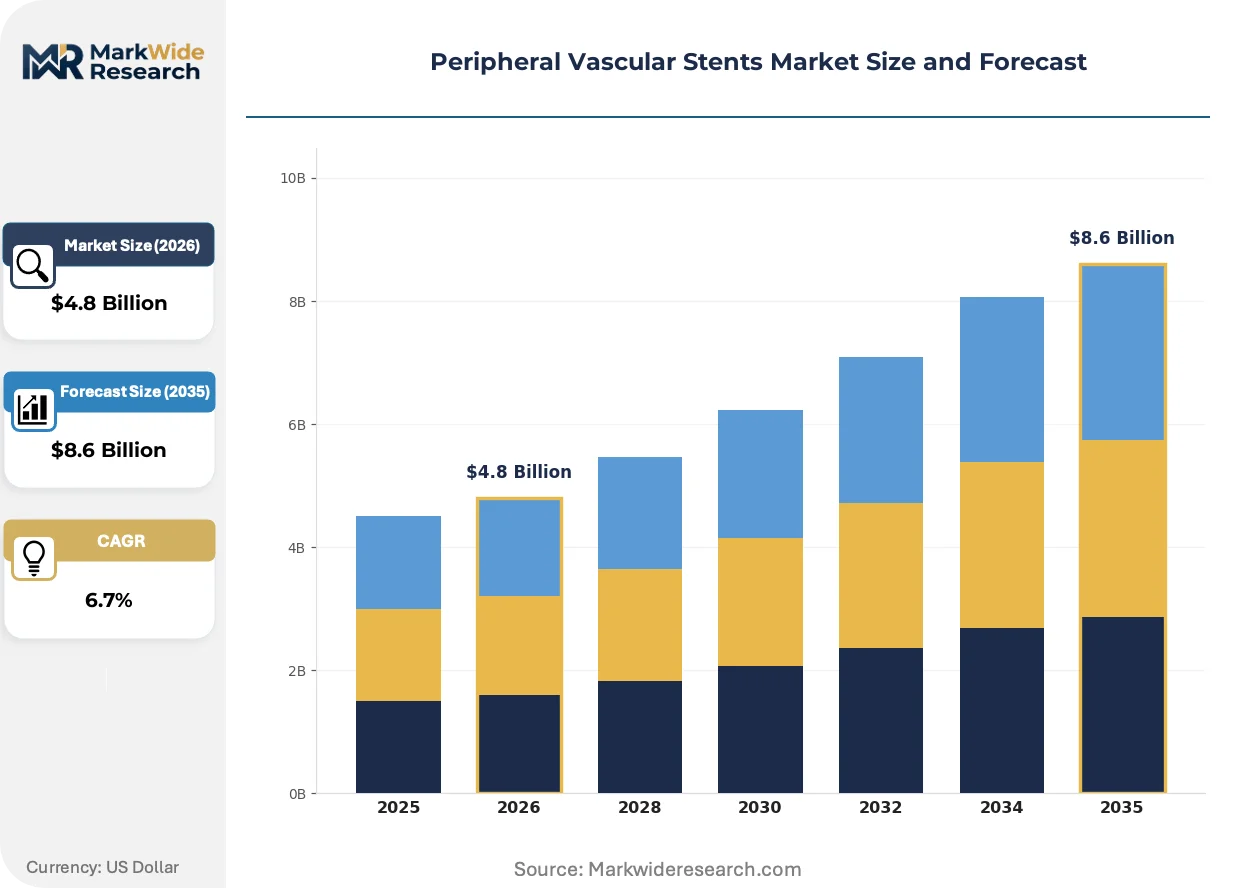
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is hardening price discipline and compressing vendor margins for peripheral vascular stent suppliers.
Growth Catalysts
- Aging demographics in Japan:The country's super-aged population sustains procedural volumes for femoropopliteal interventions, with reimbursement pathways under METI guidance supporting device utilization.
- Drug-eluting platform maturation:Polymer-based paclitaxel delivery systems demonstrate superior patency outcomes in long-segment lesions, pulling demand from bare-metal alternatives in tertiary care centers.
- FDA breakthrough device designation:Expedited review pathways for biodegradable scaffolds accelerate clinical validation timelines and compress competitive entry barriers for novel platforms.
Market Restraints
- Nitinol raw material concentration:Supply of nickel-titanium alloy feedstock concentrates among specialty metallurgical processors in the United States and Germany, exposing stent manufacturers to input volatility and long-term contracting rigidities.
- EU MDR clinical evidence requirements:The transition from MDD to MDR mandates costly post-market surveillance infrastructure and extended conformity assessment timelines, elevating capital requirements for CE marking maintenance.
- Endovascular atherectomy substitution:Plaque debulking technologies in calcified lesions reduce stent dependency in specific anatomies, constraining addressable procedure volumes in high-complexity cases.
Strategic Opportunities
- Underpenetrated Indian market:CDSCO regulatory harmonization with global standards and expanding private hospital networks in Mumbai and Delhi create whitespace for drug-eluting stent penetration beyond metropolitan tier-one cities.
- Renal artery stenosis applications:Expanding indications for small-vessel stenting in hypertension management represent an emerging procedural category with limited established competition.
- Japan PMDA Sakigake designation:Priority review incentives for first-in-class devices accelerate time-to-reimbursement for biodegradable polymer platforms targeting below-the-knee indications.
Industry Challenges
- Interventional cardiologist training pipelines:Procedural complexity in infrapopliteal and pedal access routes demands specialized fellowship pathways that academic medical centers struggle to scale.
- Bioresorbable scaffold fatigue testing:ISO 25539-2 validation protocols for polymer degradation kinetics require extended bench-top and animal studies, compressing development timelines against investor return expectations.
- Legacy EHR integration:Device tracking mandates under FDA UDI requirements force interoperability investments with hospital information systems that lack standardized implant registry modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Vascular Stents Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Drug-Eluting Stents, Bare-Metal Stents, Bioabsorbable Stents, Covered Stents Material: Plastic, Metallic, Composite, Polymer End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Deployment Method: Transluminal Angioplasty, Endovascular Surgery, Open Surgery, Balloon Angioplasty |
| Companies Covered | Boston Scientific Corp, Abbott Laboratories, Medtronic Plc, W.L. Gore & Associates Inc, CR Bard Inc, Terumo Corp, Getinge AB, Cordis Corp, Biotronik SE & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Vascular Stents Market Strategic Shifts
Biodegradable polymer scaffolds and point-of-care imaging integration are reshaping intervention workflows and post-procedure surveillance economics.
LimFlow percutaneous deep vein arterialization is decentralizing revascularization options for no-option chronic limb ischemia patients previously relegated to amputation. Vascular surgery departments at academic medical centers in Germany and the United States are adopting this technique following positive 12-month limb salvage data. The technology is decentralizing high-complexity case volumes from traditional bypass centers into catheterization labs with advanced imaging capabilities.
EU MDR Article 117 requirements for notified body involvement in drug-device combination reviews are extending time-to-market for paclitaxel-eluting platforms by 18-24 months. Manufacturers must now submit comprehensive clinical evaluation reports against state-of-the-art benchmarks rather than predicate device equivalency. Small and mid-cap stent developers in Switzerland and Ireland are responding by prioritizing bare-metal platform iterations while deferring drug-eluting pipeline investments.
Integrated delivery networks in the United States are consolidating stent purchasing through centralized value analysis committees, displacing individual physician preference item selection. Cardiovascular service line administrators now mandate head-to-head patency data and total cost-of-care analytics before formulary inclusion. This behavioral shift is most visible in California and Texas health systems where Kaiser Permanente and HCA have implemented standardized device tiering protocols.
Peripheral Vascular Stents Market Segmentation
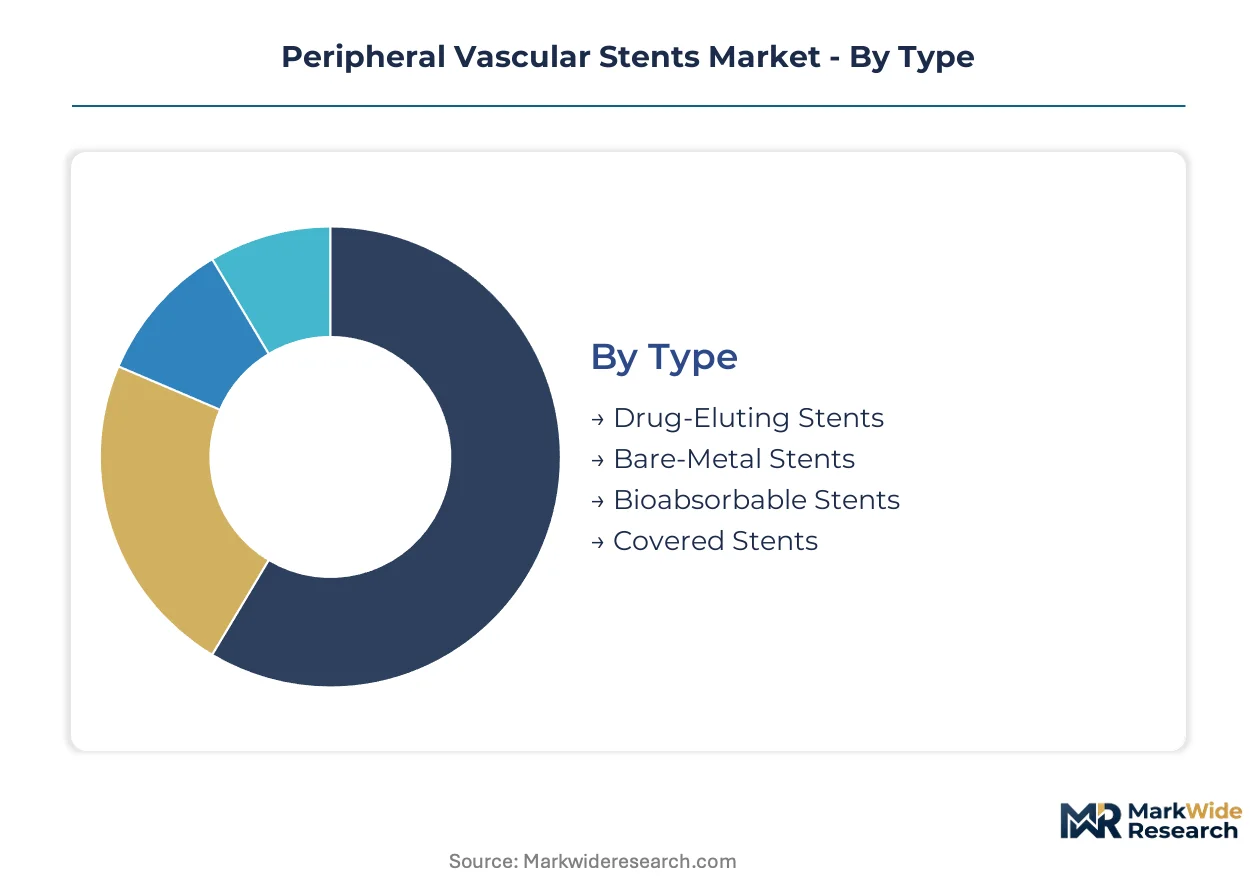
Segmentation in peripheral vascular stents reflects divergent clinical economics across lesion complexity, reimbursement tiers, and procedural settings. Manufacturers configure product portfolios around material science capabilities and regulatory pathway timelines rather than uniform platform strategies.
Type:
Customization intensity spans from fully programmable drug-release kinetics to standardized bare-metal geometries, with each tier commanding distinct clinical evidence requirements and pricing authority.
- Drug-Eluting Stents:Polymer matrices enable controlled paclitaxel or sirolimus release over 3-12 months, suppressing neointimal hyperplasia in femoropopliteal segments exceeding 150mm. Demand clusters in United States tertiary centers where CMS reimbursement covers premium device costs for TASC C/D lesions. Patency advantages in long-segment disease sustain formulary preference despite procurement consolidation pressures.
- Bare-Metal Stents:Nitinol or cobalt-chromium tubular mesh provides mechanical scaffolding without pharmaceutical payload, suited to shorter lesions and cost-constrained environments. Volume concentrates in Indian private hospitals and German statutory insurance cases where reference pricing limits device expenditure. Immediate availability and lower inventory carrying costs reinforce utility in emergency limb-salvage procedures.
- Bioabsorbable Stents:Magnesium alloy or polylactic acid constructs degrade to restore vessel vasomotion, eliminating permanent foreign body retention. Polymer degradation kinetics under ISO 25539-2 validation protocols extend development timelines against investor return expectations.
- Covered Stents:Expanded polytetrafluoroethylene or polyester fabric bonded to metallic frames excludes blood flow from aneurysmal or perforated arterial walls. Indications remain narrow relative to other stent categories.
Leading the category by volume: Bare-Metal Stents. Growing fastest: Drug-Eluting Stents.
Material:
Cost tier separation between commodity feedstocks and specialty alloys determines margin architecture across manufacturer portfolios.
- Metallic:Cobalt-chromium and nitinol alloys dominate mechanical performance requirements, with nickel-titanium shape memory enabling self-expanding deployment in tortuous iliac anatomy. Supply concentrates among United States and German specialty metallurgical processors, exposing stent manufacturers to long-term contracting rigidities.
- Polymer:Biodegradable polylactic acid and polycaprolactone platforms enable drug-eluting matrix integration and eventual scaffold resorption. Japan PMDA Sakigake designation accelerates priority review for first-in-class biodegradable platforms targeting below-the-knee indications.
- Plastic:Polyethylene terephthalate and similar thermoplastics serve covered stent fabric applications where flexibility and thromboresistance prove critical. Limited to specific aneurysmal exclusion indications.
- Composite:Hybrid material constructions combine metallic radial strength with polymer drug-delivery surfaces or biodegradable outer layers. Manufacturing complexity elevates quality system requirements under FDA 21 CFR Part 820.
Dominating procurement value: Metallic platforms. Expanding most quickly: Polymer systems.
End User:
Customer type segmentation tracks the migration of peripheral interventions from inpatient surgical suites to outpatient catheterization facilities.
- Hospitals:Integrated delivery networks in California and Texas consolidate purchasing through centralized value analysis committees, mandating head-to-head patency data before formulary inclusion. Cardiovascular service line administrators displace individual physician preference item selection.
- Ambulatory Surgical Centers:Freestanding endovascular facilities in Germany and United States capture femoropopliteal cases suitable for same-day discharge. Reimbursement arbitrage between facility fees and hospital outpatient prospective payment drives site-of-service shift.
- Specialty Clinics:Dedicated vascular access centers concentrate high-volume operators with advanced imaging capabilities. LimFlow percutaneous deep vein arterialization techniques decentralize no-option chronic limb ischemia cases from academic bypass centers.
- Rehabilitation Centers:Post-acute settings manage wound care and surveillance following revascularization, with device tracking mandates under FDA UDI requirements forcing EHR interoperability investments.
Capturing majority procedure volume: Hospitals. Gaining share fastest: Ambulatory Surgical Centers.
Deployment Method:
Application-specific technique selection reflects lesion morphology, calcification burden, and operator training pathways.
- Transluminal Angioplasty:Percutaneous access with fluoroscopic guidance enables retrograde tibial or pedal approaches for infrapopliteal disease. Procedural complexity demands specialized fellowship training that academic medical centers struggle to scale.
- Balloon Angioplasty:Predilation with semi-compliant or non-compliant balloons precedes stent deployment in calcified lesions, with plaque modification reducing stent dependency in specific anatomies. Endovascular atherectomy substitution constrains addressable stent volumes in high-complexity cases.
- Endovascular Surgery:Hybrid operating room configurations combine open surgical backup with percutaneous technique, accommodating bail-out scenarios. Infrastructure requirements limit penetration to metropolitan tier-one hospital systems.
- Open Surgery:Surgical bypass with autologous vein conduit remains reference standard for long-segment disease, with stent deployment reserved to focal lesions or poor conduit candidates.
Commanding current procedural mix: Transluminal Angioplasty. Steepest expansion trajectory: Balloon Angioplasty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peripheral vascular stent demand concentrates in aging economies with established reimbursement pathways for endovascular interventions. The United States, Germany, and Japan sustain the highest procedural volumes, while India and Brazil represent expansion frontiers where private hospital networks are scaling catheterization capabilities.
United States
Integrated delivery networks in California and Texas consolidate cardiovascular purchasing through value analysis committees that mandate comparative effectiveness data. FDA premarket approval pathways for drug-eluting platforms enforce rigorous clinical trial investment. The Cleveland Clinic and Mayo Clinic anchor high-complexity limb-salvage referral patterns that concentrate no-option chronic limb ischemia cases.
Germany
Statutory insurance reference pricing limits device expenditure for bare-metal stent selection in femoropopliteal cases, while supplemental private coverage enables drug-eluting utilization. EU MDR conformity assessments through notified bodies extend time-to-market for paclitaxel-eluting platforms. The Rhine-Ruhr metropolitan cluster hosts specialized vascular surgery departments adopting LimFlow deep vein arterialization techniques.
Japan
METI reimbursement guidance under the universal health coverage system sustains procedural volumes for super-aged demographics requiring infrapopliteal intervention. PMDA Sakigake designation accelerates priority review for first-in-class biodegradable scaffolds targeting below-the-knee indications. Tokyo and Osaka academic medical centers concentrate specialized fellowship training for pedal access routes.
India
CDSCO regulatory harmonization with global standards enables multinational stent manufacturers to streamline import licensing for drug-eluting platforms. Expanding private hospital networks in Mumbai and Delhi create whitespace for penetration beyond metropolitan tier-one cities. Price controls on coronary stents have redirected manufacturer attention toward peripheral vascular applications with less regulatory pressure.
Brazil
ANVISA regulatory pathways for class III cardiovascular devices require in-country clinical studies that extend registration timelines for novel stent platforms. Private health insurance expansion in São Paulo and Rio de Janeiro supports elective endovascular procedures outside the public SUS system. Regional vascular surgery societies are formalizing training curricula for complex infrapopliteal intervention.
Peripheral Vascular Stents Market Competitive Environment
United States producers anchor one tier; European and Japanese specialists hold differentiated positions in materials science and regulatory navigation. The vendor base organizes around three strategic archetypes: diversified cardiovascular conglomerates with deep clinical trial infrastructure, mid-cap specialists concentrating on bare-metal platform iterations, and emerging players pursuing biodegradable scaffold differentiation. Competitive moves center on M&A for manufacturing scale and strategic partnerships for EU MDR compliance infrastructure.
Within the diversified conglomerate tier, Abbott Laboratories, Medtronic Plc, and Boston Scientific Corp occupy positions defined by integrated cardiovascular service line presence and global distribution reach. These entities exemplify the capital intensity required for sustained FDA premarket approval investment and EU MDR post-market surveillance compliance. Their geographic diversification across United States, European, and Asia-Pacific regulatory jurisdictions represents the standard competitive configuration for maintaining formulary access amid hospital procurement consolidation.
| Leading Market Players |
|---|
| Boston Scientific Corp |
| Abbott Laboratories |
| Medtronic Plc |
| W.L. Gore & Associates Inc |
| CR Bard Inc |
| Terumo Corp |
| Getinge AB |
| Cordis Corp |
| Biotronik SE & Co KG |
| Others |
Value Chain & Pricing Dynamics
EU MDR Article 117 conformity requirements gate qualified supply for drug-device combination stents, restricting premium-tier pricing access to manufacturers with notified body partnerships and extended clinical evaluation infrastructure. This regulatory barrier concentrates pricing power among incumbent platforms while elevating capital thresholds for competitive entry.
Pricing Analysis
Volume concentrates in bare-metal nitinol platforms while margins accrue to drug-eluting systems with polymer-based paclitaxel delivery. Three-tier pricing structure across premium drug-eluting, standard bare-metal, and economy covered stent tiers separates CMS-reimbursed tertiary centers from cost-constrained Indian private hospitals. Price differentiation hinges on FDA premarket approval tier and head-to-head patency data against predicate devices. Cost compression in bare-metal segments is intensifying because statutory insurance reference pricing in Germany limits device expenditure.
Supply Chain Analysis
Nitinol feedstock rests on specialty metallurgical processors in the United States and Germany, with cobalt-chromium alloy sourcing tethered to the same geographic cluster. Polymer matrix materials for drug-eluting platforms draw from Japanese and Swiss specialty chemical producers, while ePTFE fabric for covered stents centers on United States and Ireland medical textile manufacturers. Single-source vulnerability in nickel-titanium alloy exposes stent manufacturers to long-term contracting rigidities. Distribution runs through integrated delivery network value analysis committees that consolidate purchasing authority across cardiovascular service lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in qualified nitinol feedstock and EU MDR compliance infrastructure prop pricing for incumbent drug-eluting platforms, creating defendable margin structures for manufacturers with established notified body relationships.
For Market Incumbents: Extend manufacturing scale in United States and German metallurgical processing corridors to secure nitinol alloy supply commitments against specialty processor capacity limitations. Deepen clinical trial investment for biodegradable scaffold platforms ahead of Japan PMDA Sakigake priority review windows, as FDA breakthrough device designation compresses competitive entry timelines for novel polymer degradation kinetics. For New Entrants and Emerging Players: Enter via CDSCO regulatory harmonization pathways in Indian private hospital networks beyond Mumbai and Delhi metropolitan clusters, where coronary stent price controls have redirected multinational attention toward peripheral vascular whitespace. Target renal artery stenosis applications for small-vessel stenting in hypertension management, leveraging limited established competition in this emerging procedural category. For Investors and Strategic Acquirers: Japan PMDA reimbursement determination for below-the-knee biodegradable indications is the leading indicator that polymer scaffold platforms will capture premium positioning in super-aged demographics. Mid-cap specialists with bare-metal platform iterations and deferred drug-eluting pipeline investments represent acquisition targets with near-term cash flow and regulatory optionality across the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review accelerates biodegradable scaffold validation against predicate device benchmarks. |
| EU MDR Notified Body Partnership | Article 117 compliance infrastructure extends time-to-market for paclitaxel-eluting platforms. |
| Hospital System Value Analysis Committee Engagement | Head-to-head patency data mandates secure formulary inclusion in California and Texas IDNs. |
| CDSCO Import Licensing Streamlining | Regulatory harmonization enables drug-eluting penetration in Indian tier-two city private networks. |
| LimFlow Technique Training Partnership | Deep vein arterialization capability decentralizes no-option chronic limb ischemia case capture. |
Study Parameters
Independent corroboration across vascular surgery department heads, hospital purchasing committee administrators, GPO contracts managers, and biomedical engineering specialists underwrites the qualitative findings on procurement consolidation patterns. Secondary validation draws from FDA 510(k) and PMA filings, EMA post-market surveillance databases, CMS national coverage determinations, and hospital procurement contract registries. Bottom-up procedure volume modeling triangulates against top-down manufacturer revenue segmentation across drug-eluting, bare-metal, and covered stent platforms.
Rate-of-change decomposition across the analysis window separates volume drivers from value drivers, with segmentation modeling spanning stent type, material composition, end-user facility class, and deployment technique. CAGRs derive from procedure volume trajectories in femoropopliteal, iliac, and renal artery indications, cross-referenced against reimbursement pathway evolution in United States, German, and Japanese markets. Forecast inputs incorporate METI guidance updates, EU MDR transition timelines, and CDSCO regulatory harmonization progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA UDI implementation delays or nitinol supply disruptions from specialty metallurgical processor consolidation. Assumptions reflect current reimbursement tiers, regulatory pathway timelines, and hospital procurement behavioral patterns. A small set of named triggers warrants ongoing watch: PMDA Sakigake designation announcements, EU MDR notified body capacity constraints, and integrated delivery network value analysis committee mandate expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Global Vascular Embolization Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular CT Systems Market