
 Internet of Things (IoT) in Logistics Market | 2026-2036
Internet of Things (IoT) in Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) in Logistics Market Intelligence
Sensor manufacturing capacity across East Asian electronics clusters is consolidating as foundries prioritize automotive-grade IoT modules over consumer variants. SAP Logistics Business Network leverages its ERP integration depth to anchor enterprise fleet deployments across European manufacturing corridors. FourKites competes through predictive visibility algorithms that reduce dwell-time penalties at North American port terminals. Manhattan Associates specializes in warehouse execution systems where RFID-tagged inventory feeds directly into robotic sortation workflows.
Internet of Things in Logistics denotes networked sensor and actuator ecosystems embedded across freight infrastructure, typically operating through low-power wide-area protocols with sub-100 millisecond latency requirements for real-time cargo telemetry. These systems synchronize vehicle location, environmental condition, and inventory status data to optimize multimodal transportation orchestration and reduce spoilage or theft incidents. Fleet Management applications dominate current deployment value as fuel cost volatility pushes operators toward dynamic routing engines, while Warehouse Automation represents the fastest-expanding segment where autonomous mobile robots depend on continuous wireless sensor network coverage. RFID technology sustains premium pricing in pharmaceutical cold chains where tamper-evident pedigree tracking is non-negotiable.
The Federal Motor Carrier Safety Administration's electronic logging device mandate reshaped North American long-haul compliance, forcing analog fleet operators into connected telematics upgrades. The EU Green Deal's emissions reporting frameworks are accelerating demand for fuel-consumption sensors that feed directly into CSRD-aligned sustainability disclosures. Stakeholders must weigh edge versus cloud deployment architectures against evolving data sovereignty requirements as cross-border freight corridors fragment under divergent national cybersecurity standards.
Market Dynamics
Edge computing architectures are consolidating around freight corridors as latency requirements for pharmaceutical cold chain telemetry harden below 100 milliseconds, forcing infrastructure decisions that favor distributed processing over centralized cloud models.
Growth Catalysts
- Pharmaceutical Traceability Mandates:The FDA's Drug Supply Chain Security Act compels cold chain operators to deploy tamper-evident sensor networks across temperature-controlled lanes, creating embedded demand for RFID-tagged environmental monitors.
- Automotive Just-in-Time Compression:German automotive supply chains now mandate sub-second latency tracking for inbound component flows, pulling LPWAN infrastructure investments into manufacturing corridors.
- Fuel Cost Volatility:Dynamic routing engines that ingest real-time vehicle telematics are becoming standard fleet equipment as diesel price swings force operators toward algorithmic dispatch optimization.
Market Restraints
- Semiconductor Foundry Prioritization:East Asian electronics clusters are reallocating automotive-grade IoT module capacity away from logistics sensor variants, creating procurement bottlenecks for cold chain hardware.
- Data Sovereignty Fragmentation:Divergent national cybersecurity standards across cross-border freight corridors are fragmenting cloud deployment architectures and multiplying compliance engineering costs.
- Legacy Fleet Upgrade Burden:Analog fleet operators face stranded asset risk as electronic logging device mandates force telematics retrofits on aging vehicle pools with limited CAN bus compatibility.
Strategic Opportunities
- Warehouse Automation Convergence:Autonomous mobile robot deployments depend on continuous wireless sensor network coverage, creating bundled infrastructure opportunities for facility-scale IoT integrators.
- EU Emissions Reporting Alignment:The EU Green Deal's CSRD-aligned sustainability disclosures are accelerating demand for fuel-consumption sensors that feed directly into verified carbon accounting systems.
- Predictive Port Visibility:North American terminal operators are adopting dwell-time reduction algorithms that require granular container location telemetry, opening specialized analytics service layers.
Industry Challenges
- RF Engineering Talent Scarcity:Deployment of sub-100 millisecond latency networks requires specialized radio frequency optimization skills that outpace current technical education pipeline output.
- Multi-Protocol Integration Complexity:Fleet operators struggle to harmonize data streams across heterogeneous telematics standards when retrofitting mixed-vendor vehicle pools.
- Cybersecurity Certification Timelines:Cross-border freight corridors face extended approval cycles as national regulators impose divergent penetration testing requirements on connected cargo infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) in Logistics Market |
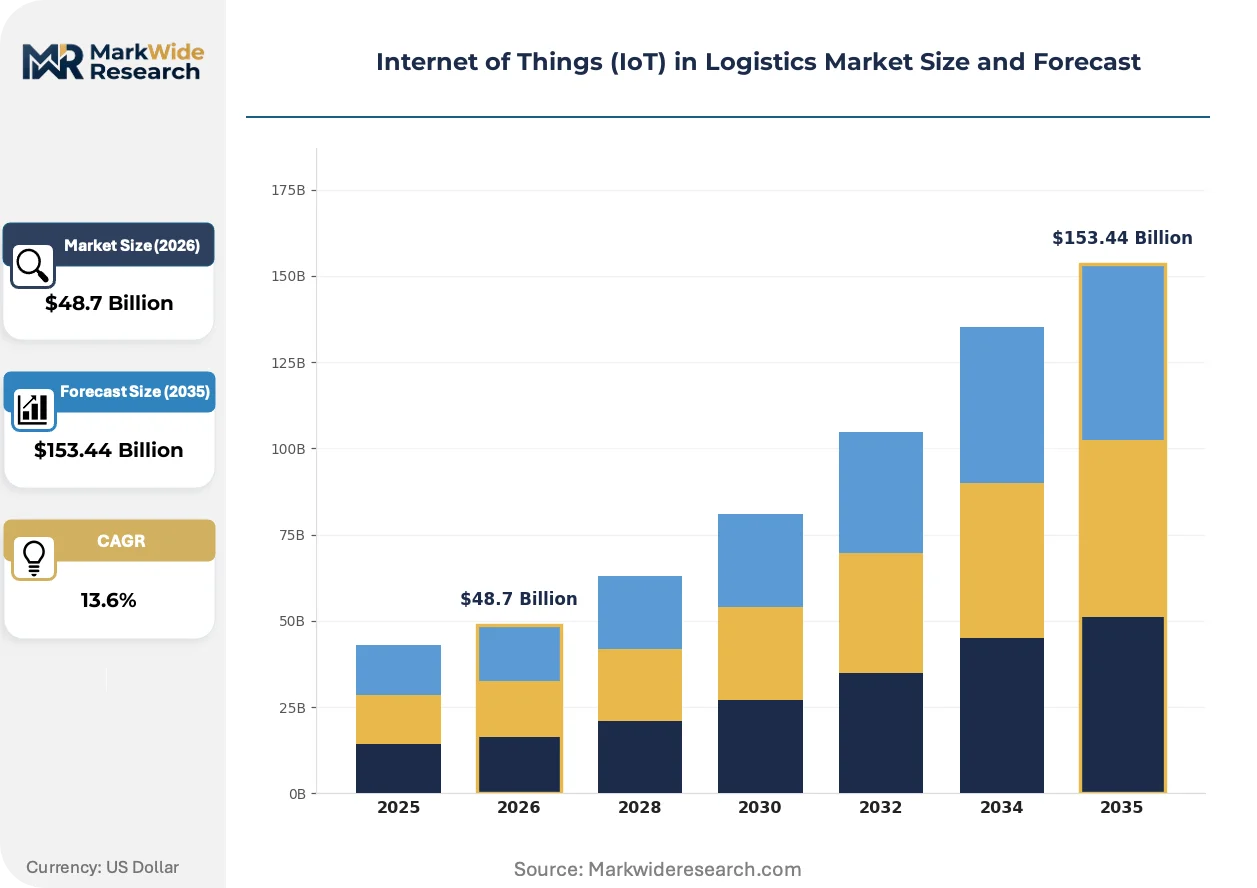
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $153.44 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Asset Tracking, Fleet Management, Inventory Monitoring, Route Optimization, Warehouse Automation Technology: RFID, GPS, Barcode Scanning, Wireless Sensor Networks, Cloud Computing Deployment: Cloud-based, On-premise, Hybrid, Edge Computing End User: Freight Forwarders, Third-Party Providers, Retail Chains, Distribution Centers, Shipping Companies |
| Companies Covered | SAP Logistics Business Network, Descartes Systems Group, Yalantis, Taabi Mobility, UVIONIX Innovations, Oracle Logistics Cloud, FourKites, Rovigos, Manhattan Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) in Logistics Market Strategic Shifts & Innovations
Real-time freight monitoring is migrating toward distributed intelligence as latency requirements harden and data sovereignty concerns multiply, compressing the architectural window for centralized cloud dependency.
LPWAN sensor networks with integrated edge processing capabilities are consolidating cold chain monitoring infrastructure. Pharmaceutical distributors in temperature-sensitive lanes are deploying these systems fastest, with German automotive inbound logistics following. This distributed architecture is consolidating vendor relationships around integrated hardware-software providers capable of sub-50 millisecond local decision loops.
The EU Green Deal's emissions reporting frameworks are mandating granular fuel-consumption telemetry across commercial vehicle fleets. This regulatory pressure is forcing telematics providers to embed certified carbon calculation engines directly into onboard units. Heavy-duty freight operators in Germany and France face the steepest compliance curves as CSRD disclosure deadlines approach.
Buyer procurement patterns are rotating toward outcome-based visibility contracts that penalize data latency rather than reward hardware installation. Third-party logistics providers are displacing direct equipment purchases with managed service agreements that bundle sensor maintenance, connectivity, and analytics. This shift is most pronounced in North American port drayage and European automotive just-in-time lanes where dwell-time penalties cascade through supply chains.
Internet of Things (IoT) in Logistics Market Segmentation
Segmentation in IoT logistics reveals where certification burdens concentrate and which infrastructure investments unlock compliance value. The FDA's Drug Supply Chain Security Act and EU Green Deal frameworks create divergent technical requirements across application types, forcing buyers to match deployment architecture against specific regulatory exposure.
Application:
FDA DSCSA mandates for pharmaceutical cold chains impose tamper-evident sensor requirements on Asset Tracking and Fleet Management deployments, while warehouse robotics drive faster certification cycles for Warehouse Automation.
- Fleet Management:Dynamic routing engines ingest real-time vehicle telematics to optimize fuel consumption against diesel price volatility. German automotive supply chains mandate sub-second latency here, pulling LPWAN infrastructure investments into manufacturing corridors.
- Warehouse Automation:Autonomous mobile robots require continuous wireless sensor network coverage with sub-50 millisecond local decision loops. Pharmaceutical distributors and German automotive inbound logistics deploy these systems fastest.
- Asset Tracking:RFID-tagged environmental monitors serve temperature-controlled lanes with tamper-evident pedigree tracking.
- Inventory Monitoring:RFID feeds directly into robotic sortation workflows for real-time stock visibility.
- Route Optimization:Algorithmic dispatch engines reduce dwell-time penalties at North American port terminals.
Leading the category by volume: Fleet Management. Growing fastest: Warehouse Automation.
Technology:
Cost tiers separate premium-certified modules from standard commercial variants, with automotive-grade foundry capacity commanding price premiums over consumer electronics grades.
- RFID:Sustains premium pricing in pharmaceutical cold chains where FDA DSCSA-compliant tamper-evident pedigree tracking is non-negotiable. German automotive corridors deploy UHF variants for component-level traceability.
- Wireless Sensor Networks:LPWAN architectures with integrated edge processing consolidate cold chain monitoring infrastructure. Sub-100 millisecond latency requirements favor distributed processing over centralized cloud models.
- GPS:Standard telematics location tracking for fleet visibility across long-haul corridors.
- Barcode Scanning:Legacy inventory capture technology in cost-sensitive warehouse operations.
- Cloud Computing:Centralized data aggregation facing displacement by edge architectures under data sovereignty pressures.
RFID commands the highest certification premiums. Wireless Sensor Networks are climbing the fastest as edge computing consolidates vendor relationships.
Deployment:
Customer type determines architecture risk tolerance, with freight forwarders accepting cloud dependency while pharmaceutical distributors demand on-premise control over pedigree data.
- Edge Computing:Distributed intelligence architectures process telemetry locally to meet sub-100 millisecond latency requirements for pharmaceutical cold chain monitoring. German automotive just-in-time mandates pull these deployments into manufacturing corridors.
- Hybrid:Blends local processing with cloud analytics for fleet operators navigating divergent national cybersecurity standards across cross-border freight corridors.
- Cloud-based:Centralized models facing fragmentation under EU data sovereignty requirements and divergent national penetration testing mandates.
- On-premise:Isolated infrastructure for high-security pharmaceutical pedigree tracking with complete data custody.
Edge Computing leads deployment value. Hybrid architectures are expanding most quickly as operators hedge sovereignty risk.
End User:
Margin structures vary sharply across customer types, with third-party logistics providers capturing service bundling premiums while retail chains face hardware depreciation pressure.
- Third-Party Providers:Outcome-based visibility contracts now penalize data latency rather than reward hardware installation. These providers bundle sensor maintenance, connectivity, and analytics into managed service agreements.
- Freight Forwarders:Multi-modal orchestrators requiring harmonized data streams across heterogeneous telematics standards when managing mixed-vendor vehicle pools.
- Retail Chains:High-volume RFID deployments for inventory accuracy feeding automated replenishment systems.
- Distribution Centers:Facility-scale wireless sensor network coverage enabling robotic sortation workflows.
- Shipping Companies:Vessel and container telemetry for port dwell-time reduction algorithms.
Third-Party Providers dominate contract value. Freight Forwarders are gaining share fastest as outcome-based pricing spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor foundries anchor sensor module supply for logistics IoT deployments, while European regulatory frameworks pull demand toward certified cold chain infrastructure. Manufacturing gravity concentrates in German automotive corridors and North American pharmaceutical distribution hubs.
United States
The FDA's Drug Supply Chain Security Act mandates tamper-evident sensor networks across temperature-controlled pharmaceutical lanes. The Federal Motor Carrier Safety Administration enforces electronic logging device compliance on long-haul fleets. Chicago and Memphis distribution corridors deploy edge-computing freight monitors to reduce dwell-time penalties at intermodal terminals.
Germany
Automotive just-in-time supply chains mandate sub-second latency tracking for inbound component flows. The EU Green Deal's CSRD-aligned emissions reporting accelerates fuel-consumption sensor deployment across commercial vehicle fleets. The Stuttgart and Munich manufacturing corridors pull LPWAN infrastructure investments for real-time assembly line synchronization.
China
MIIT standards govern low-power wide-area network spectrum allocation for industrial IoT applications. Dual carbon goals drive fleet operators toward telemetry-enabled fuel optimization. Yangtze River Delta logistics clusters consolidate sensor manufacturing capacity alongside electronics foundry expansion in Suzhou and Shanghai.
India
The PLI scheme incentivizes domestic electronics manufacturing for automotive-grade IoT modules. BIS certification requirements shape cold chain hardware procurement for pharmaceutical distribution. Mumbai-Pune and Delhi-Mumbai industrial corridors deploy warehouse automation systems with RFID-tagged inventory feeds.
Japan
METI promotes Industry 4.0 integration across logistics infrastructure through standardized sensor protocols. JIS certification requirements maintain premium pricing for pharmaceutical-grade tracking hardware. The Chubu region around Nagoya anchors automotive supply chain sensor deployment for just-in-time component flows.
Internet of Things (IoT) in Logistics Market Key Industry Players
Global majors compete with regional champions across ERP integration depth and predictive analytics capabilities. The vendor base stratifies between enterprise software platforms, specialized visibility providers, and hardware-integrated systems integrators. Three archetypes dominate: ERP-anchored network operators, predictive visibility specialists, and warehouse execution system providers. Competitive moves concentrate on strategic partnerships with semiconductor foundries and geographic expansion into German automotive corridors.
Within the ERP-anchored tier, SAP Logistics Business Network and Oracle Logistics Cloud exemplify platform-scale competitors leveraging enterprise integration depth. FourKites occupies a position among predictive visibility specialists focused on freight monitoring algorithms. Manhattan Associates represents the warehouse execution archetype where RFID-tagged inventory feeds robotic automation workflows.
| Leading Market Players |
|---|
| SAP Logistics Business Network |
| Descartes Systems Group |
| Yalantis |
| Taabi Mobility |
| UVIONIX Innovations |
| Oracle Logistics Cloud |
| FourKites |
| Rovigos |
| Manhattan Associates |
| Others |
Cost & Logistics Intelligence
RF engineering talent scarcity across East Asian electronics clusters widens labor-cost differentials between certified edge-computing integrators and commodity sensor assemblers, compressing pricing-tier spreads for sub-100 millisecond latency solutions.
Pricing Analysis
Warranty and sensor-maintenance bundling separates premium managed-service contracts from unbundled hardware-only transactions. Subscription-based SaaS tiers dominate fleet telematics, with price differentiation resting on FDA DSCSA certification grade and edge-processing capability depth. Cost compression in standard-tier modules intensifies as foundries reallocate automotive-grade capacity. Third-party logistics providers show lowest price sensitivity due to outcome-based contract structures, while retail chains face acute hardware depreciation pressure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for automotive-grade IoT module fabrication. Semiconductor foundry output draws from silicon wafers, rare-earth substrates, and precision RF components. Tariff exposure on cross-border component flows threatens cost predictability. Distribution runs through East Asian electronics clusters before final integration at German automotive corridors and North American pharmaceutical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Internet of Things in Logistics Market operates as a cost-of-compliance arena where the FDA's Drug Supply Chain Security Act erects certification barriers that moat-compliant sensor vendors against undifferentiated hardware entrants.
For Market Incumbents: Deepen backward integration into automotive-grade foundry partnerships to secure capacity allocation against consumer electronics prioritization. Fortify ERP-anchored platform positions through predictive analytics acquisitions that neutralize dwell-time penalty exposure at North American terminals. Edge-computing certification investments represent the critical defensive lever. For New Entrants and Emerging Players: Enter via warehouse automation convergence where autonomous mobile robot deployments create bundled infrastructure demand with shorter certification cycles. White-space concentrates in Indian pharmaceutical distribution corridors under PLI scheme incentives. Outcome-based visibility contracts offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-deployment specialists given EU data sovereignty fragmentation forcing architecture hedging. Long-term viability favors vendors with demonstrated sub-50 millisecond edge-processing capabilities across the next decade. Watch German automotive just-in-time mandate enforcement velocity as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Deployment | Sub-100 millisecond latency architectures displace centralized cloud models under FDA DSCSA pharmaceutical mandates. |
| Automotive-Grade Foundry Partnership | Secures semiconductor capacity allocation against consumer electronics prioritization in Taiwan and South Korea. |
| Predictive Visibility Algorithm Development | Dwell-time reduction engines capture outcome-based contract premiums at North American port terminals. |
| EU CSRD Emissions Reporting Integration | Fuel-consumption telemetry embeds certified carbon calculation engines for Green Deal compliance. |
| Pharmaceutical Cold Chain Certification | Tamper-evident RFID pedigree tracking commands premium pricing under DSCSA temperature-controlled lane requirements. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs across this analysis. Primary interviews with fleet telematics directors, pharmaceutical distribution compliance officers, warehouse automation engineers, and semiconductor procurement leads combined with bottom-up sensor deployment tallies and top-down logistics spending estimates. Secondary sources encompassed FDA DSCSA guidance documents, EU Green Deal CSRD implementation texts, FMCSA electronic logging device enforcement data, and MIIT low-power wide-area network spectrum allocations. Triangulation validated volume assumptions against customs records of IoT module imports.
Data-stream reconciliation across hardware shipment volumes, connectivity subscription counts, and software licensing disclosures shaped the analytical framework. Segmentation dimensions modeled encompassed application type, technology protocol, deployment architecture, and end-user category alongside regulatory compliance tier across the projection horizon. CAGRs derived from slope-intercept fitting of annualized deployment trajectories. Industry-specific forecast inputs incorporated German automotive production schedules and pharmaceutical cold chain lane expansion plans.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor foundry capacity reallocation decisions and divergent national cybersecurity standard implementation timelines. Forecasts reflect documented assumptions regarding edge-computing adoption velocity and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Colombia Freight and Logistics Market