
 Bangladesh Contract Logistics Market | 2026-2036
Bangladesh Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Contract Logistics Market Insights
Premium contract logistics services is shifting away from commodity freight brokerage across Bangladesh's garment corridor. Maersk leverages its integrated ocean-feeder network to control end-to-end container movements from factory gate to port. DHL Supply Chain sustains specialized pharmaceutical cold-chain operations serving Dhaka's growing generics sector. Kuehne + Nagel anchors European buyer compliance programs through its vendor-managed inventory platforms in Ashulia and Gazipur.
Bangladesh contract logistics encompasses outsourced supply-chain execution where third-party operators manage transportation, warehousing, inventory management, and distribution under multi-year agreements, typically spanning bonded warehouse facilities with customs-synchronized inventory tracking and temperature-controlled pharmaceutical storage. Transportation services dominate current revenue pools due to fragmented road networks and port congestion penalties, while warehousing is accelerating fastest as export processing zones expand dry-port capacity near Chittagong. E-commerce end users concentrate demand around last-mile sortation centers in Dhaka's peripheral districts, though manufacturing retains the deepest contract durations tied to annual production cycles.
Bangladesh Bank governs foreign-exchange documentation for export logistics financing, while the National Board of Revenue enforces customs-bonded warehouse licensing that shapes operator eligibility and facility standards. These frameworks compel providers to maintain dual compliance certifications for international buyer audits and domestic tax authority inspections. Stakeholders must weigh whether to build captive warehouse assets or outsource to licensed operators as Dhaka's land constraints intensify and customs automation timelines compress.
Market Dynamics
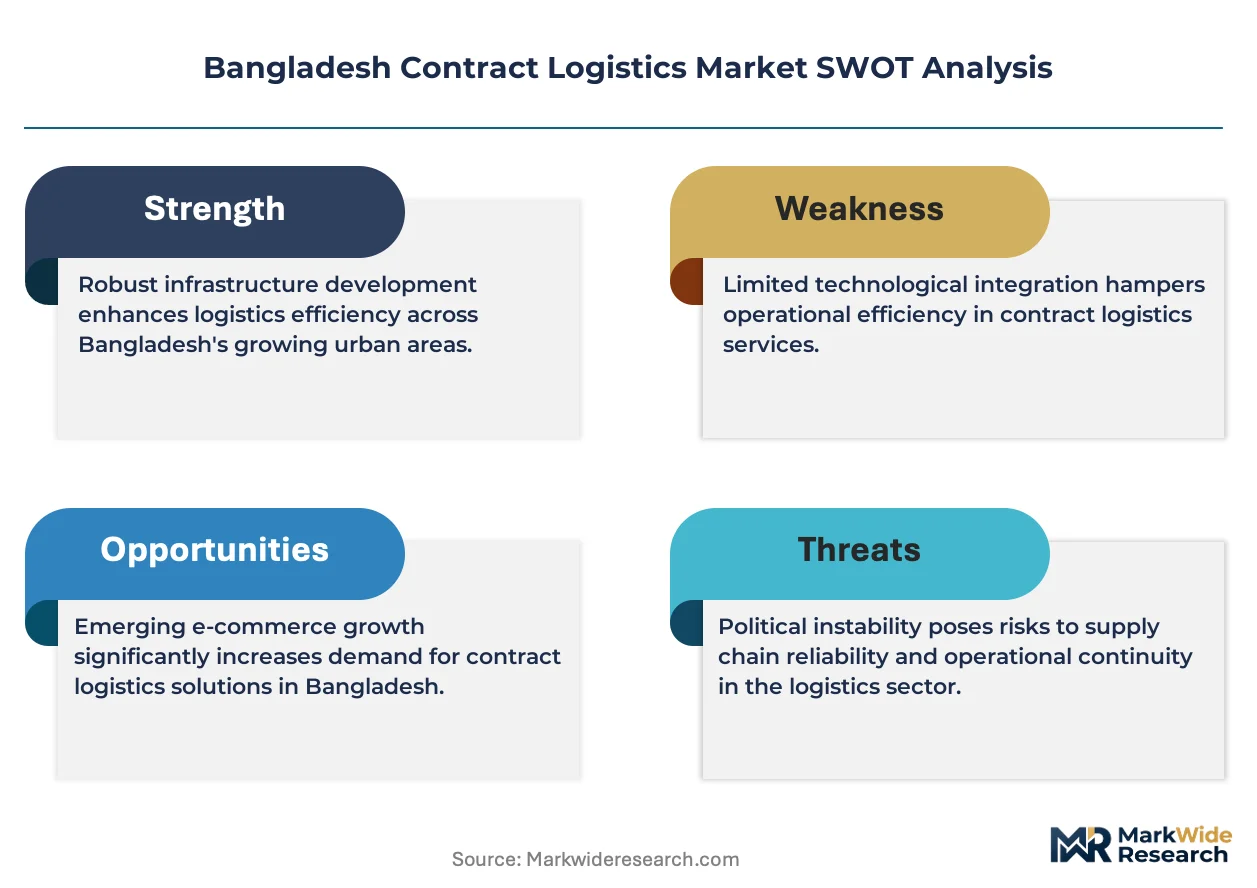
Bonded warehouse licensing under Bangladesh Bank foreign-exchange documentation rules is compressing operator eligibility timelines and forcing asset-light strategies among third-party logistics providers serving Dhaka-Chittagong export corridors.
Growth Catalysts
- Export Processing Zone Expansion:Dry-port capacity additions near Chittagong are pulling bonded warehouse demand from traditional port-adjacent facilities. Apparel exporters now synchronize inventory with automated customs corridors.
- Bangladesh Bank Documentation Tightening:Stricter foreign-exchange filing requirements for export-oriented units are mandating customs-synchronized inventory tracking systems that only licensed operators can provision.
- Pharmaceutical Cold-Chain Investment:Dhaka's generics sector requires temperature-controlled storage that meets international buyer audit standards, creating specialized contract demand beyond commodity freight.
Market Restraints
- Land Scarcity in Dhaka Metropolitan:Industrial plot availability constraints warehouse construction timelines and inflames facility lease rates for operators seeking bonded status.
- Port Congestion Penalties:Chittagong container dwell charges and vessel waiting-time costs erode margin structures for transportation-heavy contract portfolios.
- Fragmented Road Networks:Highway infrastructure gaps between Dhaka and Chittagong extend transit variability and complicate just-in-time delivery commitments to European buyers.
Strategic Opportunities
- Peripheral District Sortation Centers:E-commerce volume concentration in Dhaka's outer zones creates greenfield warehouse development potential beyond core metropolitan land constraints.
- Vendor-Managed Inventory Platforms:European buyer compliance programs favor operators capable of upstream integration into supplier production schedules at Ashulia and Gazipur clusters.
- Customs Automation Timelines:National Board of Revenue digital clearance corridor investments reward early-mover operators with preferred queue positioning and reduced inspection frequency.
Industry Challenges
- Dual Certification Burden:Operators must maintain parallel compliance documentation for international buyer audits and domestic tax authority inspections, duplicating back-office overhead.
- Captive vs. Outsourced Asset Decisions:Exporters face compressed decision windows for building in-house warehouse capacity versus contracting licensed operators as land prices escalate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Contract Logistics Market |
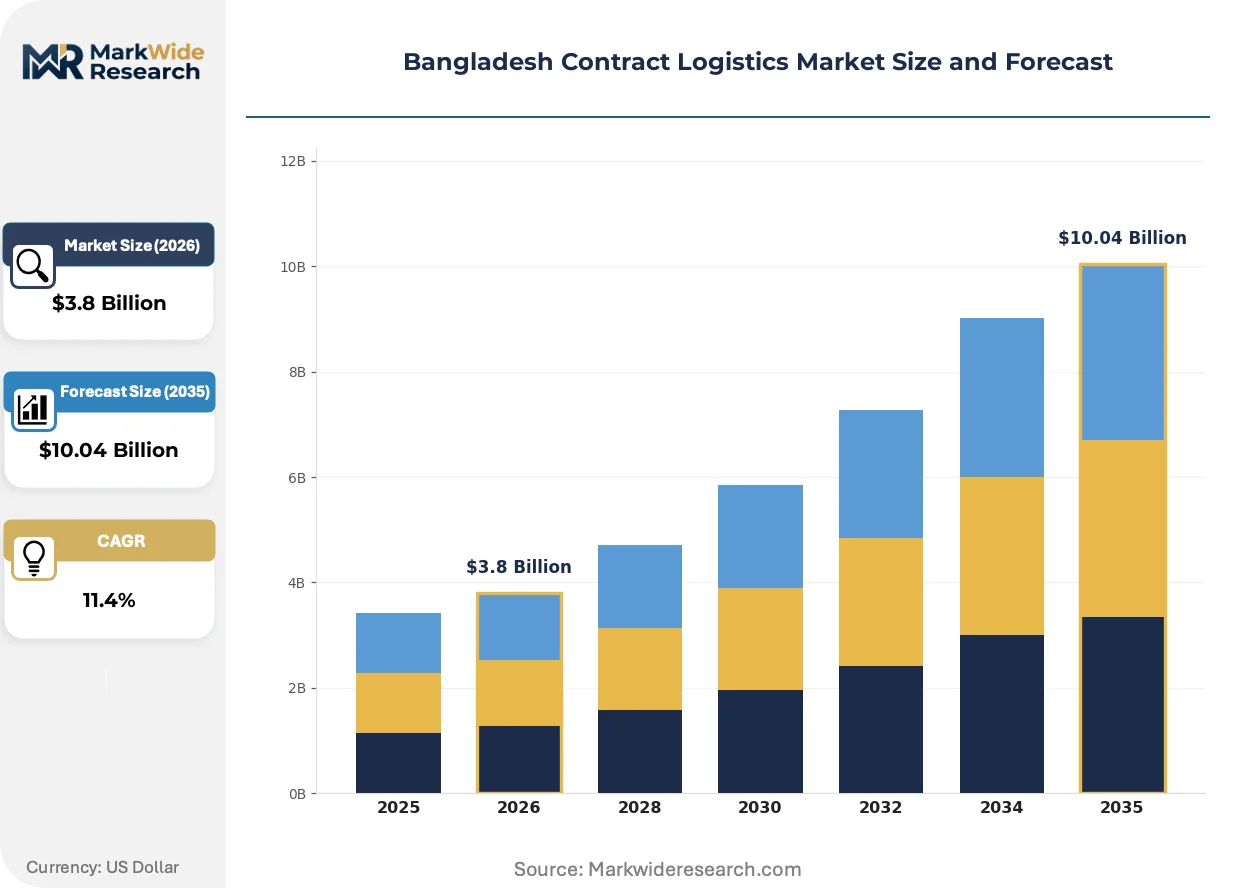
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Distribution End User: Retail, Manufacturing, E-commerce, Pharmaceuticals Technology: Automation, GPS Tracking, RFID, Transportation Management System Contract Duration: Short-term, Long-term, Project-based, Seasonal |
| Companies Covered | Maersk, DHL Supply Chain, Kuehne + Nagel, DB Schenker, CEVA Logistics, XPO Logistics, Agility, Yusen Logistics, We Freight, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Contract Logistics Market Trends and Innovations
Digital inventory synchronization and customs automation are reshaping competitive positioning among Bangladesh contract logistics operators, compressing the gap between factory gate visibility and port clearance velocity.
Blockchain-enabled cargo documentation is decentralizing trust architecture across multi-party supply chains. Garment exporters in Savar and Narayanganj are piloting distributed ledger systems for origin certification. This technology is decentralizing document verification away from single-point customs bottlenecks toward consensus-based clearance protocols.
Bangladesh Bank's real-time foreign-exchange reporting mandate is forcing API integration between warehouse management systems and central bank databases. Operators must now maintain live data pipes for export receipt validation. Small and mid-tier providers lacking IT infrastructure face exclusion from formal sector contracts.
Direct-to-retail procurement patterns among European apparel buyers are compressing traditional forwarding intermediaries. Large exporters now negotiate ocean-feeder slots independently, relegating contract logistics providers to warehouse execution roles. This disintermediation concentrates most visibly in Dhaka-Chittagong corridors serving fast-fashion replenishment cycles.
Bangladesh Contract Logistics Market Segmentation
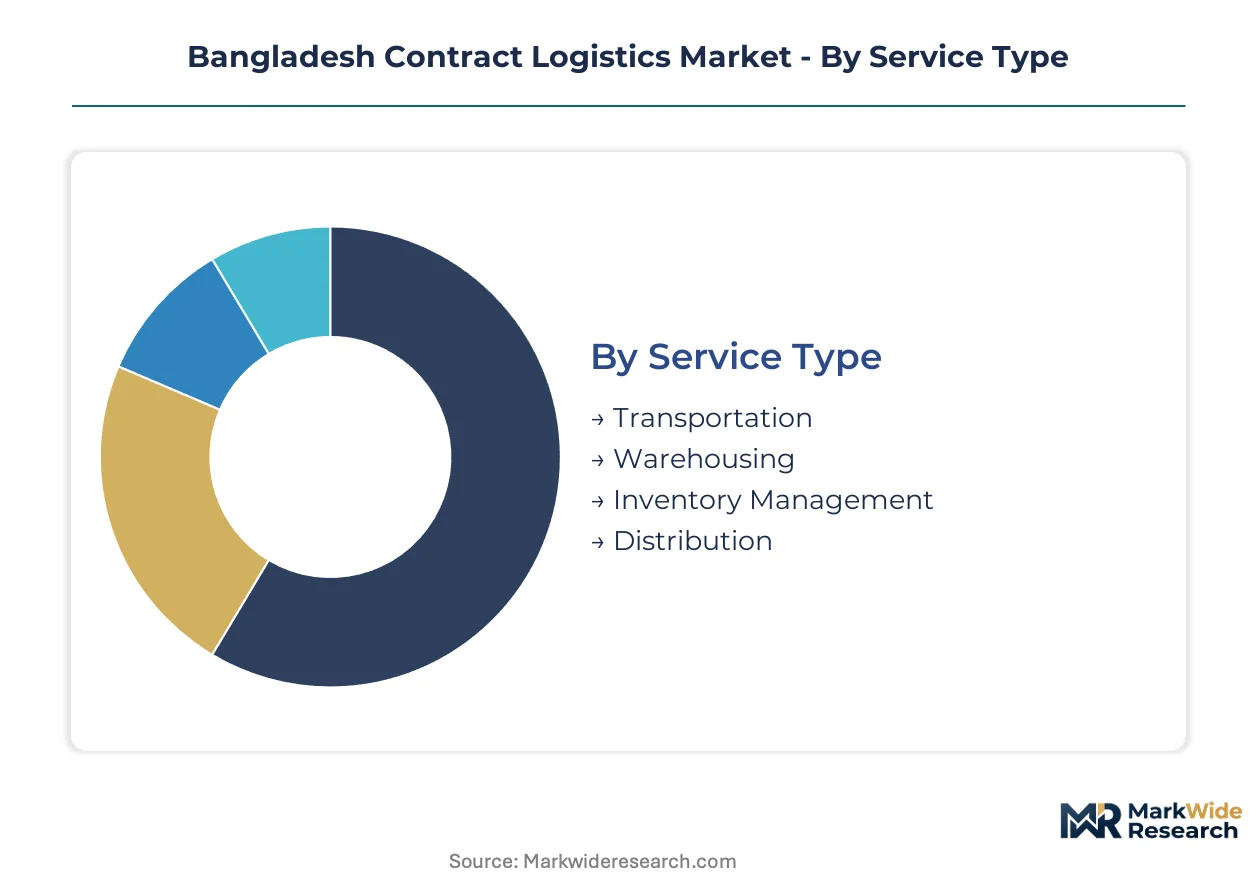
Segmentation in Bangladesh contract logistics reveals how service portfolios align with export processing zone expansion and customs automation timelines. Distinct buyer requirements across bonded warehousing, cold-chain pharmaceuticals, and fast-fashion replenishment create specialized operational footprints.
Service Type:
Supply concentration around Dhaka-Chittagong export corridors shapes which service layers capture disproportionate investment.
- Transportation:Road and feeder vessel movements dominate revenue pools due to fragmented highway infrastructure and Chittagong port congestion penalties. Apparel exporters in Gazipur and Narayanganj absorb the bulk of fleet capacity tied to European buyer delivery windows.
- Warehousing:Bonded facilities with customs-synchronized inventory tracking command premium positioning as Bangladesh Bank documentation rules tighten. Dry-port capacity additions near Chittagong are accelerating fastest among service investments.
- Inventory Management:Vendor-managed inventory platforms integrate upstream into supplier production schedules at Ashulia clusters. European buyer compliance programs drive adoption of real-time stock visibility systems.
- Distribution:Last-mile sortation centers in Dhaka's peripheral districts serve e-commerce volume concentration. Peripheral land availability offers greenfield development potential beyond core metropolitan constraints.
Transportation absorbs the bulk of installed capacity; warehousing is expanding most quickly.
End User:
Cost tier differentiation separates commodity freight brokerage from specialized contract logistics serving regulated sectors.
- Manufacturing:Apparel exporters anchor the deepest contract durations tied to annual production cycles and bonded warehouse licensing requirements. Dhaka-Chittagong industrial belt concentration creates scale economies for licensed operators.
- Pharmaceuticals:Temperature-controlled storage meeting international buyer audit standards commands specialized contract premiums. Dhaka's generics sector drives cold-chain investment beyond commodity freight capabilities.
- E-commerce:Volume concentration in Dhaka's outer zones demands peripheral sortation infrastructure. Last-mile density challenges favor asset-light partnership models over captive fleet investment.
- Retail:Direct-to-retail procurement patterns among European buyers compress traditional forwarding intermediaries. Large exporters now negotiate ocean-feeder slots independently.
Manufacturing retains the longest contract tenures; pharmaceuticals posts the steepest expansion trajectory.
Technology:
Application maturity varies sharply between legacy tracking systems and API-integrated compliance infrastructure mandated by central bank reporting.
- Transportation Management System:Platform-based fleet optimization and route planning reduce transit variability on Dhaka-Chittagong corridors. Real-time visibility supports just-in-time delivery commitments to European buyers.
- Automation:Warehouse robotics and automated sortation address labor availability constraints in metropolitan Dhaka. Bonded facilities prioritize customs-synchronized inventory accuracy over pure throughput speed.
- GPS Tracking:Vehicle location monitoring mitigates highway infrastructure gaps and extends supply chain visibility to factory gate. Fragmented road networks amplify the value of transit time predictability.
- RFID:Item-level tagging supports origin certification requirements for garment exporters in Savar and Narayanganj pilot programs. Blockchain-enabled cargo documentation pilots leverage RFID data for distributed ledger verification.
Transportation Management System deployments absorb the bulk of technology investment; automation is gaining share fastest.
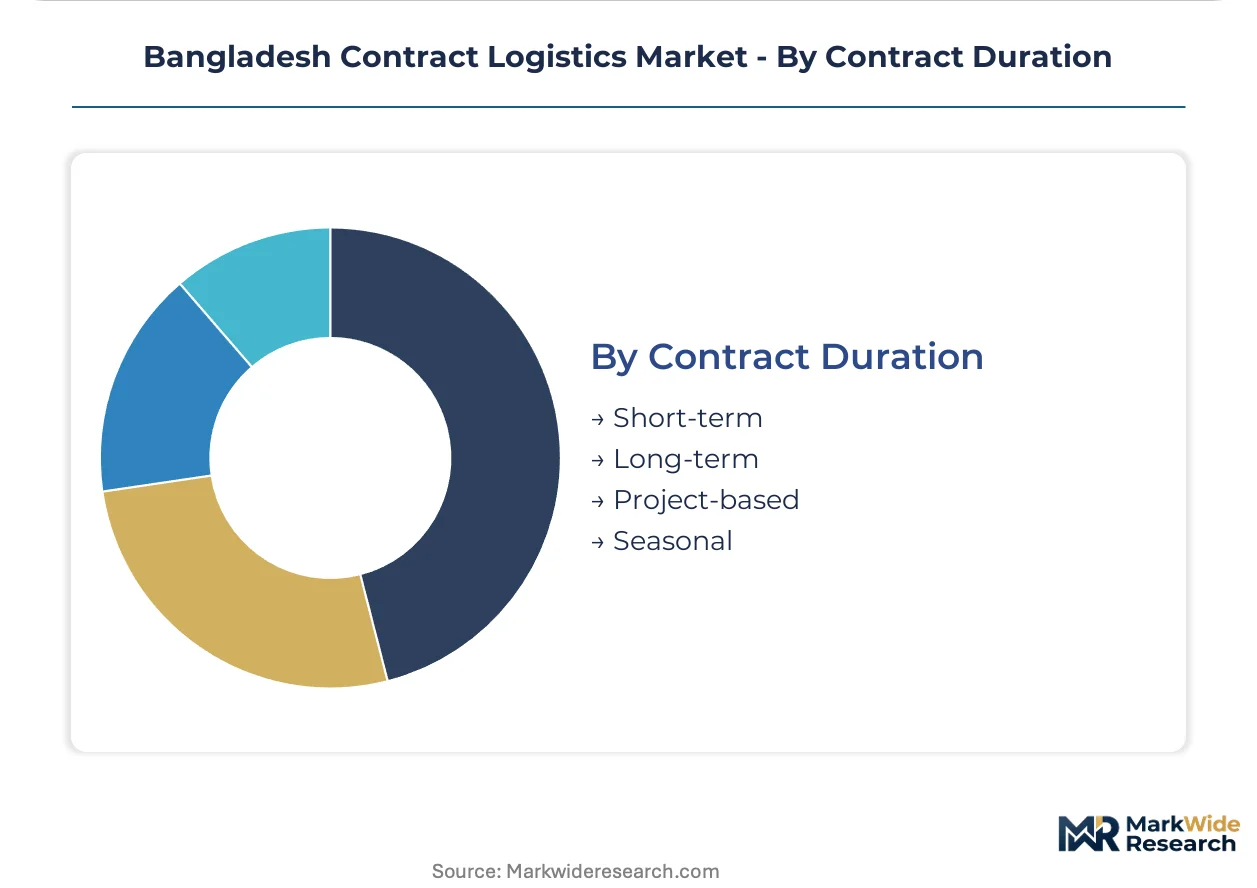
Contract Duration:
Customer type and margin profile dictate commitment length, with export manufacturing favoring multi-year stability and e-commerce accepting shorter terms.
- Long-term:Multi-year agreements spanning bonded warehouse facilities with customs-synchronized inventory tracking. Annual production cycles in apparel manufacturing lock in facility dedication and preferred queue positioning.
- Project-based:Event-driven logistics for trade exhibitions, seasonal harvest movements, or infrastructure construction material flows. Limited predictability restricts operator willingness to dedicate fixed assets.
- Short-term:Spot market transportation and overflow warehousing responding to demand surges or port congestion disruptions. Price volatility and capacity scarcity characterize this tier.
- Seasonal:Agricultural input distribution and pre-Eid retail replenishment create predictable annual spikes. Operators maintain flexible labor pools and temporary facility leases to serve cyclical demand.
Long-term contracts absorb the bulk of facility investment; project-based arrangements are climbing the fastest as infrastructure construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dhaka-Chittagong industrial belt anchors Bangladesh contract logistics demand, with bonded warehouse capacity clustering around export processing zones and automated customs corridors. Chittagong port congestion and Bangladesh Bank documentation rules concentrate operator investment along this corridor.
Dhaka Metropolitan
Apparel exporters in Gazipur and Narayanganj absorb fleet capacity tied to European buyer delivery windows. Bangladesh Bank's real-time foreign-exchange reporting mandate forces API integration between warehouse management systems and central bank databases. Ashulia clusters host vendor-managed inventory platforms serving European compliance programs.
Chittagong Division
Dry-port capacity additions near the port pull bonded warehouse demand from traditional port-adjacent facilities. National Board of Revenue customs modernization concentrates demand around automated clearance corridors. Anwara and Sitakunda industrial zones synchronize inventory with customs-synchronized tracking systems.
Sylhet Division
Agricultural input distribution creates predictable seasonal spikes for contract logistics operators. The country's national agricultural regulator oversees fertilizer and seed movement documentation. Sunamganj and Moulvibazar sub-districts maintain flexible labor pools for cyclical harvest logistics.
Rajshahi Division
Mango and lychee export cold-chain requirements generate specialized pharmaceutical-grade storage demand. Bangladesh Bank export receipt validation rules apply to perishable foreign-exchange earnings. Chapainawabganj and Rajshahi city host temperature-controlled consolidation points for Middle Eastern markets.
Khulna Division
Shrimp processing export units require bonded cold-chain facilities meeting HACCP international standards. National Board of Revenue enforces customs-bonded warehouse licensing for aquaculture exporters. Mongla port expansion creates alternative gateway capacity to Chittagong congestion.
Bangladesh Contract Logistics Market Competitive Landscape
Capital-heavy asset owners compete with asset-light platform operators across Bangladesh's contract logistics market. Integrated ocean-feeder networks, captive warehouse portfolios, and technology-licensed intermediaries represent three coexisting strategic archetypes. Market structure tilts toward consolidation near Dhaka-Chittagong corridors where bonded licensing creates barriers. Dominant competitive moves include customs automation pre-positioning and dry-port capacity anchoring.
Within the integrated network tier, Maersk and Kuehne + Nagel occupy positions shaped by ocean-feeder control and European buyer compliance integration respectively. DHL Supply Chain exemplifies the specialized cold-chain archetype serving Dhaka's pharmaceutical corridor. These three anchors demonstrate how geographic origin and service specialization stratify competitive positioning without overlapping operational footprints.
| Leading Market Players |
|---|
| Maersk |
| DHL Supply Chain |
| Kuehne + Nagel |
| DB Schenker |
| CEVA Logistics |
| XPO Logistics |
| Agility |
| Yusen Logistics |
| We Freight |
| Others |
Pricing and Supply Chain Analysis
Bangladesh Bank's real-time foreign-exchange reporting mandate gates both qualified supply and premium-tier pricing access, as operators lacking API-integrated warehouse management systems face exclusion from formal sector contracts while licensed providers command bonded warehouse premiums.
Pricing Analysis
Outcome-based pricing tied to customs clearance velocity and inventory accuracy anchors contract structures for bonded warehouse services. Three-tier pricing structure across premium, standard, and economy levels separates licensed operators with Bangladesh Bank certification from unlicensed competitors and spot-market brokers. Cost compression in transportation-heavy portfolios is intensifying because Chittagong port congestion penalties erode margins. E-commerce last-mile operators exhibit highest price sensitivity, while pharmaceutical cold-chain buyers accept premium positioning for temperature-controlled compliance.
Supply Chain Analysis
Freight cost volatility between Dhaka and Chittagong corridors shapes operator margin structures and asset deployment decisions. Supply concentrates in Bangladesh's garment belt, with feeder vessel capacity from Singapore and Colombo feeding Chittagong port movements. Diesel fuel, bonded warehouse construction materials, and temperature-controlled equipment draw from regional import channels. Single-source vulnerability around Chittagong port congestion creates systemic risk for just-in-time delivery commitments. Distribution runs through licensed bonded facilities with customs-synchronized inventory tracking before final feeder vessel connection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dhaka's industrial land scarcity props pricing for licensed bonded warehouse capacity, creating a supply-constrained environment where operators with pre-positioned assets capture disproportionate contract flow.
For Market Incumbents: To counter disintermediation from large exporters negotiating ocean-feeder slots independently, deepen upstream integration into vendor-managed inventory platforms at Ashulia and Gazipur clusters while securing preferred queue positioning through early customs automation adoption. For New Entrants and Emerging Players: Enter via peripheral district sortation centers in Dhaka's outer zones where land availability exceeds core metropolitan constraints, targeting e-commerce volume concentration with asset-light partnership models rather than captive fleet investment. For Investors and Strategic Acquirers: National Board of Revenue digital clearance corridor investments is the leading indicator that early-mover operators will secure sustainable competitive positioning. Five-to-ten year viability favors licensed operators with bonded warehouse portfolios and API-integrated compliance infrastructure. Watch for Bangladesh Bank documentation rule expansions as the signal for accelerated market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Licensing Investment | Bangladesh Bank certification creates barrier to entry and pricing power for compliant operators. |
| Customs Automation Pre-Positioning | National Board of Revenue digital corridor investments reward early movers with reduced inspection frequency. |
| Peripheral Sortation Center Development | Dhaka outer zone land availability enables greenfield e-commerce infrastructure beyond metropolitan constraints. |
| Cold-Chain Capability Expansion | Temperature-controlled pharmaceutical storage meets international buyer audit standards and commands premium contracts. |
| Vendor-Managed Inventory Integration | Upstream platform deployment at Ashulia clusters aligns with European buyer compliance program requirements. |
Research Methodology
Document review covered customs authority filings, Bangladesh Bank regulatory circulars, and export processing zone development records, complemented by interviews with bonded warehouse operators, apparel exporter logistics directors, pharmaceutical supply chain managers, and National Board of Revenue officials. Secondary validation drew from trade association publications, port authority throughput statistics, and central bank foreign-exchange documentation guidelines. Bottom-up facility capacity assessments and top-down export value triangulation anchored market sizing.
Segmentation outputs across service type, end user, technology deployment, and contract duration dimensions were modeled over the projection horizon. CAGRs were derived from export volume growth trajectories, processing zone expansion timelines, and customs automation penetration curves. Forecast inputs incorporated bonded warehouse licensing queue data and pharmaceutical cold-chain investment flows.
Revisions become necessary when Bangladesh Bank documentation rules expand, Chittagong port congestion penalties escalate, or European buyer procurement patterns shift toward direct ocean-feeder negotiation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Air Freight Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Europe Logistics Automation Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Outbound Logistics Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
Inland Container Depot and Dry Port Market