
 Germany Express Delivery Market | 2026-2036
Germany Express Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Express Delivery Market Insights
Last-mile electrification investment is reconfiguring capital allocation across German express networks. DHL Group leverages its StreetScooter manufacturing footprint to control electric van supply for urban routes. Hermes Europe GmbH anchors its position through a dense network of parcel shops and automated pickup stations. DB Schenker competes on intercity trunk efficiency, linking industrial zones to regional distribution hubs with scheduled rail-road combinations.
Germany express delivery encompasses time-critical parcel and document transport services operating within guaranteed windows, typically leveraging integrated sorting hubs, GPS-tracked vehicle fleets, and electronic proof-of-delivery systems to achieve service-level agreements measured in hours. Same-day and next-day service categories dominate volume throughput, while time-definite scheduled offerings capture premium-margin corporate contracts for automotive and pharmaceutical supply chains. Cargo truck and van delivery modes handle the bulk of intercity freight, though drone pilot programs in Bavaria and Baden-Württemberg signal emerging structural options for urgent medical and high-value shipments.
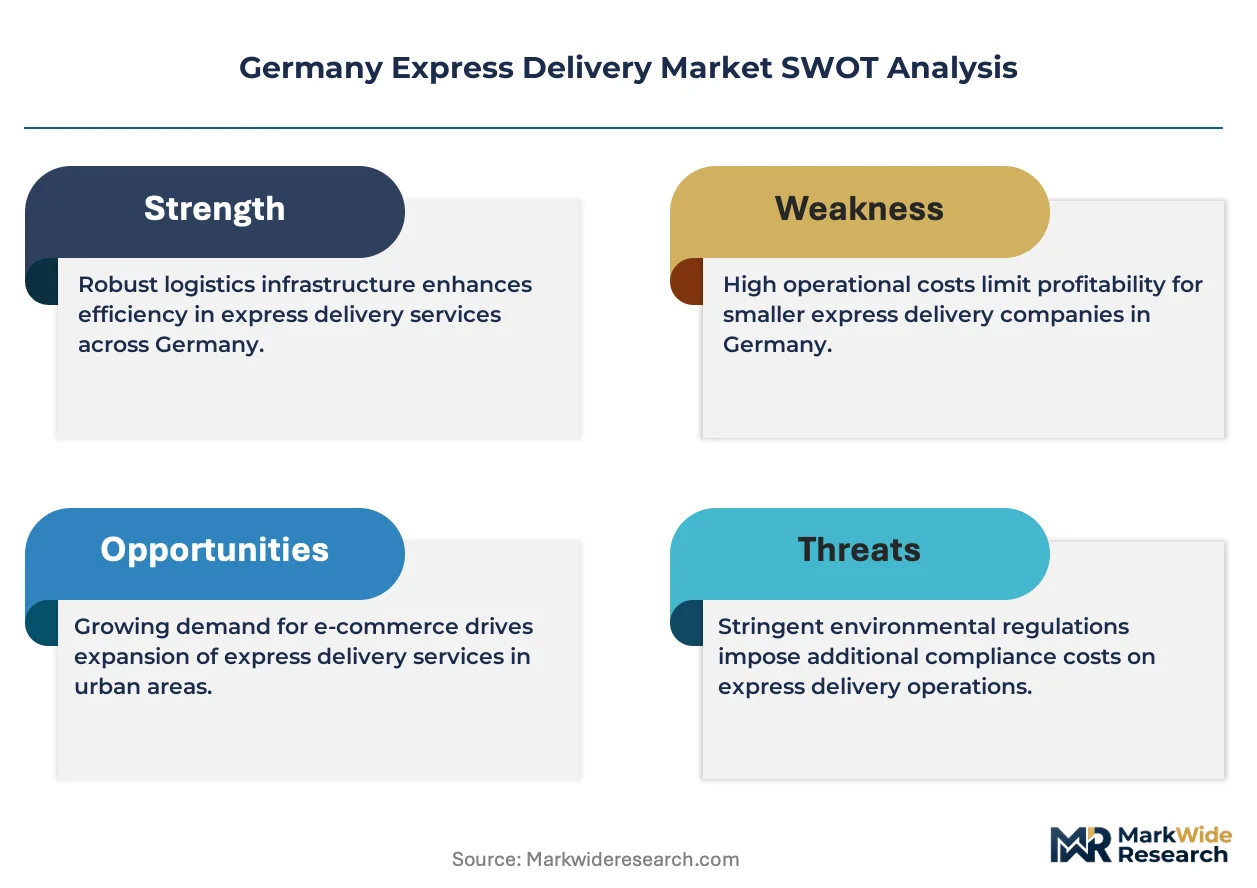
The EU Green Deal and Germany's national climate targets enforced by the Federal Motor Transport Authority (KBA) mandate progressive fleet CO2 reductions, compelling operators to retire diesel vehicles ahead of residual value cycles. REACH compliance for battery materials and packaging waste directives from the Federal Environment Agency shape procurement standards for electric vehicle components and recyclable shipping materials. Stakeholders must weigh the capital intensity of zero-emission fleet conversion against the regulatory risk of delayed compliance in an environment where municipal low-emission zones expand unpredictably.
Market Dynamics
Fleet electrification mandates from the KBA are forcing express operators to restructure capital deployment toward battery-electric vans and charging infrastructure, compressing residual value recovery timelines for diesel assets.
Growth Catalysts
- EU Green Deal fleet mandates:Binding CO2 reduction targets for commercial vehicles accelerate replacement cycles and open subsidy windows for zero-emission procurement.
- E-commerce fashion and electronics throughput:Metropolitan corridor density in Rhine-Ruhr and Rhine-Main agglomerations sustains parcel volume expansion with predictable route economics.
- Automated pickup station deployment:Parcel shop networks reduce failed delivery rates and lower per-stop labor costs in urban last-mile configurations.
Market Restraints
- Battery supply concentration:Cell production bottlenecks and raw material processing constraints in Asia-Pacific create procurement risk for fleet conversion timelines.
- REACH compliance friction:Chemical registration requirements for battery electrolytes and thermal management fluids extend component qualification periods.
- Intermodal rail capacity limits:Scheduled rail-road combinations face terminal congestion at Mannheim and Cologne hubs during peak retail windows.
Strategic Opportunities
- Drone pilot corridors:Bavaria and Baden-Württemberg regulatory sandboxes enable urgent medical and high-value shipment networks beyond road congestion.
- Carbon border adjustment mechanisms:EU CBAM phase-in creates competitive advantage for operators with verified low-emission last-mile credentials.
- Reverse logistics integration:Apparel and electronics retailers demand consolidated return stream handling, opening margin capture from historically cost-draining flows.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance networks lack certified personnel for battery-electric van diagnostics and repair at sufficient scale.
- Legacy IT integration:Route optimization platforms require reconfiguration to incorporate real-time charging station availability and range constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Express Delivery Market |
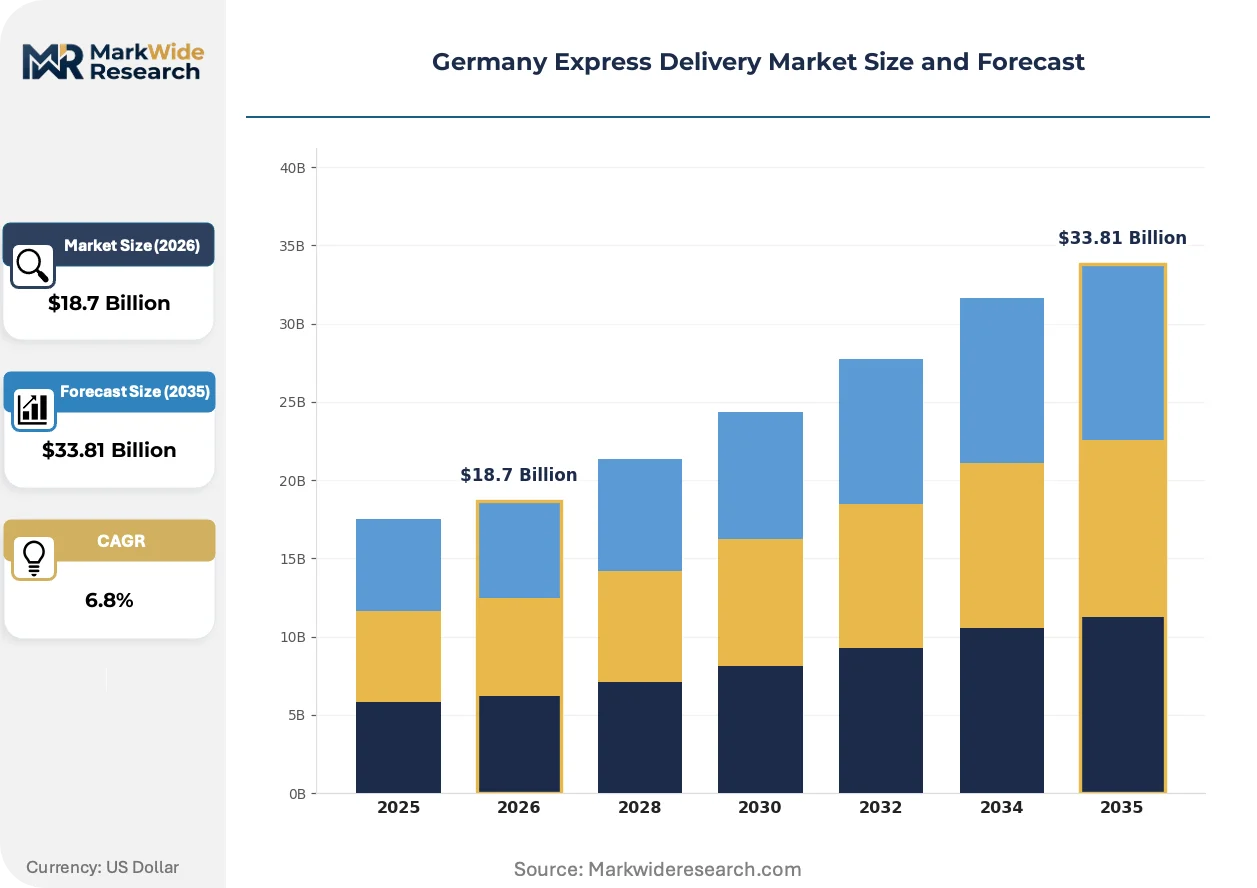
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same Day, Next Day, Time-Definite, Scheduled Delivery Mode: Motorcycle, Van, Cargo Truck, Drone Customer Type: E-Commerce, Retail, Corporate, Individual Payment Model: Prepaid, Postpaid, Subscription, Pay-As-You-Go |
| Companies Covered | DHL Group, Hermes Europe GmbH, Dynamic Parcel Distribution (DPD), General Logistics Systems B.V. (GLS), United Parcel Service (UPS), FedEx Express, DB Schenker, Amazon Logistics, Go Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Express Delivery Market Trends and Innovations
Operational digitization and zero-emission infrastructure deployment are compressing cost structures while regulatory enforcement tightens performance standards for urban delivery networks.
Dynamic route optimization algorithms fed by real-time traffic, weather, and customer presence data are collapsing delivery window variance for same-day services. Electronics retailers and pharmaceutical distributors deploy these systems to hit two-hour commitment windows. The compression of route uncertainty enables labor pool flexibilization through gig-platform integration without service degradation.
KBA enforcement of Germany's national climate targets binds express operators to progressive fleet CO2 reductions with audit-ready documentation. Non-compliance triggers exclusion from municipal procurement contracts and low-emission zone access permits. Automotive and pharmaceutical supply chain contracts now mandate zero-emission last-mile performance as a qualification threshold.
Consolidated pickup point preferences among urban consumers are displacing home delivery as the default expectation. Parcel shop and locker networks absorb volume that previously required multiple delivery attempts. Berlin and Hamburg show the fastest channel shift, with automated station density approaching one unit per thousand households in core districts.
Germany Express Delivery Market Segmentation
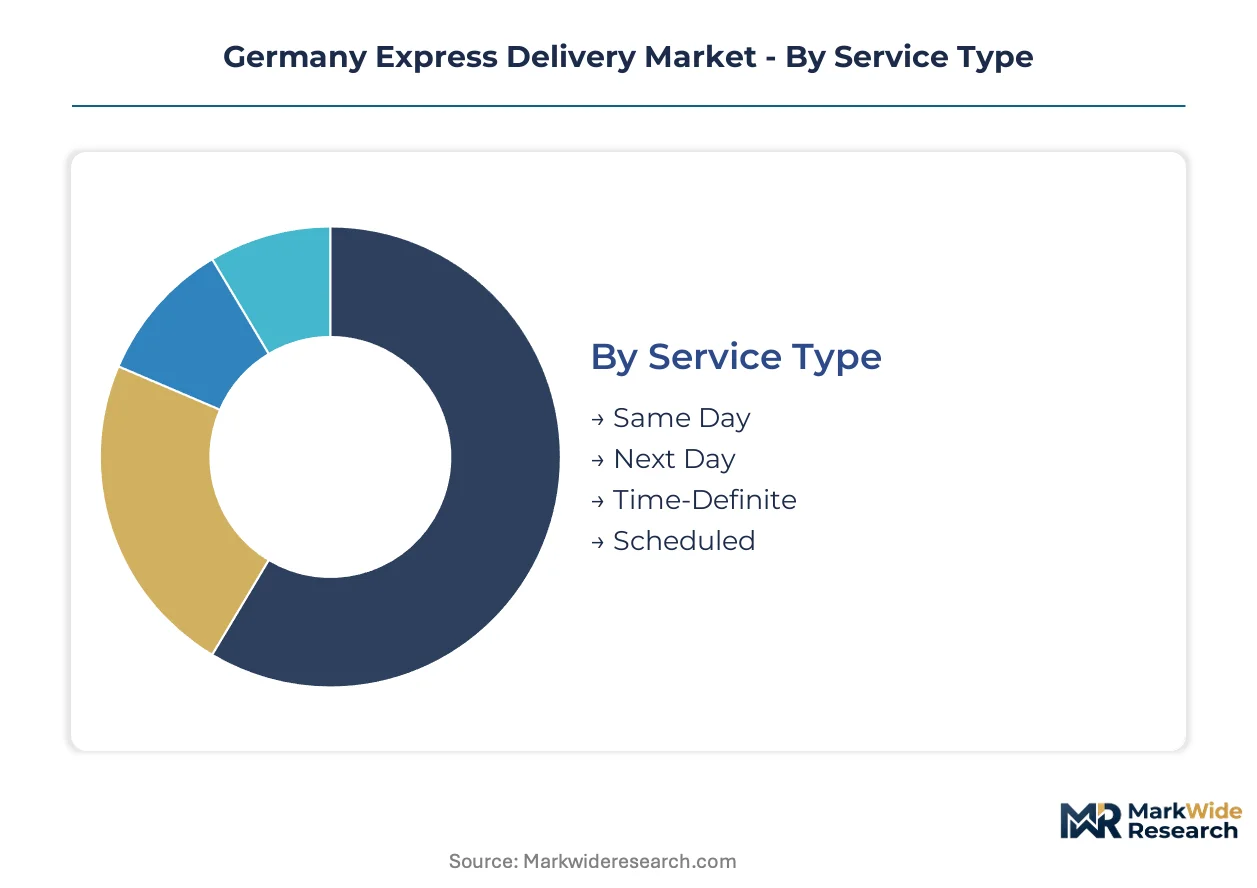
Segmentation in the Germany express delivery market reveals distinct operational economics across service tiers and delivery infrastructure. Each dimension shapes capital deployment, fleet composition, and last-mile density requirements differently across metropolitan corridors.
Service Type:
After-sales service intensity varies sharply across service tiers, with time-definite and same-day offerings demanding real-time exception management and dedicated customer support infrastructure.
- Same Day:Two-hour and four-hour commitment windows require dynamic routing algorithms integrated with real-time traffic feeds. Demand concentrates in Berlin and Munich for pharmaceutical and electronics emergency replenishment, where stockout costs exceed premium delivery fees.
- Next Day:Guaranteed 24-hour delivery operates through hub-and-spoke networks with cutoff-time discipline. Rhine-Ruhr and Rhine-Main agglomerations sustain volume density that justifies dedicated sorting capacity and scheduled line-haul departures.
- Time-Definite:Precision scheduling for automotive and manufacturing supply chains with contractual penalty clauses for missed windows.
- Scheduled:Recurring pickup and delivery slots for corporate mailrooms and distribution centers with predictable volume profiles.
Next Day holds the largest share; momentum sits with Same Day as electronics and pharmaceutical retailers compress replenishment cycles.
Delivery Mode:
Cost tier differentiation separates high-frequency urban routes from intercity trunk movements, with electrification mandates reshaping vehicle procurement priorities.
- Van:Battery-electric and diesel panel vans handle 70% plus of parcel volume through urban and suburban routes. KBA fleet mandates accelerate conversion timelines in Berlin, Hamburg, and Cologne low-emission zones where diesel access permits face phase-out.
- Cargo Truck:Articulated and rigid trucks manage intercity trunk hauls between regional distribution centers. Scheduled rail-road combinations at Mannheim and Cologne terminals compete for long-haul efficiency against pure road options.
- Motorcycle:Two-wheelers navigate congestion in historic city centers with parking constraints and narrow street grids.
- Drone:Pilot programs in Bavaria and Baden-Württemberg test urgent medical delivery beyond road network reach.
Van dominates current volume; cargo truck electrification trials are expanding most quickly as battery-electric rigid models achieve range viability for regional corridors.
Customer Type:
Application focus determines route density patterns, with e-commerce driving residential delivery proliferation while corporate accounts anchor scheduled network efficiency.
- E-Commerce:Fashion and electronics retailers generate parcel volume with high return rates and delivery attempt failure costs. Automated pickup station deployment in Berlin and Hamburg reduces per-stop labor intensity for last-mile operators.
- Corporate:B2B contracts with automotive and pharmaceutical supply chains demand time-definite performance with audit-ready documentation. EU Green Deal compliance requirements now embed zero-emission last-mile clauses in procurement specifications.
- Retail:Omnichannel fulfillment from store inventory requires ship-from-store integration with existing express networks.
- Individual:Document and small parcel shipments with lower frequency and higher price sensitivity.
E-Commerce holds the largest share; momentum sits with Corporate as sustainability procurement mandates harden qualification thresholds.
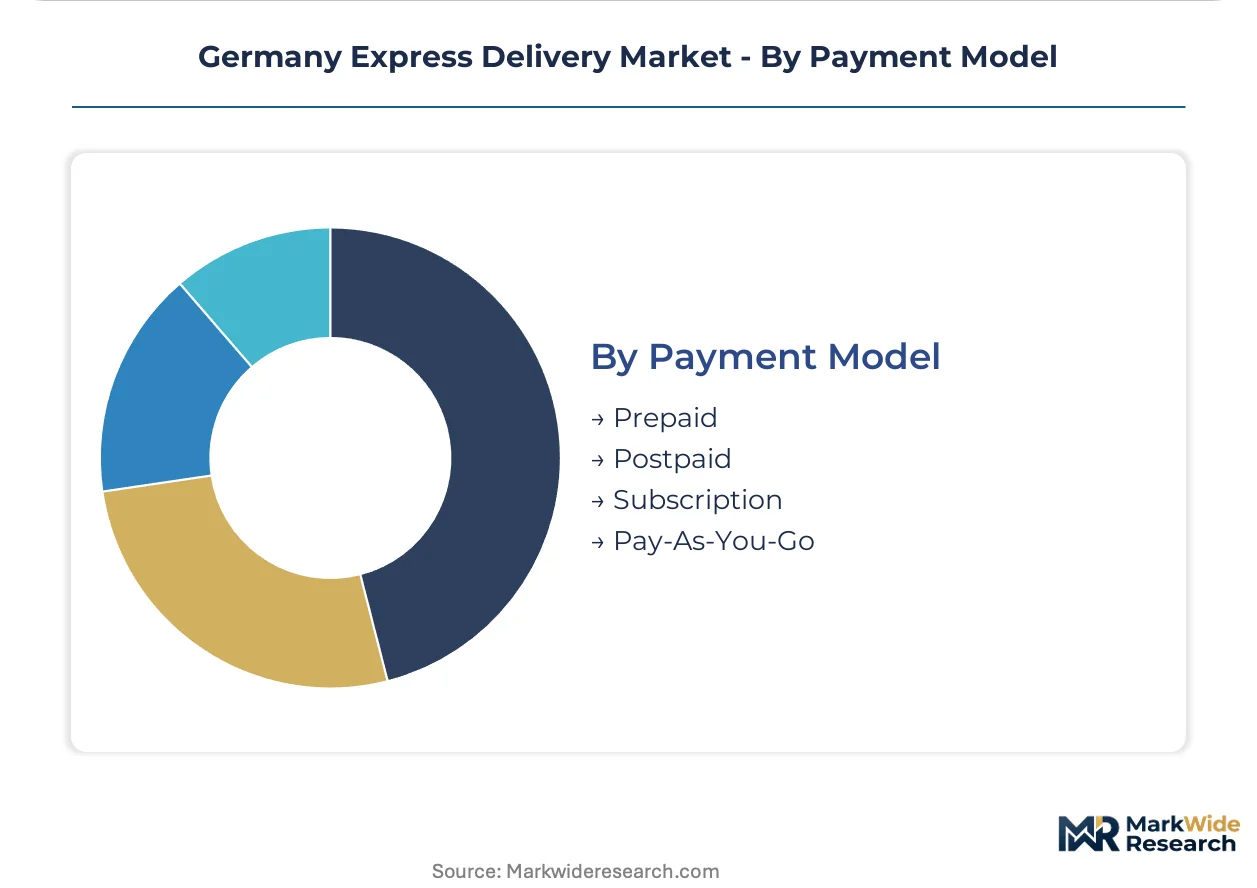
Payment Model:
Customer relationship duration and cash flow predictability separate prepaid transactional shipments from contracted subscription arrangements with enterprise accounts.
- Prepaid:Single-shipment payment at point of order dominates e-commerce integration with retailer checkout flows.
- Postpaid:Monthly invoicing for corporate accounts with consolidated shipping activity and negotiated rate cards.
- Subscription:Flat-fee unlimited delivery plans for frequent shippers with predictable volume commitments.
- Pay-As-You-Go:Top-up credit models for occasional individual shippers without account establishment requirements.
Prepaid holds the largest share; momentum sits with Subscription as platform integration deepens habitual shipping behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Express delivery demand elasticity varies sharply across German sub-regions, with dense metropolitan corridors showing price inelasticity for same-day services while peripheral rural zones remain highly sensitive to surcharges. Corporate procurement in industrial clusters absorbs premium pricing for time-definite contracts, whereas individual e-commerce consumers in cost-conscious regions default to economy options.
North Rhine-Westphalia
The Rhine-Ruhr agglomeration generates the highest parcel throughput density in Germany, driven by fashion e-commerce fulfillment centers and automotive component supply chains. KBA fleet decarbonization mandates accelerate electric van deployment across Cologne and Düsseldorf distribution networks. The Ruhr industrial corridor anchors intermodal rail-road terminals at Duisburg and Dortmund, where scheduled trunk hauls compete with pure road options.
Bavaria
Munich's pharmaceutical and electronics manufacturing clusters sustain premium same-day demand for emergency replenishment services with minimal price sensitivity. Bavarian regulatory sandboxes enable drone pilot programs for urgent medical deliveries beyond road network reach. The Nuremberg-Erlangen industrial zone concentrates semiconductor and medical device logistics requiring time-definite performance with audit-ready documentation.
Baden-Württemberg
Stuttgart's automotive supply chain density drives scheduled delivery contracts with contractual penalty clauses for missed windows. The state's climate action plan mandates municipal low-emission zone expansion in Karlsruhe and Freiburg, compressing diesel vehicle residual value recovery timelines. The Rhine-Neckar metropolitan region links Mannheim's intermodal terminal to express networks serving chemical and pharmaceutical distribution.
Hesse
Frankfurt's financial services and pharmaceutical headquarters generate high-margin document and temperature-controlled shipments with strict compliance requirements. Rhine-Main airport cargo infrastructure supports time-critical international express connections with domestic last-mile integration. The EU Green Deal's carbon border adjustment mechanisms create competitive advantage for operators with verified low-emission credentials in this procurement-heavy corridor.
Berlin-Brandenburg
Berlin's e-commerce consumer density drives the fastest adoption of automated pickup stations, with locker networks approaching one unit per thousand households in core districts. The city's low-emission zone enforcement by the Federal Motor Transport Authority excludes non-compliant diesel fleets from central district access. Brandenburg's logistics parks at Schönefeld and Großbeeren absorb overflow sorting capacity from constrained Berlin urban operations.
Germany Express Delivery Market Competitive Landscape
Capability concentration sits with integrated postal operators controlling manufacturing and fleet supply; scale advantage sits with platform-integrated logistics networks leveraging density economics. The vendor base stratifies across three tiers: national postal incumbents with captive infrastructure, European parcel networks with dense pickup point coverage, and platform-integrated specialists serving e-commerce fulfillment. Dominant competitive moves include fleet electrification capital deployment and automated pickup station network densification.
Among Germany-based integrated operators, DHL Group and Hermes Europe GmbH exemplify divergent strategic archetypes. DHL Group occupies a position defined by upstream manufacturing control through captive electric van production. Hermes Europe GmbH anchors its competitive stance through parcel shop density and automated locker penetration in metropolitan corridors. DB Schenker represents the intermodal efficiency archetype, linking industrial zones to regional hubs through scheduled rail-road combinations.
| Leading Market Players |
|---|
| DHL Group |
| Hermes Europe GmbH |
| Dynamic Parcel Distribution (DPD) |
| General Logistics Systems B.V. (GLS) |
| United Parcel Service (UPS) |
| FedEx Express |
| DB Schenker |
| Amazon Logistics |
| Go Express |
| Others |
Pricing and Supply Chain Analysis
Rhine-Ruhr logistics park concentration anchors fleet procurement leverage for German express operators, with Duisburg and Dortmund distribution hub density translating into volume-based equipment pricing power against van manufacturers. Battery-electric conversion timelines compress residual value recovery for diesel assets, forcing operators to absorb accelerated depreciation while negotiating charging infrastructure scale discounts.
Pricing Analysis
After-sales service intensity drives lifetime value capture across German express networks, with time-definite contracts bundling real-time tracking and exception management at premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates same-day pharmaceutical emergency replenishment from next-day e-commerce and scheduled corporate mailroom services. Cost compression in standard-tier parcel delivery is intensifying because automated pickup station deployment reduces per-stop labor intensity. Individual e-commerce consumers show highest price sensitivity, defaulting to economy options when surcharges apply, while automotive supply chain procurement shows minimal elasticity for time-definite performance guarantees.
Supply Chain Analysis
Tariff exposure between China and Germany dominates battery cell procurement risk for fleet electrification programs, with Asian-Pacific processing concentration for lithium and cobalt creating single-source vulnerability. Cell production draws from China, South Korea, and Japan, while thermal management fluids and power electronics components rest on German and Czech manufacturing footprints. Supply chain risk centers on REACH compliance friction extending component qualification periods for electrolyte chemistry variants. Distribution runs through regional distribution hubs at Mannheim and Cologne, with scheduled rail-road combinations competing against pure road options for intercity trunk efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among e-commerce platform operators and automotive OEM procurement functions, with volume consolidation across fashion and electronics retail compressing rate negotiation leverage for express carriers.
For Market Incumbents: Entrench position through captive electric van manufacturing scale and automated pickup station density in Berlin and Hamburg metropolitan corridors. Battery supply agreements with Asian cell producers anchor fleet conversion timelines against procurement bottlenecks. Channel control via parcel shop networks defends margin position against platform-integrated logistics entrants. For New Entrants and Emerging Players: Build out drone pilot corridor specialization in Bavaria and Baden-Württemberg regulatory sandboxes for urgent medical and high-value shipments beyond road network constraints. Reverse logistics integration for apparel and electronics returns represents the most penetrable white-space target, with consolidated return stream handling capturing margin from historically cost-draining flows. Go-to-market angle should emphasize carbon border adjustment mechanism compliance credentials for EU procurement-heavy corridors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with verified low-emission last-mile infrastructure and dense automated pickup networks over pure asset-light platform models. Long-term viability over the next decade hinges on KBA fleet mandate compliance execution and charging infrastructure scale economics. Acquisition target archetype: regional operators with established low-emission zone access permits and captive technician training pipelines for high-voltage diagnostics. Signal to watch: municipal procurement contract award patterns favoring zero-emission performance thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Acceleration | KBA mandate compliance secures low-emission zone access permits in Cologne and Berlin districts. |
| Automated Pickup Station Densification | Locker networks approaching one unit per thousand households reduce failed delivery labor costs. |
| Drone Corridor Regulatory Sandbox Entry | Bavaria and Baden-Württemberg pilot programs enable urgent medical delivery beyond road congestion. |
| Reverse Logistics Integration | Consolidated returns handling captures margin from apparel and electronics retailer cost drains. |
| Intermodal Rail-Road Capacity Expansion | Scheduled combinations at Mannheim and Cologne terminals compete for long-haul efficiency against road. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, last-mile logistics managers, e-commerce supply chain executives, and KBA regulatory compliance officers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of Federal Motor Transport Authority enforcement patterns, EU Green Deal implementation documentation, and customs data on electric van component trade flows. Bottom-up volume modeling across service tiers and delivery modes triangulated against top-down macroeconomic freight demand indicators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, delivery mode, customer category, and payment model plus fleet propulsion technology mix. CAGRs were derived from trajectory analysis of e-commerce penetration rates and regulatory compliance cost curves. Industry-specific forecast inputs incorporated KBA fleet CO2 reduction mandates and municipal low-emission zone expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated logistics specialists or battery supply chain disruptors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
UK Freight Forwarding Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
South Korea Parcel Delivery Market