
 Germany Dangerous Goods Logistics Market | 2026-2036
Germany Dangerous Goods Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Dangerous Goods Logistics Market Insights
Lithium-ion battery chemistries is expanding their share of dangerous goods volumes as electrification redraws logistics economics. DB Schenker leverages its European rail network to anchor temperature-controlled battery transport across Germany. DHL sustains dominance in pharmaceutical dangerous goods through certified cold-chain infrastructure. Hellmann Worldwide Logistics specializes in project cargo involving oversized hazardous equipment.
Germany Dangerous Goods Logistics encompasses the planning, execution, and compliance management of transporting substances classified under ADR, IATA, IMDG, and RID standards, requiring specialized packaging, labeling, vehicle certification, and trained personnel. Flammable liquids transport leads volume flows due to Germany's petrochemical refining density around Cologne and Ludwigshafen. Radioactive materials logistics commands premium margins given the dual-use nuclear medicine and research reactor ecosystem. Road delivery mode occupies the largest share of domestic movements, though rail is capturing intermodal flows for bulk chemicals.
Germany's KBA enforces ADR vehicle and driver certification standards, while the Federal Office for Goods Transport monitors cross-border compliance. REACH and the EU Green Deal are forcing logistics providers to document chemical substance flows and carbon intensity per shipment. Stakeholders must monitor how the EU AI Act shapes automated hazardous goods inspection protocols before committing to sensor infrastructure investments.
Market Dynamics
Germany's Supply Chain Due Diligence Act is compressing liability onto logistics providers, forcing hazardous material handlers to document every custody transfer and subcontractor certification across the Rhine-Ruhr chemical corridor.
Growth Catalysts
- Battery electrification:Automotive OEMs in Stuttgart and Munich are outsourcing lithium-ion transport to certified cold-chain specialists as cell production scales.
- REACH substance tracking:Chemical manufacturers must document full material flows, creating retained demand for audit-capable logistics partners with digital chain-of-custody systems.
- Rhine-Ruhr refining density:Petrochemical clusters around Cologne and Ludwigshafen generate continuous flammable liquid volumes requiring specialized tanker and intermodal capacity.
Market Restraints
- Driver certification scarcity:KBA-mandated ADR training programs face 6-month backlogs, constraining fleet expansion regardless of vehicle availability.
- Specialized packaging cost:UN-certified containers for Class 1 explosives and Class 7 radioactive materials carry 3-4x standard freight packaging premiums.
- Rail infrastructure fragmentation:RID-compliant rolling stock concentrates with DB Cargo, limiting multimodal flexibility for non-captive chemical shippers.
Strategic Opportunities
- Port of Rotterdam-Hamburg corridor:Battery-grade lithium hydroxide imports from Chile and Australia are concentrating customs clearance and bonded warehousing demand in northern Germany.
- EU AI Act inspection protocols:Automated hazardous goods screening using computer vision creates first-mover advantage for terminals investing in sensor infrastructure before 2026 implementation deadlines.
- Pharmaceutical cold-chain:Cell and gene therapy shipments require cryogenic logistics capabilities that generalist temperature-controlled carriers cannot replicate.
Industry Challenges
- ADR certification timelines:Vehicle type approvals and driver qualification renewals create operational gaps during peak chemical shipping seasons.
- Legacy IT integration:Real-time dangerous goods tracking systems must interface with shipper ERP platforms built on incompatible data standards.
- Carbon accounting granularity:EU Green Deal reporting requires emissions per shipment calculations that most logistics providers lack fuel-consumption telemetry to generate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Dangerous Goods Logistics Market |
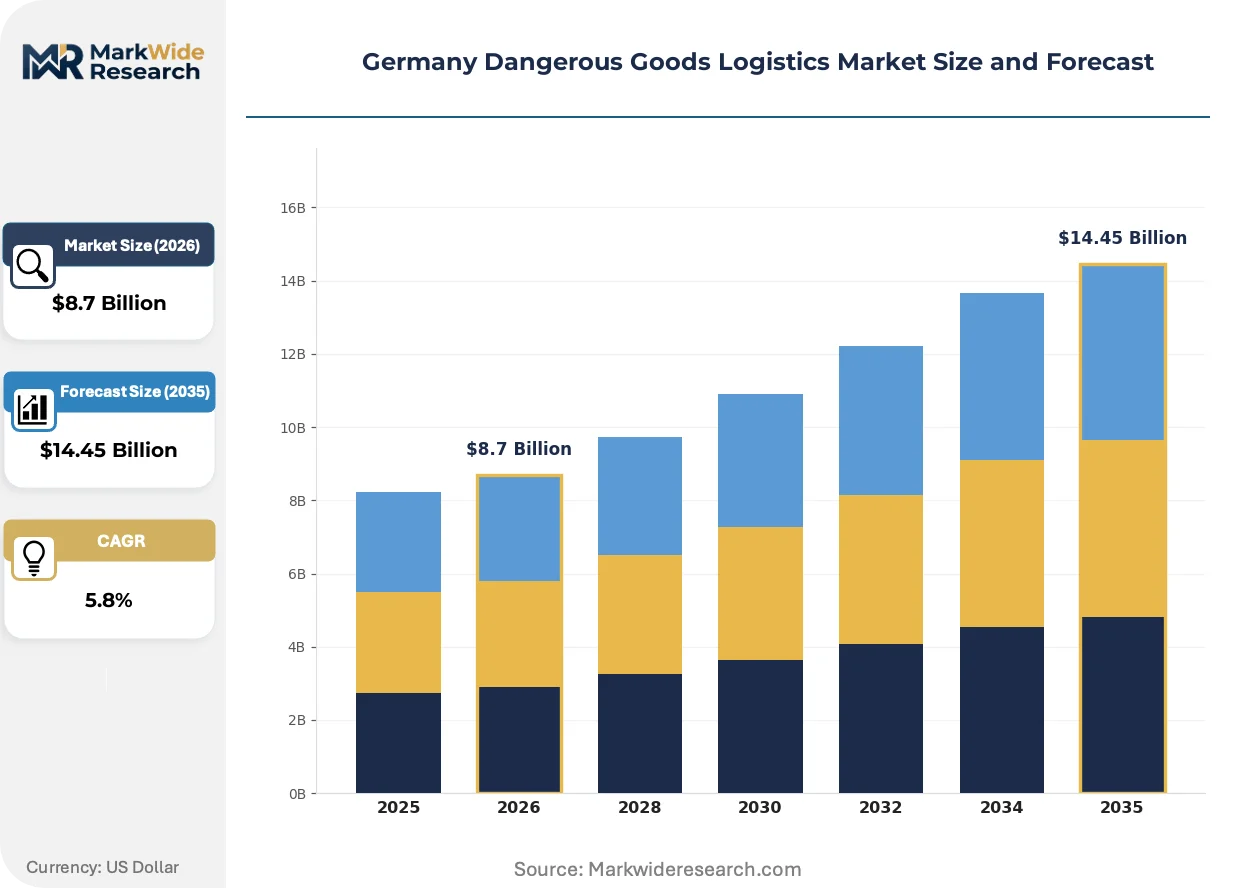
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Explosives, Flammable Liquids, Radioactive Materials, Toxic Substances Service Type: Transportation, Warehousing, Packaging, Consultation Delivery Mode: Road, Rail, Air, Sea Compliance Standard: ADR, IATA, IMDG, RID |
| Companies Covered | DHL, DB Schenker, Kuehne + Nagel, Hellmann Worldwide Logistics, UPS, DACHSER, Gebrüder Weiss, Rhenus Logistics, Panalpina, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Dangerous Goods Logistics Market Trends and Innovations
Digital custody verification and automated inspection systems are displacing paper-based dangerous goods documentation across German chemical logistics corridors.
Sensor-equipped UN-certified containers with blockchain-anchored custody records are automating compliance verification for cross-border chemical shipments. Pharmaceutical manufacturers and battery producers are adopting these units fastest, paying 15-20% freight premiums for real-time temperature and shock monitoring. The technology is automating audit preparation and reducing customs detention incidents at Rotterdam and Hamburg terminals.
REACH substance registration requirements now mandate digital safety data sheet exchange through standardized EDI protocols. Chemical distributors must reconfigure warehouse management systems to capture batch-level substance identifiers for every pallet movement. Small and mid-sized logistics providers in the Rhine-Neckar region are consolidating to afford compliance infrastructure investments.
Just-in-sequence delivery contracts are replacing traditional inventory-holding arrangements for hazardous raw materials. Automotive battery plants in Lower Saxony now require lithium carbonate arrivals synchronized to production line schedules within 4-hour windows. This procurement compression is visible most acutely among cathode material processors supplying CATL and Volkswagen Group facilities.
Germany Dangerous Goods Logistics Market Segmentation
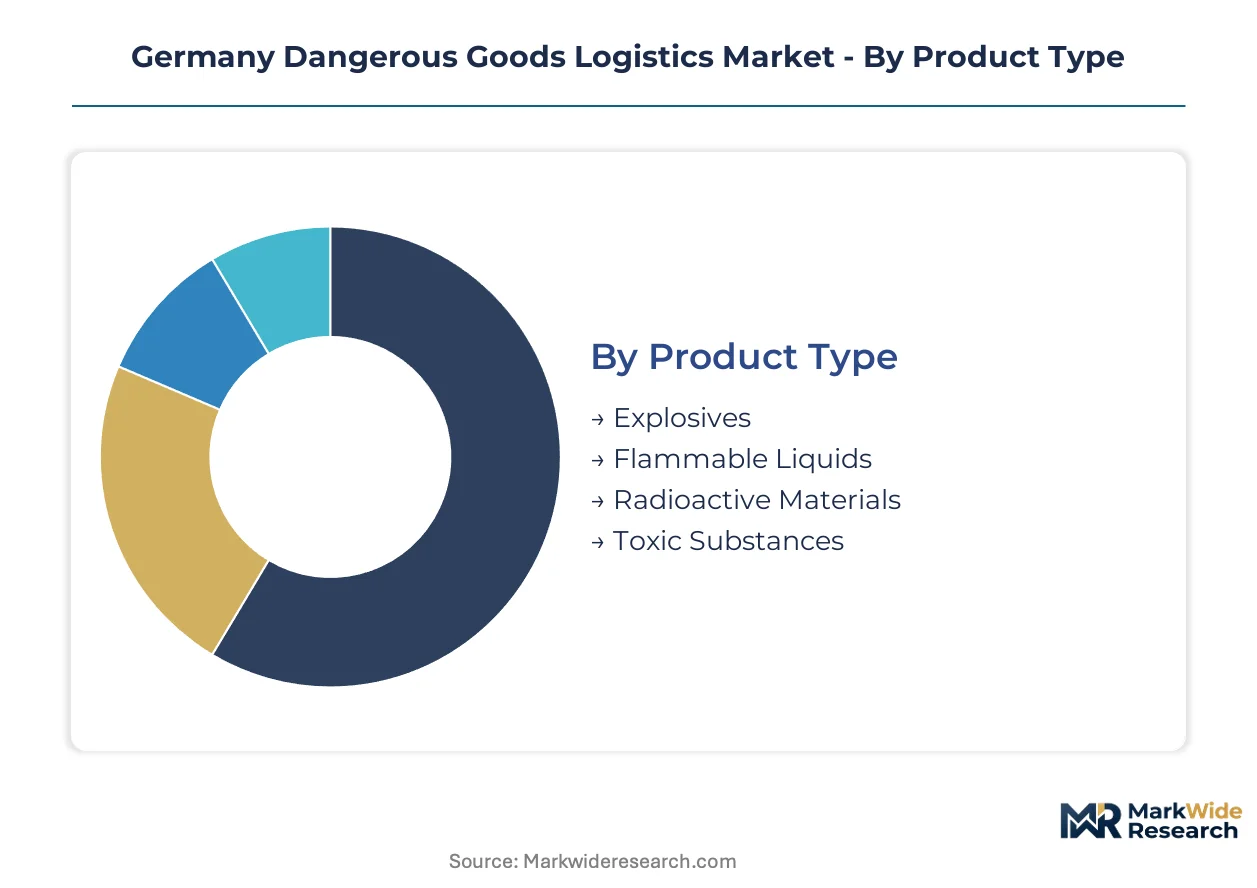
Dangerous goods logistics in Germany fragments across chemical hazard classes, service intensity tiers, and modal infrastructure availability. Each segmentation axis carries distinct compliance burdens and margin profiles that reshape carrier specialization strategies.
Product Type:
Volume concentration sits with flammable liquids, while premium margins concentrate in radioactive materials where dual-use medical and research applications sustain pricing power.
- Flammable Liquids:Petrochemical feedstocks and refined fuels dominate tonnage flows, with Rhine-Ruhr refineries around Cologne and Ludwigshafen generating continuous demand for ADR-certified tanker capacity. Chemical manufacturers outsource specialized handling as KBA enforcement tightens custody documentation requirements.
- Radioactive Materials:Class 7 shipments command the highest freight multiples due to specialized shielding, escort protocols, and limited carrier certification. Nuclear medicine isotopes for Heidelberg and Munich research hospitals drive recurring high-value lanes.
- Explosives:Mining and construction blasting materials require UN-certified containment and segregated storage, with demand clustering in Saxony lignite regions.
- Toxic Substances:Industrial chemicals and agrochemical precursors move under strict exposure limits, with REACH batch tracking now mandatory for cross-border movements.
Mature deployment sits with flammable liquids. Newer deployment is concentrated in radioactive materials as nuclear medicine capacity expands.
Service Type:
Transportation captures the largest revenue share, though integrated warehousing and packaging services are climbing fastest as shippers seek consolidated liability structures.
- Transportation:Road haulage handles most domestic movements, with DB Schenker and DHL maintaining certified fleets for temperature-sensitive battery and pharmaceutical cargo. Intermodal rail growth is accelerating for bulk chemicals along Rotterdam-Hamburg corridors.
- Warehousing:Bonded storage for lithium hydroxide and cathode materials is concentrating in Hamburg port zones, with automated climate control and fire suppression systems commanding rent premiums.
- Packaging:UN-certified container production and reconditioning services face supply constraints, with 3-4x cost premiums over standard freight packaging for Class 1 and Class 7 materials.
- Consultation:Compliance advisory and audit preparation are expanding as Supply Chain Due Diligence Act liability compresses onto logistics providers managing subcontractor networks.
Transportation infrastructure is most mature. Consultation services are expanding most quickly as regulatory complexity outpaces shipper internal capabilities.
Delivery Mode:
Road retains domestic dominance, though modal shift incentives and infrastructure investments are redrawing intermodal economics for bulk chemical flows.
- Road:Flexible routing and last-mile access sustain ADR truck dominance for just-in-sequence battery plant deliveries in Lower Saxony and Baden-Württemberg.
- Rail:RID-compliant bulk movements are gaining chemical shipper preference for Rotterdam-Hamburg corridors, though rolling stock concentration with DB Cargo limits non-captive flexibility.
- Air:Frankfurt and Munich airports handle pharmaceutical cold-chain and time-critical nuclear medicine isotopes under IATA dangerous goods protocols.
- Sea:Hamburg port manages lithium hydroxide imports from Chile and Australia, with bonded warehousing and customs clearance integration critical for cathode material processors.
Road deployment is most mature. Rail is gaining share fastest as Rhine corridor congestion and carbon accounting pressure reshape modal selection.
Compliance Standard:
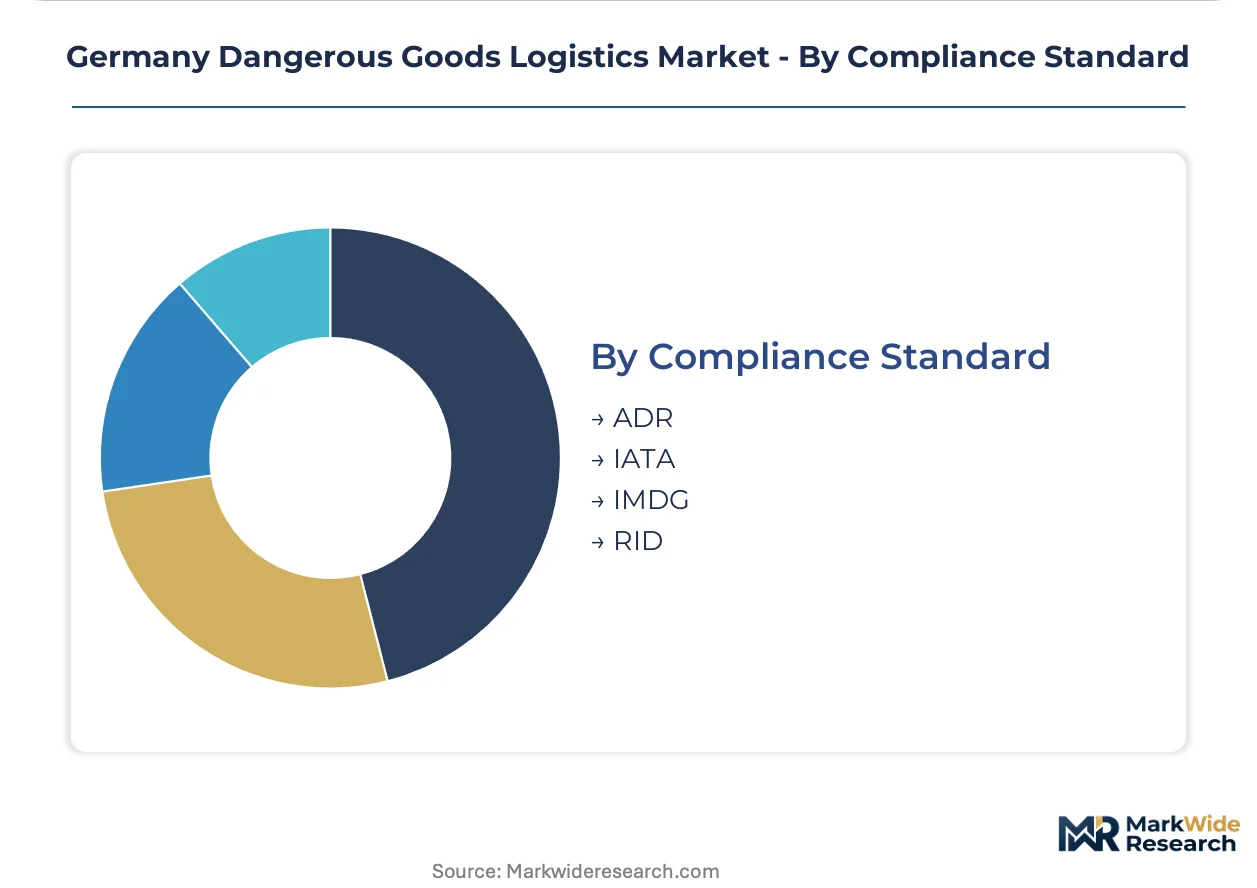
Carrier certification portfolios now determine market access, with multi-standard capabilities becoming table stakes for integrated chemical and battery logistics contracts.
- ADR:Road transport certification enforced by KBA covers the majority of domestic movements, with driver qualification backlogs currently constraining fleet expansion regardless of vehicle availability.
- IATA:Air cargo dangerous goods handling concentrates at Frankfurt and Munich, with pharmaceutical and nuclear medicine shippers requiring certified ground handling agents.
- IMDG:Maritime dangerous goods protocols govern Hamburg port operations for lithium and chemical imports, with documentation automation reducing customs detention incidents.
- RID:Rail dangerous goods standards apply to chemical bulk movements, with infrastructure fragmentation limiting multimodal optionality for non-integrated shippers.
ADR certification is most mature. IATA capabilities are expanding most quickly as pharmaceutical cold-chain and battery air freight volumes accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for dangerous goods logistics concentrates in Germany's industrial corridors, with chemical refining clusters and battery production facilities driving specialized handling requirements across federal states.
North Rhine-Westphalia
The Rhine-Ruhr petrochemical corridor generates sustained flammable liquid volumes from refineries around Cologne and Leverkusen. KBA enforcement of ADR certification standards tightens custody documentation for every transfer point. Chemical manufacturers in Ludwigshafen are outsourcing hazardous material handling as Supply Chain Due Diligence Act liability compresses onto logistics providers.
Baden-Württemberg
Automotive OEMs in Stuttgart are scaling lithium-ion cell production, creating just-in-sequence delivery requirements for cathode materials. REACH substance tracking mandates digital safety data sheet exchange through standardized EDI protocols. Battery plants in Heilbronn and Ulm require 4-hour delivery windows synchronized to production schedules.
Lower Saxony
Volkswagen Group's battery cell factory in Salzgitter anchors demand for temperature-controlled lithium carbonate transport. The Federal Office for Goods Transport monitors cross-border compliance for Rotterdam-Hamburg corridor movements. Cathode material processors supplying CATL facilities are concentrating bonded warehousing demand in Wolfsburg industrial zones.
Bavaria
Munich research hospitals drive recurring high-value nuclear medicine isotope shipments under IATA dangerous goods protocols. EMA pharmaceutical regulations enforce cold-chain integrity for cell and gene therapy logistics. The Munich airport cargo zone handles time-critical radioactive materials for Heidelberg and Tübingen medical centers.
Hamburg
The port manages battery-grade lithium hydroxide imports from Chile and Australia, with bonded warehousing critical for customs clearance integration. EU Green Deal carbon accounting requirements force documentation of emissions per shipment for maritime dangerous goods. Automated inspection systems using computer vision are deploying ahead of EU AI Act implementation deadlines.
Germany Dangerous Goods Logistics Market Competitive Landscape
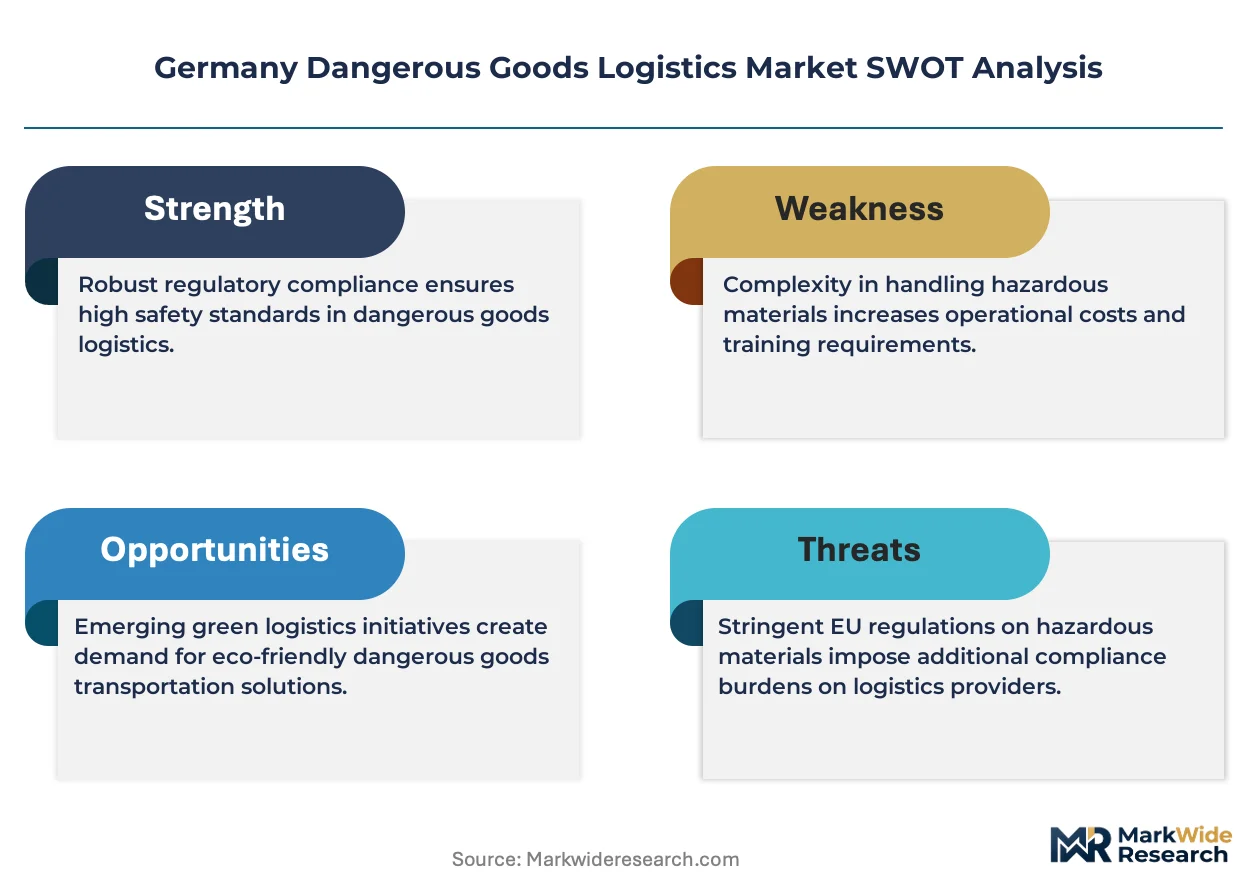
Branded specialists and integrated logistics groups split share differently across segments, with chemical transport consolidating around ADR-certified fleet operators while pharmaceutical cold-chain retains premium-tier fragmentation. Tier-one carriers maintain multi-standard certification portfolios spanning ADR, IATA, IMDG, and RID protocols. Strategic archetypes include rail-anchored intermodal specialists, pharmaceutical cold-chain pure-plays, and project cargo handlers for oversized hazardous equipment. Dominant competitive moves center on sensor infrastructure investment for automated compliance verification and consolidation of subcontractor networks to satisfy Supply Chain Due Diligence Act liability requirements.
Among Germany-based integrated logistics groups, DHL and DB Schenker occupy anchor positions across distinct capability vectors. DHL represents the pharmaceutical cold-chain archetype with certified infrastructure for temperature-sensitive dangerous goods. DB Schenker exemplifies rail-anchored intermodal specialization through RID-compliant bulk chemical movements. Kuehne + Nagel sits within the global forwarder tier, leveraging Hamburg port integration for lithium hydroxide import logistics. These three structures illustrate how certification depth and modal infrastructure determine competitive positioning in Germany's tightening regulatory environment.
| Leading Market Players |
|---|
| DHL |
| DB Schenker |
| Kuehne + Nagel |
| Hellmann Worldwide Logistics |
| UPS |
| DACHSER |
| Gebrüder Weiss |
| Rhenus Logistics |
| Panalpina |
| Others |
Pricing and Supply Chain Analysis
Just-in-sequence procurement from automotive battery plants in Lower Saxony and Baden-Württemberg compresses delivery windows to four-hour tolerances, forcing logistics providers to absorb buffer inventory costs and premium fleet positioning that reshape contract pricing structures across the Rhine corridor.
Pricing Analysis
Volume concentration in flammable liquids transport generates thin margins, while radioactive materials and cryogenic pharmaceutical shipments sustain premium multiples. Three-tier pricing structure across certified cold-chain, standard ADR-compliant, and economy bulk chemical levels separates carriers by KBA certification depth and sensor infrastructure investment. Cost compression in standard chemical haulage intensifies because driver certification backlogs constrain fleet expansion regardless of vehicle availability. Small and mid-sized Rhine-Neckar logistics providers exhibit highest price sensitivity, whereas nuclear medicine shippers prioritize reliability over freight rates.
Supply Chain Analysis
Freight economics for battery-grade lithium hydroxide hinge on Hamburg port throughput and Rotterdam transshipment efficiency, with Chile and Australia anchoring upstream extraction. Cathode material processing draws from German chemical refining clusters around Cologne and Ludwigshafen, while specialized UN-certified container production rests on limited European molding capacity. Single-source vulnerability concentrates in RID-compliant rolling stock controlled by DB Cargo, constraining multimodal optionality. Distribution runs through bonded warehousing zones in Hamburg and Wolfsburg, with last-mile road haulage handling just-in-sequence plant deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into upstream packaging production and downstream customs brokerage is accelerating as Supply Chain Due Diligence Act liability compresses onto logistics providers managing subcontractor networks.
For Market Incumbents: Lock in ADR-certified driver pipelines through captive training academy investments before KBA backlogs worsen. Deepen backward integration into UN-certified container production to capture packaging premiums that currently leak to specialized manufacturers. Consolidate subcontractor networks under direct certification to satisfy custody documentation requirements. For New Entrants and Emerging Players: The mid-market price gap between DHL pharmaceutical cold-chain premiums and economy chemical haulage rates offers entry space for temperature-controlled battery transport specialists. Target cathode material processors supplying CATL and Volkswagen Group facilities with 4-hour delivery guarantees. Enter through sensor-equipped fleet leasing partnerships to bypass capital-intensive rolling stock ownership. For Investors and Strategic Acquirers: Re-rating potential sits with rail-anchored intermodal specialists given EU Green Deal carbon accounting pressure on road haulage. Long-term viability favors carriers with multi-standard certification portfolios spanning ADR, IATA, IMDG, and RID protocols. Monitor KBA driver qualification backlog resolution as inflection indicator for fleet expansion capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Infrastructure Investment | Automated hazardous goods screening using computer vision creates first-mover advantage before EU AI Act deadlines. |
| Backward Integration into Packaging | In-house UN-certified container production captures 3-4x freight packaging premiums for Class 1 and Class 7 materials. |
| Multi-Standard Certification Expansion | Portfolio spanning ADR, IATA, IMDG, and RID protocols secures integrated chemical and battery logistics contracts. |
| Subcontractor Network Consolidation | Direct certification of downstream partners satisfies Supply Chain Due Diligence Act custody documentation requirements. |
| Bonded Warehousing Capacity Addition | Hamburg port zone expansion captures lithium hydroxide import demand from Chile and Australia. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet operations directors, chemical procurement leads at Rhine-Ruhr refineries, KBA certification officers, pharmaceutical supply chain managers, and Hamburg port terminal operators. Secondary sources incorporated BAG freight statistics, ECHA REACH substance databases, EU customs clearance records, and Federal Office for Goods Transport compliance monitoring reports. Bottom-up carrier capacity modeling and top-down chemical production flow analysis were triangulated against segment revenue estimates.
Data-stream reconciliation across modal volume splits, certification tier distributions, and service-type revenue mixes informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompass hazard class, service intensity tier, delivery mode, and compliance standard. CAGRs were derived from trend extrapolation of battery electrification-driven lithium transport demand, REACH substance tracking mandates, and modal shift incentives under EU Green Deal carbon accounting requirements.
Inputs from BAG and ECHA databases were available through the study window; gaps in real-time fleet telemetry and subcontractor certification audit trails introduce uncertainty bands around capacity expansion assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
US Event Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Asia-Pacific Logistics Automation Market