
 Jordan Freight and Logistics Market | 2026-2036
Jordan Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Jordan Freight and Logistics Market Foresight
Last-mile delivery networks is reconfiguring across Jordan's urban corridors. Aramex leverages its express courier infrastructure to dominate direct-to-consumer channels in Amman. DHL Group sustains pharmaceutical cold-chain certifications that anchor premium logistics contracts. Kawar Group competes through specialized warehousing near the Aqaba port zone.
Jordan freight and logistics encompasses the integrated planning, execution, and control of goods movement via road, sea, air, and rail modes, typically operating across temperature bands from ambient to frozen with tracking systems maintaining real-time visibility. The sector serves industrial supply chains, retail replenishment, and pharmaceutical distribution with time-definite delivery commitments. Road freight leads volume throughput due to Jordan's extensive highway links with Saudi Arabia and Iraq, while air freight captures the fastest expansion as perishable and pharmaceutical exports require speed. Warehousing services command concentrated margin pools where bonded facilities and temperature-controlled storage create differentiation against commoditized transportation.
Jordan's Ministry of Transport and the Aqaba Special Economic Zone Authority coordinate infrastructure investment and operator licensing, while customs procedures align with the WCO SAFE Framework to secure trade lanes. The national regulator enforces truck weight limits and driver hour rules that shape fleet composition and route economics. Stakeholders must monitor how customs digitization timelines affect brokerage service margins and whether cold-chain certification requirements expand beyond pharmaceuticals into fresh food exports.
Market Dynamics
Customs digitization under the WCO SAFE Framework is compressing clearance timelines and redistributing margin pools from traditional brokerage toward technology-enabled operators across Jordan's logistics corridors.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Temperature-controlled warehousing investments are accelerating across Amman and Aqaba to serve biologics distribution. The country's national pharmaceutical regulator is tightening storage certification requirements that favor certified 3PL operators.
- Aqaba Special Economic Zone transshipment:Red Sea routing shifts are elevating container volumes through Jordan's primary port. Bonded warehouse capacity additions near the port zone capture re-export traffic between Asia and Levantine markets.
- Digital customs platforms:Single-window clearance systems are reducing documentary processing from days to hours. The WCO SAFE Framework implementation is standardizing advance cargo information protocols across land and sea borders.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations directly compress road freight margins on the Saudi Arabia and Iraq corridors. Fleet operators lack fuel surcharge mechanisms with smaller shippers.
- Port capacity concentration:Aqaba handles over 90 percent of maritime cargo, creating single-point vulnerability for national trade flows. Container yard congestion during peak seasons amplifies dwell cost penalties.
- Truck driver hour regulations:National transport ministry enforcement of maximum duty periods limits fleet utilization rates on long-haul routes to Gulf Cooperation Council destinations.
Strategic Opportunities
- Fresh food export cold-chain:Jordan Valley produce growers lack certified pre-cooling and refrigerated trucking to access European supermarket procurement standards. Investment in farm-gate collection centers bridges this gap.
- E-commerce fulfillment infrastructure:Direct-to-consumer parcel volumes are outpacing existing last-mile capacity in Amman and Zarqa. Micro-fulfillment centers in dense urban districts reduce delivery cost per stop.
- Rail freight revival:Phosphate and potash mining corridors offer captive bulk volumes for rehabilitated track infrastructure. Integration with Aqaba port operations would divert heavy truck movements from highway corridors.
Industry Challenges
- Cold-chain technician scarcity:Refrigeration mechanics with pharmaceutical-grade calibration expertise are concentrated in Amman, limiting warehouse expansion to secondary cities.
- Legacy customs broker adaptation:Documentary specialists face margin erosion as automated classification and duty calculation platforms displace manual entry services.
- Warehouse management system integration:Temperature monitoring IoT sensors require real-time data pipelines that many existing facilities lack, forcing capital-intensive retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jordan Freight and Logistics Market |
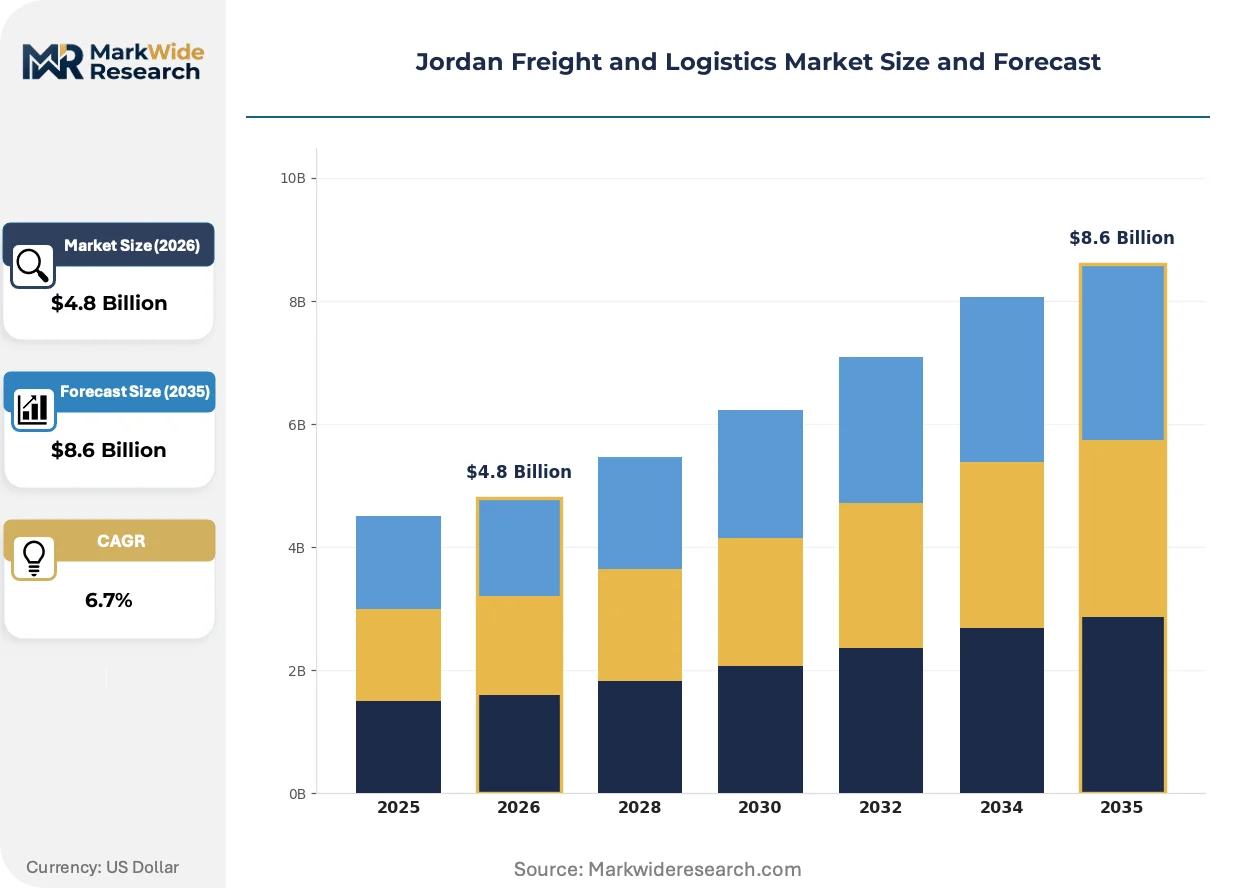
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage Product Type: Road Freight, Sea Freight, Air Freight, Rail Freight Customer Type: Retailers, Manufacturers, E-commerce, Pharmaceutical Delivery Mode: Direct Delivery, Cross-Docking, Last-Mile Delivery, Consolidated Shipment |
| Companies Covered | A.P. Moller - Maersk, Golden Ways Logistics, Aramex, Kawar Group, Jordan Post, Naouri Group, GAC Group, La Vega Logistics, DHL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jordan Freight and Logistics Market Shifts & Advancements
Telematics convergence with customs platforms is reshaping how cargo visibility translates into clearance priority and insurance pricing across Jordan's multimodal networks.
Blockchain-enabled trade documentation is hybridizing paperless origin certification with smart contract execution. Pharmaceutical exporters and their logistics providers are piloting immutable chain-of-custody records for temperature-sensitive shipments. This technology is compressing dispute resolution timelines and reducing cargo insurance premiums for certified lanes.
The WCO SAFE Framework is mandating advance cargo information submission 24 hours pre-departure for all maritime imports. Jordan Customs has aligned its National Single Window with these protocols, forcing freight forwarders to restructure data collection workflows. Smaller brokerage operations are consolidating or exiting as compliance costs rise.
Shippers are unbundling transportation from warehousing contracts to optimize working capital. Retail and pharmaceutical buyers now tender storage and line-haul separately, pressuring integrated operators to demonstrate discrete cost advantages in each service layer. This pattern is most visible among Amman-based distributors serving the Iraqi market reconstruction.
Jordan Freight and Logistics Market Segmentation
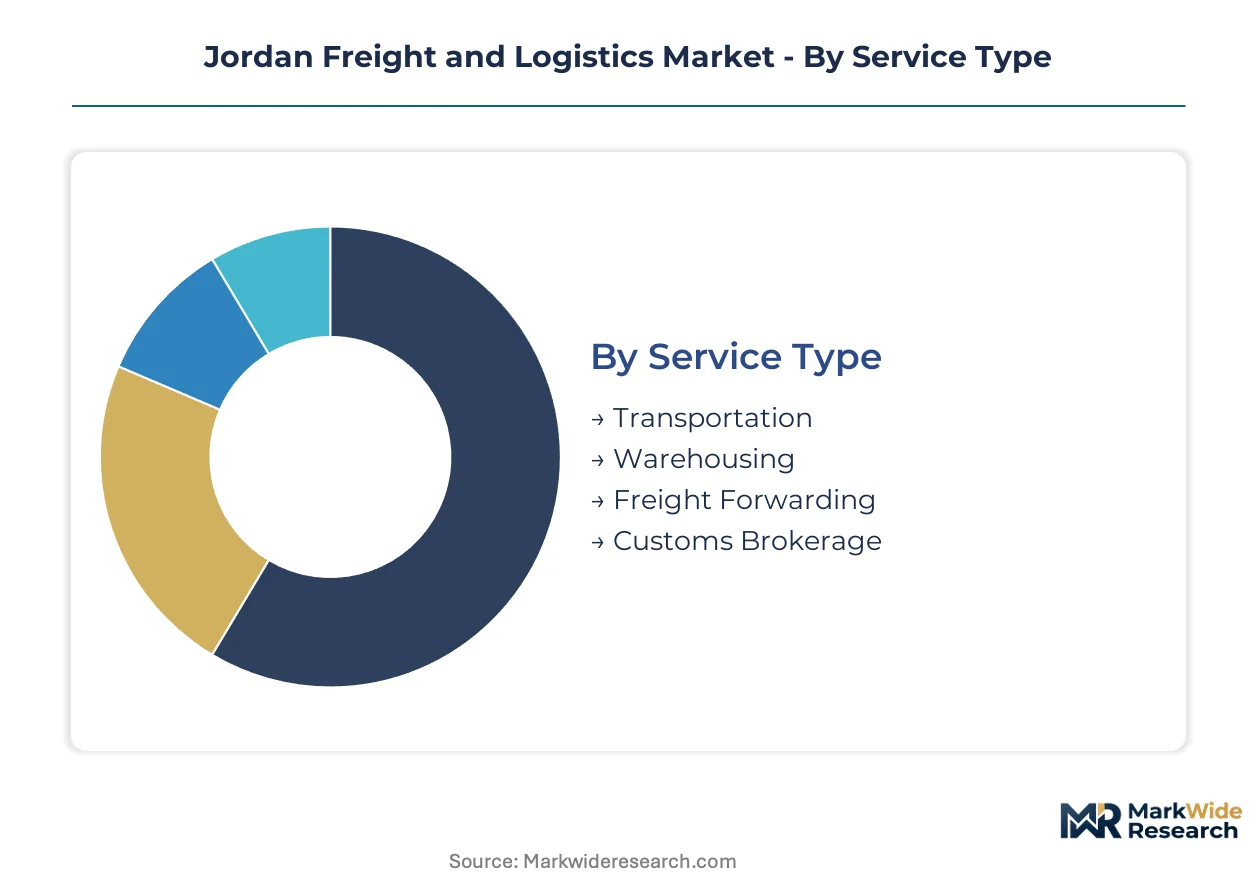
Service differentiation in Jordan's freight and logistics sector determines contract duration, margin stability, and capital intensity requirements. Segment boundaries blur as integrated operators bundle transportation with warehousing to capture sticky pharmaceutical and retail relationships.
Service Type:
Transportation cycles inventory fastest, while customs brokerage locks in multi-year retainer structures with the slowest revenue turnover.
- Transportation:Road, air, and sea line-haul operations move cargo across temperature bands from ambient to frozen. Fleet utilization rates on the Saudi Arabia and Iraq corridors shape profitability, with fuel surcharge pass-throughs weaker among smaller shippers.
- Warehousing:Bonded facilities and temperature-controlled storage near Aqaba port command premium rates for re-export traffic. Cold-chain certification requirements from Jordan's national pharmaceutical regulator favor certified 3PL operators over commodity players.
- Freight Forwarding:Document preparation, carrier booking, and cargo insurance placement services coordinate multimodal movements.
- Customs Brokerage:Classification, duty calculation, and clearance facilitation face margin compression as the WCO SAFE Framework digitizes documentary processing.
Transportation dominates installed base. Warehousing is where expansion concentrates.
Product Type:
Cost tiers separate heavy-asset modes from asset-light coordination, with rail freight requiring the steepest infrastructure commitment.
- Road Freight:Highway networks link Amman to Saudi Arabia and Iraq with flexible scheduling for retail replenishment. Diesel price volatility directly compresses margins where fuel surcharge mechanisms lack contractual enforceability.
- Sea Freight:Container movements through Aqaba port handle over 90 percent of Jordan's maritime cargo volume. Dwell cost penalties during peak seasons amplify operational rigidity for shippers lacking bonded warehouse access.
- Air Freight:Perishable and pharmaceutical exports from Queen Alia International Airport require speed-definite delivery commitments. Temperature-controlled cargo terminals serve biologics distributors with cold-chain integrity guarantees.
- Rail Freight:Phosphate and potash mining corridors offer captive bulk volumes for rehabilitated track infrastructure. Integration with Aqaba port operations would divert heavy truck movements from highway corridors.
Sea Freight dominates installed base. Air Freight is expanding most quickly.
Customer Type:
Application urgency varies sharply, with pharmaceutical shipments demanding continuous temperature monitoring versus retail's tolerance for consolidated delivery windows.
- Pharmaceutical:Biologics distribution requires GDP-compliant warehousing and validated cold-chain transport from Amman to Aqaba. National regulator certification mandates are tightening storage requirements that favor specialized 3PL operators.
- E-commerce:Direct-to-consumer parcel volumes are outpacing last-mile capacity in Amman and Zarqa urban districts. Micro-fulfillment centers in dense neighborhoods reduce delivery cost per stop.
- Retailers:Supermarket and department store replenishment programs prioritize predictable lead times over speed.
- Manufacturers:Industrial supply chains coordinate inbound raw materials and outbound finished goods movements.
Retailers dominate installed base. E-commerce is where expansion concentrates.
Delivery Mode:
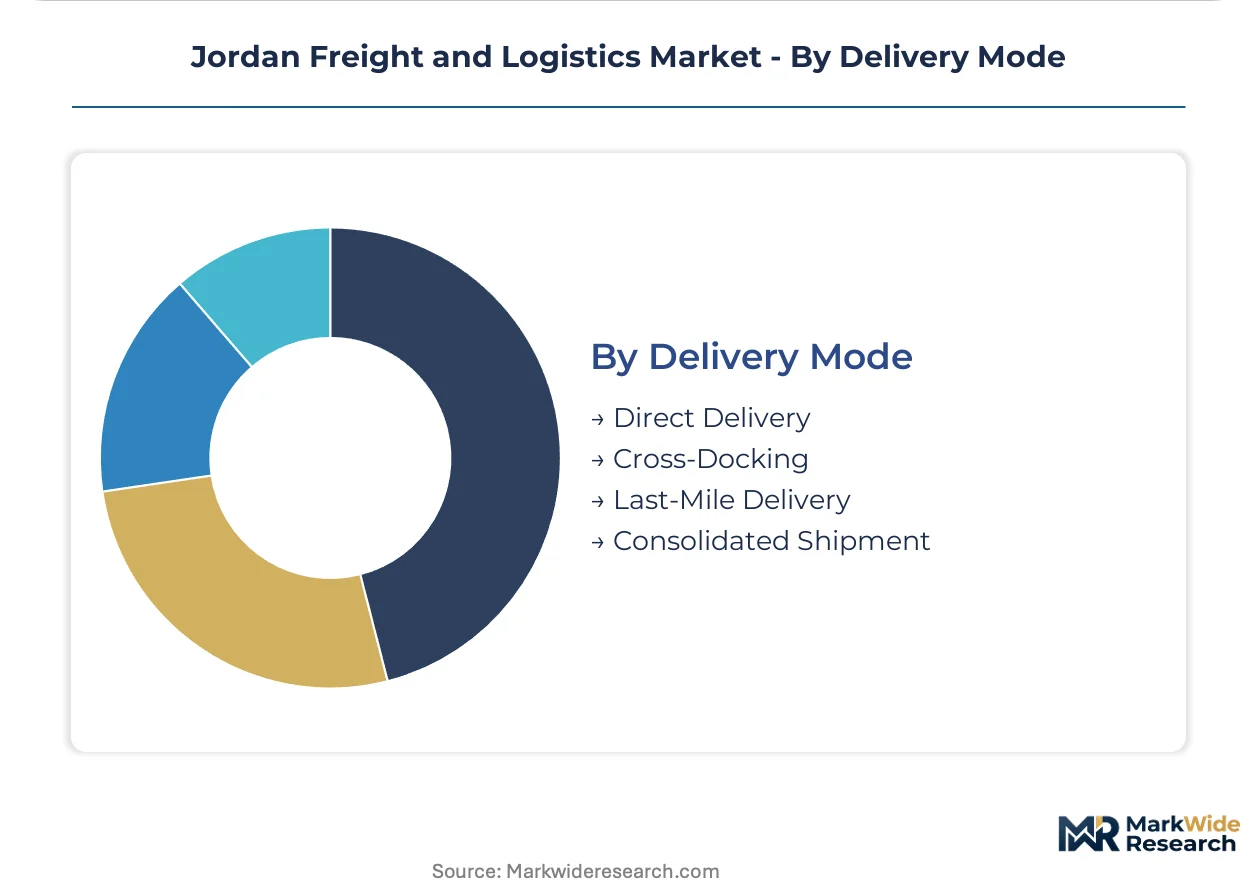
Volume concentration favors consolidated shipment economics, while last-mile delivery absorbs disproportionate cost per unit handled.
- Last-Mile Delivery:Final-leg parcel distribution in Amman's dense urban corridors requires route optimization to control cost per stop. Aramex leverages express courier infrastructure to dominate direct-to-consumer channels.
- Cross-Docking:Inventory bypasses storage through rapid freight transfer from inbound to outbound vehicles. Aqaba port zone facilities serve re-export traffic between Asia and Levantine markets with minimal dwell time.
- Direct Delivery:Full-truckload movements from shipper to consignee eliminate intermediate handling.
- Consolidated Shipment:Less-than-truckload cargo aggregation spreads fixed costs across multiple shippers.
Consolidated Shipment dominates installed base. Last-Mile Delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Aqaba Port Complex anchors Jordan's logistics function across the Red Sea corridor, handling maritime transshipment volumes that connect Asian manufacturing bases with Levantine and Iraqi consumer markets.
Amman Governorate
Pharmaceutical distribution clusters concentrate GDP-compliant warehousing investments along the Airport Road corridor. Jordan's national pharmaceutical regulator enforces storage certification mandates that favor specialized 3PL operators over commodity warehouse providers. Cold-chain facilities near Queen Alia International Airport serve biologics exporters with validated temperature monitoring infrastructure.
Aqaba Special Economic Zone
Container yard expansions capture re-export traffic between Asia and regional markets as Red Sea routing shifts elevate throughput. The Aqaba Special Economic Zone Authority coordinates bonded warehouse licensing and operator permits that shape margin pools for logistics service providers. Port-adjacent free zone facilities minimize dwell cost penalties during peak seasonal surges.
Zarqa Governorate
Industrial zone manufacturers generate consolidated shipment demand for raw material inbound and finished goods outbound movements. The Ministry of Transport enforces truck weight limits and driver hour regulations that constrain fleet utilization on corridors to Saudi Arabia. Dry port facilities near the city center reduce highway congestion for Amman-bound container traffic.
Irbid Governorate
Agricultural produce from the Jordan Valley requires farm-gate collection centers with pre-cooling capacity to access European supermarket procurement standards. Customs modernization under the WCO SAFE Framework is digitizing clearance workflows at the Sheikh Hussein border crossing with Israel. Cold-chain technician scarcity limits warehouse expansion beyond ambient storage capabilities.
Madaba and Southern Highlands
Phosphate and potash mining corridors offer captive bulk volumes for rehabilitated rail infrastructure that would divert heavy truck movements from highway corridors. The Ministry of Transport evaluates track integration with Aqaba port operations to reduce road freight congestion. Mining logistics contracts sustain dedicated fleet operators with long-term volume commitments.
Jordan Freight and Logistics Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers: integrated multinational operators with pharmaceutical cold-chain certifications, regional specialists with bonded warehouse assets near Aqaba, and domestic courier networks with dense last-mile coverage in urban corridors. Strategic archetypes include temperature-controlled 3PLs serving biologics distribution, port-centric logistics providers capturing re-export traffic, and express parcel operators optimizing direct-to-consumer delivery economics. Competitive moves concentrate on customs technology licensing partnerships and micro-fulfillment center deployments in dense urban districts.
Among integrated multinational operators, DHL Group and A.P. Moller - Maersk represent the cold-chain and maritime infrastructure archetypes respectively. Regional specialists anchored near the Aqaba port zone include Kawar Group, which occupies a position within the bonded warehousing tier. Domestic express courier capacity concentrates with Aramex, exemplifying last-mile density strategies in Amman and Zarqa urban corridors.
| Leading Market Players |
|---|
| A.P. Moller - Maersk |
| Golden Ways Logistics |
| Aramex |
| Kawar Group |
| Jordan Post |
| Naouri Group |
| GAC Group |
| La Vega Logistics |
| DHL Group |
| Others |
Supply & Pricing Matrix
The Saudi Arabia-Iraq highway corridor channels diesel price volatility directly into road freight margins, concentrating pricing power among fleet operators with fuel surcharge mechanisms while squeezing smaller carriers into commodity rate competition downstream.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical GDP-certified operators from standard freight providers, with cold-chain integrity guarantees commanding substantial premiums over ambient transport rates. Price differentiation rests on certification grade and geographic delivery cost, with Aqaba port-adjacent bonded warehouses extracting premium storage fees during peak congestion periods. Pricing pressure stems from customs digitization compressing traditional brokerage margins. E-commerce parcel shippers exhibit highest price sensitivity, while biologics distributors prioritize cold-chain reliability over rate minimization.
Supply Chain Analysis
Supplier-financing facilities from bonded warehouse operators extend payment terms for re-export traders managing inventory through Aqaba's free zone. Geographic supply concentration draws from China, India, and Turkey for containerized manufacturing inputs feeding Jordan's retail and pharmaceutical sectors. Raw material dependencies center on refrigerated transport equipment, pharmaceutical packaging materials, and diesel fuel. Single-source vulnerability runs through Aqaba port handling over ninety percent of maritime cargo. Distribution runs through hub-and-spoke networks radiating from Amman to Saudi Arabia and Iraq corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Jordan's freight and logistics sector is recovering from cyclical compression as Red Sea routing shifts elevate transshipment volumes through Aqaba, restoring utilization rates for port-centric operators.
For Market Incumbents: Harden cold-chain certification moats against emerging regional 3PL competitors by accelerating GDP-compliant warehouse expansion beyond Amman into Aqaba and Zarqa. Deepen backward integration into temperature-controlled fleet ownership to capture margin pools currently leaked to subcontracted trucking operators. Anchor long-term contracts with pharmaceutical distributors before regulatory storage mandates tighten further. For New Entrants and Emerging Players: Build out micro-fulfillment infrastructure in dense Amman urban districts where last-mile delivery costs per stop remain elevated and Aramex coverage gaps persist. Target fresh food export cold-chain services for Jordan Valley produce growers lacking certified pre-cooling capacity. Pursue licensing partnerships with customs technology providers to bypass legacy brokerage entry barriers. For Investors and Strategic Acquirers: WCO SAFE Framework implementation reshapes the acquisition landscape by forcing margin compression on documentary-heavy brokerage operations and favoring technology-enabled operators with single-window integration capabilities. Long-term viability favors asset-light platform players with customs digitization capabilities over heavy-asset trucking fleets exposed to diesel volatility. Monitor cold-chain technician training pipeline expansion as inflection indicator for warehouse capacity scalability beyond Amman.| Strategic Initiative | Industry Significance |
|---|---|
| Customs Technology Licensing Partnership | Single-window integration capabilities displace traditional brokerage margins under WCO SAFE Framework mandates. |
| Cold-Chain Warehouse Expansion | GDP-compliant facilities near Queen Alia International Airport capture biologics distribution growth. |
| Micro-Fulfillment Center Deployment | Urban density in Amman and Zarqa reduces last-mile delivery cost per stop for e-commerce volumes. |
| Rail Freight Infrastructure Rehabilitation | Phosphate corridor integration with Aqaba port operations diverts heavy truck movements from highways. |
| Farm-Gate Collection Center Investment | Pre-cooling capacity bridges Jordan Valley produce growers to European supermarket procurement standards. |
Research Methodology
Desk research of customs modernization protocols, port authority throughput disclosures, and pharmaceutical regulatory filings preceded structured interviews with fleet operations managers, bonded warehouse operators, customs brokerage principals, and pharmaceutical supply chain directors. Secondary validation drew from Aqaba Special Economic Zone Authority licensing records, Ministry of Transport enforcement bulletins, and WCO SAFE Framework implementation timelines. Bottom-up service provider capacity assessments triangulated against top-down trade flow estimates from maritime cargo manifests and cross-border trucking permits.
Assumptions around customs digitization pace, fuel price banding, and cold-chain certification adoption curves were held fixed while varying transshipment volume scenarios and pharmaceutical export growth rates across the projection horizon. Segmentation modeling incorporated service type, product mode, customer application, and delivery mode dimensions. CAGRs were derived from logistic curve fitting to historical throughput data and elasticity-adjusted demand projections. Industry-specific inputs included bonded warehouse utilization rates and pharmaceutical GDP certification penetration trends.
Stress conditions across diesel price volatility, Aqaba port congestion severity, and customs platform rollout delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and infrastructure investment commitments. Macroeconomic contraction in Saudi Arabia or Iraq, accelerated WCO SAFE compliance deadlines, or breakthrough rail freight rehabilitation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Canada Freight and Logistics Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
Less-Than-Truckload Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Thailand Cold Chain Logistics Market