
 Global Air Cargo and Freight Logistics Market | 2026-2036
Global Air Cargo and Freight Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Cargo and Freight Logistics Market Analysis
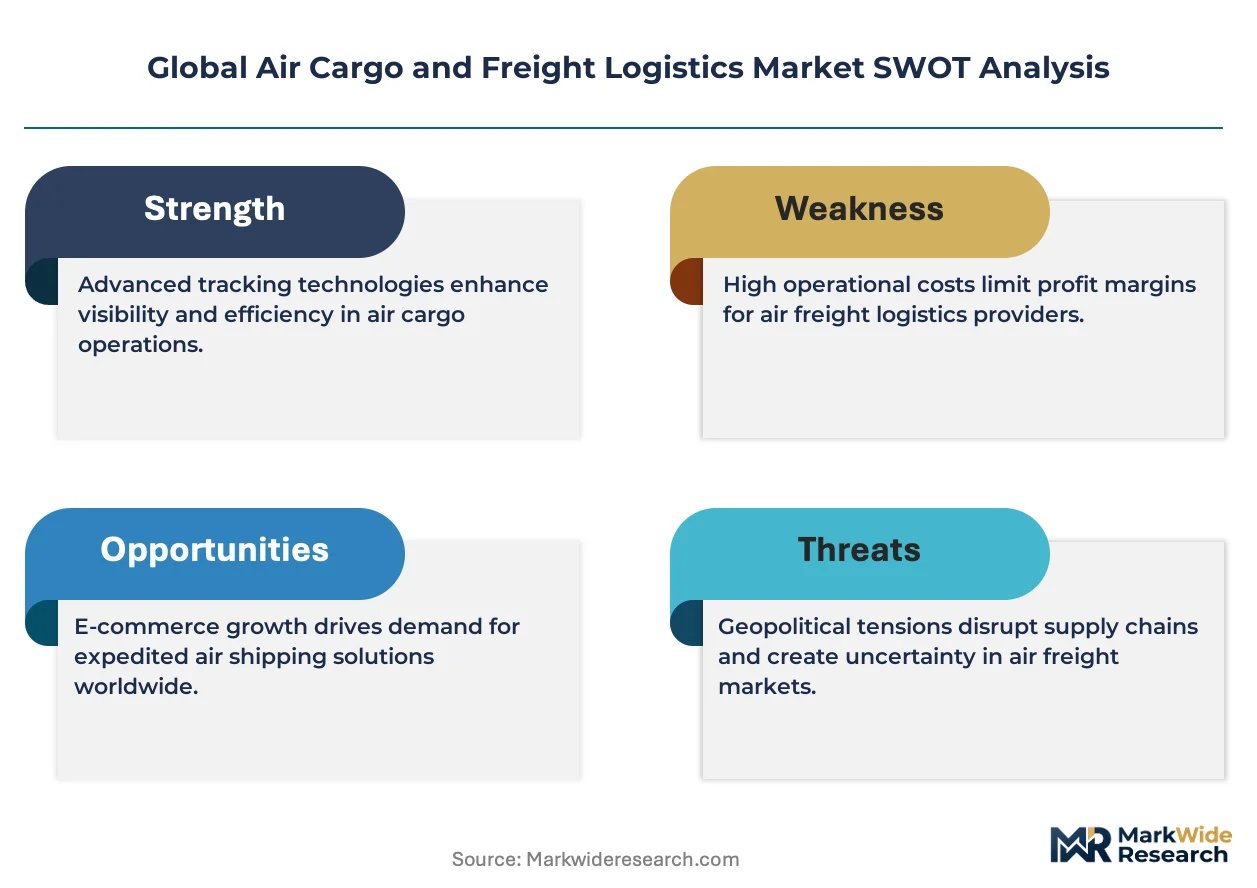
Buyer concentration in the pharmaceutical sector is broadening as biologics manufacturers fragment procurement across specialized cold-chain forwarders rather than consolidating with legacy carriers. DHL Global Forwarding leverages its GDP-certified pharma network across Europe and Asia. FedEx Corporation sustains dedicated temperature-controlled infrastructure at its Memphis superhub. Kuehne + Nagel anchors pharmaceutical air freight volumes through its KN PharmaChain service portfolio.
Air cargo and freight logistics encompasses the planning, execution, and management of goods transport via aircraft, incorporating unit load devices rated to 6,800 kg, temperature-controlled containers maintaining 2-8°C for biologics, and real-time telemetry for in-transit visibility. Its primary commercial purpose is bridging time-critical supply chains where ocean freight latency exceeds inventory carrying costs or product shelf-life constraints. Freight forwarding commands the largest value pool as shippers outsource route optimization and customs brokerage. Express delivery captures the fastest expansion as e-commerce platforms demand next-day international fulfillment. Cargo management software sits at the margin frontier as carriers digitize yield management and dynamic pricing.
The FAA goverges U.S. air carrier certification and crew rest rules that constrain freighter utilization rates. EASA implements the EU Green Deal aviation benchmarks that mandate sustainable aviation fuel blending thresholds for intra-European operations. ICAO coordinates global emissions standards through CORSIA compliance timelines. Stakeholders must monitor regulatory divergence between carbon border adjustments and open-skies agreements as these frameworks determine network economics and hub selection.
Market Dynamics
ICAO's CORSIA compliance deadlines are compressing carrier fleet replacement cycles as sustainable aviation fuel infrastructure remains geographically sparse. This regulatory pressure is forcing route network rationalization and hub consolidation across major trade lanes.
Growth Catalysts
- Pharmaceutical cold chain expansion:Biologics manufacturers in Switzerland and Singapore are mandating GDP-certified lanes for temperature-sensitive therapies. This creates dedicated demand for 2-8°C containerized freight.
- E-commerce fulfillment velocity:Cross-border express volumes from China to Europe and North America are requiring next-day delivery infrastructure. Air freight captures time-sensitive consumer electronics and fashion inventory.
- Sustainable aviation fuel mandates:The EU Green Deal aviation benchmarks are requiring SAF blending thresholds for intra-European operations. Carriers are retrofitting existing freighters rather than acquiring new assets.
Market Restraints
- Freighter conversion backlog:Narrow-body passenger-to-freighter conversion slots at conversion centers in China and Israel are booked through 2027. This constrains belly-hold capacity expansion on dense trade lanes.
- Pilot availability constraints:FAA crew rest rules and EASA flight time limitations are reducing maximum aircraft utilization rates on long-haul routes. This inflates effective operating costs per available ton-kilometer.
- Jet fuel price volatility:Kerosene derivatives represent 25-35% of direct operating costs for cargo carriers. Geopolitical supply disruptions in the Middle East transmit immediately to yield management pressure.
Strategic Opportunities
- India pharmaceutical export corridors:CDSCO-regulated vaccine and generic API manufacturers in Hyderabad and Ahmedabad are building dedicated air cargo terminals. Temperature-controlled infrastructure investment lags demand by 40%.
- Blockchain-IoT convergence:Real-time telemetry from active containers is merging with distributed ledger customs documentation. This compresses clearance times at Dubai and Singapore transshipment hubs.
- Urban air mobility last-mile:Electric vertical take-off vehicles are being certified for 50-150kg payload deliveries in Shenzhen and Los Angeles. This extends air freight reach beyond traditional airport perimeters.
Industry Challenges
- Perishables handling certification:IATA CEIV Fresh accreditation requires 18-24 month implementation timelines. Smaller forwarders lack capital for controlled-atmosphere infrastructure.
- Legacy TMS integration:Cargo management software from the 1990s dominates mid-tier forwarders. API connectivity to carrier yield management systems requires expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Cargo and Freight Logistics Market |
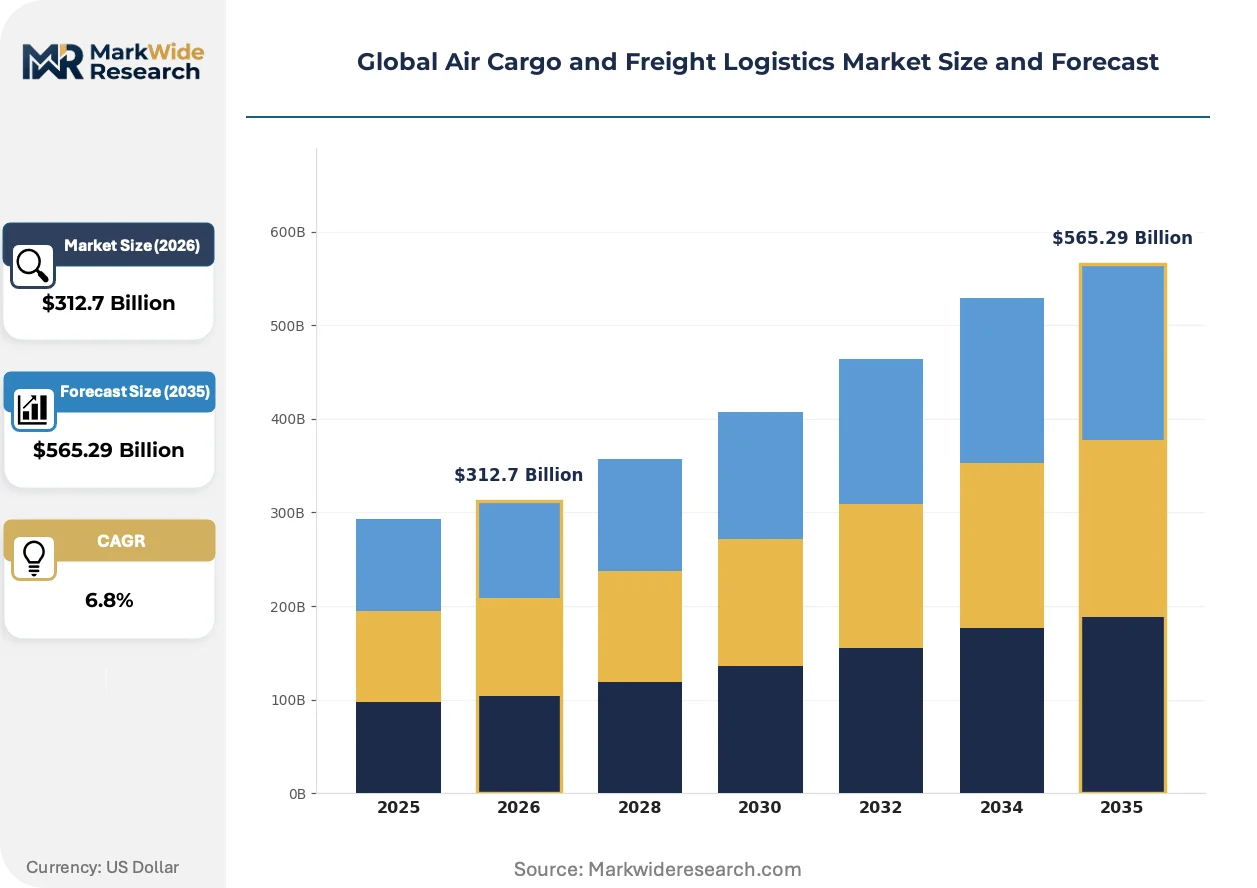
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Freight Forwarding, Charter Services, Ground Handling End User: Aerospace, Pharmaceuticals, Retail, Automotive Technology: GPS Tracking, Automation Systems, RFID Technology, Cargo Management Software Delivery Mode: Door-to-Door, Port-to-Port, Airport-to-Airport, Terminal-to-Terminal |
| Companies Covered | Kuehne + Nagel, DSV, DHL Global Forwarding, FedEx Corporation, United Parcel Service (UPS), DB Schenker, CEVA Logistics, Expeditors International, Nippon Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Cargo and Freight Logistics Market Emerging Trajectories
Digital twin technology is absorbing maintenance planning and load optimization functions across freighter operations. This convergence of simulation and real-time data is compressing turnaround times at major hubs.
Active temperature-controlled containers with integrated battery systems are absorbing pharmaceutical lane qualification requirements. Biologics manufacturers in Denmark and Massachusetts are specifying these units for international clinical trial material movements. The technology is absorbing risk from passive coolants that fail during tarmac delays.
The EU Green Deal aviation benchmarks are mandating sustainable aviation fuel blending thresholds for intra-European operations. Carriers operating Frankfurt and Amsterdam hubs are securing offtake agreements with Nordic refineries. Narrow-body freighter routes between European cities face the steepest cost adjustments.
Shippers are consolidating procurement with forwarders offering integrated customs brokerage and temperature monitoring. Pharmaceutical manufacturers in Basel and Boston are reducing vendor counts from five to two per trade lane. This concentration is most visible in trans-Atlantic corridors where GDP compliance complexity favors integrated providers.
Global Air Cargo and Freight Logistics Market Segmentation
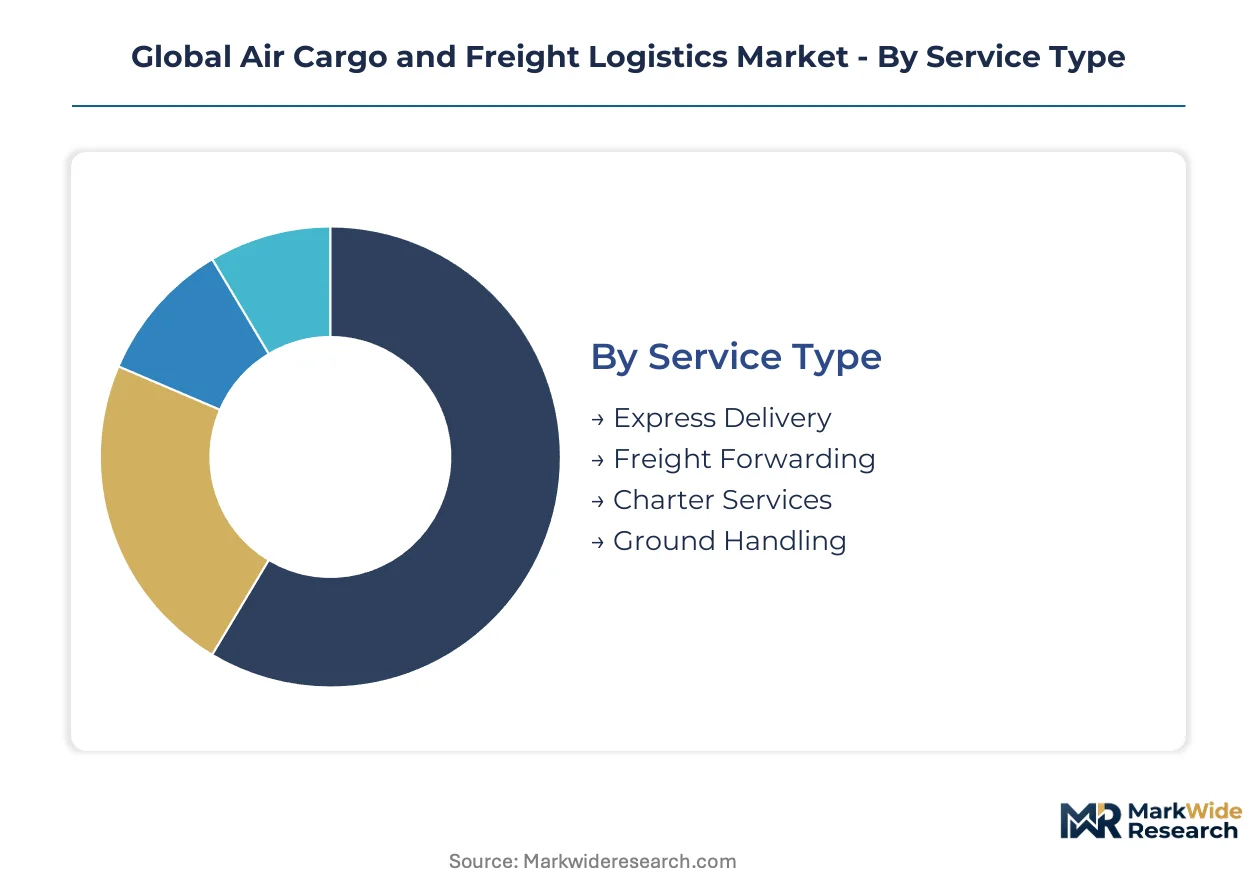
Segmentation in air cargo logistics reveals how certification requirements, infrastructure investments, and customer procurement patterns create distinct competitive arenas. Each dimension carries different margin profiles and capital intensity thresholds that reshape carrier fleet decisions and forwarder specialization strategies.
Service Type:
GDP certification for pharmaceutical lanes and IATA CEIV accreditation impose divergent compliance burdens across service categories, with express operators absorbing the strictest cold-chain validation protocols.
- Express Delivery:Time-definite services integrate last-mile ground networks with dedicated freighter capacity for next-day international fulfillment. E-commerce platforms in Shenzhen and Los Angeles are mandating sub-24-hour delivery windows for consumer electronics, forcing carriers to pre-position inventory at regional hubs.
- Freight Forwarding:Third-party logistics providers orchestrate multimodal routing, customs brokerage, and carrier selection on behalf of shippers. Pharmaceutical manufacturers in Basel and Boston are consolidating procurement with forwarders offering integrated temperature monitoring and GDP-certified lane documentation.
- Charter Services:On-demand aircraft capacity for oversized cargo, humanitarian relief, and peak season surge requirements.
- Ground Handling:Ramp operations, cargo terminal processing, and unit load device management at airport facilities.
Leading the category by volume: Freight Forwarding. Growing fastest: Express Delivery.
End User:
End-use concentration determines temperature infrastructure requirements, with biologics and perishables demanding active container systems while automotive and aerospace shipments prioritize dimensional optimization.
- Pharmaceuticals:Temperature-sensitive biologics, vaccines, and clinical trial materials require 2-8°C containerized freight with real-time telemetry. CDSCO-regulated manufacturers in Hyderabad are building dedicated air cargo terminals as temperature-controlled infrastructure investment lags demand.
- Retail:Cross-border e-commerce fulfillment drives express volume for fashion inventory and consumer electronics. Platforms in China are requiring next-day delivery infrastructure to Europe and North America, compressing traditional ocean-air hybrid timelines.
- Aerospace:Aircraft engines, avionics, and maintenance components with just-in-time delivery requirements.
- Automotive:Production parts and after-market components with line-down sensitivity.
Pharmaceuticals command premium yield per kilogram. Retail volumes are expanding most quickly.
Technology:
Technology adoption stratifies by fleet scale, with integrated carriers deploying full telemetry suites while smaller operators rely on fragmented legacy systems.
- Cargo Management Software:Yield optimization, dynamic pricing, and load planning systems digitize carrier operations. Mid-tier forwarders face expensive middleware development to connect 1990s-era TMS platforms to modern carrier APIs.
- GPS Tracking:Real-time position monitoring for shipment visibility and exception management.
- Automation Systems:Robotic sorting and automated storage/retrieval at major cargo terminals.
- RFID Technology:Contactless cargo identification and handling unit tracking.
Cargo Management Software sits at the margin frontier. GPS Tracking has achieved broadest penetration.
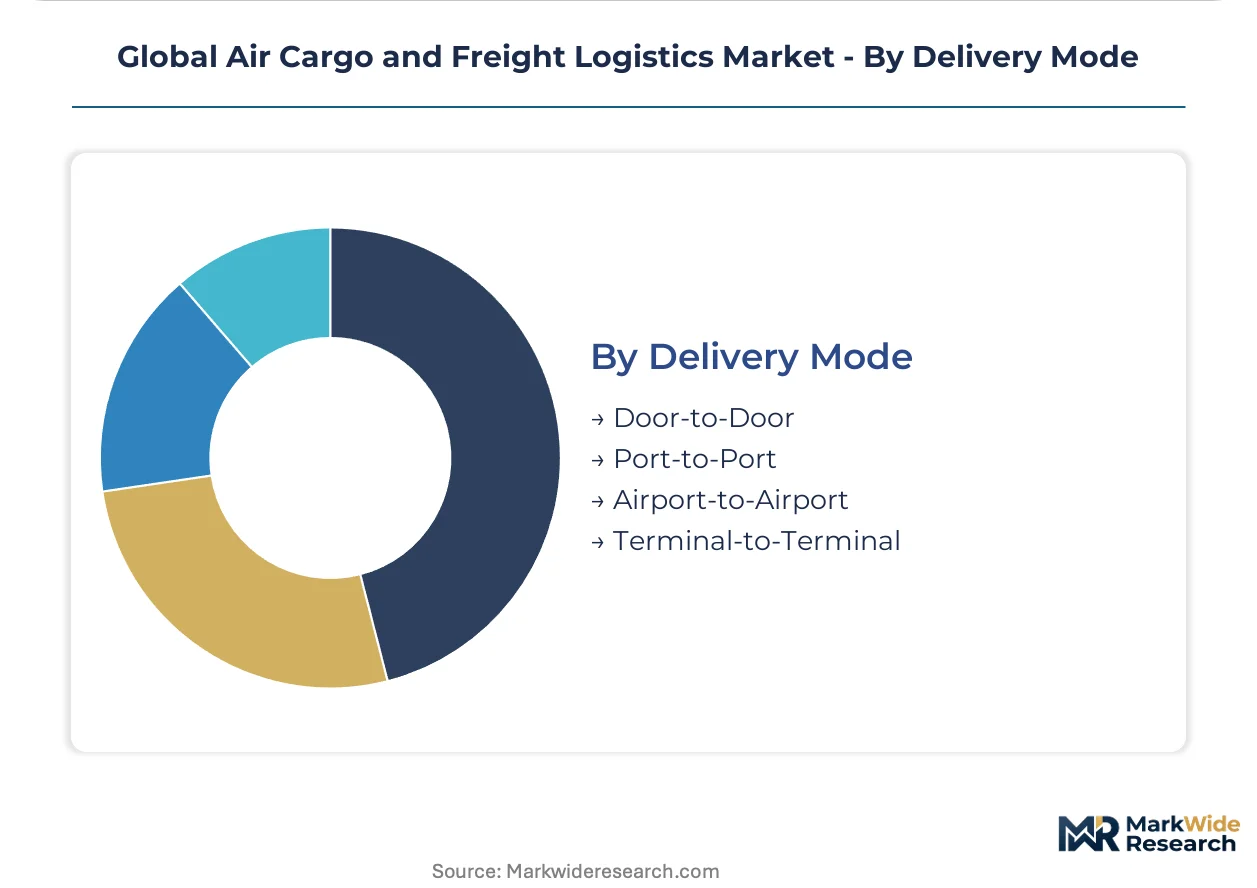
Delivery Mode:
Delivery scope determines liability boundaries and documentation complexity, with door-to-door services absorbing customs risk while airport-to-airport contracts transfer exposure at terminal boundaries.
- Door-to-Door:Integrated pickup and delivery including first-mile collection and last-mile distribution. Pharmaceutical shippers in Denmark and Massachusetts are specifying door-to-door service for clinical trial materials to eliminate handoff risks.
- Airport-to-Airport:Core air freight movement between origin and destination terminals.
- Port-to-Port:Intermodal coordination combining air and ocean segments.
- Terminal-to-Terminal:Airport cargo terminal handoff without surface transport inclusion.
Door-to-Door commands highest revenue per shipment. Airport-to-Airport retains largest volume share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical exporters in Switzerland and Singapore are fragmenting procurement across specialized cold-chain forwarders, while Chinese e-commerce platforms are compressing delivery windows to next-day service for cross-border fulfillment.
United States
FAA crew rest rules constrain freighter utilization rates on long-haul Pacific routes. The FAA governs U.S. air carrier certification standards that limit pilot duty cycles. Memphis anchors dedicated temperature-controlled infrastructure for pharmaceutical express volumes.
Germany
EASA flight time limitations reduce maximum aircraft utilization across European trunk routes. The EU Green Deal aviation benchmarks mandate sustainable aviation fuel blending thresholds for intra-European operations. Frankfurt secures SAF offtake agreements with Nordic refineries for narrow-body freighter networks.
China
E-commerce fulfillment velocity demands next-day delivery infrastructure to Europe and North America. NMPA regulates pharmaceutical export certifications for temperature-sensitive biologics. Shenzhen certifies electric vertical take-off vehicles for 50-150kg payload last-mile deliveries.
Switzerland
Biologics manufacturers mandate GDP-certified lanes for temperature-sensitive therapies. Swissmedic oversees pharmaceutical distribution compliance for international clinical trial materials. Basel consolidates procurement with forwarders offering integrated temperature monitoring and customs brokerage.
India
CDSCO-regulated vaccine and generic API manufacturers build dedicated air cargo terminals. The CDSCO governs pharmaceutical export licensing for temperature-controlled freight. Hyderabad and Ahmedabad face temperature-controlled infrastructure investment lagging demand by 40%.
Global Air Cargo and Freight Logistics Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue urban air mobility and blockchain-IoT convergence for customs clearance compression. The vendor base stratifies across integrated express carriers, specialized pharmaceutical forwarders, and digital freight platforms. Three archetypes dominate: GDP-certified cold-chain specialists, e-commerce-integrated express operators, and technology-enabled freight marketplaces. Competitive intensity centers on M&A consolidation for lane density and strategic partnerships for SAF supply security.
Within the integrated express tier, FedEx Corporation and United Parcel Service occupy positions anchored by dedicated freighter fleets and superhub infrastructure. DHL Global Forwarding exemplifies the pharmaceutical-specialist archetype through GDP-certified network coverage. Kuehne + Nagel sits within the forwarder consolidation vector, representing procurement concentration strategies among biologics manufacturers reducing vendor counts per trade lane.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| DSV |
| DHL Global Forwarding |
| FedEx Corporation |
| United Parcel Service (UPS) |
| DB Schenker |
| CEVA Logistics |
| Expeditors International |
| Nippon Express |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up freight forwarders now control lane density on trans-Atlantic and Asia-Europe corridors, compressing spot-rate volatility while extracting contract premiums through GDP-certified service bundling. This ownership concentration tightens pricing discipline as portfolio companies cross-sell temperature-controlled infrastructure across pharmaceutical and perishables verticals.
Pricing Analysis
Volume-driven belly-hold cargo on passenger wide-bodies competes with dedicated freighter capacity on yield, while express delivery commands 3-5x premiums for next-day international fulfillment. Price differentiation hinges on IATA CEIV and GDP certification tiers plus real-time telemetry integration, with uncertified forwarders facing margin compression from SAF surcharge pass-throughs. Cost compression in standard air freight intensifies as narrow-body P-to-F conversion delays constrain capacity expansion. E-commerce platforms exhibit highest price sensitivity, while biologics manufacturers accept premium pricing for lane qualification and risk transfer.
Supply Chain Analysis
Direct-to-pharma-manufacturer channels handle temperature-sensitive biologics demand through dedicated GDP-certified forwarder relationships, bypassing fragmented broker networks. Production gravity centers on China for e-commerce fulfillment infrastructure, Germany for European hub consolidation, and the United Arab Emirates for transshipment connectivity. Freighter feedstock draws from passenger aircraft retirement pools, sustainable aviation fuel from Nordic refineries, and active container systems from Swiss and German manufacturers. Single-source vulnerability concentrates in narrow-body conversion center capacity booked through 2027. Distribution runs through integrated express superhubs at Memphis and Leipzig, with forwarder-orchestrated multimodal legs completing final delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over sustainable aviation fuel offtake and temperature-controlled container fleets determines lane economics. Players securing upstream SAF supply and downstream pharma certification infrastructure capture margin that fragmented competitors forfeit.
For Market Incumbents: Acquire dedicated freighter aircraft and conversion slot positions to lock in belly-hold replacement capacity as passenger wide-body retirements accelerate. Consolidate procurement with Nordic SAF refineries to hedge EU Green Deal blending mandates. Defensive positioning requires backward integration into active container manufacturing to reduce reliance on Swiss and German equipment suppliers facing order backlogs. For New Entrants and Emerging Players: Pharmaceutical forwarders in India present channel partnership opportunities for GDP-certified lane development as CDSCO-regulated vaccine exports outstrip local cold-chain infrastructure. White-space concentration appears in Hyderabad and Ahmedabad temperature-controlled terminal development, where investment lags demand. Last-mile urban air mobility certification in Shenzhen and Los Angeles offers regulatory arbitrage for 50-150kg payload electric vertical take-off vehicle deployment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier forwarders with GDP certification gaps but dense lane coverage in trans-Atlantic and Asia-Europe corridors. Long-term viability hinges on SAF infrastructure access and pharmaceutical vertical penetration rather than generic freight forwarding scale. Watch for ICAO CORSIA compliance deadline acceleration as the inflection signal forcing fleet replacement cycle compression and carrier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Offtake Agreement | Secures fuel supply for EU Green Deal intra-European operations at Frankfurt and Amsterdam hubs. |
| GDP Certification Investment | Qualifies lanes for Swissmedic-regulated biologics exports from Basel manufacturing clusters. |
| Freighter Conversion Slot Acquisition | Locks narrow-body P-to-F capacity from China and Israel conversion centers through 2027. |
| Blockchain-IoT Platform Deployment | Compresses customs clearance at Dubai and Singapore transshipment hubs through distributed ledger integration. |
| Urban Air Mobility Certification | Extends last-mile reach beyond Shenzhen and Los Angeles airport perimeters for 50-150kg payloads. |
Methodological Framework
Document review covered IATA cargo market reports, ICAO CORSIA implementation documents, and EASA EU Green Deal aviation benchmarks, complemented by interviews with cargo yield management executives, pharmaceutical supply chain directors, freighter conversion center operators, and customs brokerage specialists. Secondary validation drew from FAA certification databases, CDSCO pharmaceutical export licensing records, and NMPA biologics distribution regulations. Bottom-up carrier capacity modeling and top-down trade flow analysis provided cross-verification across the analysis window.
Historical capacity deployment patterns were cross-referenced against executive panel input on fleet replacement intentions and SAF infrastructure investment timelines. Segmentation modeling incorporated service type, end-use vertical, technology adoption tier, and delivery mode scope throughout the forecast period. CAGRs were derived from trade lane volume projections calibrated to e-commerce platform fulfillment velocity and pharmaceutical cold-chain expansion rates. Freighter utilization assumptions incorporated FAA crew rest rule constraints and EASA flight time limitation impacts on effective aircraft availability.
Caveats apply where ICAO CORSIA timeline acceleration, SAF refinery construction delays, or narrow-body conversion center capacity constraints could materially shift the outlook. Forecasts embed assumptions regarding EU Green Deal enforcement consistency and NMPA pharmaceutical export certification reciprocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Thailand Cold Chain Logistics Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Europe Automotive Logistics Market