
 Cross-Border Road Transport Market | 2026-2036
Cross-Border Road Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Cross-Border Road Transport Market Analysis
The divergence between premium express services and commodity freight haulage is hardening as shippers split procurement between time-critical and cost-minimized lanes. Knight-Swift Transportation Holdings leverages its asset-heavy model to sustain control over dedicated cross-border fleet capacity. C.H. Robinson Worldwide competes through digital freight-matching platforms that anchor its non-asset brokerage dominance across North American border crossings. DSV A/S differentiates through integrated air-road-ocean forwarding that extends its reach into European-Asian land bridge corridors.
Cross-border road transport encompasses the movement of goods and passengers across national boundaries via highway networks, typically requiring vehicles to meet axle-load limits of 11.5–12 tonnes per axle and comply with multi-jurisdiction emissions certifications. The activity serves manufacturers and retailers by providing surface-level connectivity between production clusters and consumption markets where rail or maritime alternatives lack last-mile flexibility. Freight transport within the transport-type dimension leads volume contribution, while the less-than-truckload service category captures expanding margin pools as fragmented e-commerce shipments multiply. Trucks dominate the vehicle-type split due to their adaptability to customs-bonded container configurations, though express delivery vans are gaining share in final-mile cross-border fulfillment.
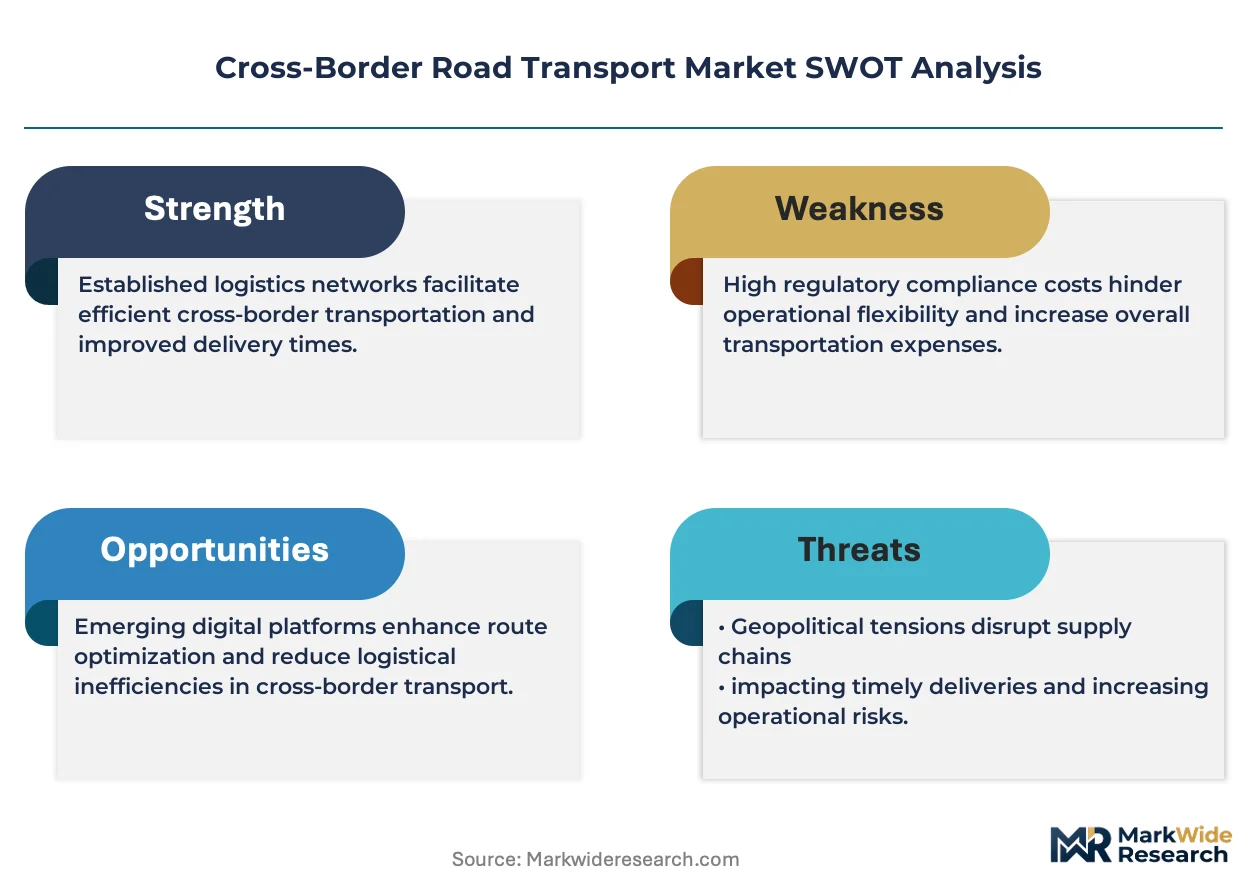
The US Department of Transportation and Mexico's Secretariat of Infrastructure, Communications and Transportation jointly shape hours-of-service mandates and cross-border carrier licensing that determine fleet utilization rates. The EU's Mobility Package and its cabotage restrictions limit how non-resident operators circulate within member states, compressing available capacity on intra-European cross-border lanes. Stakeholders must monitor whether carbon-border adjustment mechanisms will recalibrate route economics between high-emission and low-emission fleet operators.
Market Dynamics
The divergence between premium express services and commodity freight haulage is hardening as shippers split procurement between time-critical and cost-minimized lanes. E-commerce fulfillment networks are expanding their reliance on cross-border trucking corridors while regulatory bodies on both sides of the Atlantic revise operating economics through emissions mandates and driving-time restrictions.
Growth Catalysts
- EU Mobility Package cabotage reforms:Revised driving-time rules are compressing fleet utilization rates and forcing carriers to optimize asset deployment across member-state borders, creating demand for compliant capacity solutions.
- Nearshoring manufacturing investments:Production relocation along the Mexico-US corridor is intensifying cross-border freight volumes as automotive and electronics suppliers establish regional supply clusters.
- Digital freight-matching platforms:Real-time load-board technologies are reducing empty-mile ratios and improving asset turnover for non-asset brokers serving North American border crossings.
Market Restraints
- Diesel price volatility:Fuel represents the largest variable cost component for long-haul operators, with price spikes in European and North American markets compressing margin structures disproportionately for smaller fleet owners.
- Driver shortage concentration:Germany, Poland, and the United Kingdom face acute deficits in qualified commercial drivers, limiting capacity expansion even where equipment availability exists.
- Rail intermodal substitution:China-Europe land bridge rail services are capturing time-sensitive container flows that previously moved by truck, particularly on east-west corridors through Kazakhstan and Russia.
Strategic Opportunities
- Carbon-border adjustment mechanisms:Emerging EU frameworks will recalibrate route economics between high-emission and low-emission fleet operators, rewarding early adopters of alternative powertrains.
- Less-than-truckload e-commerce specialization:Fragmented parcel volumes from cross-border online retail are creating margin pools for operators with customs-bonded sorting infrastructure.
- Battery-electric corridor infrastructure:Charging networks along the Rotterdam-Milan and San Diego-Tijuana axes are enabling zero-emission fleet deployment on high-frequency lanes.
Industry Challenges
- Multi-jurisdiction emissions certification:Trucks must comply with divergent EPA, Euro VI, and emerging national standards simultaneously, extending homologation timelines and engineering costs.
- Hours-of-service harmonization failures:The US Department of Transportation and Mexico's SICT maintain incompatible rest-period mandates, complicating driver scheduling for integrated North American operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross-Border Road Transport Market |
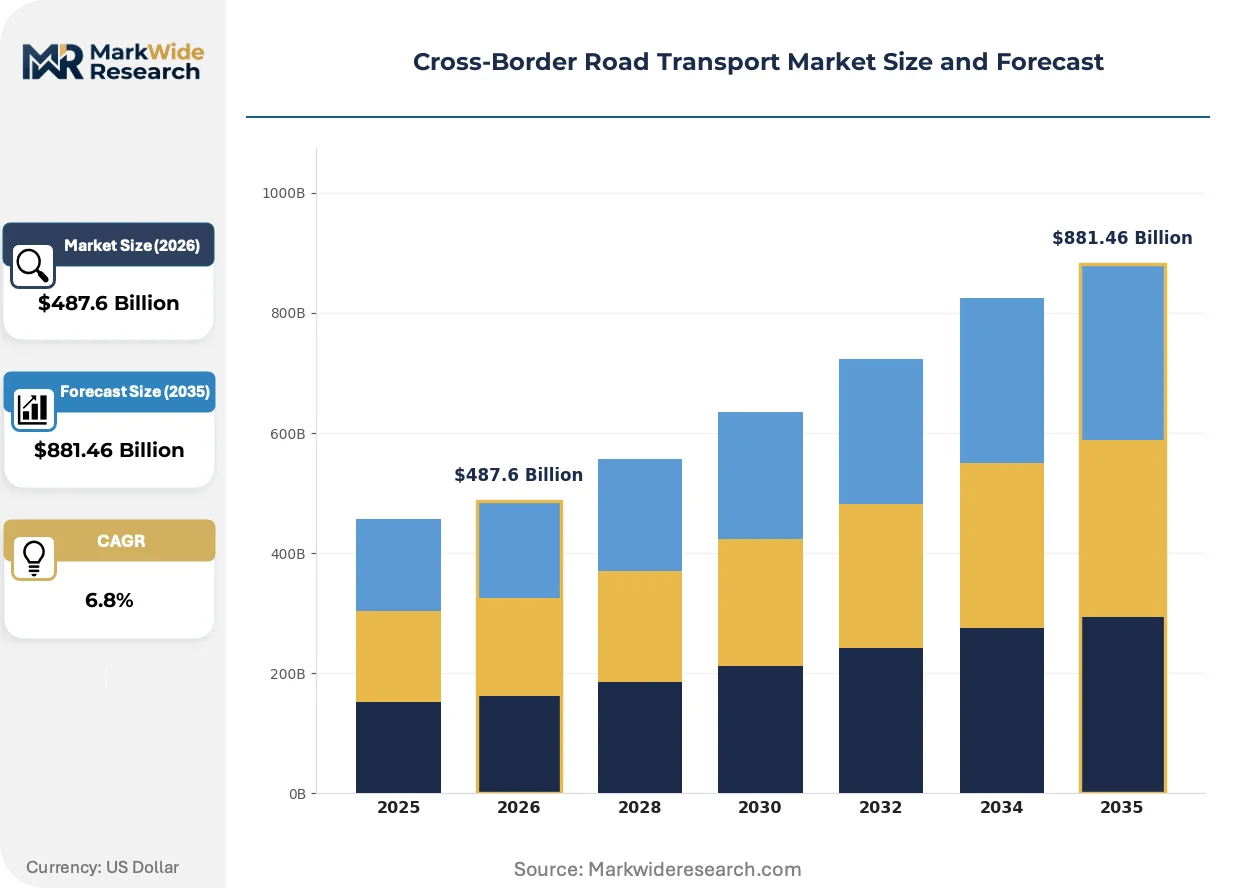
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Type: Freight, Passenger, Logistics, Delivery Vehicle Type: Trucks, Buses, Vans, Trailers Service Type: Full Truckload, Less Than Truckload, Express, Charter Market Player: Logistics Companies, Freight Forwarders, Carriers, Brokers |
| Companies Covered | Knight-Swift Transportation Holdings, Inc., FedEx Corporation, Schneider National, Inc., Landstar System, Inc., XPO, Inc., C.H. Robinson Worldwide, Inc., United Parcel Service of America, Inc. (UPS), DSV A/S, J.B. Hunt Transport, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross-Border Road Transport Market Emerging Trajectories
Telematics and predictive analytics are actively reshaping how carriers manage cross-border compliance, asset health, and route optimization. Three developments are compressing operational timelines and redefining competitive differentiation across the sector.
Autonomous truck platooning systems are expanding into high-volume freight corridors where consistent traffic patterns and established customs protocols reduce edge-case complexity. Major retailers with dedicated fleet contracts are piloting linked-vehicle convoys on the I-35 corridor between Laredo and Dallas, cutting fuel consumption through aerodynamic drafting while maintaining human oversight for border processing. This technology is expanding into lane-specific applications before broader regulatory frameworks permit fully driverless operation.
Europe's CSRD disclosure requirements are mandating granular emissions reporting across Scope 3 transport categories, compelling shippers to demand verified carbon intensity data from contracted carriers. Fleet operators must now install certified monitoring equipment and third-party audit trails to retain contract eligibility with multinational manufacturers. The regulation is accelerating investment in telematics integration among mid-sized carriers serving German and French industrial clusters.
Shippers are unbundling long-term dedicated capacity contracts in favor of spot-market exposure for non-critical freight, compressing carrier revenue predictability. This behavioral shift is most pronounced among consumer electronics distributors sourcing from Mexican maquiladoras, where weekly demand volatility outstrips contract flexibility. Digital brokerage platforms are capturing this migration by offering guaranteed capacity pools without minimum volume commitments.
Cross-Border Road Transport Market Segmentation
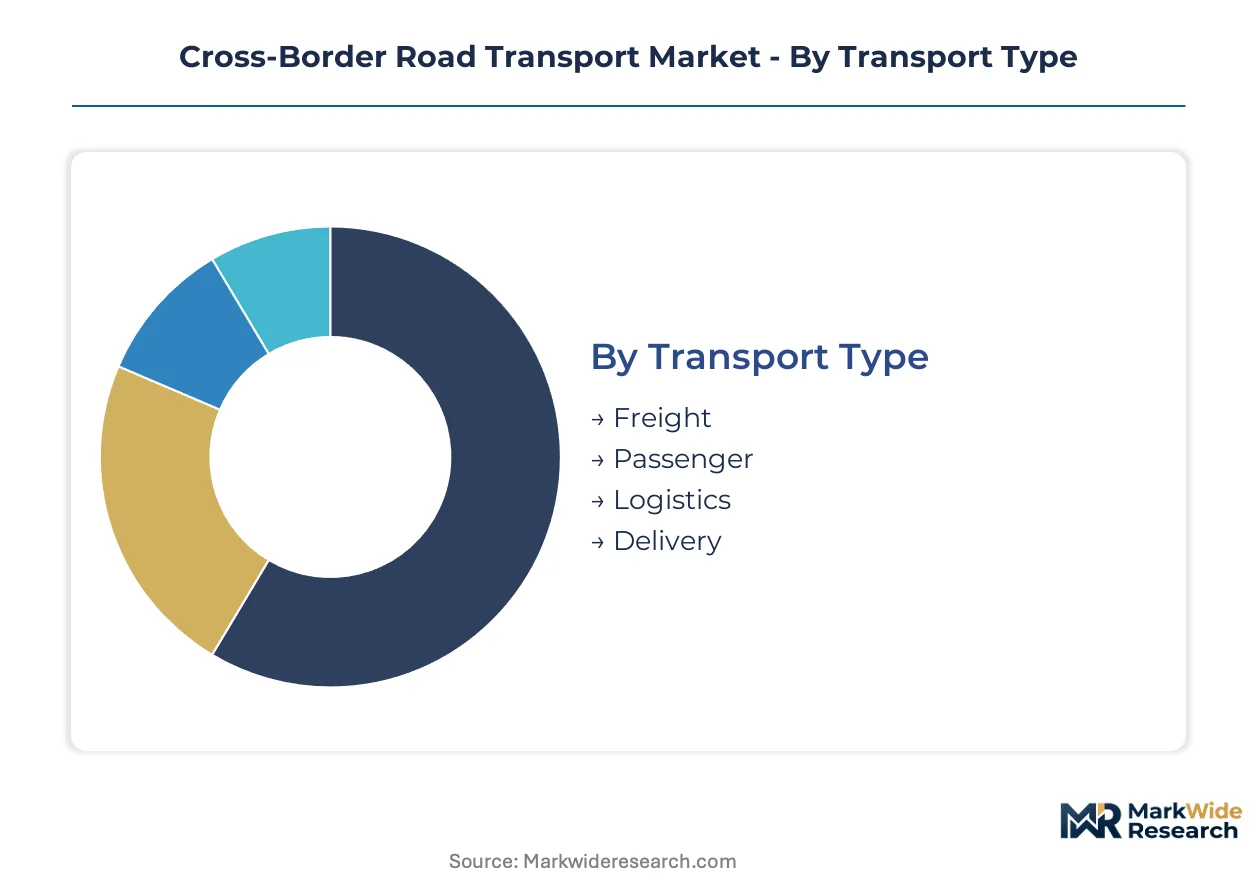
Cross-border road transport segmentation reveals how shippers split procurement between asset-heavy dedicated capacity and flexible brokerage solutions. Fleet operators and logistics providers configure service tiers around customs complexity, cargo density, and border-crossing velocity requirements.
Transport Type:
Freight transport dominates volume contribution while passenger and specialized logistics services command premium pricing tiers.
- Freight:Bulk commodity and containerized cargo movements requiring customs-bonded vehicles and multi-jurisdiction operating authority. Demand concentrates along the Mexico-US corridor where nearshoring manufacturing investments have intensified, with automotive and electronics suppliers driving lane density.
- Passenger:Scheduled intercity bus services and charter coach operations crossing Schengen or NAFTA borders under specific cabotage exemptions. Cross-border coach demand clusters on high-frequency corridors like Vienna-Bratislava and San Diego-Tijuana where rail alternatives lack frequency.
- Logistics:Integrated supply chain management combining warehousing, customs brokerage, and final-mile coordination across national boundaries.
- Delivery:Parcel and express document services operating under simplified customs procedures for low-value shipments.
Today's leader: Freight. Tomorrow's challenger: Logistics.
Vehicle Type:
Trucks anchor fleet investment due to adaptability to bonded-container configurations, though electrification is reshaping acquisition patterns.
- Trucks:Heavy-duty tractors and rigid vehicles configured for ISO container or swap-body interchangeability across EU TIR corridors and USMCA lanes. German and Polish fleets are prioritizing Euro VI-E powertrains ahead of anticipated zero-emission zone mandates in Belgium and the Netherlands.
- Vans:Light commercial vehicles serving final-mile cross-border e-commerce fulfillment from distribution hubs near border zones. Express operators are deploying battery-electric vans on Rotterdam-Antwerp and El Paso-Ciudad Juárez circuits where charging infrastructure exists.
- Buses:Intercity and tour coaches subject to passenger-specific safety and emissions certifications.
- Trailers:Semi-trailers and drawbar combinations optimized for cubic capacity within European modular limits or North American dimensional regulations.
Trucks retain volume dominance. Vans are climbing the fastest on e-commerce lane density.
Service Type:
Shippers unbundle procurement between guaranteed capacity contracts and spot-market exposure based on inventory criticality.
- Full Truckload:Dedicated vehicle allocation for single-shipper cargo from origin to destination without intermediate handling. Automotive manufacturers sourcing from Mexican maquiladoras favor FTL for just-in-sequence delivery to US assembly plants.
- Less Than Truckload:Consolidated shipments from multiple shippers requiring customs-bonded sorting facilities at border hubs. Fragmented e-commerce parcel volumes are expanding margin pools for operators with bonded infrastructure in Laredo and Rotterdam.
- Express:Time-definite delivery with guaranteed transit windows and proactive customs pre-clearance.
- Charter:On-demand vehicle deployment for project cargo or emergency supply chain continuity.
FTL commands contract volume. LTL presents the steepest expansion trajectory on cross-border parcel fragmentation.
Market Player:
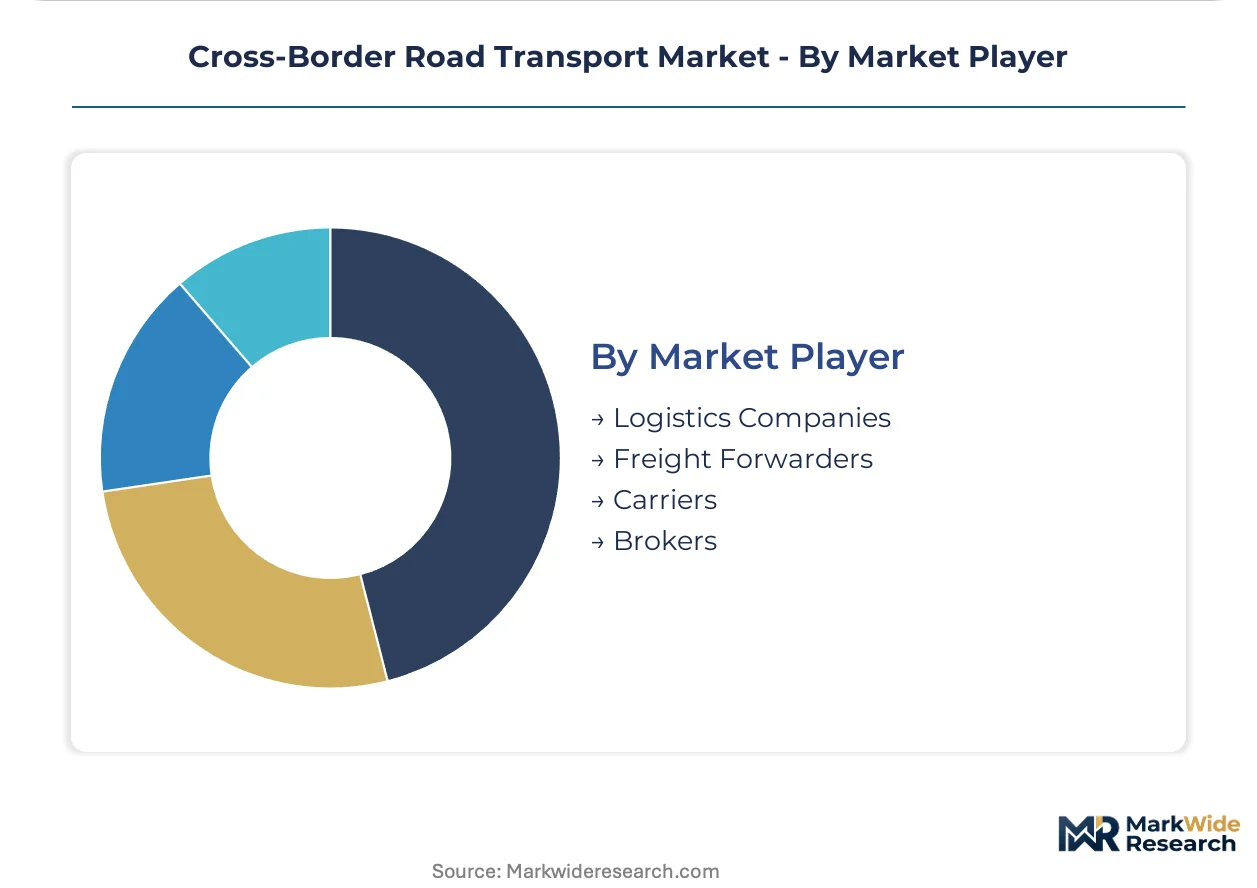
Asset ownership determines margin structure and customer stickiness across border-crossing complexity.
- Logistics Companies:Integrated providers combining owned fleets with contracted capacity and value-added services. DSV and Kuehne+Nagel leverage European land bridge expertise to capture China-Europe container flows that bypass maritime alternatives.
- Freight Forwarders:Non-asset coordinators arranging multimodal handoffs and customs documentation across jurisdictions. Forwarders with NVOCC authority are consolidating LCL shipments at Rotterdam and Hamburg for road-rail interchange to Central Asia.
- Carriers:Asset-based truck operators with direct driver employment and fleet maintenance responsibility.
- Brokers:Digital and traditional intermediaries matching spot loads with available capacity without asset ownership.
Logistics Companies control integrated margins. Brokers are expanding fastest on digital freight-matching adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Driver pools and logistics talent concentrate along the Mexico-US-Canada corridor, Germany's Rhine-Ruhr axis, and Poland's border-adjacent freight hubs, anchoring regional capacity formation.
United States
Automotive and electronics manufacturers nearshoring from Mexican maquiladoras drive cross-border freight demand. The US Department of Transportation enforces hours-of-service mandates through the Federal Motor Carrier Safety Administration. Laredo, Texas anchors the busiest commercial border crossing, processing over 40% of US-Mexico truck freight.
Germany
Industrial exporters in machinery and automotive components generate dense north-south corridor traffic toward Italian and Swiss markets. The EU Mobility Package imposes cabotage restrictions and revised driving-time rules through the European Commission. The Rhine-Ruhr metropolitan region concentrates customs-bonded warehousing capacity for Benelux-destined cargo.
Mexico
Electronics assembly and automotive supplier investments in Nuevo León and Baja California multiply northbound truck volumes. Mexico's Secretariat of Infrastructure, Communications and Transportation coordinates cross-border carrier licensing with US authorities. The Monterrey-Saltillo industrial corridor hosts expanding logistics parks serving just-in-sequence delivery to Texas assembly plants.
Poland
Central European distribution centers for German and Scandinavian retailers position Polish fleets as east-west transit operators. National road transport regulations align with EU tachograph enforcement through the General Inspectorate of Road Transport. The Słubice-Frankfurt border crossing handles substantial consolidated freight from Asian land bridge termini.
Netherlands
Rotterdam port hinterland traffic and flower-perishable exports to Germany sustain high-frequency cross-border lanes. The Dutch Human Environment and Transport Inspectorate enforces Euro VI-E emissions standards ahead of zero-emission zone mandates. The Venlo logistics cluster specializes in customs-bonded sorting for fragmented e-commerce parcel flows.
Cross-Border Road Transport Market Vendor Landscape
Top-tier vendors anchor integrated logistics networks, while mid-tier carriers compete on lane-specific efficiency and digital freight-matching capabilities. Asset-heavy operators sustain control over dedicated cross-border capacity through fleet ownership. Non-asset brokers capture spot-market volatility through technology platforms. Strategic moves concentrate on M&A consolidation for geographic coverage and battery-electric fleet partnerships for regulatory compliance.
Within the asset-heavy carrier archetype, Knight-Swift Transportation Holdings, Inc. and Schneider National, Inc. exemplify fleet ownership models prioritizing dedicated contract capacity. Among integrated logistics providers, DSV A/S occupies a position spanning European-Asian land bridge corridors. C.H. Robinson Worldwide, Inc. sits within the digital brokerage tier, representing non-asset freight-matching dominance across North American border crossings.
| Leading Market Players |
|---|
| Knight-Swift Transportation Holdings, Inc. |
| FedEx Corporation |
| Schneider National, Inc. |
| Landstar System, Inc. |
| XPO, Inc. |
| C.H. Robinson Worldwide, Inc. |
| United Parcel Service of America, Inc. (UPS) |
| DSV A/S |
| J.B. Hunt Transport, Inc. |
| Others |
Supply Flow & Price Mechanics
EU carbon-border adjustment mechanisms gate both qualified supply and premium-tier pricing access for cross-border road transport, as carriers with verified low-emission fleets command rate premiums while high-emission operators face margin compression from compliance costs. Shippers with CSRD-mandated Scope 3 reporting requirements now split procurement between certified green capacity at premium rates and commodity haulage at spot-market levels.
Pricing Analysis
Bundled long-term dedicated contracts are unbundling into spot-market exposure for non-critical freight. Three-tier pricing structure across premium express, standard contract, and economy spot levels separates time-definite guaranteed capacity from flexible load-board procurement. Pricing pressure stems from diesel cost volatility and driver wage inflation, particularly acute for smaller fleet owners lacking fuel hedging programs. E-commerce retailers show highest price sensitivity, while automotive just-in-sequence manufacturers accept premium rates for reliability.
Supply Chain Analysis
Diesel engine and axle assembly supply rests on German, Chinese, and Mexican manufacturing clusters for heavy-duty truck production. Critical inputs include semiconductors for telematics and engine management systems, specialized steel for chassis fabrication, and battery cells for electric powertrain conversion. Single-source vulnerability concentrates in advanced driver-assistance chipsets from Taiwanese foundries. Distribution runs through OEM dealer networks and independent parts distributors serving border-adjacent maintenance hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-border road transport offers margin expansion through electrification-driven operating cost reduction and premium-tier green capacity pricing. Fleet operators capturing early-mover advantages in battery-electric corridor infrastructure will extract rate premiums from CSRD-compliant shippers.
For Market Incumbents: To counter digital freight-matching platform disruption, Knight-Swift and Schneider National should deepen backward integration into charging infrastructure along Mexico-US lanes while consolidating mid-sized carriers in the Laredo-Nuevo León corridor to lock in driver pools and customs-bonded yard capacity. For New Entrants and Emerging Players: Digital freight-matching platforms present the most penetrable entry vector for asset-light operators targeting fragmented LTL e-commerce flows. Focus initial deployment on Rotterdam-Antwerp and El Paso-Ciudad Juárez circuits where charging infrastructure exists and customs pre-clearance complexity creates incumbent blind spots. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized Polish and German carriers with Euro VI-E fleets and established EU land bridge relationships. Long-term viability favors operators with demonstrated battery-electric deployment experience and contracted revenue from multinational manufacturers with Scope 3 reduction targets. Watch EU zero-emission zone mandate acceleration as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Fleet Partnership | DSV's charging infrastructure agreements with Dutch grid operators secure Rotterdam-Milan corridor access ahead of zero-emission mandates. |
| Digital Freight Platform Integration | C.H. Robinson's real-time load-matching algorithms reduce empty-mile ratios for North American border crossings below industry benchmarks. |
| Customs-Bonded Warehouse Expansion | XPO's Laredo sorting facility investments capture fragmented e-commerce parcel volumes from Mexican maquiladoras. |
| Driver Pool Consolidation | J.B. Hunt's acquisition of regional carriers in Texas border counties addresses FMCSA hours-of-service constraints. |
| Telematics Compliance Integration | Landstar's certified emissions monitoring systems retain contract eligibility with German automotive manufacturers under CSRD requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, customs brokerage managers, shipper procurement leads, and EU transport regulator officials with secondary validation from FMCSA enforcement data, EU TIR transit statistics, SEC 10-K filings of listed carriers, and customs/trade flow databases. Bottom-up carrier capacity modeling and top-down trade corridor demand estimates were triangulated against cross-border tonnage measurements.
Segment-weighting approaches applied differential growth assumptions across transport type, vehicle type, service type, and market player categories over the projection horizon. Freight transport, trucks, full truckload, and logistics companies received baseline weights reflecting current volume concentration, with adjustment factors for e-commerce LTL expansion and digital brokerage penetration. CAGRs were derived from elasticity modeling against manufacturing output and inventory-to-sales ratios, with specific inputs including EU Mobility Package implementation timelines and nearshoring investment announcements.
The model assumes a particular technology adoption path; alternative pathways for battery-electric and hydrogen fuel cell powertrains would alter the outlook for fleet replacement cycles and infrastructure investment requirements. Forecasts reflect assumptions regarding regulatory harmonization between US DOT and Mexico SICT hours-of-service rules. A small set of named triggers warrants ongoing watch: EU carbon-border adjustment mechanism enforcement dates, zero-emission zone geographic expansion, and China-Europe rail land bridge capacity restoration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Mexico Customs Brokerage Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
Romania Road Freight Transport Market