
 Spain Pharmaceutical Logistics Market | 2026-2036
Spain Pharmaceutical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Pharmaceutical Logistics Market Insights
Direct-to-pharmacy distribution is narrowing as hospital networks consolidate procurement and demand integrated cold chain guarantees. DHL Supply Chain Spain leverages its temperature-validated warehouse network across Iberia to capture this shift. Movianto anchors government and institutional contracts through specialized vaccine and plasma logistics capabilities. Logista Pharma competes on last-mile density, operating the most extensive refrigerated delivery footprint to retail pharmacies nationwide.
Pharmaceutical logistics encompasses the temperature-controlled storage, handling, and distribution of medicinal products, with cold chain segments requiring continuous monitoring between 2°C and 8°C for biologics and vaccines. The discipline ensures product integrity from manufacturer to patient through validated thermal packaging, real-time telemetry, and chain-of-custody documentation. Cold chain services command premium positioning due to specialized equipment and regulatory liability exposure, while track and trace technology segments expand fastest as EU serialization deadlines tighten compliance investment. Warehousing retains the largest value pool, though automated systems integration is displacing labor-intensive operations in high-throughput regional hubs.
Spain's AEMPS enforces EU Good Distribution Practice standards, while the national implementation of the Falsified Medicines Directive through the Spanish Medicines Verification System mandates end-to-end serialization. These frameworks elevate operational barriers, favoring providers with validated quality management systems and capital-intensive infrastructure. Stakeholders must monitor how AEMPS interpretation of EU pharmaceutical legislation evolves alongside autonomous community-level health procurement reforms that fragment purchasing authority across Catalonia, Andalusia, and Madrid.
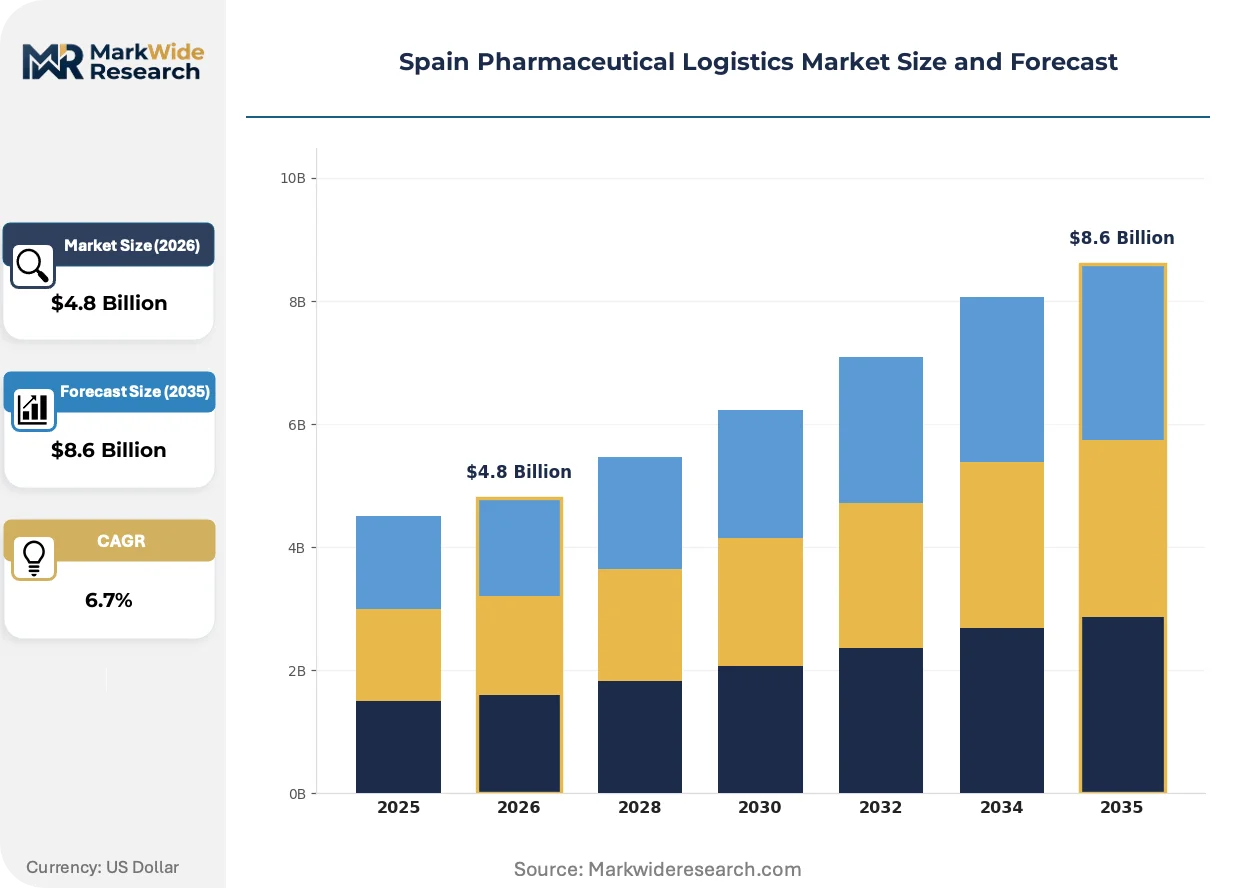
Market Dynamics
Hospital procurement consolidation across Spain's autonomous communities is compressing distributor margins while simultaneously elevating cold chain compliance requirements. This structural squeeze favors logistics providers with capital reserves to absorb upfront validation costs and multi-site temperature-controlled infrastructure.
Growth Catalysts
- EU Falsified Medicines Directive:AEMPS enforcement of end-to-end serialization mandates drives investment in track-and-trace infrastructure, expanding addressable market for compliant third-party logistics providers.
- Biologics manufacturing expansion:Temperature-sensitive monoclonal antibody and cell therapy production in Catalonia's Barcelona cluster generates dedicated cold chain demand from manufacturer to patient.
- Centralized hospital purchasing:Madrid's Servicio Madrileño de Salud and similar regional health services consolidate procurement volumes, creating contract opportunities for integrated distribution networks.
Market Restraints
- Energy cost volatility:Refrigerated warehouse operations face margin pressure from Iberian electricity market price swings, particularly affecting smaller regional distributors without renewable energy hedging.
- Equipment supplier concentration:Cold chain refrigeration systems rely heavily on German and Danish OEMs, exposing Spanish operators to euro-denominated import cost fluctuations and extended lead times.
- Labor certification scarcity:EU Good Distribution Practice requires qualified personnel for temperature mapping and deviation management, constraining operational scaling in secondary cities.
Strategic Opportunities
- Andalusian vaccine hub development:Seville's emerging biomanufacturing zone lacks mature cold chain infrastructure, creating first-mover advantage for temperature-validated distribution centers serving southern Spain and Portugal.
- Real-time telemetry convergence:Integration of IoT sensors with blockchain custody records enables premium service tiers for high-value plasma and gene therapy shipments.
- Autonomous community procurement fragmentation:Divergent tendering rules across Catalonia, Basque Country, and Valencia create niche specialization openings for regionally focused logistics operators.
Industry Challenges
- Deviation investigation capacity:Temperature excursion root-cause analysis requires specialized quality assurance personnel that outpace current vocational training pipeline output.
- Legacy warehouse retrofitting:Older Madrid and Barcelona facilities face structural constraints installing automated storage and retrieval systems compatible with pharmaceutical-grade environmental controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Pharmaceutical Logistics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Cold Chain, Compliance Delivery Mode: Direct Delivery, Drop Shipping, Last-Mile, Standard Shipping End User: Pharmaceutical Manufacturers, Distributors, Retail Pharmacies, Hospitals Technology: Track & Trace, Automated Systems, IoT Solutions, RFID |
| Companies Covered | United Parcel Service (UPS), CEVA Logistics, DHL Supply Chain Spain, Movianto, DSV, Logista Pharma, FedEx Express, Eurotranspharma, Kuehne + Nagel S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Pharmaceutical Logistics Market Trends and Innovations
Digital infrastructure investments are compressing decision cycles across Spain's pharmaceutical supply chain, replacing paper-based custody documentation with automated verification systems. This shift reconfigures competitive advantage toward data architecture capabilities.
Passive thermal packaging with integrated IoT loggers is collapsing the distinction between ambient and cold chain monitoring, enabling granular temperature visibility without active refrigeration. Generic drug distributors serving retail pharmacies adopt these systems fastest, stripping cost from previously premium-tracked shipments. The technology is collapsing traditional service tier boundaries that separated validated cold chain from standard distribution.
AEMPS interpretation of EU Good Distribution Practice tightens documentation requirements for cross-border shipments entering Spain from Portuguese and French manufacturing sites. The regulator now demands Spanish-language deviation reports and accelerated notification timelines for temperature excursions. Import-dependent biologics suppliers are responding by pre-positioning inventory in Madrid-Barcelona corridor hubs rather than maintaining direct cross-border delivery models.
Hospital pharmacy directors increasingly unbundle logistics services from product procurement, contracting distribution separately from pharmaceutical purchasing. This disintermediation fragments previously consolidated vendor relationships and opens direct contracting channels with specialized cold chain operators. The pattern is most visible in Catalonia's public hospital network, where pharmacy autonomy from central procurement has accelerated post-pandemic.
Spain Pharmaceutical Logistics Market Segmentation
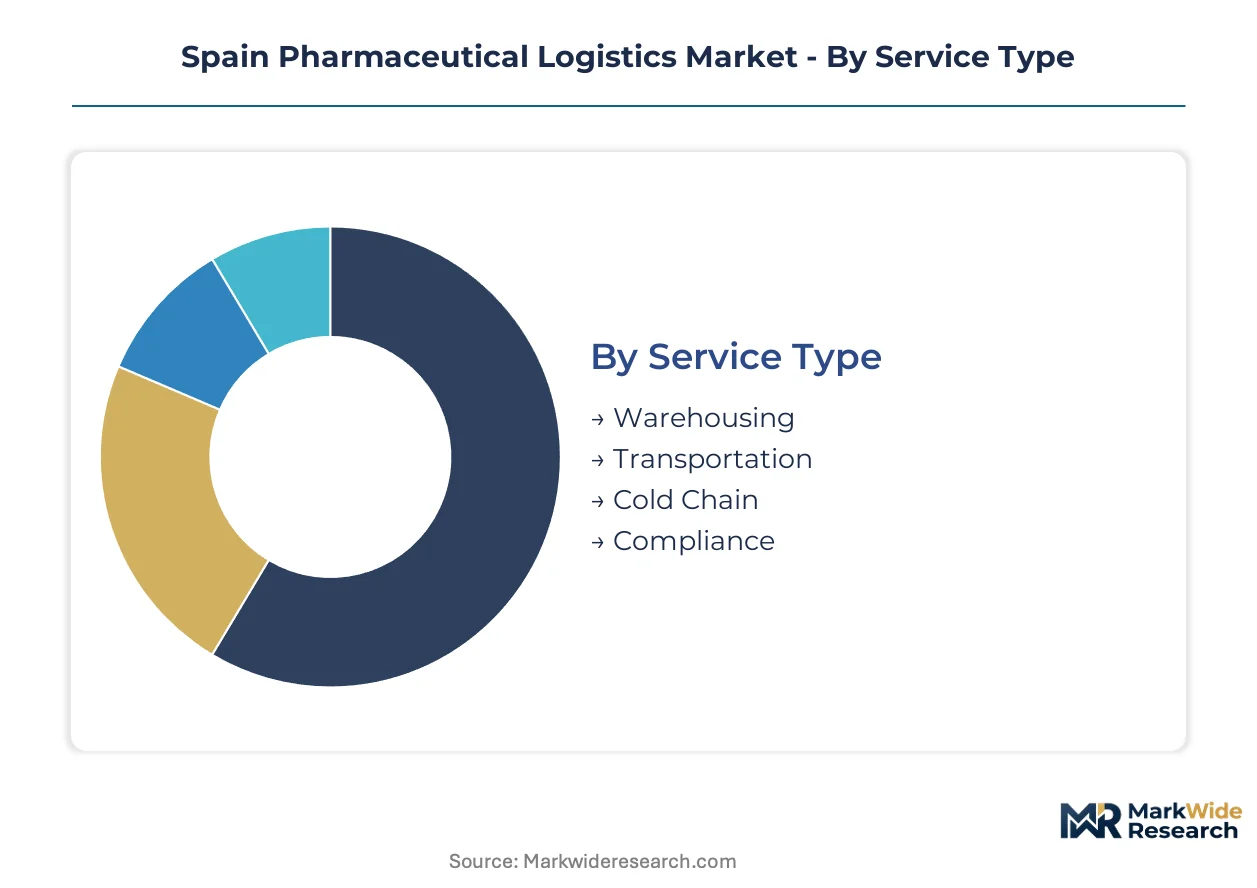
Segmentation in Spain's pharmaceutical logistics market reveals how service specialization, delivery configuration, and technology adoption align with AEMPS regulatory requirements and autonomous community procurement patterns. Understanding these divisions exposes where capital investment concentrates and where margin compression threatens incumbent positioning.
Service Type:
Use-case spectrum spans ambient storage for generic tablets to validated cold chain for Catalonia-manufactured biologics, with compliance services commanding premium positioning under EU serialization mandates.
- Warehousing:Temperature-controlled facilities with automated storage and retrieval systems dominate capital allocation, particularly in Madrid-Barcelona corridor hubs serving consolidated hospital procurement networks. AEMPS inspections favor providers with redundant backup power and continuous environmental monitoring.
- Cold Chain:Continuous 2°C to 8°C validation for vaccines and plasma products carries highest liability exposure and steepest barrier to entry. Barcelona's monoclonal antibody manufacturing cluster generates dedicated demand for manufacturer-integrated distribution.
- Transportation:Fleet operations with validated thermal packaging and real-time telemetry support cross-autonomous community movements under AEMPS documentation requirements.
- Compliance:Serialization integration, deviation investigation, and Spanish-language regulatory reporting services expand as EU Falsified Medicines Directive enforcement tightens.
The dominant share belongs to Warehousing, while Cold Chain is closing the gap fastest.
Delivery Mode:
Cost tier differentiation separates capital-intensive last-mile refrigerated networks from standardized parcel integration, with hospital procurement consolidation reshaping volume allocation.
- Last-Mile:Refrigerated delivery to retail pharmacies nationwide requires dense route optimization and temperature-validated vehicle fleets. Logista Pharma's extensive footprint captures this segment through pharmacy network coverage.
- Direct Delivery:Manufacturer-to-hospital shipments bypass distributor intermediation where pharmacy directors unbundle logistics from procurement, particularly in Catalonia's autonomous hospital networks.
- Drop Shipping:Third-party fulfillment from regional hubs reduces inventory carrying costs for generic distributors serving fragmented retail pharmacy demand.
- Standard Shipping:Ambient parcel services for non-temperature-sensitive products face margin erosion from passive thermal packaging adoption collapsing traditional service boundaries.
Last-Mile retains volume leadership, though Direct Delivery is expanding most quickly as hospital networks consolidate.
End User:
Customer type determines contract structure, with government-backed hospital procurement demanding integrated cold chain guarantees while retail pharmacy serves fragmented, price-sensitive demand.
- Hospitals:Centralized purchasing through Servicio Madrileño de Salud and similar regional health services creates large-scale contract opportunities for providers with multi-site temperature-controlled infrastructure and AEMPS-validated quality systems.
- Pharmaceutical Manufacturers:Catalonia-based biologics producers require dedicated cold chain partnerships from production facility to patient, with deviation investigation capabilities specified in service agreements.
- Distributors:Wholesale intermediaries face margin compression from procurement consolidation while investing in track-and-trace infrastructure for EU compliance.
- Retail Pharmacies:Fragmented nationwide network demands last-mile density, with autonomous community-level procurement rules creating regional specialization openings.
Hospitals command the largest contract values, while Pharmaceutical Manufacturers are driving fastest adoption of integrated cold chain services.
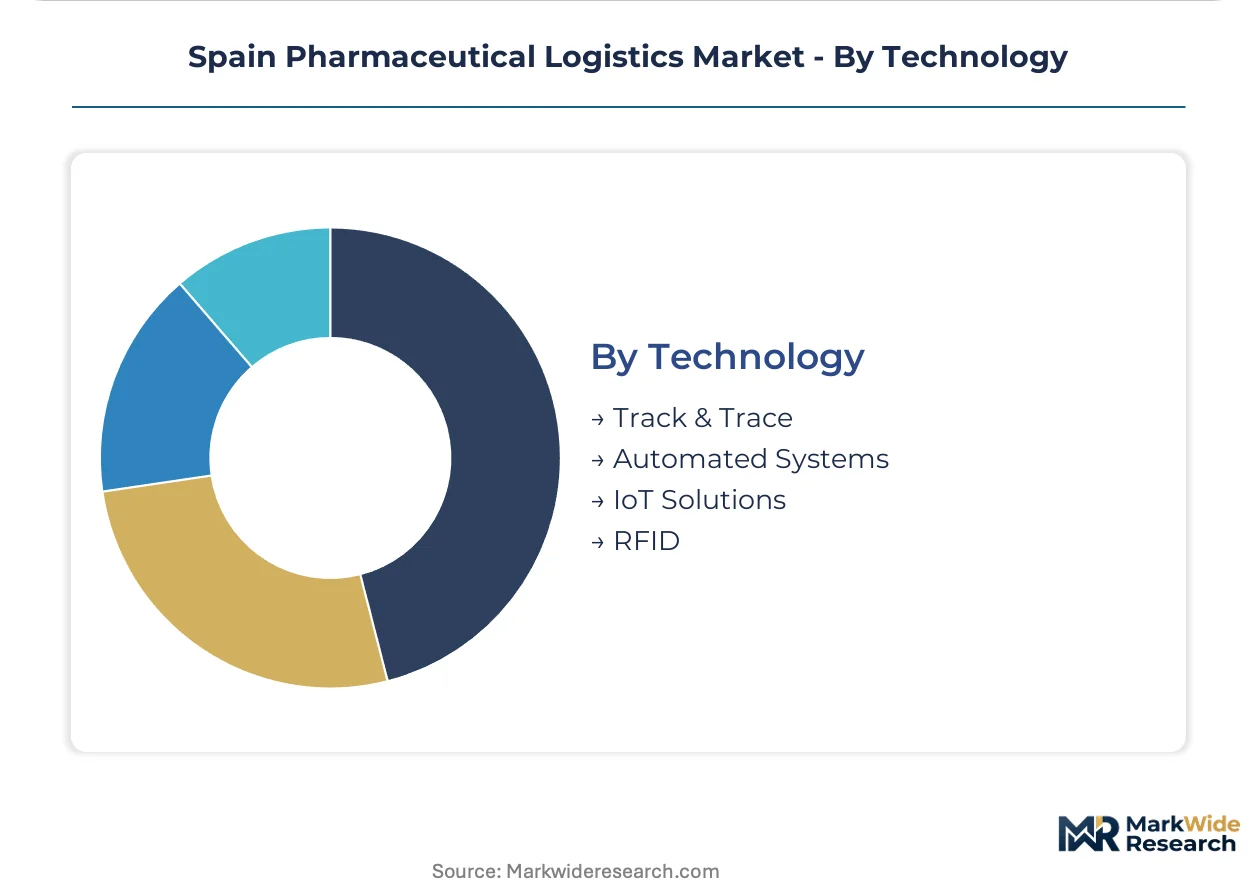
Technology:
Maturity gradient separates established track-and-trace compliance infrastructure from emerging IoT-blockchain convergence for high-value plasma custody.
- Track & Trace:Serialization systems mandated by AEMPS under EU Falsified Medicines Directive represent baseline compliance investment, with Spanish-language deviation reporting now required for cross-border shipments.
- IoT Solutions:Real-time temperature telemetry with automated alert systems enables premium service tiers for gene therapy and personalized medicine shipments requiring continuous custody documentation.
- Automated Systems:Robotic storage and retrieval in high-throughput regional hubs displaces labor-intensive operations, though legacy Madrid and Barcelona facilities face structural retrofitting constraints.
- RFID:Item-level tracking for inventory management operates at pilot scale, with adoption limited by integration costs against established barcode infrastructure.
Track & Trace holds installed base dominance, while IoT Solutions are climbing the fastest as biologics manufacturing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates along the Madrid-Barcelona corridor, where temperature-controlled infrastructure density commands premium logistics rates, while peripheral autonomous communities face service gaps and elevated procurement costs for specialized cold chain capabilities.
Madrid
Hospital procurement consolidation through Servicio Madrileño de Salud generates large-scale contract volumes demanding multi-site temperature-controlled infrastructure. AEMPS enforcement of EU Good Distribution Practice elevates validation requirements for warehousing operations. The capital anchors Spain's densest cluster of automated pharmaceutical distribution hubs serving consolidated regional health networks.
Catalonia
Barcelona's monoclonal antibody and cell therapy manufacturing expansion generates dedicated cold chain demand from production facility to patient. The autonomous community's pharmacy directors increasingly unbundle logistics from pharmaceutical procurement, opening direct contracting channels with specialized operators. Temperature-sensitive biologics production concentrates in the Barcelona metropolitan zone.
Basque Country
Specialized plasma and blood product logistics capabilities serve regional hospital networks with stringent deviation investigation requirements. Divergent tendering rules from Madrid and Catalonia create niche specialization openings for regionally focused operators. Bilbao-San Sebastián corridor hosts validated cold chain infrastructure serving northern Spain and cross-border French demand.
Andalusia
Seville's emerging biomanufacturing zone lacks mature cold chain infrastructure, creating first-mover advantage for temperature-validated distribution centers. Energy cost volatility from Iberian electricity market price swings particularly affects regional distributors without renewable energy hedging. Southern Spain's vaccine hub development attracts capital for facilities serving Portugal and North African markets.
Valencia
Fragmented retail pharmacy networks demand last-mile density with autonomous community-level procurement rules distinct from neighboring regions. Valencia's port infrastructure supports import-dependent biologics suppliers pre-positioning inventory to avoid direct cross-border delivery complexity. Regional health service consolidation patterns lag Madrid and Catalonia, preserving intermediary distributor relationships longer.
Spain Pharmaceutical Logistics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying validated thermal packaging and refrigeration equipment. The vendor base separates between capital-intensive national networks with AEMPS-validated multi-site infrastructure and regional specialists capturing autonomous community procurement fragmentation. Three archetypes dominate: integrated cold chain platform operators, last-mile density specialists, and compliance-focused institutional contractors. Competitive moves concentrate on warehouse automation retrofitting and strategic partnerships with biologics manufacturers for dedicated distribution agreements.
Among international platform operators, DHL Supply Chain Spain and UPS anchor the integrated infrastructure tier, exemplifying capital-reserved providers absorbing upfront validation costs across Iberian temperature-controlled networks. Movianto occupies a position within the institutional specialist archetype, its government and vaccine logistics capabilities representing the compliance-heavy contractor model. These three names illustrate how AEMPS enforcement of EU serialization mandates and cold chain standards favors operators with redundant quality management systems and multi-regional hub coverage.
| Leading Market Players |
|---|
| United Parcel Service (UPS) |
| CEVA Logistics |
| DHL Supply Chain Spain |
| Movianto |
| DSV |
| Logista Pharma |
| FedEx Express |
| Eurotranspharma |
| Kuehne + Nagel S.A. |
| Others |
Pricing and Supply Chain Analysis
The Madrid-Barcelona corridor's temperature-controlled warehouse capacity concentration enables logistics providers to command premium rates for AEMPS-validated cold chain services, while peripheral autonomous communities absorb elevated procurement costs due to infrastructure scarcity.
Pricing Analysis
The customization-premium spread separates standard ambient distribution from validated cold chain services with continuous 2°C to 8°C monitoring and deviation investigation capabilities. Price differentiation rests on AEMPS certification tier and geographic delivery density, with hospital procurement consolidation compressing margins for undifferentiated ambient storage. Cost compression in standard shipping intensifies as passive thermal packaging with integrated IoT loggers collapses traditional service boundaries. Retail pharmacy networks demonstrate highest price sensitivity, while biologics manufacturers accept premium positioning for gene therapy custody documentation.
Supply Chain Analysis
Extended payment terms from consolidated hospital procurement networks strain working capital for regional distributors lacking supply-chain finance facilities. Equipment supply concentrates in Germany and Denmark for refrigeration systems, while thermal packaging materials draw from specialized European converters. Single-source vulnerability runs through German and Danish OEMs for cold chain infrastructure. Distribution feeds from Madrid-Barcelona corridor hubs to autonomous community health networks, with cross-border pre-positioning replacing direct Portuguese and French manufacturing site delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
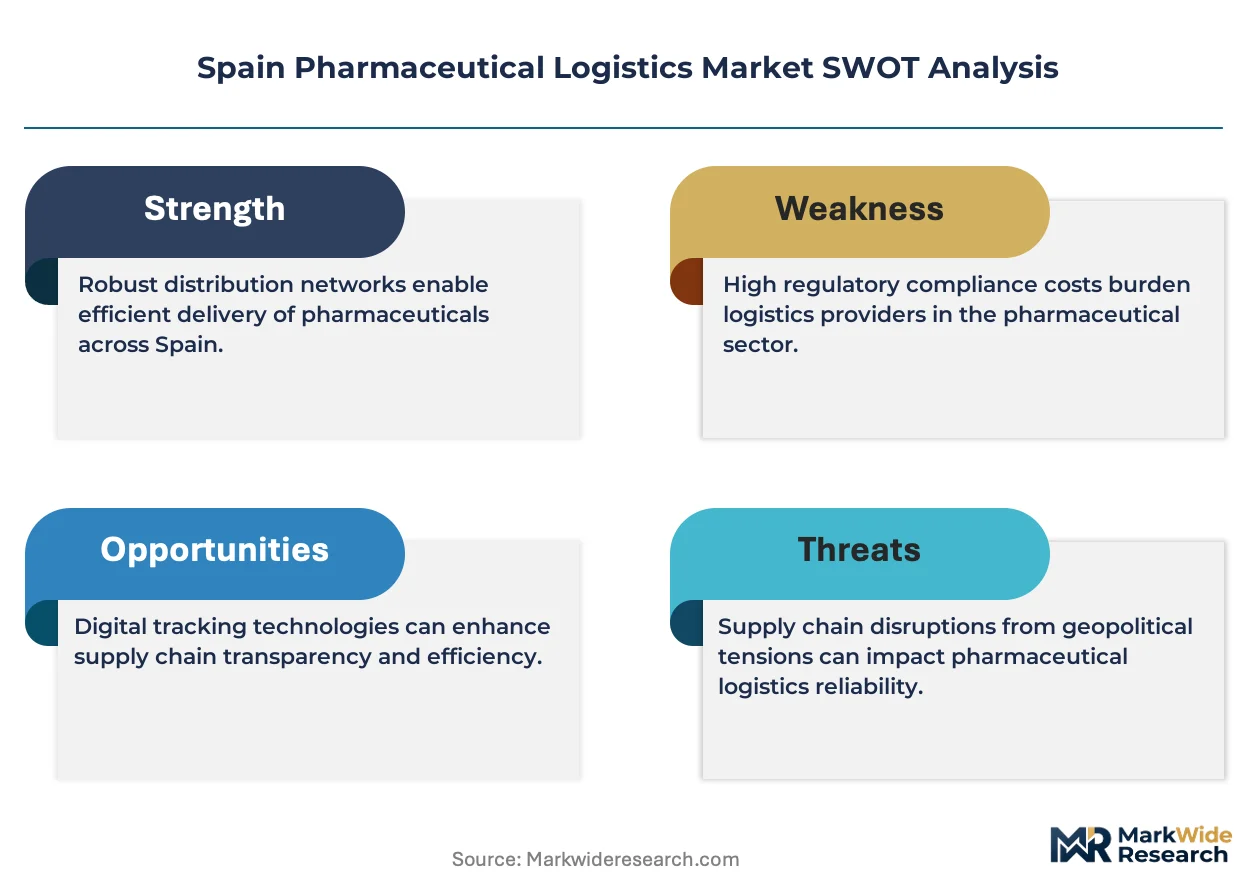
Incumbents face substitution pressure from passive thermal packaging technologies that collapse traditional cold chain premium tiers, requiring defensive repositioning around data architecture and compliance capabilities.
For Market Incumbents: Entrench multi-site temperature-controlled infrastructure across the Madrid-Barcelona corridor to absorb AEMPS validation costs that smaller regional distributors cannot shoulder. Deepen backward integration into automated storage and retrieval systems to offset labor certification scarcity. Passive thermal packaging adoption threatens premium service tier boundaries. For New Entrants and Emerging Players: Andalusian vaccine hub development in Seville represents the most penetrable entry point, with biomanufacturing expansion outpacing mature cold chain infrastructure. Autonomous community procurement fragmentation in Valencia and Basque Country creates niche specialization openings distinct from Madrid-Catalonia consolidation patterns. Target direct contracting channels with pharmacy directors unbundling logistics from procurement in Catalonia's public hospital network. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with IoT-blockchain convergence capabilities over component specialists in validated thermal packaging. The five-to-ten year viability window rewards acquisition of regional operators with AEMPS-validated quality systems and redundant backup power infrastructure. Monitor AEMPS interpretation shifts for EU Good Distribution Practice enforcement intensity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Retrofitting | Robotic storage and retrieval displaces labor-intensive operations in high-throughput Madrid-Barcelona corridor hubs. |
| Biologics Manufacturer Partnership | Dedicated distribution agreements with Catalonia monoclonal antibody producers secure manufacturer-integrated cold chain volumes. |
| Real-Time Telemetry Integration | IoT sensor convergence with blockchain custody records enables premium service tiers for plasma and gene therapy shipments. |
| Andalusian Distribution Center Buildout | First-mover temperature-validated facilities capture Seville biomanufacturing zone demand serving southern Spain and Portugal. |
| Compliance Service Expansion | Spanish-language deviation investigation and accelerated AEMPS notification capabilities address cross-border shipment documentation requirements. |
Research Methodology
Desk research of AEMPS regulatory filings, EU pharmaceutical legislation databases, and autonomous community health procurement records preceded structured interviews with hospital pharmacy directors, cold chain logistics operators, biologics manufacturing supply chain leads, and temperature-controlled warehouse facility managers. Secondary validation drew from Spanish Medicines Verification System documentation, EU Falsified Medicines Directive implementation reports, and Iberian electricity market price data. Bottom-up facility capacity modeling triangulated against top-down autonomous community health expenditure analysis.
Assumptions held AEMPS enforcement intensity and EU serialization mandate timelines fixed while varying energy cost volatility scenarios and biologics manufacturing expansion rates across the projection horizon. Segmentation modeling incorporated service type, delivery mode, end user archetype, and technology adoption dimensions alongside regional regulatory cluster differentiation. CAGRs derived from facility investment pipelines, hospital procurement consolidation patterns, and cold chain equipment order backlogs.
Practitioners should monitor AEMPS interpretation evolution, autonomous community health procurement reform progression, and Iberian electricity market price volatility for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Cargo Transportation Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Asia-Pacific Logistics Automation Market
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
China Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
UK Freight Forwarding Market