
 UAE Contract Logistics Market | 2026-2036
UAE Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Contract Logistics Market Insights
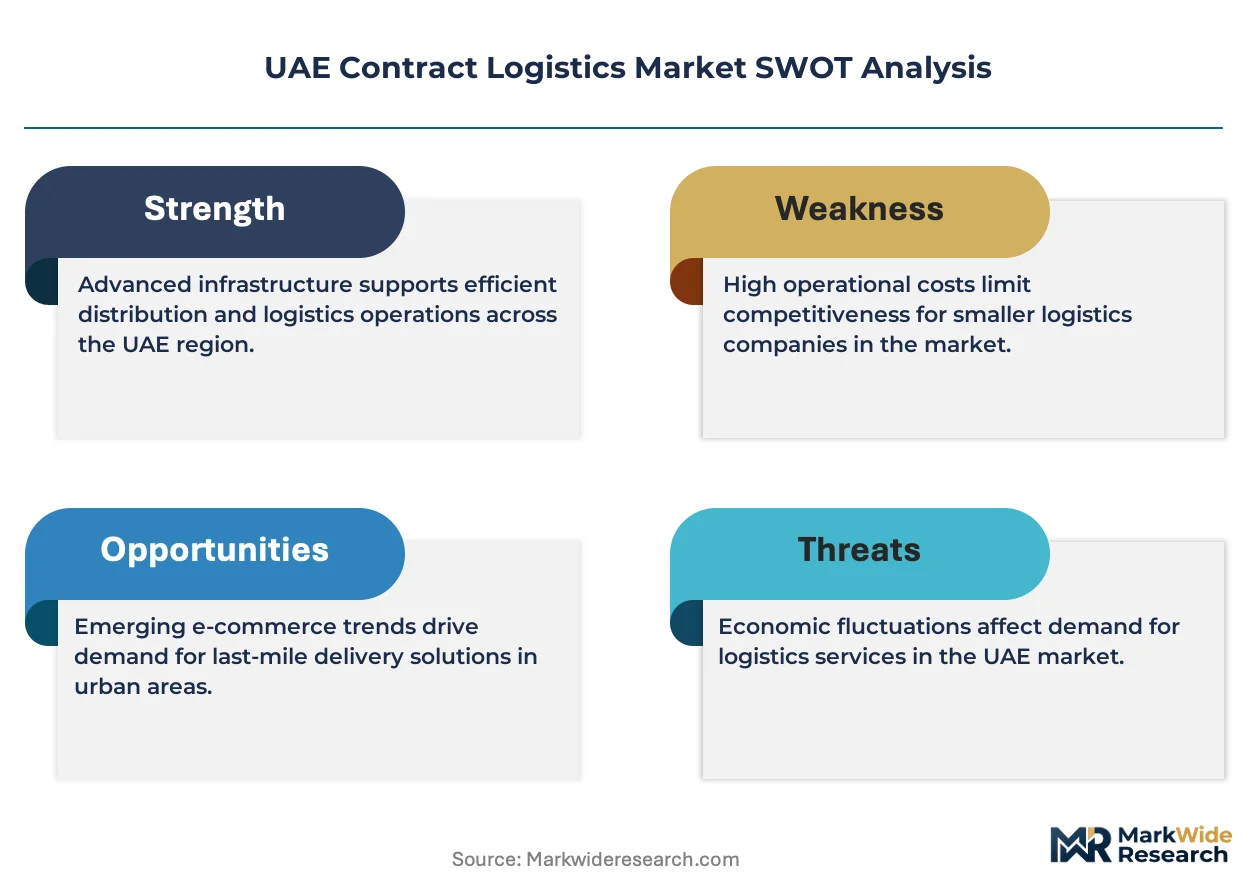
Modular warehousing configurations with flexible racking and scalable square footage is recalibrating how retailers and automotive suppliers contract for space. DHL Supply Chain leverages its multi-client campus model near Jebel Ali to capture economies of shared labor and equipment. Agility anchors its regional footprint through temperature-controlled facilities serving healthcare clients. Al Futtaim Logistics dominates last-mile distribution through its captive retail relationships across mall and hypermarket networks.
Contract logistics encompasses the outsourcing of supply chain execution activities—encompassing inventory storage, order fulfillment, and distribution coordination—typically governed by multi-year service agreements with defined KPIs for accuracy and timeliness. Its primary commercial purpose is to replace fixed warehouse assets and direct labor with variable-cost structures that align fulfillment spending with shipment volumes. Warehousing commands the deepest margin pools due to long-lease infrastructure and value-added service attachments, while e-commerce distribution channels exhibit the fastest structural expansion as direct-to-consumer order profiles reshape picking and packing workflows. Automation technology investments in sortation and robotic goods-to-person systems are concentrating among operators serving high-velocity consumer goods accounts.
The UAE's logistics sector operates under dual oversight from the Ministry of Economy's commercial licensing framework and free zone authorities such as Jebel Ali Free Zone and Dubai South, with customs compliance administered by the Federal Customs Authority. These layered regulatory structures shape warehouse location economics, labor mobility rules, and cross-border duty deferral options that directly influence contract design. MOHAP pharmaceutical storage guidelines and forthcoming UAE energy efficiency standards for cold chain facilities will tighten facility certification requirements. Stakeholders must monitor how free zone incentive recalibrations and federal corporate tax implementation alter the net cost advantage of outsourced versus captive logistics operations.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing warehouse lease structures and forcing multi-client operators to reconfigure shared labor pools around same-day cutoffs rather than batch processing cycles.
Growth Catalysts
- MOHAP pharmaceutical storage guidelines:Cold chain certification mandates are expanding temperature-controlled warehouse demand among healthcare distributors seeking compliant third-party capacity.
- Dual licensing regime flexibility:Free zone and mainland operating permits allow operators to site facilities across Dubai South and Jebel Ali corridors while optimizing customs duty deferral positions.
- Robotic goods-to-person systems:Automation deployment in high-velocity consumer goods accounts is reducing pick labor intensity and enabling denser SKU storage configurations.
Market Restraints
- Skilled warehouse technician scarcity:Maintenance and robotics programming talent pools remain shallow in the UAE logistics labor market, inflating operator training costs.
- Free zone incentive recalibration risk:Corporate tax implementation and evolving duty structures may erode the net cost advantage of outsourced versus captive warehouse operations.
- Cross-border customs friction:Federal Customs Authority compliance complexity creates documentation bottlenecks for multi-country distribution contracts.
Strategic Opportunities
- Ras Al Khaimah and northern emirates penetration:Underdeveloped logistics infrastructure outside Dubai-Abu Dhabi corridors offers first-mover positioning for regional distribution hubs.
- Energy efficiency standards for cold chain:Upcoming federal certification requirements will disqualify aging facilities, creating replacement demand for compliant build-to-suit warehouses.
- Automotive EV parts logistics:Battery storage protocols and hazardous materials handling expertise are opening specialized contract segments as electric vehicle sales expand.
Industry Challenges
- WMS integration with legacy ERP systems:Retail and automotive clients operate fragmented technology stacks that delay contract onboarding and inflate customization costs.
- Multi-client campus labor allocation:Shared workforce models struggle to balance surge capacity across e-commerce, healthcare, and industrial accounts with divergent seasonal patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Contract Logistics Market |
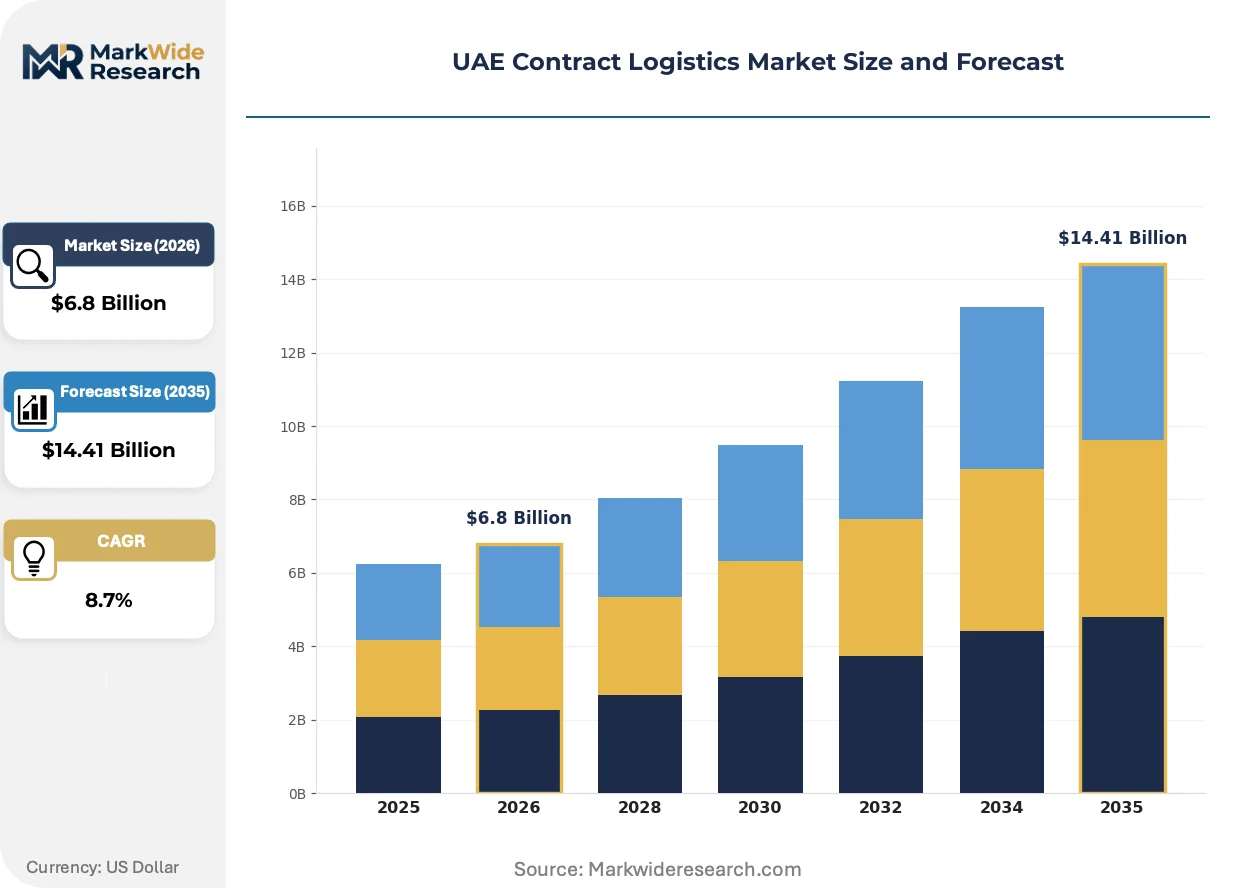
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Value-Added Services End User: Retail, Healthcare, Automotive, Consumer Goods Technology: Automation, IoT, Cloud Computing, Big Data Distribution Channel: Direct, E-commerce, Third-party, Multi-channel |
| Companies Covered | Aramex, DHL Supply Chain, FedEx Supply Chain, Kuehne + Nagel, Gulf Agency Company, CEVA Logistics, Al Futtaim Logistics, DB Schenker, Agility, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Contract Logistics Market Trends and Innovations
Automation density and regulatory certification requirements are bifurcating operator strategies between high-velocity consumer goods campuses and specialized healthcare-automotive facilities.
Autonomous mobile robots are integrating shuttle-based inventory transport with existing warehouse management systems. Retail operators serving direct-to-consumer channels are deploying these systems at accelerated pace to compress order cycle times. The technology is integrating picking labor with robotic transport layers, reducing headcount per unit shipped while raising facility throughput ceilings.
MOHAP pharmaceutical storage guidelines are tightening temperature monitoring and documentation protocols for healthcare logistics contracts. Facility operators must now deploy redundant cold chain infrastructure and real-time tracking systems to maintain compliance. Healthcare distributors are responding by consolidating volumes with certified third-party operators possessing dedicated quality assurance teams.
Same-day delivery cutoffs are compressing order cutoff windows and reshaping labor scheduling across e-commerce fulfillment networks. Traditional batch-picking workflows are yielding to continuous order release patterns that demand flexible staffing models. Dubai South corridor operators are most exposed to this shift given their concentration of fashion and electronics retail accounts.
UAE Contract Logistics Market Segmentation
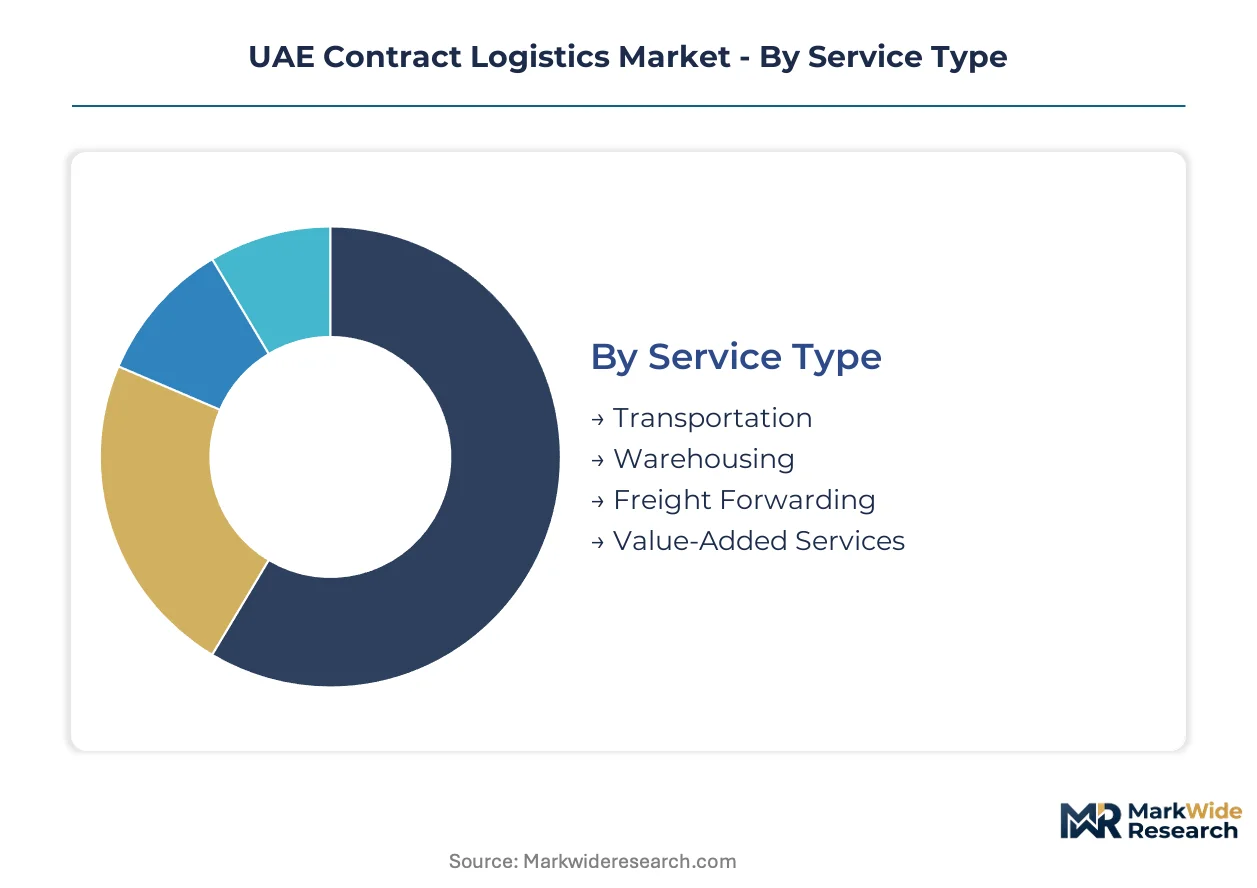
Segmentation in UAE contract logistics reveals how service configuration, end-use concentration, and technology deployment create distinct margin profiles. Buyers select providers based on whether their priority lies in cost efficiency, compliance certification, or velocity capabilities. Each segment carries different infrastructure requirements and contract structures.
Service Type:
Buyers weigh fixed-asset substitution against variable-cost flexibility when selecting service bundles.
- Transportation:Fleet-based execution of line-haul and last-mile movements under dedicated or shared-user contracts. Demand concentrates among retail operators serving Dubai South corridor e-commerce accounts where same-day cutoff windows compress route optimization requirements.
- Warehousing:Physical storage infrastructure with inventory management, order fulfillment, and value-added processing attachments. Jebel Ali Free Zone operators capture the deepest margin pools through multi-client campus models that spread labor and equipment costs across consumer goods and healthcare accounts.
- Freight Forwarding:Coordination of international cargo movements across air, sea, and land modes. Customs brokerage and documentation services under Federal Customs Authority oversight create compliance-driven selection criteria for cross-border distributors.
- Value-Added Services:Kitting, labeling, quality inspection, and returns processing that extend basic logistics execution. Automotive and electronics manufacturers deploy these services to postpone final configuration until destination-market orders materialize.
Warehousing leads on scale; value-added services lead on momentum.
End User:
Application-specific compliance requirements and velocity thresholds segment buyer priorities across verticals.
- Retail:Fashion, electronics, and general merchandise operators demanding omnichannel fulfillment capabilities. Dubai South corridor concentration drives automation investments in robotic goods-to-person systems for direct-to-consumer order profiles.
- Healthcare:Pharmaceutical distributors and medical device suppliers requiring MOHAP-certified temperature-controlled storage. Cold chain infrastructure redundancy and real-time tracking systems command premium pricing structures.
- Automotive:OEM parts distribution and aftermarket logistics with specialized handling for batteries and hazardous materials. EV parts storage protocols are opening specialized contract segments as electric vehicle penetration expands.
- Consumer Goods:High-velocity packaged goods and perishables with seasonal demand volatility. Multi-client operators struggle to balance surge capacity against divergent peak patterns across retail and industrial accounts.
Retail leads on scale; healthcare leads on momentum.
Technology:
Deployment maturity and integration complexity determine which technology investments deliver measurable throughput gains.
- Automation:Robotic picking, autonomous mobile robots, and shuttle-based inventory transport systems. High-velocity consumer goods accounts in Jebel Ali corridor deploy these systems to reduce labor intensity per unit shipped.
- IoT:Sensor networks for real-time asset tracking, environmental monitoring, and predictive maintenance. Cold chain operators leverage IoT to satisfy MOHAP pharmaceutical documentation mandates.
- Cloud Computing:Scalable warehouse management system hosting and multi-facility data integration. Fragmented legacy ERP stacks at retail and automotive clients delay cloud migration timelines.
- Big Data:Demand forecasting, route optimization, and inventory positioning analytics. E-commerce operators apply predictive models to compress order cycle times against same-day delivery cutoffs.
Automation leads on scale; IoT leads on momentum.
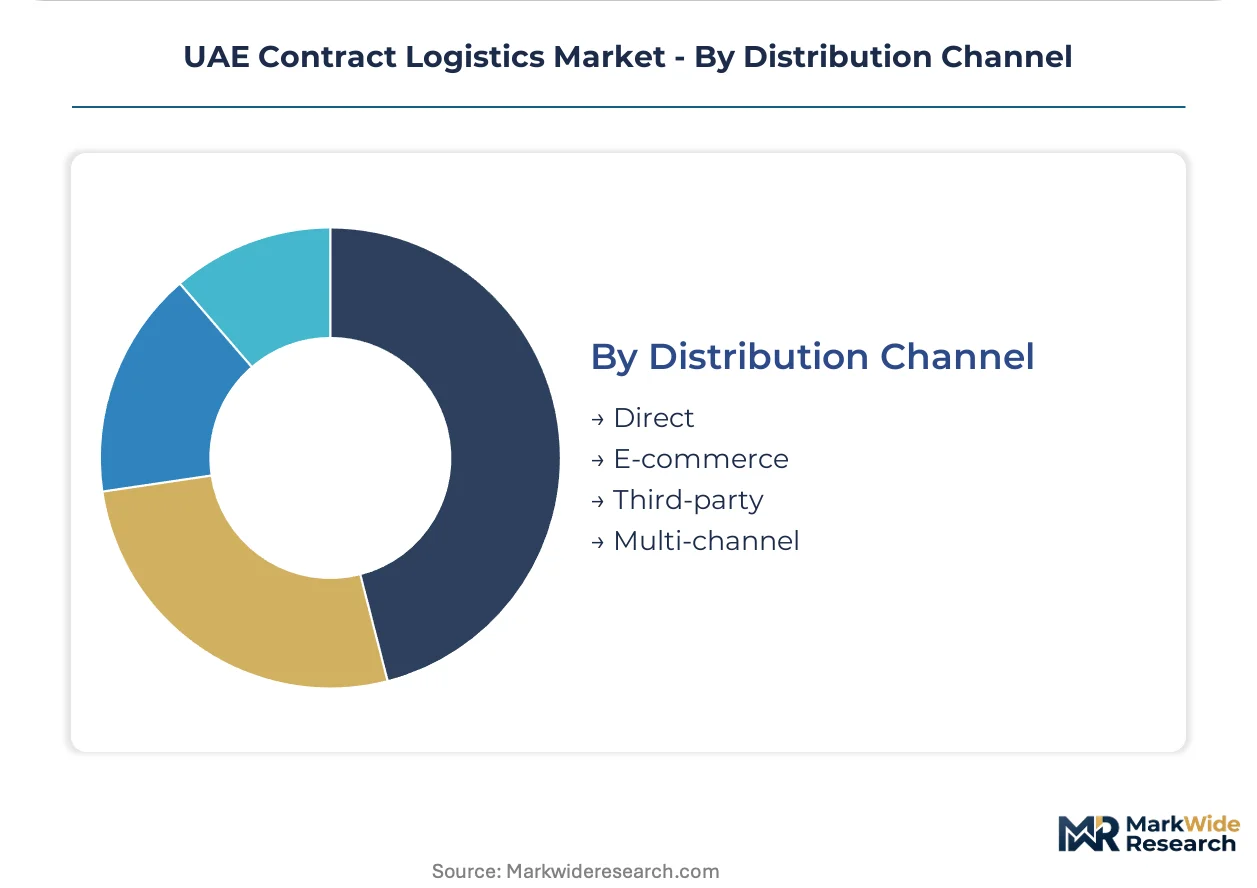
Distribution Channel:
Channel structure dictates facility location economics and labor scheduling models.
- Direct:Manufacturer-controlled logistics serving captive retail networks or B2B accounts. Al Futtaim Logistics dominates this channel through mall and hypermarket captive relationships.
- E-commerce:Direct-to-consumer fulfillment with continuous order release patterns replacing batch workflows. Dubai South operators face the most acute labor flexibility pressures from compressed cutoff windows.
- Third-party:Outsourced execution to contract logistics specialists under multi-year service agreements. DHL Supply Chain leverages multi-client campuses to capture shared labor economies.
- Multi-channel:Integrated fulfillment across retail storefronts, online platforms, and wholesale accounts. Inventory positioning complexity drives demand for modular warehousing with scalable square footage.
Third-party leads on scale; e-commerce leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE's logistics infrastructure traces its modern lineage to the 1970s port development at Jebel Ali, which established Dubai as a transshipment hub before expanding into integrated contract logistics services. Federal and emirate-level coordination has since layered free zone incentives atop customs modernization programs. Today, warehouse siting decisions concentrate across four distinct economic zones.
Dubai
E-commerce fulfillment velocity drives demand for modular warehousing near Dubai South and Jebel Ali corridors. The Department of Economic Development's dual licensing regime allows operators to hold both mainland and free zone permits. Jebel Ali Free Zone anchors multi-client campus models serving retail and healthcare verticals with shared labor pools.
Abu Dhabi
Industrial diversification programs under the Department of Economic Development are expanding non-oil logistics demand. Khalifa Port and KIZAD free zone offer integrated customs deferral for automotive and aerospace parts distributors. The zone's energy efficiency mandates for cold chain facilities are accelerating warehouse replacement cycles.
Sharjah
Cost-sensitive warehousing operators are migrating from Dubai to Sharjah's Hamriyah Free Zone and industrial zones. The emirate's lower land costs support bulk storage and consumer goods distribution serving northern UAE markets. Sharjah's customs coordination with Federal Customs Authority maintains cross-border clearance speeds competitive with Dubai.
Northern Emirates
Ras Al Khaimah and Fujairah present underdeveloped logistics infrastructure with first-mover positioning potential. Ras Al Khaimah Economic Zone offers extended lease terms for build-to-suit facilities targeting regional distribution networks. Fujairah's port expansion is attracting maritime logistics operators seeking Indian Ocean corridor access.
UAE Contract Logistics Market Competitive Landscape
The competitive structure tilts toward diversified global operators with multi-client campus capabilities. Three to four integrated logistics providers command disproportionate share of pharmaceutical and automotive verticals, while regional specialists retain last-mile density in captive retail networks. Two strategic archetypes dominate: global 3PLs leveraging cross-border freight forwarding integration, and vertically integrated conglomerate logistics arms monetizing internal demand. Capacity expansion and automation deployment constitute the primary competitive moves, with operators investing in robotic goods-to-person systems to compress order cycle times.
Within the global 3PL tier, DHL Supply Chain and Kuehne + Nagel exemplify integrated service models spanning warehousing, forwarding, and value-added processing. Agility occupies a specialized position in temperature-controlled healthcare logistics. Regional conglomerate logistics arms including Al Futtaim Logistics anchor last-mile distribution through captive retail relationships across mall and hypermarket networks.
| Leading Market Players |
|---|
| Aramex |
| DHL Supply Chain |
| FedEx Supply Chain |
| Kuehne + Nagel |
| Gulf Agency Company |
| CEVA Logistics |
| Al Futtaim Logistics |
| DB Schenker |
| Agility |
| Others |
Pricing and Supply Chain Analysis
Family-owned logistics conglomerates with captive retail networks anchor pricing discipline across Dubai and Abu Dhabi corridors, while their asset-heavy balance sheets tether rate structures to warehouse lease economics and shared labor pool utilization. This ownership pattern concentrates supply-side bargaining power among operators with multi-client campus capabilities, compressing margins for standalone warehousing specialists.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments contract logistics buyers by compliance certification and velocity requirements. Premium tiers attach to MOHAP-certified cold chain facilities and same-day e-commerce fulfillment, while economy tiers serve bulk consumer goods storage in Sharjah's lower-cost zones. Cost compression in standard-tier warehousing intensifies as Dubai South operators compete for fashion and electronics retail accounts with compressed order cutoffs. Healthcare distributors exhibit the least price sensitivity due to regulatory non-negotiability, whereas general merchandise retailers arbitrage aggressively across free zone and mainland licensing structures.
Supply Chain Analysis
Domestic-content mandates under the UAE's In-Country Value program are reshaping procurement patterns for warehouse automation equipment and cold chain infrastructure, pushing operators toward regional assembly partnerships. Supply concentrates in Germany for robotic goods-to-person systems, China for IoT sensor networks and autonomous mobile robots, and South Korea for battery storage systems serving EV parts logistics. Single-source vulnerability runs through European automation vendors with extended lead times for Jebel Ali corridor expansions. Distribution runs through multi-client campus models that aggregate freight forwarding, warehousing, and last-mile execution under unified service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UAE contract logistics rests on automation-driven labor efficiency gains and the premium-tier shift toward MOHAP-certified healthcare facilities. Operators capturing both dynamics simultaneously command superior unit economics.
For Market Incumbents: Deploy robotic goods-to-person systems across high-velocity consumer goods accounts to compress pick labor intensity per unit shipped. DHL Supply Chain's multi-client campus model near Jebel Ali demonstrates how shared equipment pools defray automation capital outlays across divergent seasonal patterns. Certification investment in redundant cold chain infrastructure captures healthcare distributor consolidation as MOHAP guidelines disqualify aging facilities. For New Entrants and Emerging Players: Free zone authority partnerships in Ras Al Khaimah Economic Zone offer build-to-suit positioning for regional distribution networks underserved by Dubai-Abu Dhabi corridor concentration. Northern emirates logistics infrastructure remains penetrable for operators willing to accept extended lease terms and lower throughput density. Automotive EV parts logistics presents a white-space target requiring hazardous materials handling expertise that incumbent generalists lack. For Investors and Strategic Acquirers: Regional conglomerate logistics arms are the most active acquirer in this space, seeking captive demand monetization and mall-hypermarket last-mile density. Long-term viability favors operators with dual licensing flexibility and automation deployment experience across the forecast horizon. Watch free zone incentive recalibration under federal corporate tax implementation as the inflection signal for outsourced versus captive logistics economics.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Client Campus Expansion | Jebel Ali Free Zone operators spread labor and equipment costs across healthcare and retail verticals. |
| Cold Chain Certification Investment | MOHAP-compliant facilities capture healthcare distributor consolidation as aging warehouses face disqualification. |
| Automation Technology Deployment | Robotic goods-to-person systems reduce pick headcount for Dubai South e-commerce fulfillment accounts. |
| Dual Licensing Structure Optimization | Mainland and free zone permits allow customs duty deferral arbitrage across Dubai South corridors. |
| Northern Emirates Geographic Expansion | Ras Al Khaimah Economic Zone offers first-mover build-to-suit positioning for regional distribution networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with logistics operators, healthcare procurement managers, retail supply chain directors, and free zone authority representatives with secondary validation. Secondary sources included Federal Customs Authority trade documentation, MOHAP pharmaceutical storage guideline filings, Dubai South and Jebel Ali Free Zone operator disclosures, and customs deferral structure analyses. Bottom-up facility capacity modeling and top-down sectoral demand aggregation triangulated market sizing across service type and end-user segments.
Historical reference periods anchored demand trajectory assumptions across the analysis window, with projection horizons extending through infrastructure build-out cycles and regulatory implementation phases. Segmentation dimensions modeled encompassed service configuration, end-use vertical, technology deployment maturity, and distribution channel structure. CAGRs derived from facility expansion pipelines, automation capital expenditure disclosures, and e-commerce fulfillment velocity requirements. Cold chain certification mandates and dual licensing regime flexibility served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to free zone incentive recalibration, federal corporate tax implementation effects on outsourcing economics, and cross-border customs friction under Federal Customs Authority oversight. Forecasts reflect documented assumptions regarding automation adoption curves and healthcare regulatory compliance timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Ocean Freight Software Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
North America Refrigerated Container Shipping Market