
 Colombia Freight and Logistics Market | 2026-2036
Colombia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Freight and Logistics Market Outlook
Colombia's Pacific port expansion at Buenaventura is reconfiguring maritime throughput capacity for containerized agricultural exports. Grupo TCC leverages its nationwide ground network to dominate domestic less-than-truckload services. Coordinadora Mercantil S.A. anchors temperature-controlled distribution for pharmaceutical and perishable supply chains. DSV competes in project cargo and international forwarding through its integrated air-sea offerings.
Colombia freight and logistics encompasses the physical movement, storage, and information management of goods across road, rail, air, and waterway modes, typically involving cargo handling above 500 kilograms with multimodal bill-of-lading documentation. The sector serves as the circulatory infrastructure for national trade, connecting production zones to consumption centers and export terminals through coordinated carrier and warehouse operations. Transportation services absorb the dominant share of revenue as highway freight governs domestic connectivity, while last-mile delivery represents the fastest-expanding segment as e-commerce order frequency reshapes urban distribution economics. Warehousing margins concentrate in cold-chain facilities serving Bogotá's pharmaceutical manufacturing and Cundinamarca's flower export zones.
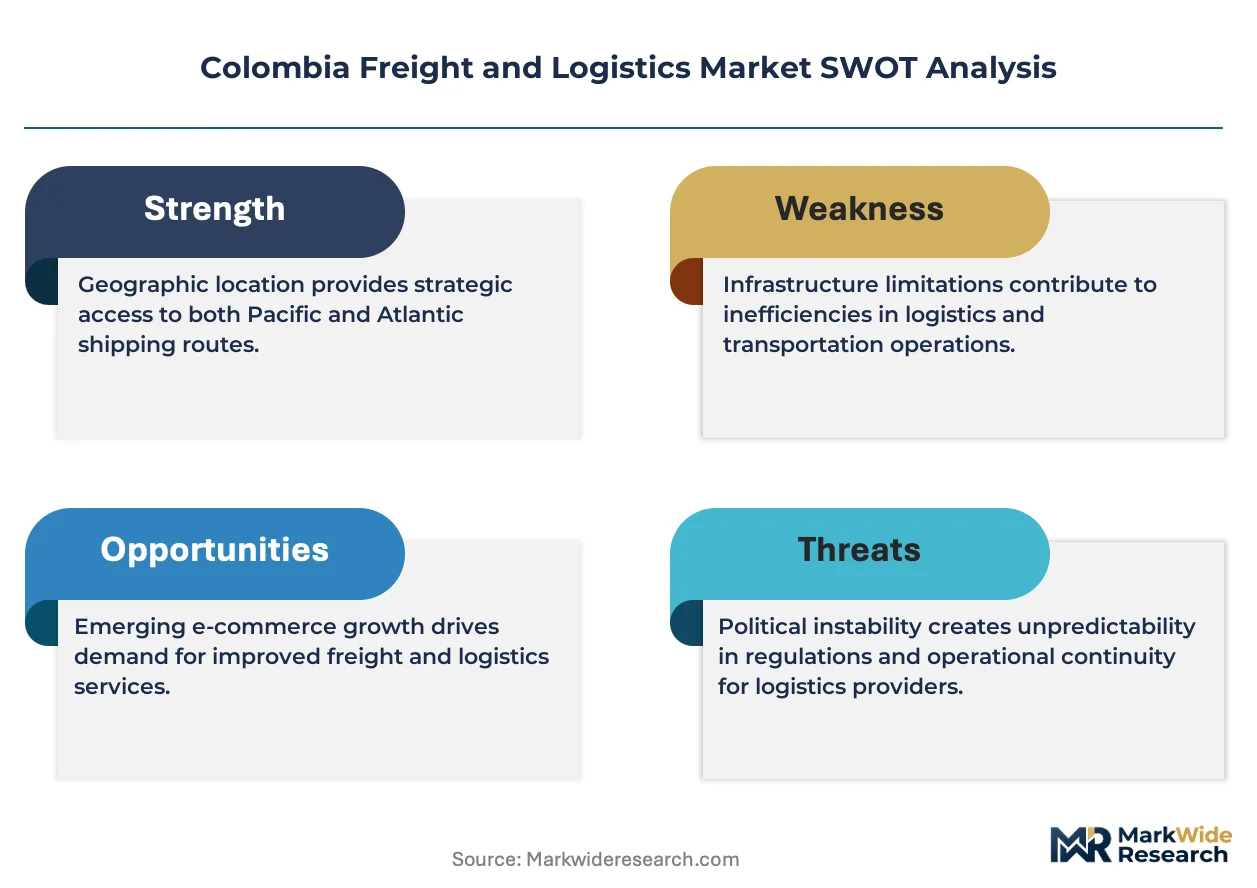
The Colombian Ministry of Transport enforces axle-load regulations and concession standards for 4G/5G highway infrastructure, directly conditioning fleet investment cycles and route economics for carriers. BIS-equivalent technical norms govern container safety and cross-border documentation alignment with Andean Community protocols, shaping market access for international forwarders. ANTT regulates intermodal tariffs and terminal access pricing, influencing cost structures for logistics operators serving Pacific and Caribbean corridors. Stakeholders must monitor infrastructure concession timelines and regulatory harmonization with Ecuador and Peru to anticipate lane capacity and border clearance efficiencies.
Market Dynamics
The Colombian Ministry of Transport's 4G and 5G highway concession programs are compressing transit times between Bogotá, Medellín, and Cali, forcing carriers to rebalance fleet deployment around new corridor economics rather than legacy route structures.
Growth Catalysts
- E-commerce fulfillment infrastructure:Warehouse clusters along the Andean corridor are absorbing demand from cross-border digital retail, creating dedicated last-mile nodes in Cundinamarca and Valle del Cauca.
- 4G/5G highway modernization:The Colombian government's infrastructure concessions are raising axle-load limits and reducing Bogotá-Buenaventura transit times, expanding catchment zones for Pacific port routing.
- Temperature-controlled pharmaceutical distribution:Bogotá's vaccine and generics manufacturing base is generating specialized cold-chain requirements that command premium warehousing margins.
Market Restraints
- Fuel cost volatility:Diesel price exposure dominates carrier operating economics, with limited hedging instruments available in Colombian peso terms.
- Pacific port concentration risk:Overreliance on Buenaventura for containerized agricultural exports creates vulnerability to landslide-related closure events on the connecting highway corridor.
- Andean Community documentation friction:Cross-border harmonization gaps with Ecuador and Peru generate customs delays that erode just-in-time service commitments.
Strategic Opportunities
- Amazon basin connectivity gaps:Leticia and southeastern Colombia remain underserved by integrated logistics networks, offering first-mover positioning for regional distribution hubs.
- Rail-sea intermodal revival:The Fenoco corridor between Bogotá and Caribbean ports presents underutilized capacity for bulk agricultural and mining exports.
- Green freight incentives:Colombia's carbon-neutral transport pilot programs are creating preferential lane access and toll reductions for LNG and electric fleet operators.
Industry Challenges
- Certified cold-chain technician scarcity:GDP-compliant pharmaceutical handling requires specialized training that outpaces current vocational program output in Cundinamarca.
- Legacy fleet telematics integration:Smaller carriers face capital barriers to retrofitting vehicles for real-time cargo monitoring mandated by major exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Freight and Logistics Market |
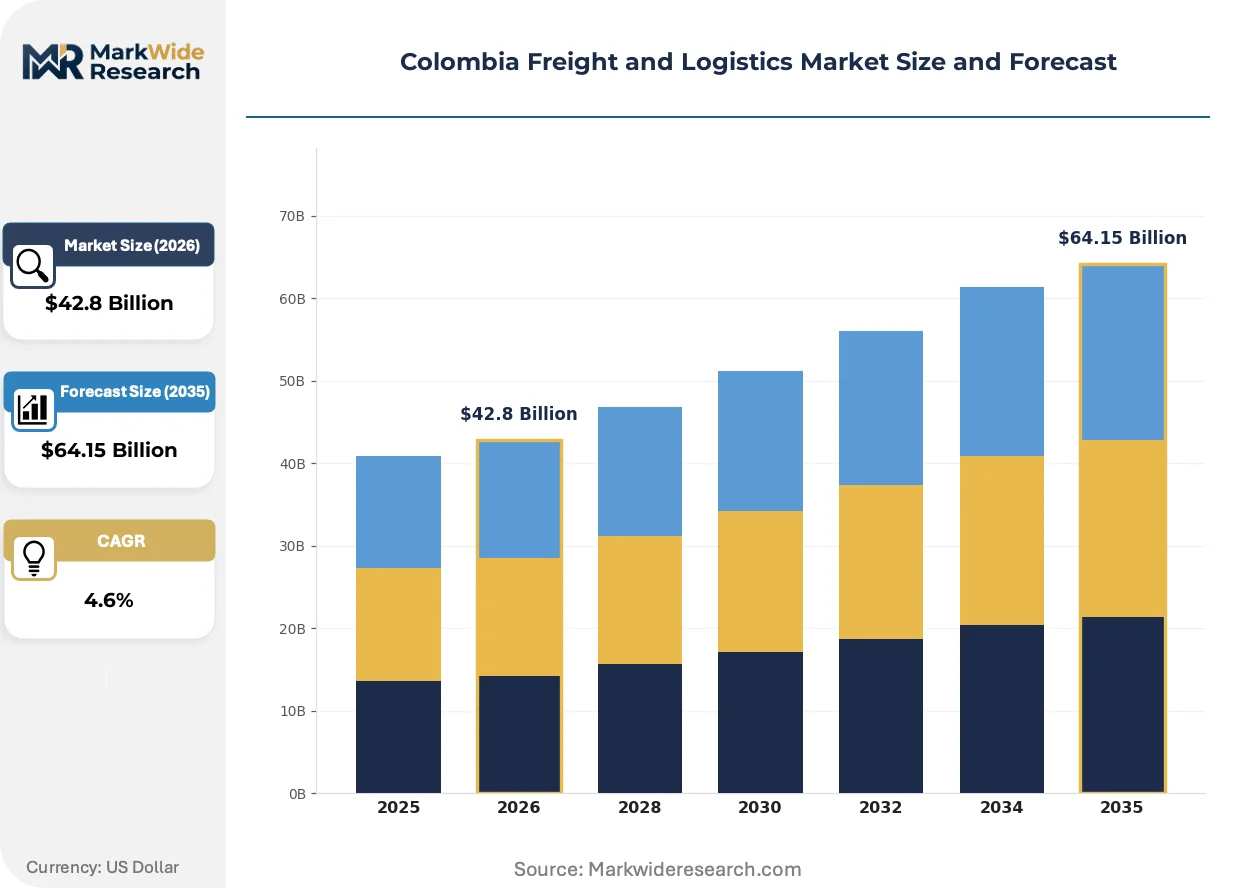
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Last-Mile Delivery Technology: IoT, Cloud Computing, Blockchain, Automation End User: Retail, Manufacturing, E-commerce, Agriculture Distribution Channel: Direct Sales, Online Platforms, Third-Party Logistics, Brokers |
| Companies Covered | Transportes Vigia Sociedad Por Acciones Simplificada S.A.S., Grupo TCC, Coordinadora Mercantil S.A., ABC Cargo Logistic S.A.S., Grupo Logístico Especializado, Operadores Logisticos De Carga OPL Carga S.A.S., Transportes Sanchez Polo S.A., DSV, TCC S.A.S., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Freight and Logistics Market Strategic Shifts
Digital freight matching platforms and automated warehouse systems are compressing coordination costs across Colombia's historically fragmented carrier base, while regulatory pressure on emissions and safety is accelerating equipment replacement cycles.
Telematics-enabled dynamic routing is collapsing the information asymmetry between shippers and available truck capacity. Mid-sized agricultural exporters in the Coffee Triangle are adopting these platforms fastest, shifting spot-market pricing from phone-based brokerage to algorithmic matching. The structural consequence is compressing dispatch margins for traditional freight forwarders who lack proprietary load-matching technology.
The Colombian Ministry of Transport's updated axle-load enforcement protocols are mandating on-board weighing systems for interstate operations. This regulatory tightening is forcing fleet operators to retire overweight vehicles prematurely or face route suspension penalties. Heavy-haul carriers serving mining and construction sectors in Antioquia are responding fastest, retrofitting tractors with certified scale systems to maintain concession lane access.
Shippers are consolidating vendor relationships around integrated service providers capable of managing temperature excursions across multimodal handoffs. Pharmaceutical distributors in Bogotá are replacing fragmented cold-chain segments with single-custody contracts that bundle warehousing, ground transport, and last-mile delivery. This consolidation pattern is most visible in Cundinamarca's flower export zones, where traceability requirements from European supermarkets are driving preference for vertically capable operators.
Colombia Freight and Logistics Market Segmentation
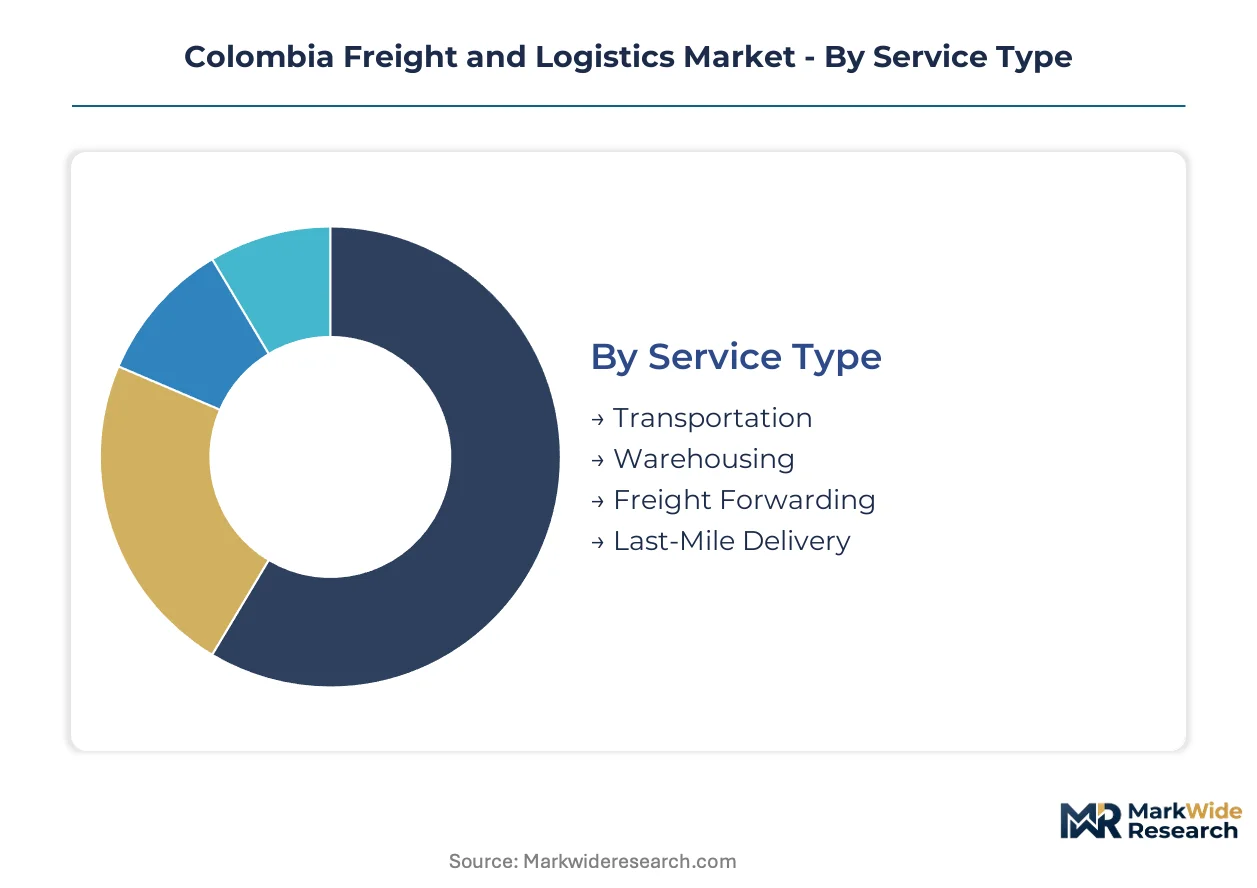
Segmentation in Colombia's freight and logistics market reveals how service specialization, technology adoption, and channel configuration determine competitive positioning. Each dimension captures distinct margin structures and capital intensity requirements that shape operator strategy across the Andean corridor.
Service Type:
Mature highway-based segments dominate revenue concentration while emerging integrated offerings capture premium pricing from pharmaceutical and e-commerce clients.
- Transportation:Road freight governs domestic connectivity through the Bogotá–Medellín–Cali triangle, absorbing the dominant revenue share as carriers rebalance fleet deployment around 4G/5G corridor economics. Demand concentrates in Cundinamarca and Valle del Cauca where axle-load enforcement is tightening fleet replacement cycles.
- Warehousing:Temperature-controlled facilities command premium margins serving Bogotá's pharmaceutical manufacturing and flower export zones. Cold-chain GDP compliance requirements are consolidating vendor relationships around vertically capable operators in Cundinamarca.
- Freight Forwarding:International coordination services manage multimodal handoffs through Buenaventura and Caribbean terminals.
- Last-Mile Delivery:Urban distribution nodes are expanding fastest as e-commerce order frequency reshapes fulfillment economics in major metropolitan zones.
Transportation retains volume leadership; last-mile delivery holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive automation investments from accessible cloud-based coordination tools that mid-sized carriers adopt fastest.
- IoT:On-board weighing systems and real-time cargo monitoring are becoming mandatory for interstate operations under updated Ministry of Transport protocols. Agricultural exporters in the Coffee Triangle are deploying telematics-enabled dynamic routing to compress dispatch margins.
- Cloud Computing:Digital freight matching platforms collapse information asymmetry between shippers and available truck capacity. Mid-sized carriers leverage algorithmic load-matching to bypass traditional phone-based brokerage structures.
- Blockchain:Documentation integrity solutions address cross-border harmonization gaps with Ecuador and Peru.
- Automation:Warehouse robotics and automated sorting systems concentrate in e-commerce fulfillment clusters along the Andean corridor.
Cloud computing retains volume leadership; automation holds the steepest expansion curve.
End User:
Application-driven demand patterns separate high-frequency retail replenishment from project-based agricultural and manufacturing logistics.
- Retail:Omnichannel distribution networks require synchronized inventory positioning across urban and regional markets. Domestic consumption centers in Bogotá and Medellín are driving consolidation around integrated service providers.
- E-commerce:Cross-border digital retail is absorbing dedicated fulfillment infrastructure in Cundinamarca and Valle del Cauca. Warehouse clusters are emerging as distinct last-mile nodes with specialized sorting capabilities.
- Manufacturing:Just-in-time component flows connect production zones to assembly operations.
- Agriculture:Containerized exports through Buenaventura face vulnerability to landslide-related corridor disruptions.
Retail retains volume leadership; e-commerce holds the steepest expansion curve.
Distribution Channel:
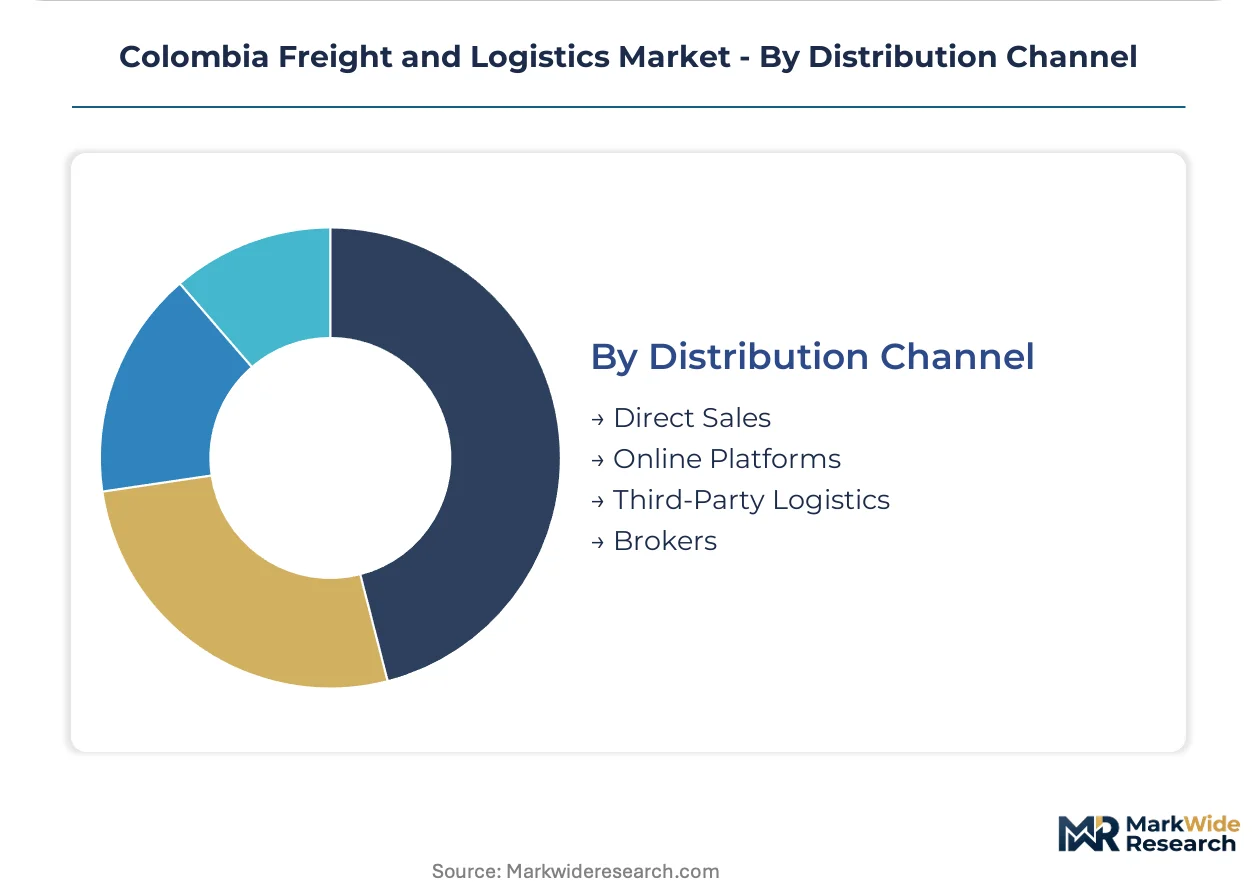
Customer type and relationship depth determine channel economics, from transactional broker arrangements to embedded third-party partnerships.
- Direct Sales:Large shippers in mining and construction sectors in Antioquia negotiate dedicated capacity contracts with heavy-haul carriers. Direct relationships enable customized equipment specifications and priority lane access.
- Third-Party Logistics:Pharmaceutical distributors in Bogotá are replacing fragmented cold-chain segments with single-custody contracts bundling warehousing, ground transport, and last-mile delivery.
- Online Platforms:Digital marketplaces for spot freight are compressing coordination costs across historically fragmented carrier bases.
- Brokers:Traditional freight intermediaries face margin pressure from algorithmic matching platforms.
Third-party logistics retains volume leadership; online platforms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Buenaventura Pacific port expansion anchors Colombia's maritime throughput capacity, reshaping containerized agricultural export corridors while the 4G/5G highway network compresses transit economics across the Andean corridor.
Bogotá–Cundinamarca
Pharmaceutical manufacturing clusters and flower export zones drive specialized cold-chain demand in this central region. The Colombian Ministry of Transport's axle-load enforcement protocols mandate on-board weighing systems for interstate carriers serving Bogotá's distribution hubs. Cundinamarca's warehousing clusters are consolidating around vertically integrated operators capable of GDP-compliant temperature control.
Valle del Cauca
Sugar and coffee exports through Buenaventura generate heavy bulk freight flows along the Pacific corridor. ANTT-regulated intermodal tariffs influence terminal access pricing for carriers routing through Cali's logistics nodes. The Palmira–Yumbo industrial corridor is absorbing dedicated e-commerce fulfillment infrastructure as cross-border digital retail expands.
Antioquia
Mining and construction equipment movements dominate heavy-haul demand in Medellín's hinterland. Colombia's updated concession standards for 4G highways are raising fleet replacement requirements for carriers serving Rionegro's manufacturing zones. The Medellín–Bogotá corridor is experiencing the steepest transit time compression from infrastructure modernization.
Caribbean Coast
Container traffic through Cartagena and Barranquilla competes with Pacific routing for agricultural exports. The Fenoco rail corridor between Bogotá and Caribbean ports presents underutilized bulk capacity for coal and grain movements. Santa Marta's port expansion is attracting cold-chain investments for banana and avocado exports.
Amazon Basin
Leticia and southeastern Colombia remain structurally underserved by integrated logistics networks. Colombia's carbon-neutral transport pilot programs are testing LNG fleet incentives for operators willing to establish regional distribution hubs. The lack of paved connectivity to Brazil and Peru perpetuates air freight dependence for perishable trade.
Colombia Freight and Logistics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. Colombia's freight market structures around three tiers: nationwide ground networks with dedicated fleet assets, temperature-controlled specialists serving pharmaceutical verticals, and digital freight platforms collapsing spot-market coordination costs. Strategic moves concentrate on fleet modernization for axle-load compliance, warehouse automation for e-commerce throughput, and single-custody cold-chain contracts bundling multimodal services.
Among domestic carriers, Transportes Vigia Sociedad Por Acciones Simplificada S.A.S. and Grupo TCC exemplify the integrated ground network archetype with nationwide less-than-truckload coverage. Coordinadora Mercantil S.A. occupies a position within the temperature-controlled tier, anchoring specialized distribution for perishable and pharmaceutical supply chains. DSV represents the international forwarding segment, competing through air-sea integration for project cargo movements.
| Leading Market Players |
|---|
| Transportes Vigia Sociedad Por Acciones Simplificada S.A.S. |
| Grupo TCC |
| Coordinadora Mercantil S.A. |
| ABC Cargo Logistic S.A.S. |
| Grupo Logístico Especializado |
| Operadores Logisticos De Carga OPL Carga S.A.S. |
| Transportes Sanchez Polo S.A. |
| DSV |
| TCC S.A.S. |
| Others |
Value Chain & Pricing Dynamics
Buenaventura's port capacity expansion and Pacific corridor modernization are compressing freight rates for agricultural exporters while concentrating pricing power among carriers with axle-load compliant fleets serving the Andean corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs carrier contracts, with premium tiers capturing cold-chain pharmaceutical shipments from Bogotá's manufacturing base and economy tiers serving bulk agricultural spot markets. Price differentiation hinges on GDP certification status and real-time cargo monitoring capability, with uncertified operators facing rate compression. Pricing pressure stems from digital freight matching platforms collapsing dispatch margins for traditional phone-based brokers. E-commerce fulfillment clients show lowest price sensitivity due to service-level requirements, while coffee exporters in the Coffee Triangle exhibit highest sensitivity to per-kilogram freight differentials.
Supply Chain Analysis
Grupo TCC and Coordinadora Mercantil S.A. anchor domestic contract logistics capacity, with international coordination resting on DSV's air-sea integration and regional freight forwarders. Geographic supply concentration centers on Colombia's Bogotá–Medellín–Cali logistics triangle, with secondary nodes in Cartagena and Barranquilla. Diesel fuel, specialized reefer equipment, and telematics hardware constitute critical input dependencies. Single-source vulnerability concentrates in Buenaventura's landslide-prone highway corridor connecting Pacific port throughput to interior production zones. Distribution runs through third-party logistics providers bundling warehousing, ground transport, and last-mile delivery for pharmaceutical and e-commerce verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's freight market is entering a cyclical recovery phase as 4G/5G highway infrastructure completion compresses transit economics and triggers fleet replacement investment cycles.
For Market Incumbents: Build switching-cost moats through proprietary telematics platforms that embed shippers in real-time cargo monitoring ecosystems. Invest in GDP-compliant cold-chain certification to capture pharmaceutical margin premiums before vocational training output catches up with technician demand. Defend against digital freight platforms by consolidating fragmented carrier relationships into single-custody contracts bundling multimodal services. For New Entrants and Emerging Players: Establish a beachhead in Amazon basin connectivity gaps where Leticia and southeastern Colombia remain structurally underserved by integrated networks. Target green freight incentives through LNG fleet deployment to secure preferential lane access and toll reductions under carbon-neutral transport pilot programs. Lead with rail-sea intermodal offerings on the underutilized Fenoco corridor to differentiate from highway-dependent incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically capable operators with temperature-controlled assets and multimodal coordination platforms over pure-play highway carriers. Long-term viability hinges on exposure to e-commerce fulfillment infrastructure expansion in Cundinamarca and Valle del Cauca. Monitor ANTT regulatory announcements on intermodal tariff structures as the inflection signal for margin compression or expansion across Pacific and Caribbean corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization for Axle-Load Compliance | Colombia's Ministry of Transport protocols mandate on-board weighing systems for interstate lane access. |
| Cold-Chain GDP Certification Investment | Bogotá's pharmaceutical manufacturing base commands premium margins for certified temperature-controlled distribution. |
| E-Commerce Fulfillment Node Expansion | Warehouse clusters in Palmira–Yumbo absorb cross-border digital retail demand along the Andean corridor. |
| Rail-Sea Intermodal Capacity Activation | Fenoco corridor between Bogotá and Caribbean ports offers underutilized bulk agricultural export capacity. |
| Digital Freight Matching Platform Deployment | Telematics-enabled dynamic routing compresses information asymmetry between Coffee Triangle shippers and available truck capacity. |
Study Parameters
Operator-level perspectives from fleet managers, warehouse operators, pharmaceutical supply chain directors, and e-commerce fulfillment executives anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through ANTT tariff filings, Colombian Ministry of Transport concession documentation, and customs trade flow records. Bottom-up carrier capacity assessments and top-down national freight volume estimates were triangulated to constrain forecast ranges.
Scenario-bracketing around infrastructure completion timelines, fuel price volatility bands, and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology adoption tier, end-user vertical, and distribution channel configuration. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce penetration rates and pharmaceutical export growth assumptions.
Stress conditions across diesel price spikes, Buenaventura corridor closure events, and Andean Community documentation friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about 4G/5G highway completion schedules and cold-chain technician training program expansion. Cross-checking against ANTT's published intermodal tariff benchmarks and sector-specific freight indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Unit Load Device Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market