
 Digital Freight Forwarding Market | 2026-2036
Digital Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Freight Forwarding Market Analysis
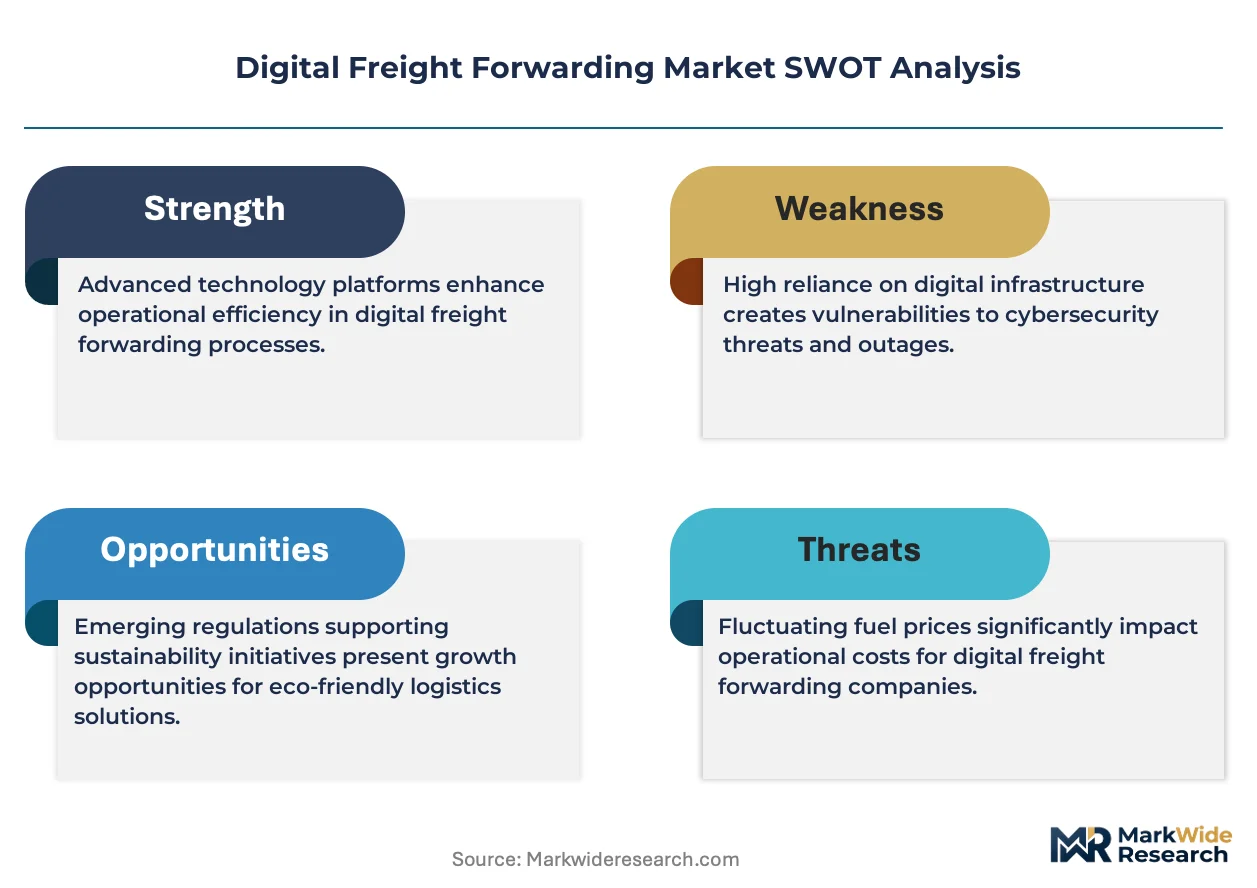
EU Green Deal emissions disclosure rules for transport logistics are rebalancing the cost-of-entry calculus for digital freight platforms. Flexport leverages its integrated customs brokerage and ocean freight visibility stack to anchor trans-Pacific lane dominance. Forto competes through proprietary carbon accounting tools that map multimodal emissions per shipment. CH Robinson Worldwide sustains its position via controlled access to North American truckload capacity through its Navisphere platform.
Digital freight forwarding denotes the automation of cargo booking, documentation, and tracking through cloud-native software platforms that integrate carrier APIs, customs databases, and real-time container telemetry. These systems eliminate manual bill-of-lading processing while providing predictive ETAs based on vessel AIS signals and port congestion algorithms. Freight consolidation services currently occupy the largest margin pool as shippers prioritize load optimization over standalone customs clearance. Machine learning applications in demand forecasting and dynamic routing represent the fastest-expanding technology segment, displacing static annual contracting models. API integration across carrier networks remains structurally underdeveloped relative to passenger aviation, creating interoperability bottlenecks that middleware specialists exploit.
FERC interstate commerce oversight and EPA emissions benchmarking shape US domestic freight platform compliance requirements, while ECHA REACH documentation obligations extend digital chain-of-custody mandates into European chemical logistics. ISO 14064 carbon verification standards are becoming de facto prerequisites for tender participation in EU public procurement lanes. Stakeholders must monitor which regulatory jurisdiction's audit requirements their platform architecture satisfies before committing to single-territory software deployments.
Market Dynamics
Container tracking APIs and real-time vessel telemetry are compressing documentation cycles from days to hours, forcing legacy forwarders to rebuild their technology stacks or exit trans-Pacific lanes entirely.
Growth Catalysts
- EU Green Deal emissions mandates:Transport logistics operators must now maintain digital audit trails for carbon disclosure, accelerating SaaS procurement for compliance automation across Hamburg-Rotterdam corridor traffic.
- E-commerce fulfillment velocity requirements:Direct-to-consumer brands demand predictive ETAs and exception management, pulling container visibility platforms into standard procurement stacks.
- Machine learning in demand forecasting:Dynamic routing algorithms are displacing static annual contracting models, enabling forwarders to optimize multimodal lane selection in near-real-time.
Market Restraints
- API interoperability gaps:Carrier network integration remains structurally underdeveloped relative to passenger aviation, creating bottlenecks that middleware specialists exploit at premium pricing.
- Legacy system replacement costs:Bill-of-lading automation requires full ERP reconfiguration, with capital intensity deterring mid-tier forwarders from platform migration.
- Concentrated carrier pricing power:Ocean alliance consolidation on Asia-Europe lanes limits forwarder margin capture even as digital tools reduce operational overhead.
Strategic Opportunities
- ISO 14064 carbon verification:Tender participation in EU public procurement lanes now requires certified emissions documentation, creating white space for platforms with embedded verification workflows.
- Freight consolidation optimization:Load pooling algorithms remain underpenetrated in chemical logistics, where ECHA REACH documentation obligations extend chain-of-custody requirements into multimodal coordination.
- Customs brokerage convergence:Integrated visibility and clearance stacks are overtaking standalone offerings as shippers prioritize single-platform accountability for delayed-release penalties.
Industry Challenges
- Maritime data science talent scarcity:Vessel AIS signal interpretation and port congestion algorithm development require specialized skill sets concentrated in Rotterdam and Singapore labor pools.
- FERC interstate commerce compliance:US domestic freight platforms must maintain dual architecture standards for EPA emissions benchmarking alongside state-level weight enforcement variations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Freight Forwarding Market |
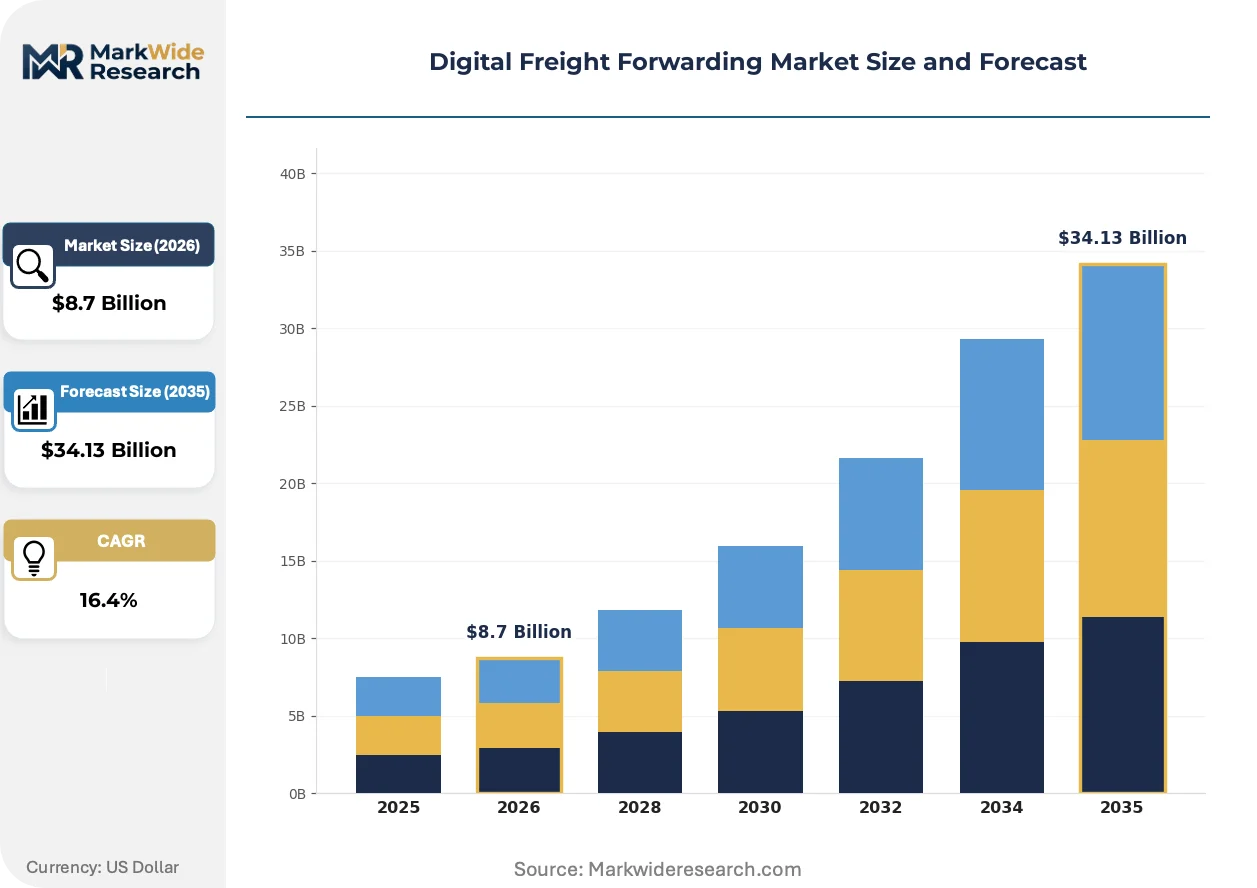
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Customs Brokerage, Freight Consolidation, Risk Management, Warehousing Technology: Blockchain, Machine Learning, IoT, API Integration End User: E-commerce, Manufacturing, Retail, Automotive Delivery Model: Door-to-Door, Port-to-Port, Intermodal, Direct Shipping |
| Companies Covered | Flexport, Twill, Forto, Cello Square, InstaFreight, Freightos, Zencargo, Shypple, CH Robinson Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Freight Forwarding Market Emerging Trajectories
Real-time container telemetry and predictive port analytics are compressing the information asymmetry that historically sustained forwarder margins, while regulatory emissions disclosure is embedding software deeper into compliance workflows.
Blockchain-enabled bill-of-lading verification is overtaking paper-based documentation in high-value cargo lanes. Pharmaceutical and electronics shippers in the Netherlands and Germany are piloting smart contract settlement to reduce letter-of-credit processing friction. This compression of documentary trade cycles is enabling faster inventory turns for just-in-time manufacturers.
REACH documentation obligations from ECHA are extending digital chain-of-custody mandates into European chemical logistics. Forwarders must now maintain auditable records across multimodal handoffs, with non-compliance triggering tender exclusion. Specialty chemical producers are responding by procuring platforms with embedded substance-tracking modules.
Shippers are unbundling freight procurement from annual contracting cycles toward continuous spot-market participation with pre-negotiated API rate caps. Apparel and consumer electronics brands in the US and Germany are driving this shift, prioritizing lane flexibility over volume commitments. Forwarders are responding with dynamic pricing engines that adjust to vessel capacity fluctuations within 24-hour windows.
Digital Freight Forwarding Market Segmentation
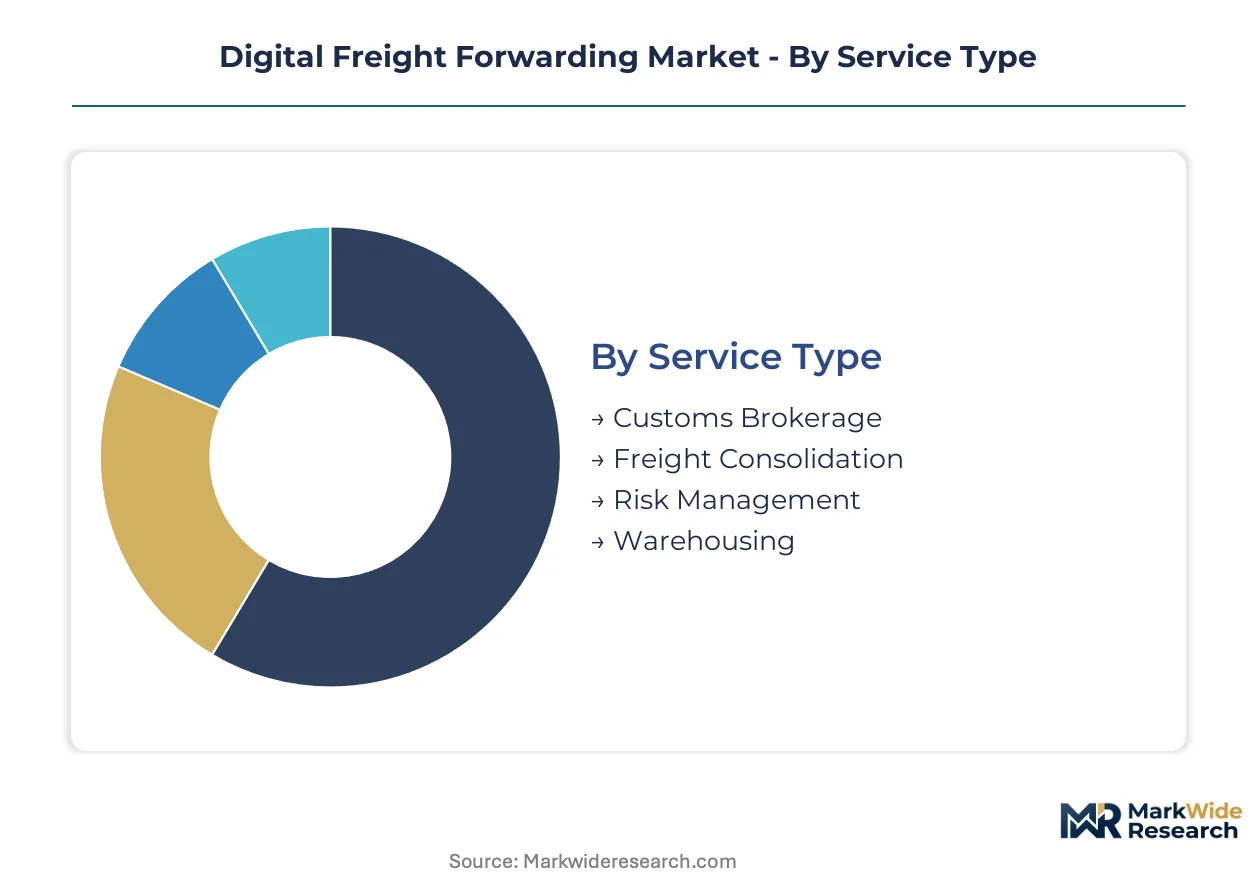
Digital freight forwarding platforms must align service architecture with distinct operational workflows across customs, consolidation, and risk functions. Technology deployment varies sharply by segment, with machine learning and API integration commanding premium positioning against legacy blockchain pilots. End-user procurement patterns diverge significantly between e-commerce velocity requirements and automotive just-in-sequence reliability demands.
Service Type:
Volume concentration sits with freight consolidation, while premium margin capture favors integrated customs brokerage stacks.
- Freight Consolidation:Load pooling algorithms optimize container utilization across multiple shippers, reducing per-unit transport costs through algorithmic matching of compatible cargo profiles. Demand concentrates among mid-market e-commerce exporters in Germany and the Netherlands seeking to bypass minimum quantity commitments from ocean carriers. EU Green Deal emissions disclosure mandates accelerate SaaS procurement for consolidation platforms with embedded carbon allocation per shipper share.
- Customs Brokerage:Automated tariff classification and duty drawback processing integrate directly with port community systems and single-window interfaces. Trans-Pacific apparel and electronics shippers in the US demand predictive release timelines to minimize demurrage exposure at Los Angeles and Long Beach terminals. FERC interstate commerce oversight and CBP ACE system requirements shape platform compliance architecture for cross-border truckload movements.
- Risk Management:Cargo insurance placement and supply chain disruption hedging through parametric weather and geopolitical triggers.
- Warehousing:Digital yard management and inventory positioning synchronized with ocean vessel ETAs via AIS signal integration.
Mature deployment sits with freight consolidation. Newer deployment is concentrated in risk management parametric products.
Technology:
API integration commands the largest procurement budgets, while machine learning applications are climbing the fastest among logistics technology investments.
- API Integration:Carrier network connectivity through standardized data exchange protocols enables real-time rate quoting and booking confirmation across ocean, air, and truckload modes. Rotterdam and Hamburg corridor forwarders prioritize middleware procurement to bridge interoperability gaps between proprietary carrier systems. Port congestion algorithms and vessel schedule reliability scores flow through these integration layers to power dynamic routing decisions.
- Machine Learning:Demand forecasting models ingest historical trade lane patterns, seasonal inventory cycles, and macroeconomic indicators to optimize multimodal lane selection. US retail and automotive shippers deploy these tools to displace static annual contracting with continuous spot-market participation. Predictive ETAs based on vessel speed, port turnaround times, and weather routing compress information asymmetry between forwarders and cargo owners.
- IoT:Container-mounted sensors transmitting location, temperature, and shock data through satellite and cellular networks.
- Blockchain:Distributed ledger documentation for bill-of-lading verification and smart contract settlement in high-value pharmaceutical and electronics cargo.
Established deployment sits with API integration. Emerging deployment is concentrated in machine learning demand forecasting.
End User:
E-commerce shippers drive platform volume, while automotive manufacturers impose the most stringent reliability and traceability requirements.
- E-commerce:Direct-to-consumer brands require predictive delivery windows and exception management for cross-border parcel and LTL movements. German and US apparel exporters prioritize platforms with embedded customs duty calculation and landed cost transparency for consumer checkout integration. Velocity requirements pull container visibility tools into standard procurement stacks alongside warehouse management systems.
- Automotive:Just-in-sequence production schedules demand sub-hour delivery precision for component shipments from tier suppliers to assembly plants. OEMs in Germany and the US mandate EDI integration and VDA 4913 message standards for inbound logistics coordination. ISO 14064 carbon verification requirements for EU public procurement lanes extend to automotive supply chain emissions documentation.
- Manufacturing:Industrial machinery and raw materials procurement with emphasis on project cargo and breakbulk coordination.
- Retail:Seasonal inventory positioning and promotional surge capacity with focus on trans-Pacific replenishment lanes.
Scaled deployment sits with e-commerce. Precision-critical deployment is concentrated in automotive.
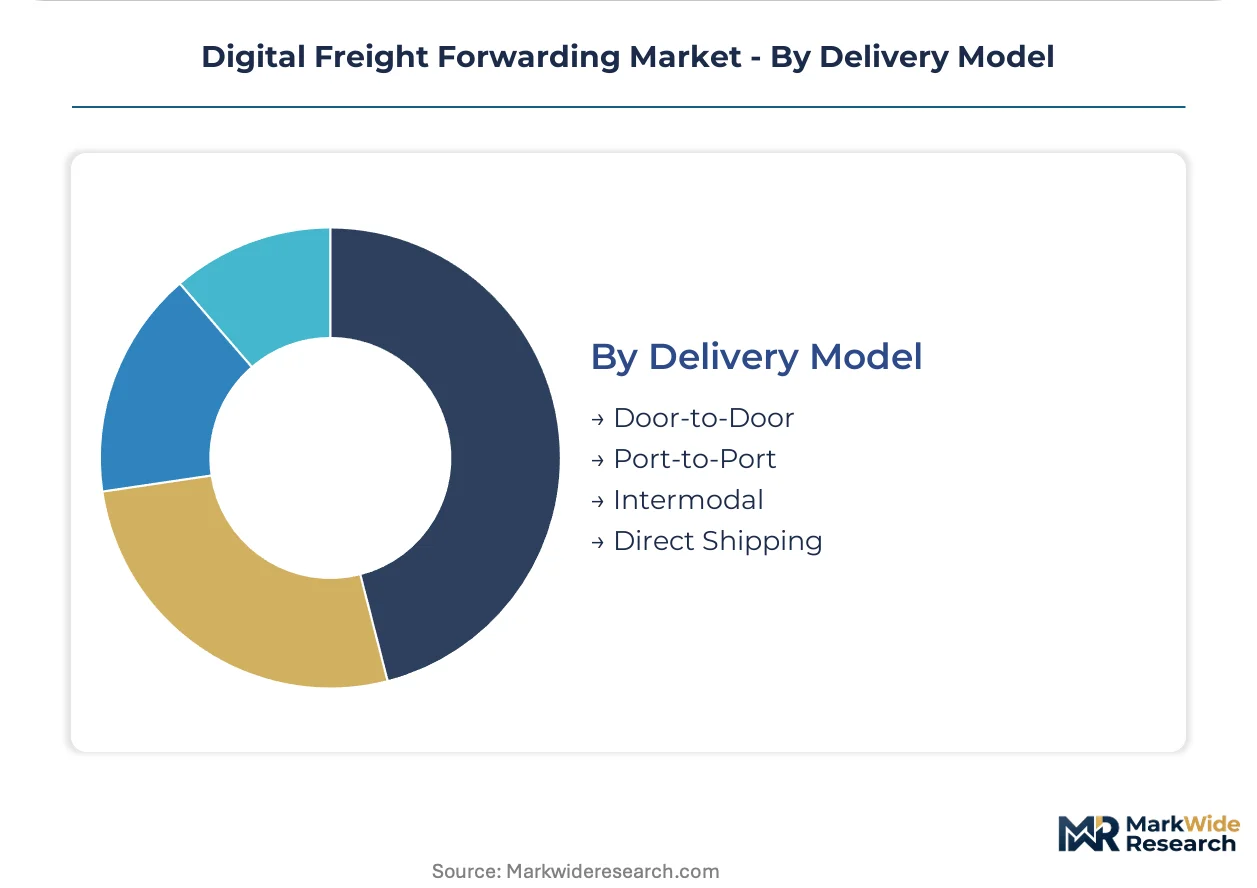
Delivery Model:
Door-to-door contracting captures premium pricing, while intermodal coordination is gaining share fastest among sustainability-focused procurement.
- Door-to-Door:Single-contract accountability for pickup, line-haul, customs clearance, and final delivery eliminates shipper coordination burden across multiple service providers. US and German mid-market exporters favor this model to avoid demurrage and detention penalty disputes. Integrated visibility stacks with predictive ETAs at each handoff point anchor competitive positioning for door-to-door specialists.
- Intermodal:Rail-truck-ocean coordination optimizes carbon intensity per ton-mile through mode shift at Hamburg, Rotterdam, and Chicago terminals. EU Green Deal emissions disclosure mandates accelerate procurement of platforms with embedded multimodal carbon accounting per shipment. Chemical logistics operators in Germany deploy intermodal solutions to satisfy ECHA REACH documentation obligations across modal handoffs.
- Port-to-Port:Traditional ocean freight contracting with shipper responsibility for pre-carriage and on-carriage arrangements.
- Direct Shipping:Dedicated vessel charter or block space agreements for high-volume, repetitive lane requirements.
Contractual maturity sits with door-to-door. Sustainability-driven deployment is concentrated in intermodal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Netherlands and UAE accelerate platform concentration by offering VAT deferral and customs simplification for logistics technology firms establishing European and Gulf hubs.
Germany
Hamburg-Rotterdam corridor traffic drives SaaS procurement for intermodal coordination as chemical exporters automate ECHA REACH documentation across modal handoffs. EU Green Deal emissions disclosure mandates force forwarders to retrofit digital audit trails for carbon verification. The Port of Hamburg anchors container visibility platform deployments serving automotive just-in-sequence supply chains.
United States
Trans-Pacific apparel and electronics shippers demand predictive release timelines to minimize demurrage exposure at Los Angeles and Long Beach terminals. FERC interstate commerce oversight and EPA emissions benchmarking shape domestic freight platform compliance requirements for cross-border truckload movements. Chicago rail-truck terminals concentrate intermodal coordination technology investments.
Netherlands
Rotterdam's port community systems enable real-time carrier API integration that bridges interoperability gaps between proprietary ocean carrier networks. EU Green Deal mandates accelerate procurement of platforms with embedded multimodal carbon accounting per shipment. Eindhoven's pharmaceutical and electronics clusters pilot blockchain-enabled bill-of-lading verification.
China
Dual carbon goals from MEE drive demand for emissions tracking platforms among export manufacturers facing EU border adjustment pressures. Yangtze River Delta container terminals deploy vessel AIS signal integration for predictive ETAs serving e-commerce fulfillment velocity requirements. Shanghai's free trade zone concentrates customs brokerage automation for cross-border direct-to-consumer brands.
Singapore
Maritime data science talent scarcity concentrates vessel AIS signal interpretation and port congestion algorithm development in this labor pool. The Maritime and Port Authority's digital port initiatives mandate API standardization across carrier networks calling at PSA terminals. Jurong Island chemical logistics operators deploy multimodal chain-of-custody tracking for hazardous cargo movements.
Digital Freight Forwarding Market Vendor Landscape
United States technology platforms anchor one tier; European specialists hold differentiated positioning through carbon accounting integration. Market structure shows moderate consolidation around integrated visibility stacks, with fragmentation persisting in regional middleware providers. Three archetypes dominate: customs brokerage convergence players, freight consolidation optimizers, and sustainability-focused carbon verification platforms. Competitive moves center on API interoperability partnerships and vertical integration into controlled truckload capacity access.
Within the integrated visibility tier, Flexport and CH Robinson Worldwide exemplify trans-Pacific lane dominance through customs brokerage and ocean freight technology stacks. Forto occupies a position among European specialists leveraging proprietary carbon accounting tools for multimodal emissions mapping per shipment. These three companies represent the strategic divergence between North American scale platforms and European compliance-focused architectures.
| Leading Market Players |
|---|
| Flexport |
| Twill |
| Forto |
| Cello Square |
| InstaFreight |
| Freightos |
| Zencargo |
| Shypple |
| CH Robinson Worldwide |
| Others |
Supply Flow & Price Mechanics
EU Green Deal emissions disclosure mandates gate access to premium-tier digital freight contracts, restricting qualified supply to platforms with ISO 14064 carbon verification while compressing margins for non-compliant forwarders locked out of Hamburg-Rotterdam corridor procurement lanes.
Pricing Analysis
Short lead-time premiums dominate digital freight pricing, with predictive ETA capabilities commanding SaaS subscription tiers while spot-market API rate caps attract price-sensitive mid-market e-commerce exporters. Pricing stratifies across premium, standard, and economy tiers based on customs brokerage integration depth and carbon accounting granularity. Cost compression in standard-tier transactional pricing stems from ocean alliance consolidation on Asia-Europe lanes. Automotive OEMs exhibit least price sensitivity due to just-in-sequence reliability requirements, while German apparel direct-to-consumer brands drive hardest bargain on per-shipment API fees.
Supply Chain Analysis
Direct-to-shipper SaaS channels handle hyperscale e-commerce demand, bypassing traditional forwarder intermediaries through embedded customs duty calculation and landed cost transparency. Platform development concentrates in Germany, the Netherlands, and the United States, with middleware specialists in Rotterdam and Singapore bridging carrier API interoperability gaps. Cloud infrastructure and maritime data science talent constitute critical input dependencies. Single-source vulnerability sits with concentrated vessel AIS signal interpretation expertise in Singapore labor pools. Distribution runs through integrated visibility stacks converging customs brokerage, ocean freight tracking, and carbon verification into single-contract accountability models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container tracking APIs are displacing manual bill-of-lading processing, forcing legacy forwarders into platform migration or lane exit as real-time telemetry becomes table stakes for trans-Pacific competitiveness.
For Market Incumbents: Extend carbon accounting module development to preempt EU Green Deal tender exclusion, while securing captive truckload capacity access through backward integration into North American and European ground transport networks. API interoperability partnerships with ocean alliance carriers anchor defensive positioning against middleware specialists extracting premium pricing from carrier network fragmentation.
For New Entrants and Emerging Players: Launch via embedded REACH documentation workflows targeting German chemical logistics operators underserved by generic consolidation platforms. White space concentrates in parametric risk management products for supply chain disruption hedging, and in intermodal carbon accounting tools for EU public procurement lanes. Go-to-market leverage rests on ISO 14064 certification as a tender participation prerequisite.
For Investors and Strategic Acquirers: Ocean carrier API standardization announcements at PSA Singapore terminals are the leading indicator that middleware-dependent business models face structural margin compression. Long-term viability favors platforms with proprietary vessel telemetry interpretation capabilities and controlled capacity access. Target acquisition archetype: European specialists with embedded carbon verification workflows and Hamburg-Rotterdam corridor density.
| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Partnership | Bridges carrier network fragmentation that middleware specialists currently exploit at premium pricing. |
| Carbon Verification Module Development | Secures ISO 14064 certification prerequisite for EU public procurement lane participation. |
| Backward Integration into Truckload Capacity | Captures controlled access to North American ground transport through Navisphere-style platform architectures. |
| Machine Learning Demand Forecasting Investment | Displaces static annual contracting with dynamic routing algorithms optimizing multimodal lane selection. |
| Blockchain Bill-of-Lading Pilot Expansion | Reduces letter-of-credit processing friction for pharmaceutical and electronics shippers in Netherlands clusters. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across freight forwarding executives, maritime data scientists, ocean carrier API product managers, and e-commerce supply chain directors. ECHA REACH documentation databases, EU Green Deal implementation reports, FERC interstate commerce dockets, and EPA emissions benchmarking disclosures supplied validation layers. Bottom-up platform deployment counts across Hamburg, Rotterdam, Los Angeles, and Singapore terminals reconciled with top-down SaaS procurement spend estimates.
Granularity-level modeling tracked service type, technology deployment, end-user industry, and delivery model dimensions at the country-corridor level. CAGRs derived from logistic curve fitting to platform adoption rates, with inflection points calibrated against EU regulatory mandate timelines. Forecast inputs incorporated vessel schedule reliability scores, port congestion algorithm accuracy improvements, and carrier API standardization progress metrics across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for blockchain-enabled documentation or parametric insurance products would alter the outlook. Forecasts reflect base-case assumptions regarding ocean alliance pricing discipline and maritime data science talent supply elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Cargo Shipping Market
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
US FTL Brokerage Market