
 Chile Air Freight Transport Market | 2026-2036
Chile Air Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Air Freight Transport Market Outlook
Premium cold-chain certification is rotating toward the center of carrier strategy in Chile's air freight sector. LATAM Airlines Chile leverages its Santiago hub dominance to capture pharmaceutical and perishable flows. DHL sustains extensive ground-feeder integration across the Central Valley. Kuehne + Nagel differentiates through specialized temperature-controlled infrastructure at Arturo Merino Benítez International Airport.
Air freight transport encompasses the commercial movement of goods via fixed-wing aircraft, typically operating within weight thresholds of 45 kg to 150 tonnes per consignment and requiring IATA-standardized unit load devices for interline transfers. Its primary purpose enables time-definite delivery of high-value or temperature-sensitive commodities across Chile's elongated geography where surface transit exceeds 4,000 km north to south. Express delivery commands premium yields from Santiago to northern mining districts, while standard freight absorbs volume from agricultural exporters in the O'Higgins and Maule regions. Cold chain logistics represents the fastest-growing technology segment as salmon and berry producers demand uninterrupted temperature documentation from farm to foreign market.
Chile's Directorate General of Civil Aeronautics (DGAC) enforces ICAO-aligned cargo security screening mandates that determine which freight forwarders qualify for known-consignor status. The National Customs Service (Servicio Nacional de Aduanas) operates the Aduana Exprés digital platform, accelerating clearance for pre-approved air cargo operators while tightening documentation for non-compliant entrants. Stakeholders must monitor DGAC's phased implementation of EU-equivalent cargo security standards, as this will determine which Chilean carriers retain direct freighter access to European Union destinations without costly third-country transloading.
Market Dynamics
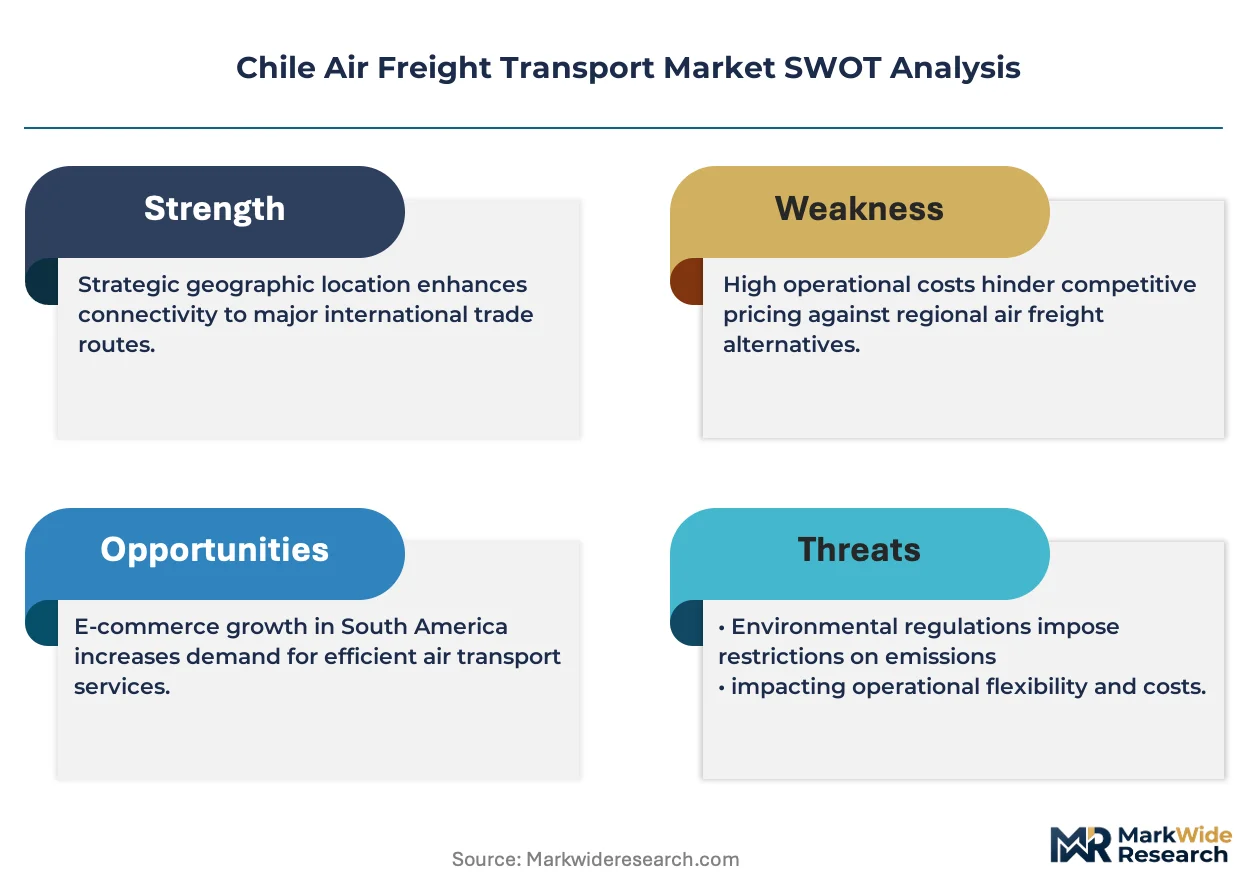
Pharmaceutical-grade cold-chain certification is restructuring carrier economics in Chile's air freight sector, as temperature-sensitive cargo now commands yield premiums exceeding standard freight rates by multiples while disqualifying uncertified operators from Santiago's highest-margin lanes.
Growth Catalysts
- EU-equivalent cargo security standards:DGAC's phased implementation creates certification moats that favor compliant forwarders with direct freighter access to European destinations, eliminating transloading costs for qualified operators.
- Salmon and berry export volumes:Chile's aquaculture and fresh produce sectors require uninterrupted temperature documentation from farm to foreign market, generating sustained demand for certified cold-chain infrastructure at Arturo Merino Benítez International Airport.
- Metropolitan Region logistics corridor:The Valparaíso-Santiago connection concentrates pharmaceutical and perishable flows, enabling ground-feeder integration that reduces transit times for time-definite shipments.
Market Restraints
- Jet fuel price volatility:Fuel represents the largest variable cost component for Chilean carriers, with price spikes immediately compressing margins on long-haul freighter routes to North American and European destinations.
- Santiago hub concentration:Over 80% of certified cold-chain capacity sits at a single airport, creating systemic vulnerability to weather disruptions, labor actions, or infrastructure failures.
- Known-consignor status barriers:DGAC's ICAO-aligned screening mandates exclude smaller freight forwarders from expedited processing, limiting market entry and consolidating volume among established players.
Strategic Opportunities
- Antofagasta mining logistics:Northern Chile's copper and lithium extraction zones remain underserved by scheduled freighter service, creating white space for express cargo operators serving just-in-time spare parts and equipment.
- Aduana Exprés platform expansion:The National Customs Service's digital clearance system offers pre-approved operators accelerated processing, with potential to extend benefits to additional certified forwarders.
- Blockchain-IoT convergence:Immutable temperature logging combined with real-time sensor networks enables pharmaceutical exporters to meet stringent chain-of-custody requirements for high-value biologics.
Industry Challenges
- Cold-chain technician scarcity:Qualified personnel for maintaining and monitoring pharmaceutical-grade refrigeration units are concentrated in Santiago, limiting operational expansion to secondary airports.
- Certification timeline compression:DGAC's phased security protocol implementation demands rapid infrastructure investment, straining capital allocation for mid-sized freight forwarders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Air Freight Transport Market |
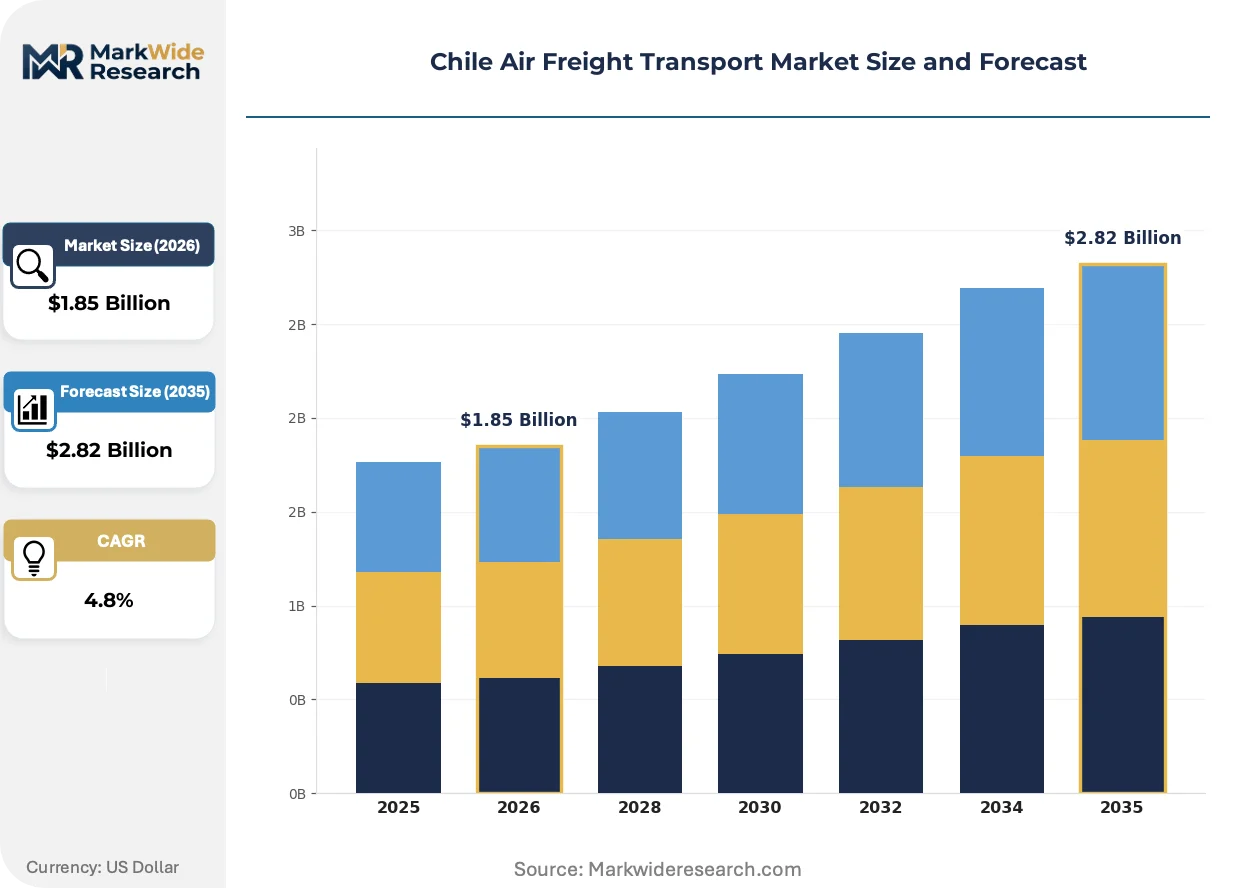
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Standard Freight, Charter Services, Priority Shipping End User: Manufacturers, Retailers, Pharmaceuticals, E-commerce Product Type: Perishable Goods, Electronics, Machinery, Textiles Technology: Automated Tracking, Cold Chain Logistics, Cargo Management Systems, UAV Delivery |
| Companies Covered | Agility Logistics Chile SA, LATAM Airlines Chile, UPS, DSV Panalpina, Andes Logistics Group, FedEx, Avianca Holdings SA, Kuehne + Nagel, DHL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Air Freight Transport Market Strategic Shifts
Digital documentation and automated handling systems are displacing paper-based processes across Chile's air cargo terminals, while regulatory pressure on temperature integrity accelerates investment in sensor infrastructure.
Active temperature-controlled containers are bifurcating the pharmaceutical freight segment in Chile. These units maintain precise thermal ranges for biologics and vaccines during extended transit. LATAM Cargo and international forwarders are deploying them on Santiago-Miami and Santiago-Amsterdam lanes. The technology is bifurcating carrier tiers, separating certified operators capable of pharmaceutical-grade service from general cargo handlers locked out of premium yield segments.
DGAC's adoption of ICAO Annex 17 cargo security amendments is tightening screening protocols for all export freight. The regulation mandates 100% hold baggage and cargo screening for passenger aircraft, with phased extension to freighter operations. Pharmaceutical and electronics exporters face extended processing times unless they qualify for known-consignor status, driving consolidation among forwarders with compliance resources.
Shipper procurement of air freight is consolidating around integrated logistics providers capable of door-to-door cold-chain custody. Chilean salmon producers and berry exporters are awarding multi-year contracts to operators with dedicated temperature-controlled infrastructure rather than spot-buying capacity. This pattern is most pronounced in the O'Higgins and Maule regions, where agricultural exporters prioritize chain-of-custody documentation over pure transport cost.
Chile Air Freight Transport Market Segmentation
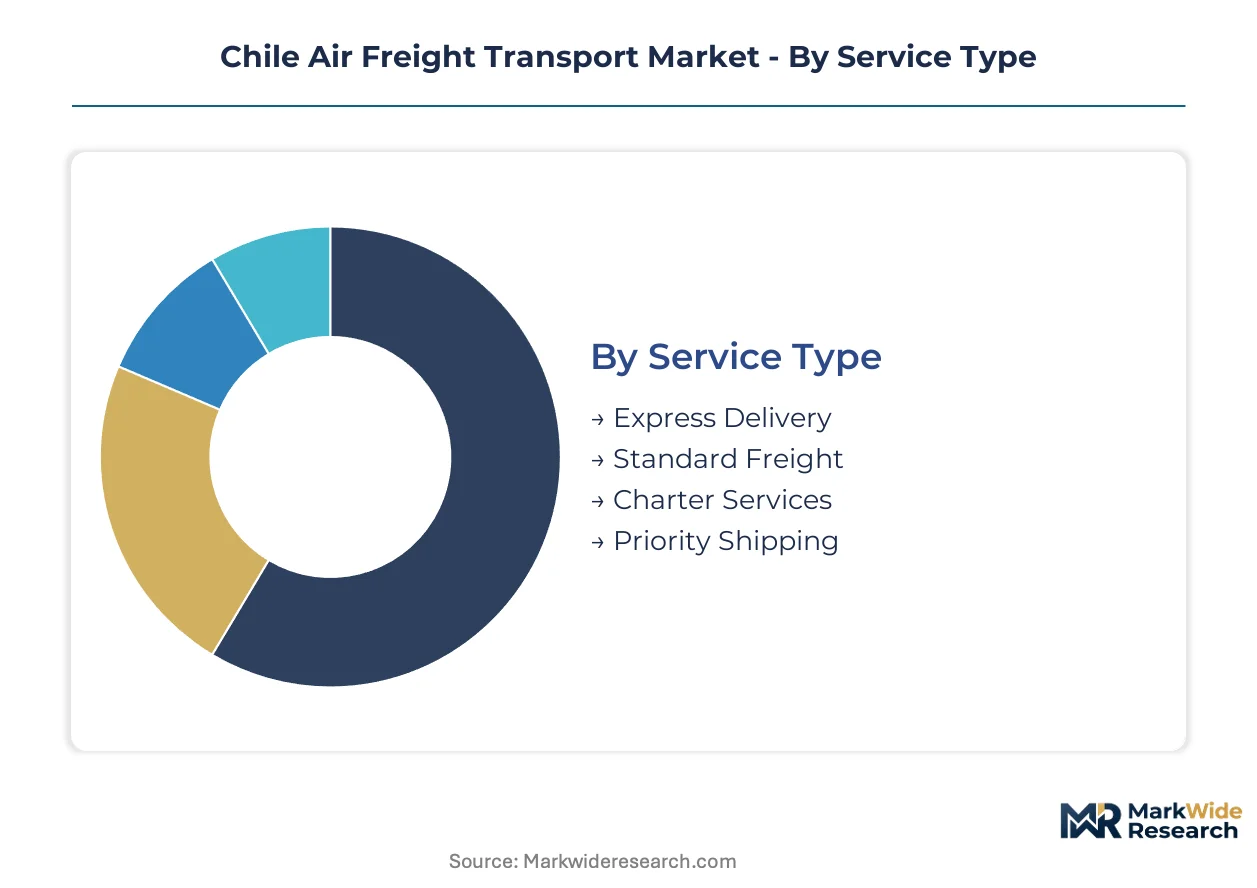
Segmentation in Chile's air freight market reveals how carrier economics bifurcate between commodity handlers and certified specialists. Service tiers, end-user requirements, and technology adoption determine which operators capture pharmaceutical-grade yields versus standard freight margins.
Service Type:
Margin pools concentrate in time-definite offerings where pharmaceutical and mining sector demand sustains rate premiums above standard freight benchmarks.
- Express Delivery:Time-critical shipments moving within 24-48 hour windows, utilizing dedicated freighter capacity and expedited ground handling. Mining districts in Antofagasta and pharmaceutical corridors in the Metropolitan Region absorb the highest volumes, with just-in-time spare parts and temperature-sensitive biologics commanding yield multiples.
- Standard Freight:Consolidated cargo moving through scheduled passenger belly-hold or freighter networks without guaranteed delivery windows. Agricultural exporters in O'Higgins and Maule regions dominate volume flows, prioritizing cost efficiency over speed for berries and non-perishable goods.
- Charter Services:Dedicated aircraft capacity for project cargo, mining equipment, and emergency logistics.
- Priority Shipping:Accelerated processing with preferential loading and customs clearance.
Express Delivery holds installed capacity. Priority Shipping is rotating up the share rankings.
End User:
Customer concentration patterns track Chile's export specialization, with pharmaceutical and mining procurement driving infrastructure investment decisions at Arturo Merino Benítez International Airport.
- Pharmaceuticals:Temperature-sensitive biologics, vaccines, and active pharmaceutical ingredients requiring uninterrupted cold-chain custody. Exporters in Santiago's Quilicura and Pudahuel industrial zones demand real-time temperature logging and known-consignor status for EU market access.
- Manufacturers:Industrial components, automotive parts, and electronics assemblies moving on scheduled frequencies. Northern Chile's copper smelters and lithium processing facilities in the Atacama Desert generate consistent demand for precision-timed inbound materials.
- Retailers:Fashion apparel, consumer goods, and seasonal merchandise.
- E-commerce:Cross-border parcel flows and returns logistics.
Pharmaceuticals holds installed capacity. E-commerce is rotating up the share rankings.
Product Type:
Physical cargo characteristics determine handling infrastructure requirements, with temperature sensitivity creating the steepest capability gaps between carrier tiers.
- Perishable Goods:Fresh salmon, blueberries, cherries, and asparagus requiring active refrigeration from farm gate to foreign market. Los Lagos and Biobío region exporters dominate volume, with DGAC-certified cold-chain documentation mandatory for EU and US destination access.
- Electronics:Semiconductors, consumer devices, and telecommunications equipment with high value-to-weight ratios. Santiago's Renca and Huechuraba logistics parks concentrate inbound flows for assembly and distribution.
- Machinery:Heavy industrial equipment and capital goods.
- Textiles:Apparel and fabric shipments with lower time sensitivity.
Perishable Goods holds installed capacity. Electronics is rotating up the share rankings.
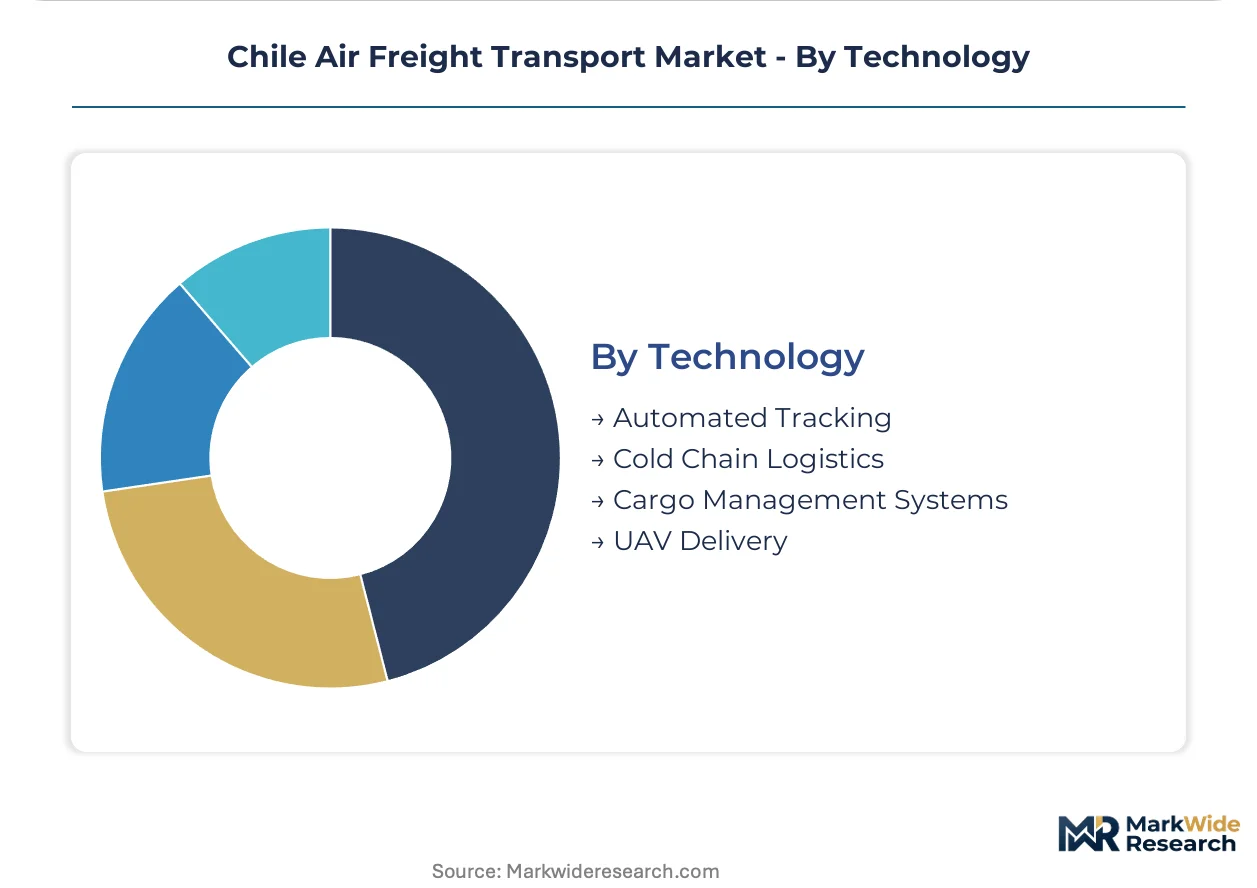
Technology:
Digital infrastructure investment separates compliant operators from those locked out of pharmaceutical and high-value lanes by documentation gaps.
- Cold Chain Logistics:Active temperature-controlled containers, pharmaceutical-grade refrigeration units, and sensor networks maintaining chain-of-custody records. LATAM Cargo and certified forwarders deploy these systems on Santiago-Miami and Santiago-Amsterdam corridors where biologics demand precise thermal ranges.
- Automated Tracking:RFID and GPS-based shipment visibility systems providing real-time location and condition monitoring. The National Customs Service's Aduana Exprés platform integrates these feeds for pre-approved operator clearance acceleration.
- Cargo Management Systems:Digital booking, load planning, and documentation platforms.
- UAV Delivery:Unmanned aerial vehicle pilot programs for last-mile connectivity.
Cold Chain Logistics holds installed capacity. Automated Tracking is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified cold-chain capacity clusters at Arturo Merino Benítez International Airport, creating a single-point dependency that shapes regional logistics investment. The Metropolitan Region's logistics corridor absorbs pharmaceutical and perishable flows while northern mining districts remain underserved by scheduled freighter service.
Metropolitan Region
Pharmaceutical exporters in Quilicura and Pudahuel industrial zones drive temperature-controlled shipment volumes through Santiago's airport hub. DGAC cargo security protocol modernization determines which forwarders qualify for known-consignor status and expedited EU market access. The Valparaíso-Santiago corridor enables ground-feeder integration that reduces transit times for time-definite biologics and perishables.
Antofagasta Region
Copper smelters and lithium processing facilities in the Atacama Desert generate consistent demand for precision-timed inbound materials and just-in-time spare parts. National Customs Service Aduana Exprés digital platform accelerates clearance for pre-approved operators serving northern mining logistics. Calama and Antofagasta cities concentrate express cargo demand that currently lacks dedicated freighter capacity.
Los Lagos Region
Salmon aquaculture operations require uninterrupted temperature documentation from farm gate to foreign markets in the US and EU. DGAC mandates EU-equivalent cargo security standards for all export freight, with phased screening protocol implementation affecting regional cold-chain certification timelines. Puerto Montt anchors perishable export flows that feed into Santiago's consolidated pharmaceutical-grade infrastructure.
Biobío Region
Blueberry and cherry producers in the Maule and Biobío zones demand certified cold-chain custody for high-value agricultural exports. The country's national aviation regulator enforces ICAO-aligned screening mandates that determine forwarder eligibility for direct freighter access without third-country transloading. Concepción and surrounding agricultural clusters prioritize chain-of-custody documentation over pure transport cost in shipper procurement decisions.
O'Higgins Region
Agricultural exporters in Rancagua and surrounding valleys absorb standard freight capacity for berries and non-perishable goods through scheduled passenger belly-hold networks. DGAC's phased security protocol implementation creates certification moats that favor compliant operators with existing infrastructure investments. The region's logistics parks feed into Santiago's centralized cold-chain terminals rather than maintaining independent pharmaceutical-grade facilities.
Chile Air Freight Transport Market Competitive Environment
Concentration sits with integrated global forwarders and national carrier groups that control certified cold-chain infrastructure at Santiago's primary airport hub. LATAM Airlines Chile leverages hub dominance to capture pharmaceutical and perishable flows, while DHL and Kuehne + Nagel sustain extensive ground-feeder integration across the Central Valley. Three archetypes define competitive positioning: integrated express operators with dedicated freighter capacity, specialized temperature-controlled logistics providers, and regional freight forwarders dependent on passenger belly-hold space. Dominant competitive moves include certification-driven capacity expansion at Arturo Merino Benítez International Airport and strategic partnerships with salmon and berry exporters seeking multi-year chain-of-custody contracts.
Within the integrated global forwarder tier, DHL and Kuehne + Nagel exemplify operators with specialized temperature-controlled infrastructure and pharmaceutical-grade certification. LATAM Airlines Chile occupies a position as the dominant national carrier group controlling hub capacity at Santiago's primary airport. Among US-based express operators, FedEx and UPS represent archetypes of integrated networks with dedicated freighter access and expedited customs clearance capabilities through pre-approved operator status.
| Leading Market Players |
|---|
| Agility Logistics Chile SA |
| LATAM Airlines Chile |
| UPS |
| DSV Panalpina |
| Andes Logistics Group |
| FedEx |
| Avianca Holdings SA |
| Kuehne + Nagel |
| DHL |
| Others |
Value Chain & Pricing Dynamics
DGAC's phased EU-equivalent cargo security standards simultaneously gate supply qualification and price differentiation, locking uncertified operators out of pharmaceutical-grade yields while concentrating premium pricing power among compliant forwarders at Santiago's Arturo Merino Benítez International Airport.
Pricing Analysis
DGAC's known-consignor certification dictates the pricing tier structure across Chile's air freight sector. Three-tier pricing stratifies across certified cold-chain, standard express, and commodity belly-hold segments, with temperature-sensitive biologics commanding multiples above standard freight rates. Price differentiation rests on certification grade and real-time temperature documentation capabilities. Cost compression in standard freight is intensifying as fuel volatility squeezes margins on long-haul routes to North American and European destinations. Agricultural exporters in O'Higgins and Maule regions exhibit highest price sensitivity, while pharmaceutical procurement teams in Santiago's Quilicura industrial zone prioritize chain-of-custody assurance over transport cost.
Supply Chain Analysis
Port congestion at Valparaíso and container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for Chilean freight forwarders. Active temperature-controlled containers and pharmaceutical-grade refrigeration units draw from manufacturing concentrations in Germany, the Netherlands, and the United States. Jet fuel procurement hinges on Singapore and US Gulf Coast spot markets, while qualified cold-chain technicians remain concentrated in Santiago's Metropolitan Region. Single-source vulnerability sits with Arturo Merino Benítez International Airport's monopoly on certified pharmaceutical infrastructure. Distribution runs through ground-feeder networks integrating the Valparaíso-Santiago corridor with regional agricultural clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's air freight sector is positioned for cyclical recovery as salmon and berry export volumes rebound from weather-driven harvest disruptions, with pharmaceutical-grade cold-chain demand providing countercyclical stability through biologics procurement cycles.
For Market Incumbents: Compound hub dominance at Arturo Merino Benítez International Airport through accelerated DGAC certification timeline compliance, securing known-consignor status moats before phased security protocol implementation excludes mid-tier competitors. Expand dedicated freighter capacity on Santiago-Amsterdam and Santiago-Miami corridors to capture pharmaceutical yield premiums. Defensive positioning against DHL and Kuehne + Nagel's ground-feeder integration requires backward integration into Central Valley warehousing assets. For New Entrants and Emerging Players: Antofagasta mining logistics under-service by scheduled freighter operators opens white space for express cargo specialists targeting just-in-time spare parts and precision-timed inbound materials for copper smelters and lithium processing facilities. Secondary airport cold-chain infrastructure scarcity in Calama and Puerto Montt presents geographic penetration opportunities. Go-to-market execution should anchor on Aduana Exprés pre-approved operator status to accelerate customs clearance credibility. For Investors and Strategic Acquirers: DGAC's EU-equivalent cargo security standard completion reshapes the acquisition landscape toward certified forwarders with direct freighter access eliminating third-country transloading costs. Long-term viability favors vertically integrated operators controlling temperature-controlled infrastructure across farm-gate-to-foreign-market custody chains. Target acquisition archetype: mid-sized Chilean forwarders with existing DGAC known-consignor status and salmon sector multi-year contracts. Monitor DGAC certification timeline compression as inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Certification Acceleration | DGAC compliance secures direct EU freighter access eliminating transloading cost penalties. |
| Mining Logistics Network Expansion | Antofagasta copper and lithium corridors lack dedicated express freighter capacity. |
| Blockchain-IoT Temperature Integration | Immutable logging meets pharmaceutical chain-of-custody documentation requirements. |
| Aduana Exprés Platform Enrollment | National Customs Service pre-approval accelerates clearance for certified operators. |
| Ground-Feeder Vertical Integration | Central Valley warehousing assets reduce transit times for O'Higgins and Maule agricultural clusters. |
Study Parameters
A spread of perspectives from LATAM Cargo operations executives, DGAC regulatory affairs officers, salmon exporter logistics directors, pharmaceutical procurement managers, and National Customs Service administrators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through IATA cargo statistics, DGAC regulatory filings, Servicio Nacional de Aduanas trade data, and airline schedule databases. Bottom-up volume triangulation across service type, end user, and technology segments was cross-checked against top-down macroeconomic indicators.
Segmentation dimensions modeled span service type, end user industry, product characteristics, and technology adoption across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and infrastructure investment cycles. Forecast inputs incorporated jet fuel price trajectory assumptions, pharmaceutical export volume patterns from Santiago's Quilicura and Pudahuel zones, and DGAC security protocol implementation schedules.
Material uncertainties — DGAC certification timeline delays, Arturo Merino Benítez infrastructure disruption events, and EU cargo security standard equivalence recognition decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding salmon harvest volumes and mining sector capital expenditure cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Fine Art Logistics Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Germany Automotive 3PL Market