
 Mexico Last Mile Delivery Market | 2026-2036
Mexico Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Last Mile Delivery Market Insights
Subscription-based route optimization software is repositioning how carriers monetize fleet capacity beyond per-package fees. DHL Supply Chain Mexico leverages integrated warehousing and final-mile networks to anchor pharmaceutical and automotive verticals. Estafeta competes through its nationwide ground infrastructure and customs brokerage capabilities. Mercado Libre dominates e-commerce logistics through captive fulfillment centers and proprietary delivery fleets in major metropolitan zones.
Last mile delivery encompasses the final transportation segment from distribution hub to end recipient, typically spanning distances under 100 kilometers and requiring real-time tracking, proof-of-delivery capture, and flexible recipient scheduling. The service integrates route algorithms, mobile driver applications, and customer notification systems to minimize failed delivery attempts and maximize first-attempt success rates. Same-day delivery and express delivery models lead service type expansion as consumer tolerance for waiting periods compresses, while scheduled delivery retains stronger margins in B2B corridors where precision windows command premium pricing. Business-to-Consumer channels occupy the fastest-growing distribution channel slot, though Third-Party Logistics providers sustain margin pools through asset-light aggregation of fragmented carrier capacity.
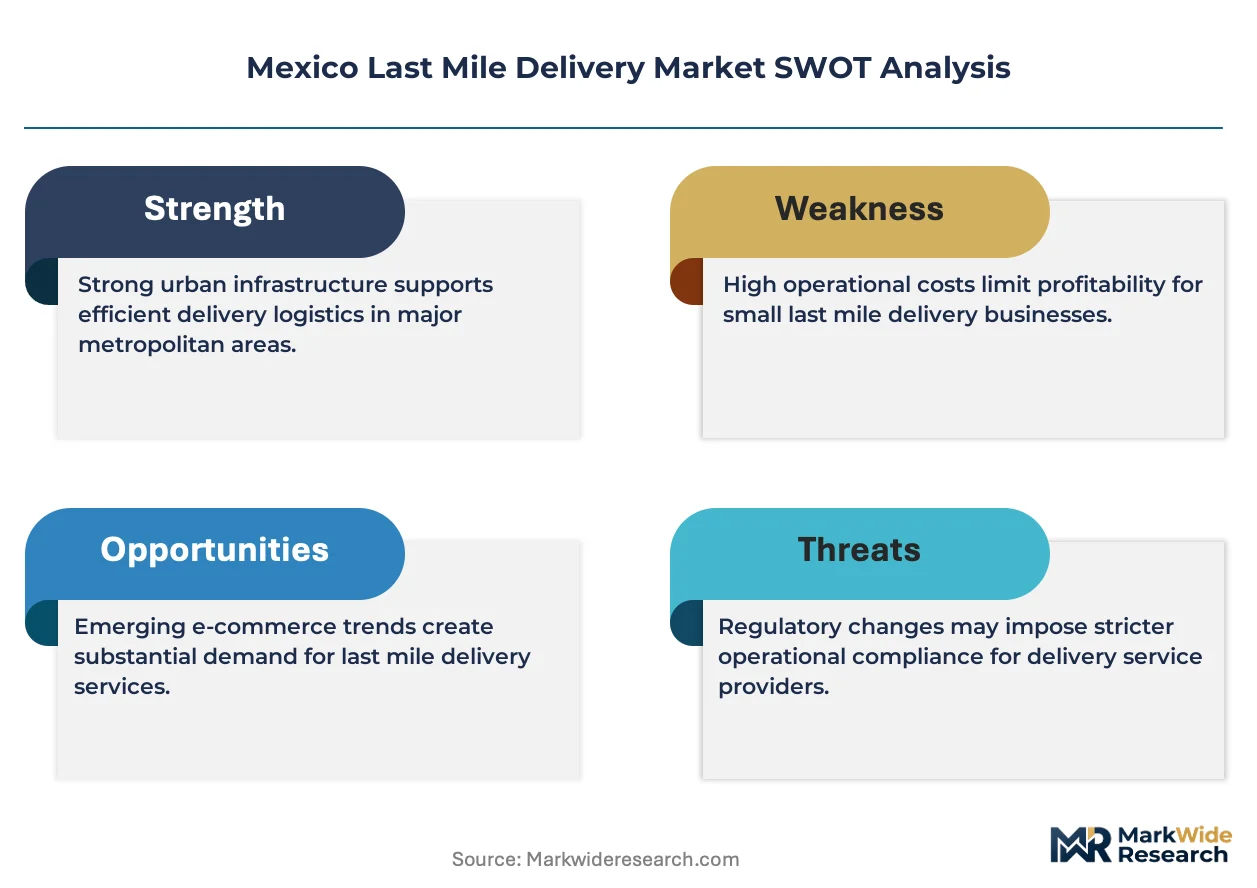
Secretariat of Communications and Transportation infrastructure standards shape cross-border corridor capacity, while Federal Consumer Protection Agency guidelines mandate transparent delivery windows and refund protocols that elevate operational compliance costs. State-level environmental regulations in Mexico City and Nuevo León increasingly restrict internal combustion vehicle access in central business districts, pushing fleet electrification timelines. Stakeholders must monitor regulatory divergence between federal logistics frameworks and municipal mobility restrictions that could fragment nationwide network economics.
Market Dynamics
Fleet electrification mandates from Mexico City and Nuevo León are compressing diesel vehicle replacement timelines while simultaneously opening subsidy windows for electric cargo bikes and light commercial vans. This regulatory pressure is forcing carriers to restructure capital deployment and route density models.
Growth Catalysts
- Federal Telecommunications Institute spectrum allocation:5G network prioritization for logistics corridors enables real-time route optimization and customer tracking applications.
- Quick-commerce apps:Dark store proliferation in Guadalajara and Monterrey generates dedicated last-mile capacity demand that traditional carriers cannot fulfill.
- Digital payment penetration:Cash-on-delivery decline reduces driver cash-handling risk and failed-delivery rates in metropolitan zones.
Market Restraints
- Petroleum price volatility:Diesel and gasoline input cost swings compress margins for internal combustion fleets operating outside electrification zones.
- Customs brokerage concentration:Cross-border e-commerce dependency on limited Nuevo León and Baja California customs capacity creates bottleneck risk.
- Last-mile labor informality:Gig-economy driver classification disputes under Federal Labor Law generate compliance cost uncertainty.
Strategic Opportunities
- Quintana Roo and Yucatán tourism corridors:Underpenetrated same-day delivery infrastructure for hospitality and pharmacy verticals.
- Secretariat of Communications and Transportation freight rail integration:Intermodal hub-to-last-mile handoff standards enable consolidated rural delivery economics.
- Refrigerated electric cargo bikes:Temperature-controlled last-mile convergence with micromobility infrastructure addresses pharmaceutical and grocery segments.
Industry Challenges
- Route optimization algorithm talent scarcity:Machine learning engineering for dynamic Mexican traffic patterns remains concentrated in Mexico City hiring pools.
- Legacy warehouse management system integration:Real-time inventory visibility handoffs between Estafeta and DHL networks require API standardization that fragmented carriers resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Last Mile Delivery Market |
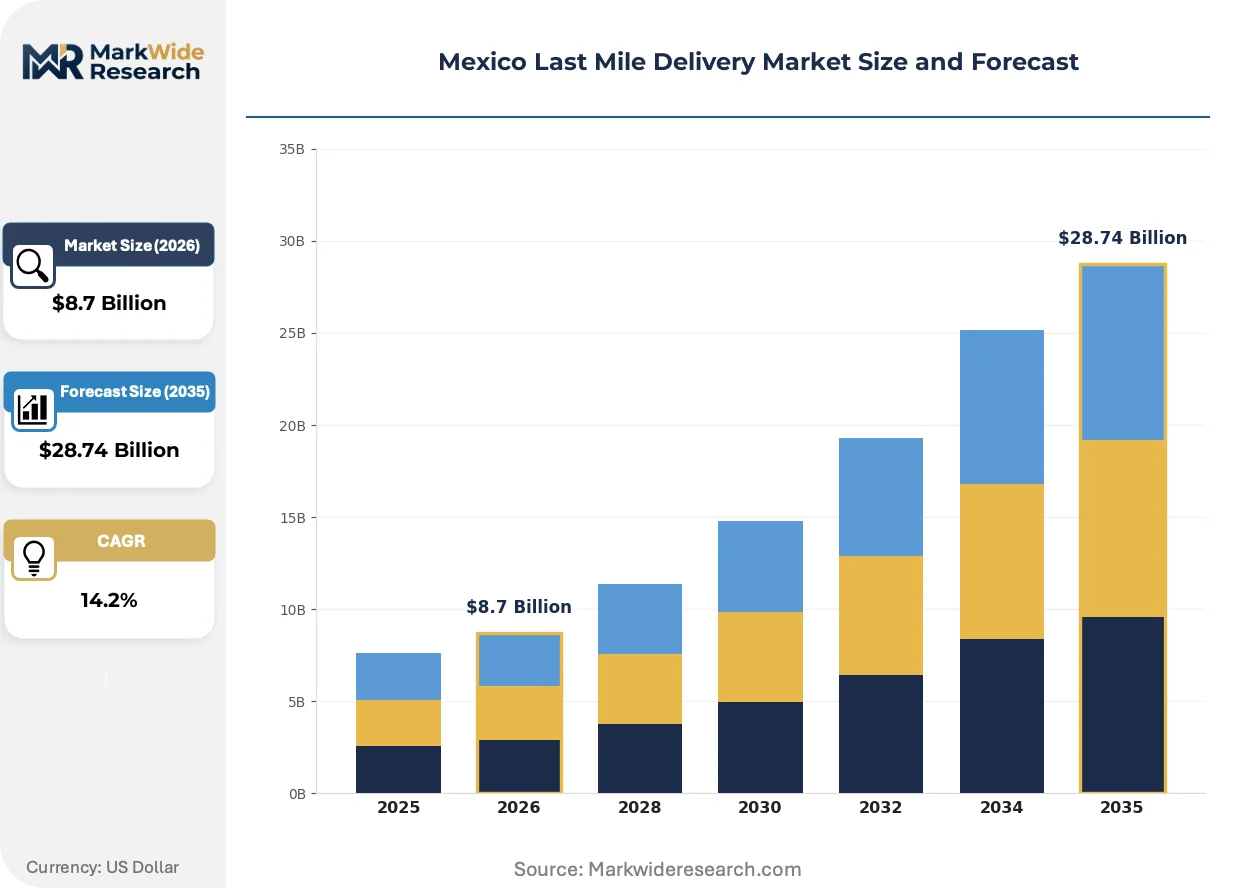
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Model: Same-Day Delivery, Scheduled Delivery, Express Delivery, Standard Delivery Service Type: Business-to-Consumer, Business-to-Business, Retail, eCommerce Distribution Channel: Online, Offline, Hybrid, Third-Party Logistics Customer Type: Individual Consumers, Small Businesses, Large Enterprises, Corporations |
| Companies Covered | DHL Supply Chain Mexico, Estafeta, FedEx Mexico, UPS Mexico, Mercado Libre, Rappi, 99minutos, Cargamos, Amazon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Last Mile Delivery Market Trends and Innovations
Electric vehicle fleet conversion is absorbing capital and operational attention across Mexican logistics networks. Three intersecting developments are determining competitive positioning.
Telematics-enabled dynamic routing is absorbing dispatcher decision-making authority into algorithmic systems. Quick-commerce operators in Mexico City deploy these platforms to compress delivery windows below 30 minutes. The technology is absorbing traditional carrier advantage in route familiarity and driver experience.
Nuevo León state environmental mobility restrictions now prohibit diesel delivery vehicles in Monterrey's central business district during peak hours. Automotive and pharmaceutical shippers must reroute to peripheral transfer points or absorb electric fleet conversion costs. B2B scheduled delivery segments face the steepest operational reconfiguration.
Buyer tolerance for delivery window uncertainty has collapsed among metropolitan e-commerce consumers. Same-day and scheduled delivery models are displacing standard 3-5 day economy options in Mexico City, Guadalajara, and Monterrey. Grocery and electronics verticals exhibit the most pronounced preference compression.
Mexico Last Mile Delivery Market Segmentation
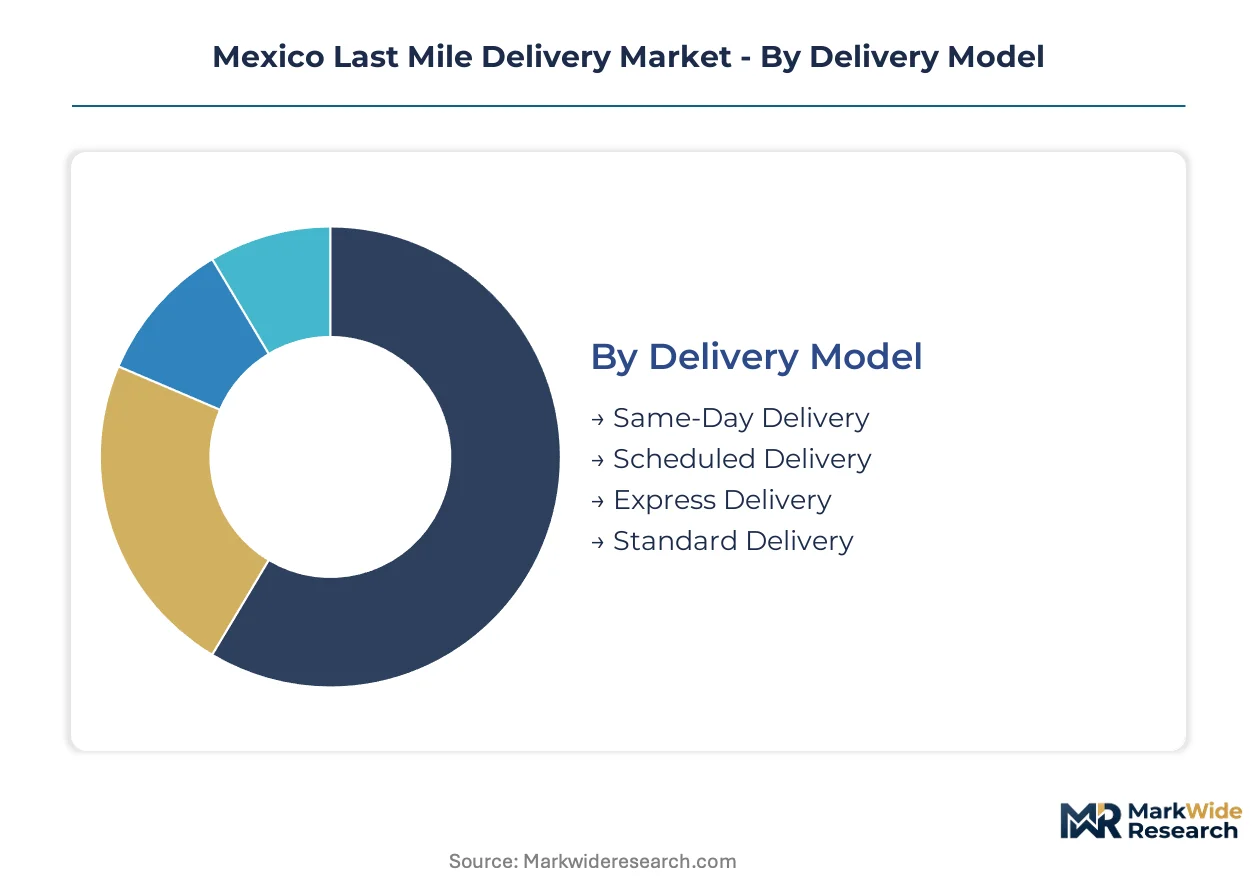
Delivery model selection determines capital intensity and route density economics for Mexican carriers. Service type and customer segmentation shape margin profiles across metropolitan corridors and cross-border corridors.
Delivery Model:
Upgrade cycles from standard to expedited delivery compress as e-commerce platforms reset consumer expectations in Mexico City, Guadalajara, and Monterrey.
- Same-Day Delivery:Ultra-compressed fulfillment windows under 24 hours require dark store proximity and algorithmic dispatch systems. Demand concentrates in grocery and electronics verticals across Mexico City metropolitan zone, where Mercado Libre and quick-commerce apps absorb premium pricing for speed.
- Scheduled Delivery:Precision time-window commitments command premium pricing in B2B pharmaceutical and automotive corridors. Nuevo León industrial shippers leverage this model to align inbound parts delivery with production line schedules, minimizing inventory carrying costs.
- Express Delivery:24-48 hour commitments balance speed against cost efficiency for mid-tier e-commerce shipments.
- Standard Delivery:3-5 day economy options retain relevance in price-sensitive rural corridors where route density fails to support expedited infrastructure.
Same-day delivery sits at the top of the volume ranking, with scheduled delivery climbing the fastest.
Service Type:
Application-driven segmentation separates high-frequency consumer replenishment from project-based enterprise procurement patterns.
- Business-to-Consumer:Direct-to-home parcel volumes surge through mobile-first purchasing interfaces. Guadalajara and Monterrey metropolitan zones exhibit steepest trajectory as digital payment penetration reduces cash-on-delivery friction and failed-attempt rates.
- eCommerce:Platform-integrated fulfillment demands captive fleet investment or tight 3PL partnerships. Federal Consumer Protection Agency refund mandates elevate compliance costs for cross-border shipments through Nuevo León and Baja California customs nodes.
- Business-to-Business:Scheduled precision requirements dominate manufacturing supply chains and pharmaceutical distribution.
- Retail:Store-to-door and buy-online-pickup-in-store hybrid models bridge physical and digital inventory systems.
Business-to-consumer channels absorb the largest share of incremental volume, though eCommerce exhibits the steepest expansion trajectory.
Distribution Channel:
Cost tier differentiation separates asset-heavy captive networks from margin-light aggregation plays.
- Third-Party Logistics:Asset-light capacity aggregation enables rapid scaling without fleet ownership burdens. DHL Supply Chain Mexico and Estafeta compete through integrated warehousing and customs brokerage capabilities, capturing pharmaceutical and automotive verticals with compliance-heavy requirements.
- Online:Platform-native booking interfaces displace traditional phone and branch-based dispatch. Federal Telecommunications Institute 5G spectrum allocation enables real-time tracking and dynamic routing applications across Mexico City logistics corridors.
- Hybrid:Blended digital-physical touchpoints accommodate cash-preferred customer segments in peripheral metropolitan zones.
- Offline:Traditional branch and phone-based dispatch retains residual share in rural corridors with limited smartphone penetration.
Third-party logistics channels dominate enterprise contract value, while online channels gain share fastest among small and mid-sized shippers.
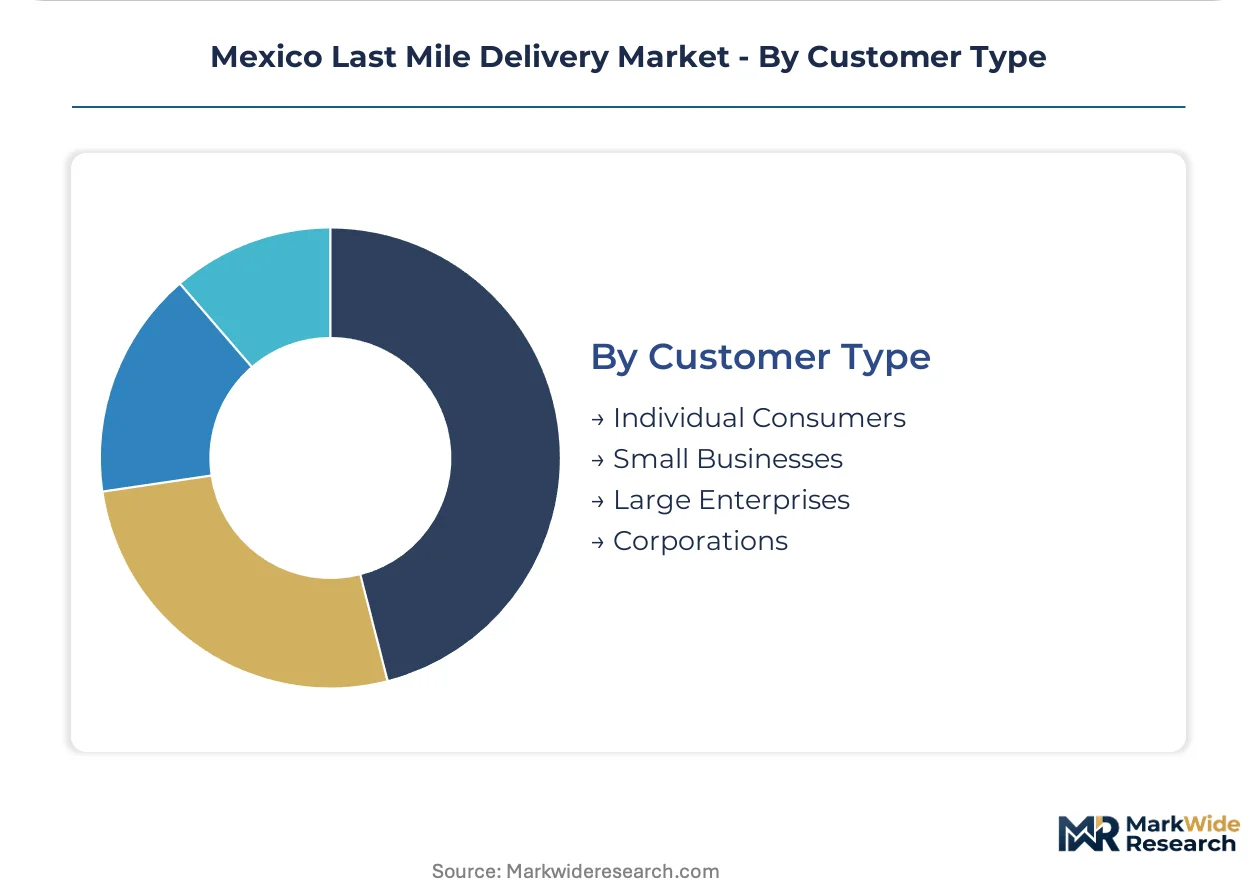
Customer Type:
Volume concentration and margin durability split across customer scale tiers with diverging procurement sophistication.
- Large Enterprises:Contract logistics demands integrate warehousing, cross-border brokerage, and final-mile execution. Automotive and pharmaceutical manufacturers in Nuevo León and Mexico State require temperature-controlled transport and serialized tracking compliant with Secretariat of Communications and Transportation infrastructure standards.
- Individual Consumers:Fragmented demand aggregates through e-commerce platforms and quick-commerce apps. Mexico City density supports unit economics for sub-30-minute delivery windows that fail in lower-density metropolitan zones.
- Small Businesses:Flexible, non-contractual 3PL relationships accommodate volume volatility and seasonal peaks.
- Corporations:Multi-divisional procurement centralization creates vendor consolidation pressure and long-term contract lock-in.
Large enterprises anchor contract value stability, with individual consumer segments expanding most quickly through platform-mediated demand aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico outpaces Brazil in last-mile logistics formalization, yet both markets grapple with informal labor structures that distort fleet economics and insurance underwriting.
Mexico City Metro
Ultra-rapid delivery demand from quick-commerce apps and grocery platforms compresses fulfillment windows below 30 minutes. Federal Telecommunications Institute 5G spectrum allocation enables real-time route optimization across the metropolitan zone. Iztapalapa and Gustavo A. Madero districts host dense dark store networks serving low-income consumer segments previously excluded from same-day service.
Nuevo León
Automotive and pharmaceutical manufacturers drive scheduled delivery precision requirements for just-in-time production lines. State environmental mobility restrictions now prohibit diesel delivery vehicles in Monterrey's central business district during peak hours. Apodaca and Santa Catarina industrial corridors absorb rerouted B2B shipments through peripheral electric fleet transfer points.
Jalisco
Guadalajara's digital payment penetration reduces cash-on-delivery friction and failed delivery rates for direct-to-home parcel volumes. Secretariat of Communications and Transportation freight rail integration standards enable intermodal hub-to-last-mile handoffs from the Bajío manufacturing belt. Zapopan's high-income residential clusters support premium same-day delivery unit economics unavailable in peripheral municipalities.
Northern Border States
Cross-border e-commerce dependency concentrates customs brokerage capacity in Nuevo León and Baja California nodes. Federal Consumer Protection Agency refund mandates elevate compliance costs for international shipments entering through Tijuana and Ciudad Juárez. Maquiladora supply chains demand synchronized last-mile coordination with US distribution networks operating on incompatible scheduling protocols.
Yucatán Peninsula
Tourism corridor underpenetration creates whitespace for pharmacy and hospitality verticals lacking same-day infrastructure. State-level environmental regulations remain permissive toward internal combustion fleets, delaying electrification timelines seen in central Mexico. Mérida's emerging middle-class density approaches the threshold for quick-commerce dark store viability.
Mexico Last Mile Delivery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics providers commanding enterprise contracts while platform-native fleets capture consumer velocity. The market structure concentrates around three archetypes: global 3PL networks with customs brokerage depth, e-commerce platforms operating captive fulfillment and delivery assets, and quick-commerce specialists deploying algorithmic dispatch for sub-hour windows. Competitive moves center on fleet electrification acceleration and dark store network densification in metropolitan corridors.
Among global integrated carriers, DHL Supply Chain Mexico and Estafeta occupy positions defined by warehousing-final mile integration and nationwide ground infrastructure respectively. Mercado Libre represents the platform-captive archetype through proprietary fulfillment centers and metropolitan delivery fleets. These three entities exemplify the strategic divergence between compliance-heavy enterprise service and velocity-driven consumer fulfillment.
| Leading Market Players |
|---|
| DHL Supply Chain Mexico |
| Estafeta |
| FedEx Mexico |
| UPS Mexico |
| Mercado Libre |
| Rappi |
| 99minutos |
| Cargamos |
| Amazon |
| Others |
Pricing and Supply Chain Analysis
Family-owned regional carriers and private-equity-rolled-up fleet operators anchor Mexico's last-mile supply base, translating fragmented ownership into pricing discipline that resists commoditization despite platform-aggregator pressure. Their localized route knowledge and municipal permit relationships create switching costs that sustain margin pools even as quick-commerce apps compress consumer-facing delivery windows.
Pricing Analysis
Capacity additions in Guadalajara and Monterrey are reshaping price floors for same-day delivery slots as dark store proliferation saturates premium corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery speed commitment and proof-of-service requirements. Cost compression in economy tiers is intensifying because diesel fleet operators absorb petroleum volatility without electrification subsidy access. Small businesses exhibit highest price sensitivity, while automotive manufacturers in Nuevo León accept premium scheduling fees for production-line precision.
Supply Chain Analysis
Secretariat of Communications and Transportation certification requirements for cross-border freight integration gate access to pharmaceutical and automotive logistics contracts. Vehicle and battery supply concentrates in China, South Korea, and domestic Mexican assembly plants serving electrification mandates. Lithium-ion cell and electric drivetrain dependencies create single-source vulnerability as Nuevo León and Mexico City accelerate fleet conversion timelines. Distribution runs through Estafeta and DHL hub-and-spoke networks for enterprise accounts, while platform-native fleets bypass intermediaries for consumer parcels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where Federal Telecommunications Institute 5G spectrum allocation and state-level environmental mobility restrictions simultaneously create compliance barriers and technology upgrade demand.
For Market Incumbents: Extend electrified fleet coverage into peripheral metropolitan zones before subsidy windows close, locking in route density advantages against insurgent quick-commerce operators. Deepen backward integration into warehouse management systems to reduce API friction with pharmaceutical and automotive enterprise clients facing serialized tracking mandates. For New Entrants and Emerging Players: Platform-native booking interfaces open direct channel access to small business shippers underserved by branch-based legacy carriers. Quintana Roo and Yucatán tourism corridors offer the most penetrable whitespace for pharmacy and hospitality verticals lacking same-day infrastructure. Target refrigerated electric cargo bike deployment to capture pharmaceutical and grocery segments without competing for diesel fleet permits in restricted zones. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light 3PL aggregators with customs brokerage capabilities but limited proprietary fleet investment. Long-term viability hinges on electrification capital deployment timing and regulatory compliance infrastructure depth. Watch Federal Labor Law gig-economy reclassification proceedings as the inflection signal for labor cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | Nuevo León and Mexico City diesel restrictions force capital reallocation toward subsidy-eligible light commercial vehicles. |
| Dark Store Network Densification | Guadalajara and Monterrey quick-commerce saturation demands hyperlocal inventory positioning for sub-30-minute delivery. |
| Customs Brokerage Integration | Cross-border e-commerce growth through Tijuana and Ciudad Juárez elevates compliance-heavy logistics contract value. |
| Route Optimization Platform Deployment | Telematics-enabled dynamic routing absorbs dispatcher authority and compresses delivery windows for platform-native competitors. |
| Refrigerated Micromobility Investment | Temperature-controlled electric cargo bikes address pharmaceutical and grocery segments without central business district access restrictions. |
Research Methodology
Coverage spans Mexico City, Guadalajara, Monterrey, and Northern Border States, with primary inputs from each metropolitan logistics corridor. The analysis combines structured interviews with fleet operations directors, 3PL contract managers, e-commerce platform logistics leads, and Federal Telecommunications Institute regulatory specialists with secondary validation against customs records, Secretariat of Communications and Transportation infrastructure filings, and state environmental mobility restriction announcements. Bottom-up route density modeling and top-down market sizing triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates volume expansion from pricing evolution and mix-shift effects across delivery model tiers. Segmentation dimensions include service type, customer scale, distribution channel, and metropolitan corridor regulatory cluster. CAGRs derive from logistic curve fitting to electrification adoption patterns and dark store penetration rates. Petroleum price volatility assumptions and Federal Labor Law compliance cost scenarios feed sensitivity testing.
Petroleum price spikes, gig-economy reclassification rulings, and 5G network rollout delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about subsidy continuity and infrastructure investment pacing. A model refresh is warranted upon material change in state-level environmental mobility restriction enforcement or Federal Consumer Protection Agency refund mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Project Logistics Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market