
 Inbound Logistics Market | 2026-2036
Inbound Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Inbound Logistics Market Insights
The shift from single-source to multi-source procurement is recalibrating how manufacturers contract inbound capacity. DHL Supply Chain & Global Forwarding leverages its European rail-road barge network to anchor automotive just-in-sequence programs. Kuehne + Nagel sustains competitive density through pharmaceutical and perishables expertise in temperature-controlled inbound lanes. C.H. Robinson differentiates by operating North America's largest digital freight matching platform for contract and spot inbound moves.
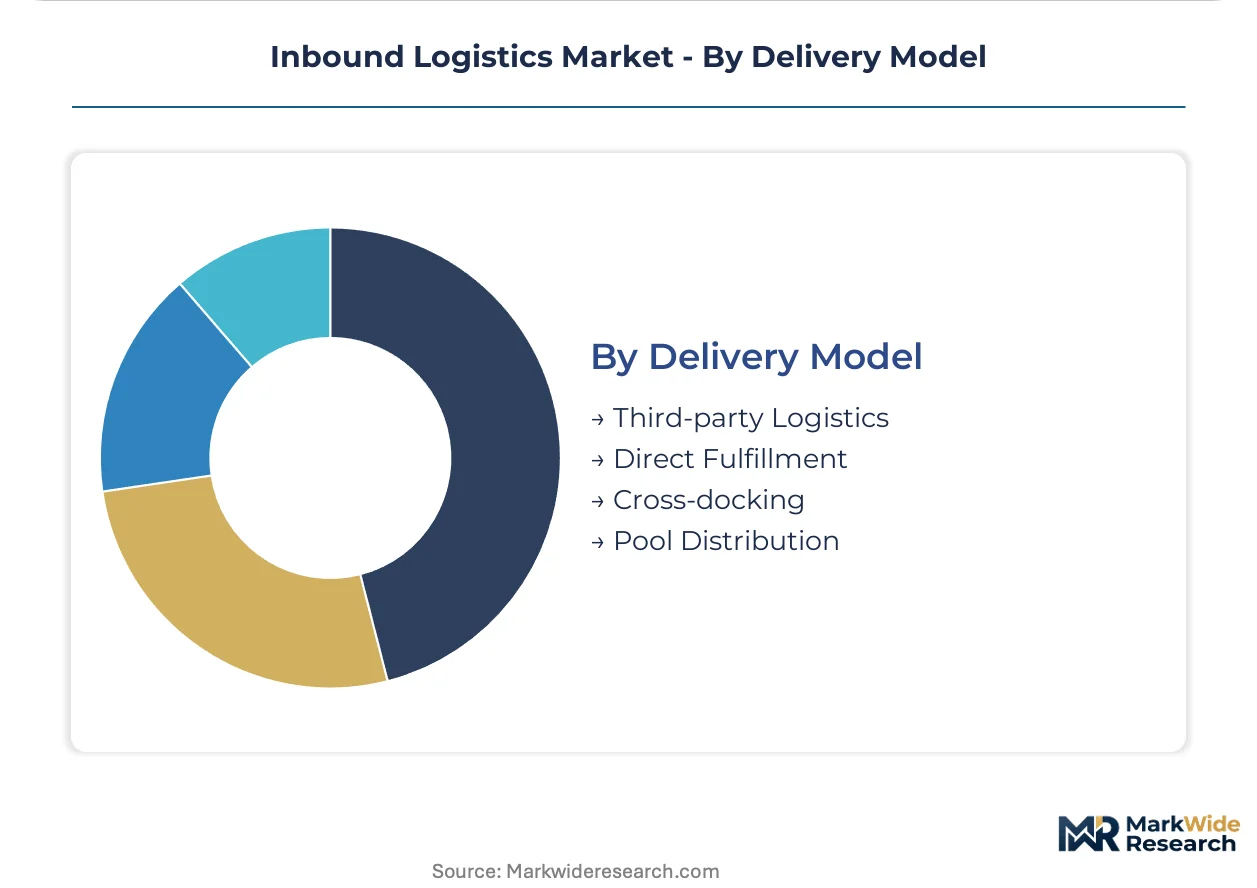
Inbound logistics encompasses the planning, execution, and control of material and product flows from suppliers to manufacturing plants, distribution centers, or retail points, typically governed by lead-time windows of 24-72 hours and fill-rate targets above 98%. Its primary purpose is to synchronize supply arrival with production schedules and inventory policies, minimizing carrying costs while preventing stockouts. Transportation services command the largest value pool within service-type segmentation, though inventory management solutions are expanding fastest as ERP-integrated demand sensing matures. Among delivery models, third-party logistics retains dominant share while cross-docking gains traction in grocery and big-box retail networks seeking dock-to-shelf velocity.
Fleet emissions rules under the EU Green Deal and EPA Phase 3 greenhouse gas standards are accelerating capital redeployment into electric and alternative-fuel tractors for first- and middle-mile collection routes. ISO 14001 environmental management certification and OSHA warehouse safety protocols further shape provider qualification criteria and facility audit schedules. Stakeholders must monitor how carbon border adjustment mechanisms and battery-electric vehicle infrastructure gaps reshape total cost of ownership calculations for long-haul inbound lanes.
Market Dynamics
Multi-source procurement strategies are fragmenting freight volumes across more contracted lanes while compressing lead-time windows, forcing logistics providers to rebuild network density around smaller, more frequent supplier collections rather than traditional milk-run consolidation.
Growth Catalysts
- EU Green Deal fleet mandates:Emissions disclosure requirements for transport are accelerating procurement of battery-electric and hydrogen tractors for first-mile collection routes serving automotive and industrial clusters.
- Automotive just-in-sequence programs:Dense supplier-to-plant corridors in Germany's manufacturing belt are generating sustained demand for synchronized inbound capacity with 24-hour delivery windows.
- ERP-integrated demand sensing:Real-time inventory visibility tools are expanding the addressable market for inbound inventory management solutions as manufacturers reduce safety stock buffers.
Market Restraints
- Battery-electric vehicle infrastructure gaps:Sparse high-power charging networks along long-haul corridors are limiting tractor deployment to urban and regional collection routes, constraining fleet electrification timelines.
- Semiconductor availability for telematics:Persistent shortages of vehicle-grade chips are delaying fleet management system upgrades and IoT sensor rollouts across contracted carrier networks.
- Driver qualification pipelines:Shrinking commercial license issuance rates in Germany, Poland, and the Czech Republic are tightening capacity availability for time-definite automotive collections.
Strategic Opportunities
- Rail-road barge multimodal integration:Underutilized inland waterway connections between Rhine ports and industrial hinterlands offer emission-reduction pathways for bulk inbound flows.
- Cross-docking penetration in grocery retail:Dock-to-shelf velocity requirements are creating demand for flow-through facilities that bypass traditional distribution center storage.
- Carbon border adjustment mechanism preparation:Early compliance infrastructure for embedded emissions tracking is opening service revenue streams for logistics providers serving EU-importing manufacturers.
Industry Challenges
- ISO 14001 audit compression:Accelerated certification timelines for environmental management systems are straining provider quality assurance teams and third-party verification capacity.
- Legacy WMS integration with control towers:Proprietary warehouse management protocols are creating data friction when connecting to cloud-based inbound visibility platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inbound Logistics Market |
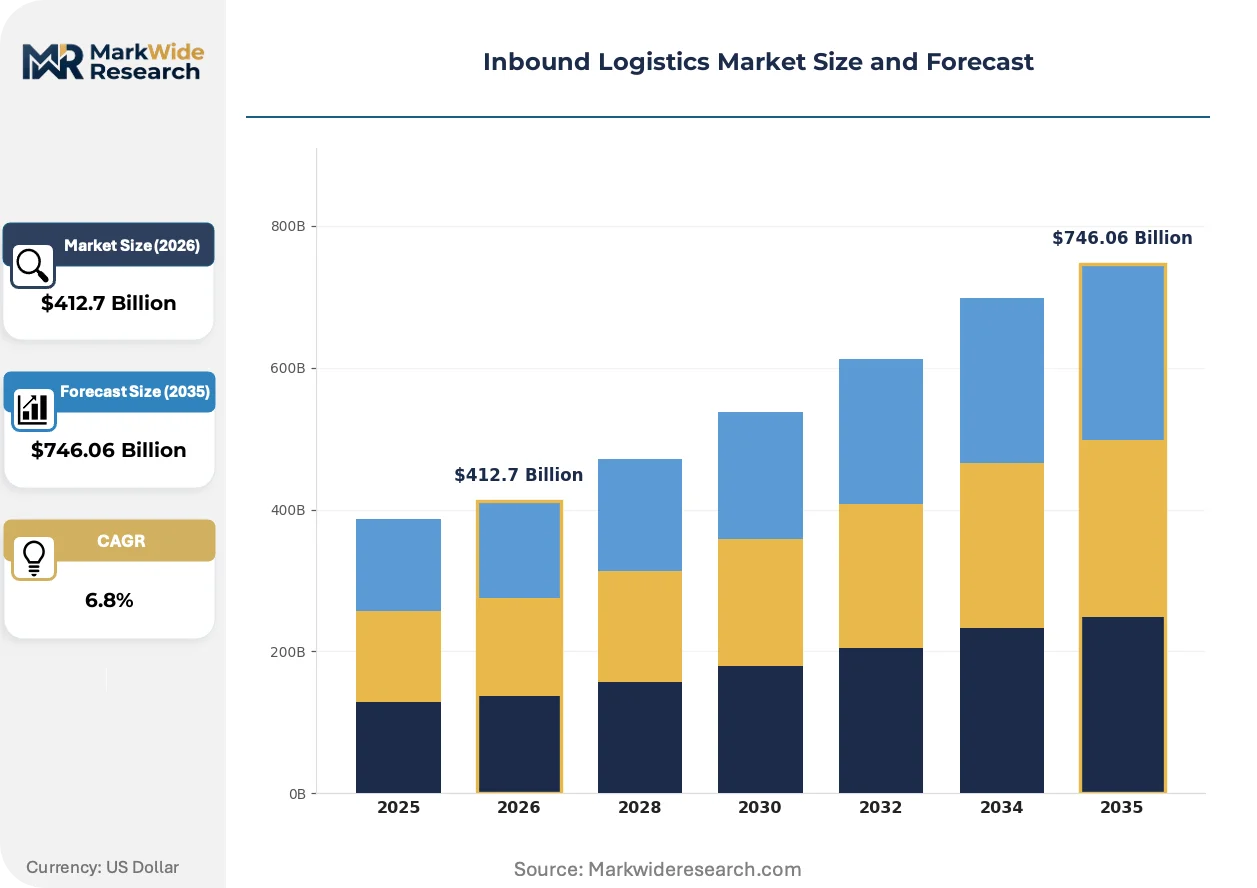
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $746.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Freight Forwarding Industry Vertical: Manufacturing, Retail, Automotive, E-commerce Technology: Blockchain, IoT, AI, Automation Delivery Model: Third-party Logistics, Direct Fulfillment, Cross-docking, Pool Distribution |
| Companies Covered | DHL Supply Chain & Global Forwarding, Kuehne + Nagel, DB Schenker, DSV, UPS Supply Chain Solutions, FedEx Logistics, C.H. Robinson, CEVA Logistics, Nippon Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inbound Logistics Market Trends and Innovations
Digital freight matching platforms are compressing contract procurement cycles while artificial intelligence tools rewrite how carriers predict lane-level demand. These shifts are reshaping provider technology stacks and buyer sourcing behavior simultaneously.
Artificial intelligence-driven demand forecasting is rewriting how automotive manufacturers position inbound inventory. Tier-1 suppliers in Germany's Baden-Württemberg cluster are deploying machine learning models that predict plant-level consumption 72 hours forward. This compression is enabling same-day replenishment triggers and reducing safety stock holdings by half.
EPA Phase 3 greenhouse gas standards are tightening tractor efficiency requirements for US-based fleet operators serving inbound lanes. The regulation mandates progressive CO2 reductions through model year 2027, pushing carriers toward aerodynamic retrofits and alternative-fuel trials. Long-haul routes from Mexico to Midwest assembly plants face the steepest compliance cost adjustments.
Buyer consolidation around outcome-based logistics contracts is fragmenting traditional rate-per-mile pricing structures. Large automotive OEMs in Bavaria and Lower Saxony are unbundling transport from inventory carrying, paying providers only for on-time, in-full performance. This shift concentrates volume with carriers possessing integrated warehouse and transport assets.
Inbound Logistics Market Segmentation
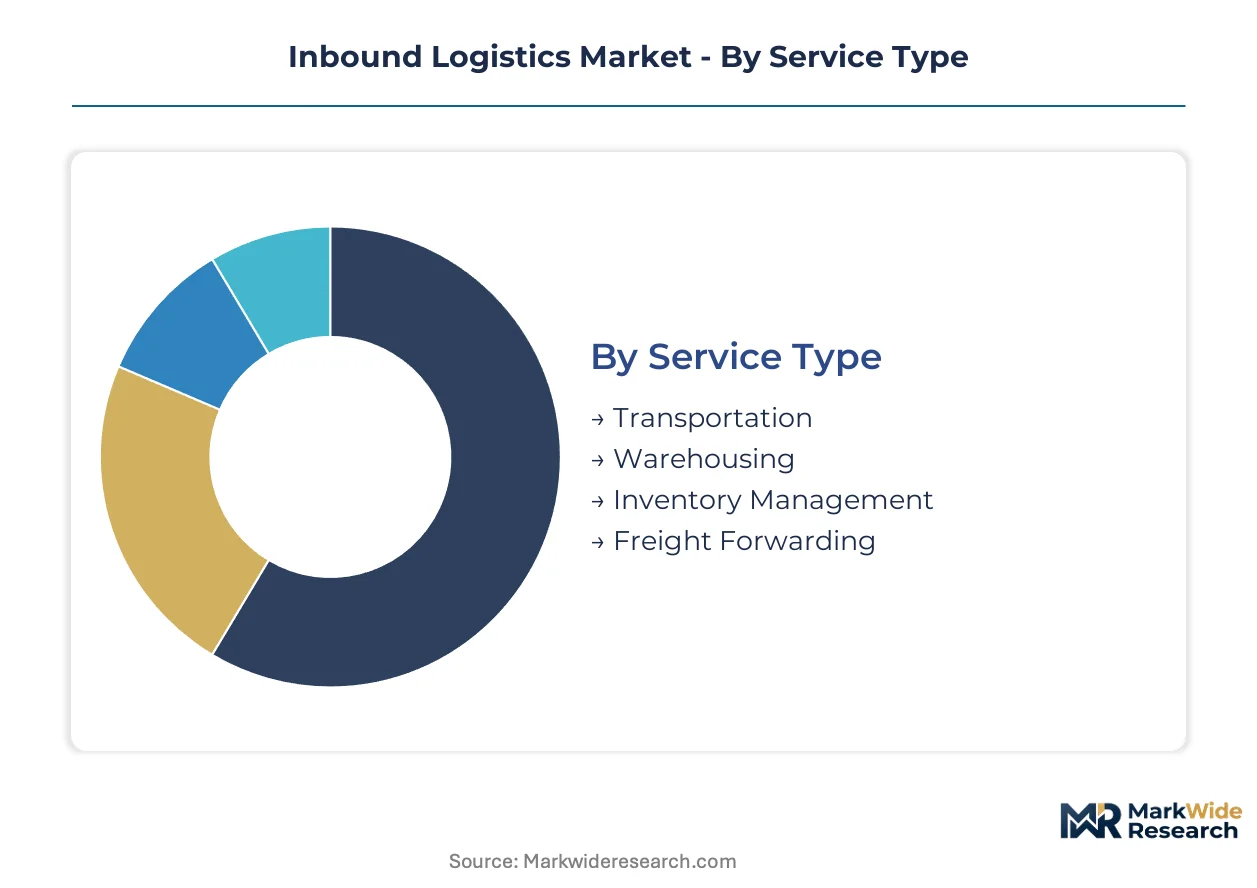
Inbound logistics segmentation reveals how buyer priorities diverge across service complexity, vertical requirements, and technology maturity. Procurement teams weight cost predictability against synchronization precision when selecting provider configurations.
Service Type:
Cost tier determines provider selection more than any other factor, with buyers unbundling premium synchronization from baseline transport.
- Transportation:Movement execution across road, rail, and waterway modes governed by contracted lane density and tractor fleet specifications. Demand concentrates in Germany's automotive corridors where just-in-sequence programs require 24-hour delivery windows and fill rates above 98%.
- Inventory Management:ERP-integrated demand sensing, safety stock positioning, and supplier collaboration portals that compress replenishment cycles. German tier-1 suppliers in Baden-Württemberg are deploying these solutions to halve buffer holdings while maintaining production continuity.
- Warehousing:Receiving, put-away, and cross-dock operations supporting flow-through velocity for retail and grocery networks.
- Freight Forwarding:Multimodal coordination and customs clearance for international supplier lanes.
Transportation leads on scale; inventory management leads on momentum.
Industry Vertical:
Application-specific compliance requirements reshape provider qualification criteria and facility audit protocols.
- Automotive:Just-in-sequence and just-in-time programs demanding synchronized supplier collections with hourly delivery windows to assembly plants. Germany's Bavaria and Lower Saxony clusters generate the densest demand for time-definite inbound capacity.
- Manufacturing:Discrete and process production environments requiring raw material and component flow coordination with production schedules.
- Retail:High-velocity replenishment networks prioritizing dock-to-shelf speed over inventory carrying.
- E-commerce:Fulfillment center inbound receiving scaled to handle fragmented supplier bases and promotional demand spikes.
Automotive commands the steepest service requirements; e-commerce is climbing the fastest.
Technology:
Technology maturity curves determine implementation sequencing, with buyers prioritizing proven ROI over experimental capabilities.
- AI:Machine learning models predicting plant-level consumption 72 hours forward, enabling same-day replenishment triggers and automated procurement decisions.
- IoT:Sensor networks providing real-time visibility into shipment location, condition, and ETA across contracted carrier fleets.
- Automation:Robotic receiving, sortation, and put-away systems reducing dock labor dependency in high-volume facilities.
- Blockchain:Distributed ledger applications for supplier documentation and carbon emissions verification.
IoT leads on deployment breadth; AI is gaining share fastest.
Delivery Model:
Customer type and shipment profile dictate whether buyers outsource entirely or retain control over critical lanes.
- Third-party Logistics:Comprehensive outsourcing of inbound network design, execution, and optimization to specialized providers. EU Green Deal emissions disclosure requirements are pushing fleet operators toward 3PL partners with certified environmental management systems.
- Cross-docking:Flow-through facilities bypassing traditional distribution center storage to achieve dock-to-shelf velocity for grocery and big-box retail networks.
- Direct Fulfillment:Supplier-to-plant or supplier-to-store movements without intermediate consolidation.
- Pool Distribution:Consolidated receiving and break-bulk operations for fragmented supplier bases serving common destinations.
Third-party logistics retains dominant share; cross-docking shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing inbound logistics demand as manufacturers relocate production to jurisdictions with lower emissions compliance costs. The EU Green Deal's disclosure mandates and carbon border adjustments are accelerating this migration pattern.
Germany
Automotive just-in-sequence programs and dense supplier-to-plant corridors drive concentrated demand for time-definite inbound capacity. The EU Green Deal fleet mandates under KBA supervision are pushing carriers toward battery-electric tractor procurement for first-mile collections. Bavaria and Lower Saxony clusters generate the steepest requirements for synchronized supplier deliveries with hourly windows.
United States
EPA Phase 3 greenhouse gas standards are tightening tractor efficiency requirements for fleet operators serving automotive and industrial inbound lanes. E-commerce fulfillment networks are expanding contracted inbound services as order velocity rises. Midwest assembly plants and Southeast distribution hubs face the steepest compliance cost adjustments for long-haul routes from Mexico.
China
Dual carbon goals under MEE supervision are reshaping fleet procurement priorities for manufacturers serving export-oriented production zones. Dense industrial clustering in the Yangtze River Delta generates high-volume inbound corridors requiring multimodal coordination. Shanghai and Suzhou manufacturing belts are deploying ERP-integrated demand sensing to compress replenishment cycles.
Japan
METI industrial efficiency guidelines are accelerating adoption of AI-driven demand forecasting among automotive tier-1 suppliers. Pharmaceutical and electronics manufacturers require temperature-controlled inbound lanes with strict chain-of-custody documentation. The Kansai and Chubu industrial corridors maintain specialized just-in-time networks for precision component flows.
India
PLI scheme incentives are expanding manufacturing capacity and associated inbound logistics requirements across automotive and electronics sectors. BIS certification standards for warehousing infrastructure are elevating provider qualification barriers. Maharashtra and Gujarat industrial zones are developing dedicated supplier-to-plant freight corridors to serve new assembly investments.
Inbound Logistics Market Competitive Landscape
Established providers occupy the premium synchronization tier; emerging entrants pursue digital freight matching and specialized vertical niches. The market structure consolidates around integrated 3PL operators with multimodal assets while fragmenting across regional specialists and technology platforms. Three archetypes dominate: asset-heavy European network operators, North American digital brokers, and Asia-Pacific freight forwarders with strong customs capabilities. Competitive moves concentrate on M&A for geographic density and strategic partnerships for electric fleet deployment.
Within the integrated European network tier, DHL Supply Chain & Global Forwarding and DB Schenker exemplify asset-heavy operators with rail-road-barge multimodal capabilities. Kuehne + Nagel occupies a position bridging pharmaceutical specialization with global forwarding scale. These entities represent the premium-tier archetype where environmental certification and synchronized delivery windows determine contract awards.
| Leading Market Players |
|---|
| DHL Supply Chain & Global Forwarding |
| Kuehne + Nagel |
| DB Schenker |
| DSV |
| UPS Supply Chain Solutions |
| FedEx Logistics |
| C.H. Robinson |
| CEVA Logistics |
| Nippon Express |
| Others |
Pricing and Supply Chain Analysis
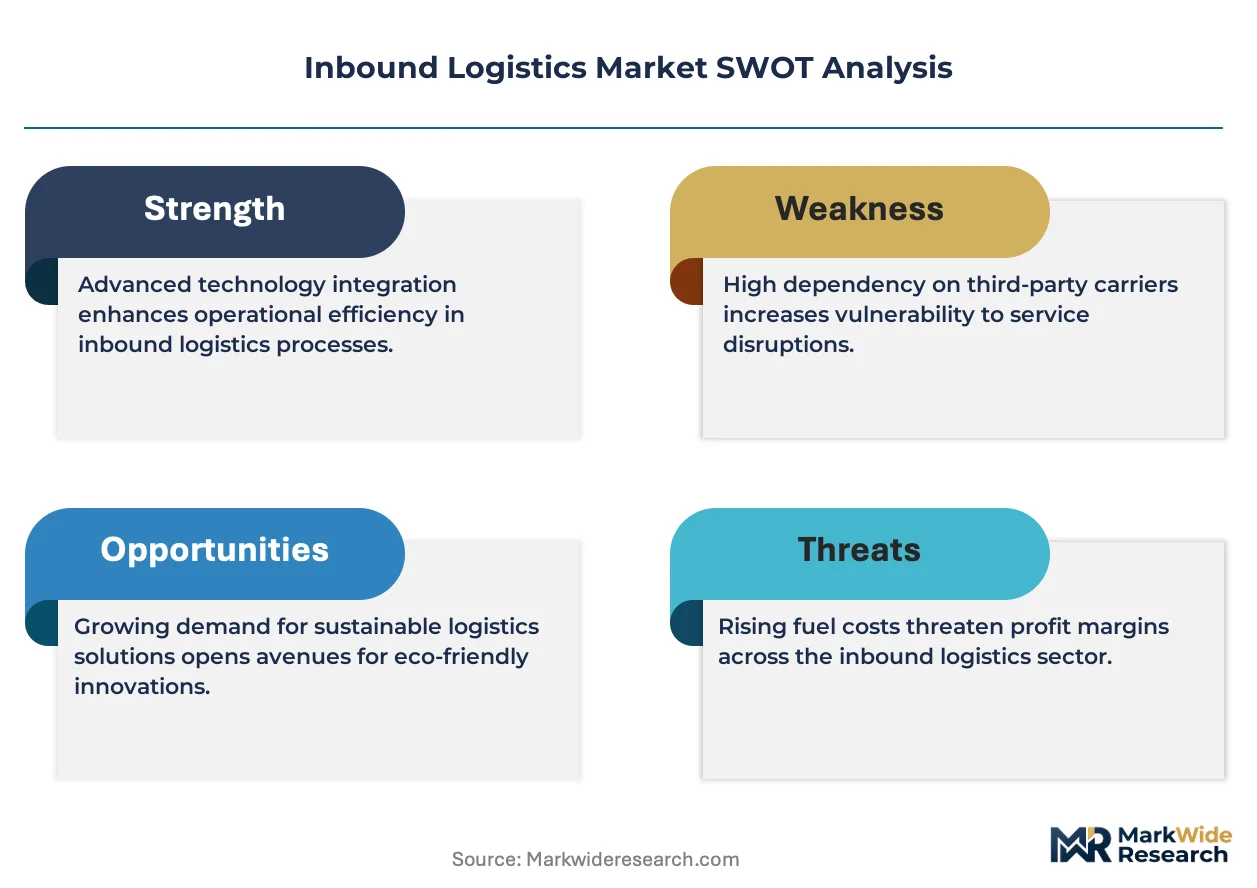
Certification-tier divergence between ISO 14001-certified operators and uncertified carriers manifests in both rate premiums and sourcing patterns. Buyers in Germany's automotive corridors pay differential rates for synchronized just-in-sequence capacity while routing procurement toward providers with verified environmental management systems.
Pricing Analysis
Distributor margins for third-party logistics providers compress under outcome-based contract structures that unbundle transport from inventory carrying. Three-tier pricing structure across premium synchronization, standard contract, and spot-market economy levels separates automotive OEMs paying for hourly delivery windows from retail buyers prioritizing dock-to-shelf velocity. Pricing pressure stems from ERP-integrated demand sensing tools that reduce safety stock buffers and shrink addressable inventory management revenue. Small and mid-sized manufacturers show highest price sensitivity, while Tier 1 automotive suppliers prioritize fill-rate guarantees over rate-per-mile negotiations.
Supply Chain Analysis
EU Green Deal domestic-content mandates for emissions disclosure are reshaping tractor procurement toward battery-electric and hydrogen alternatives. Supply concentration centers on Germany, Poland, and the Czech Republic for automotive component flows, with China dominating electric vehicle battery production for fleet electrification. Critical dependencies include vehicle-grade semiconductors, high-power charging infrastructure, and carbon-certified warehousing capacity. Single-source vulnerability runs through contracted carrier networks facing driver qualification pipeline constraints. Distribution runs through rail-road-barge multimodal corridors anchored at Rhine ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inbound logistics market functions as a regulatory compounder where EU Green Deal fleet mandates and EPA Phase 3 standards continuously reshape capital deployment and contract structures.
For Market Incumbents: To counter digital freight matching platforms compressing contract procurement cycles, DHL Supply Chain and Kuehne + Nagel should deepen rail-road-barge multimodal integration across Rhine corridors while accelerating ISO 14001 certification density to capture premium automotive just-in-sequence awards. For New Entrants and Emerging Players: Digital freight matching platforms offer the most penetrable entry vector for AI-driven lane optimization tools targeting mid-market manufacturers in Baden-Württemberg and Lower Saxony. Focus initial deployment on cross-docking penetration for grocery retail networks seeking dock-to-shelf velocity without legacy warehouse management system integration burdens. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional carriers lack electric fleet scale to meet EU Green Deal procurement requirements. Target acquisition archetypes include specialized temperature-controlled operators in pharmaceutical lanes and undercapitalized rail-road barge integrators in Rhine hinterlands. Watch battery-electric vehicle charging infrastructure buildout rates as the inflection signal for long-haul electrification viability.| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Road-Barge Multimodal Expansion | Reduces emissions for bulk automotive flows while meeting EU Green Deal disclosure requirements. |
| ISO 14001 Certification Acceleration | Qualifies providers for Bavaria and Lower Saxony OEM procurement with environmental audit mandates. |
| AI-Driven Demand Forecasting Deployment | Enables same-day replenishment triggers for Tier 1 suppliers compressing safety stock holdings. |
| Cross-Docking Facility Buildout | Captures grocery retail demand for flow-through velocity bypassing traditional distribution centers. |
| Battery-Electric Fleet Procurement | Positions carriers for KBA-supervised first-mile collections under tightening EU fleet mandates. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and India, with primary inputs from each market gathered through structured interviews. The research combines discussions with automotive procurement directors, 3PL operations managers, fleet electrification specialists, and warehouse management system integrators with secondary validation from KBA emissions filings, EPA Phase 3 regulatory dockets, EU Green Deal implementation guidelines, and customs trade data. Bottom-up carrier capacity assessments and top-down manufacturing output projections undergo triangulation to anchor volume estimates.
Granularity-level modeling disaggregates the market across service type, industry vertical, technology maturity, and delivery model dimensions. The analytical framework projects value expansion across the analysis window by linking automotive production schedules to inbound lane density requirements. CAGRs derive from correlated manufacturing output trajectories and fleet electrification investment cycles. Key inputs include just-in-sequence program adoption rates and ERP-integrated demand sensing penetration among Tier 1 suppliers.
The model assumes a particular technology adoption path for battery-electric tractors in first-mile collection routes; alternative pathways for hydrogen fuel cell deployment would alter the outlook for long-haul corridor economics. Forecasts reflect assumptions about semiconductor availability stabilizing and driver qualification pipelines recovering. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United Kingdom Freight and Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Europe Logistics Automation Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
Digital Logistics Market