
 Germany Third-Party Logistics (3PL) Market | 2026-2036
Germany Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Third-Party Logistics (3PL) Market Foresight
German freight forwarding capacity is shifting toward integrated digital platforms that synchronize multimodal networks. Hellmann Worldwide Logistics leverages its European road-rail hub network to sustain cross-border consolidation advantages. FIEGE Logistics anchors specialized contract logistics for industrial manufacturing clients across North Rhine-Westphalia. DHL Supply Chain & Global Forwarding competes through pharma-certified cold chain infrastructure that meets stringent temperature compliance standards.
Third-party logistics in Germany encompasses outsourced supply chain execution where providers manage transportation, warehousing, and inventory coordination through integrated information systems, typically operating warehouse management platforms with real-time inventory tracking and route optimization algorithms. The primary commercial purpose is to replace fixed logistics assets with variable-cost structures that improve working capital efficiency for shippers. Warehousing Solutions captures concentrated margin pools as e-commerce fulfillment demands same-day processing capabilities and automated sortation infrastructure. Transportation Management leads volume contribution but faces compressed yields from fuel cost pass-through mechanics and driver shortage premiums. Pharmaceutical Providers within Industry Vertical represent the fastest-growing demand cluster as serialization requirements and temperature-validated distribution create defensible specialization barriers.
The KBA enforces commercial vehicle emissions standards that directly shape fleet replacement cycles and alternative powertrain investment timelines for German road freight operators. REACH and the EU Green Deal mandate carbon footprint transparency across supply chain tiers, forcing 3PL customers to demand emissions reporting from contracted logistics partners. Stakeholders must monitor how the CSRD's scope-three disclosure requirements will restructure shipper procurement criteria and elevate certified green logistics providers in competitive tenders.
Market Dynamics
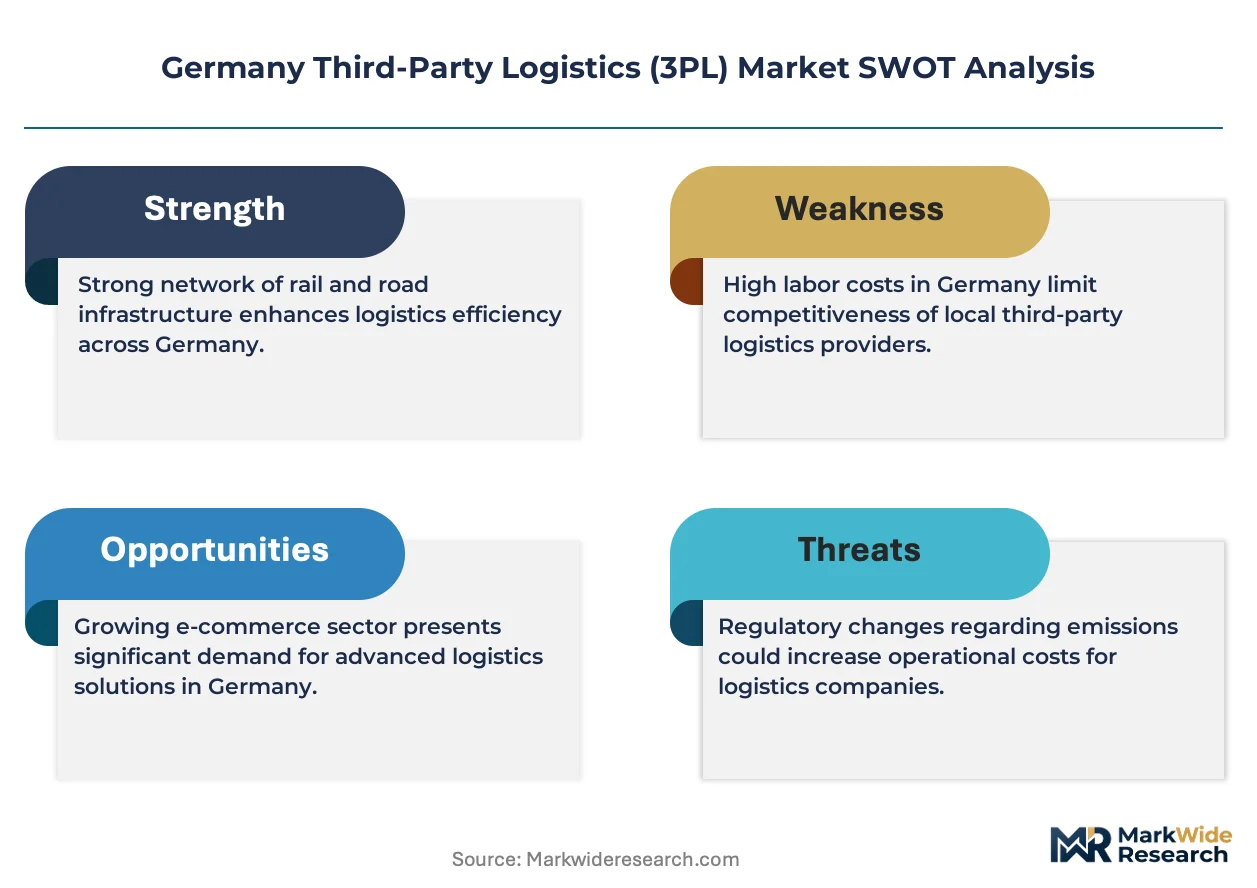
EU Green Deal emissions mandates are restructuring German 3PL fleet procurement, forcing diesel-to-electric conversion timelines that compress asset replacement cycles and reshape carrier economics across the Rhine-Ruhr corridor.
Growth Catalysts
- CSRD Scope-Three Disclosure:Mandatory carbon reporting across supply chain tiers elevates certified green logistics providers in competitive tenders, creating procurement preference for emissions-transparent 3PL partners.
- Automotive Just-in-Time Outsourcing:German OEMs are expanding contract logistics for complex sequencing operations, driving demand for synchronized inbound-to-assembly-line coordination.
- Pharmaceutical Serialization:EMA track-and-trace requirements for medicinal products generate specialized cold chain and compliance-validated distribution contracts with defensible margin structures.
Market Restraints
- Commercial Driver Shortage:Germany's Fachkräftemangel in logistics occupations inflates wage premiums and caps fleet utilization rates for road freight operators.
- Battery Supply Concentration:Dependence on Asian cell manufacturers for electric truck powertrains creates procurement bottlenecks and extended delivery timelines for fleet electrification programs.
- Grid Infrastructure Lag:Inadequate high-power charging density along Autobahn freight corridors delays full-electric long-haul deployment and forces hybrid transition architectures.
Strategic Opportunities
- Shared Urban Consolidation:Micro-hub networks in Berlin and Hamburg enable pooled last-mile delivery for mid-market retailers lacking standalone fulfillment infrastructure.
- Hydrogen Corridor Development:German government H2Mobility funding for heavy-duty fuel cell trucks opens early-mover positioning on Frankfurt-Dresden and Munich-Stuttgart routes.
- Reverse Logistics Specialization:E-commerce return volumes create dedicated processing facilities for apparel and electronics refurbishment workflows.
Industry Challenges
- Warehouse Automation Integration:Legacy WMS platforms require costly API redevelopment to synchronize with AMR fleets and automated sortation systems.
- Temperature Validation Certification:GDP compliance for pharmaceutical logistics demands documented cold chain integrity across multi-modal handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Third-Party Logistics (3PL) Market |
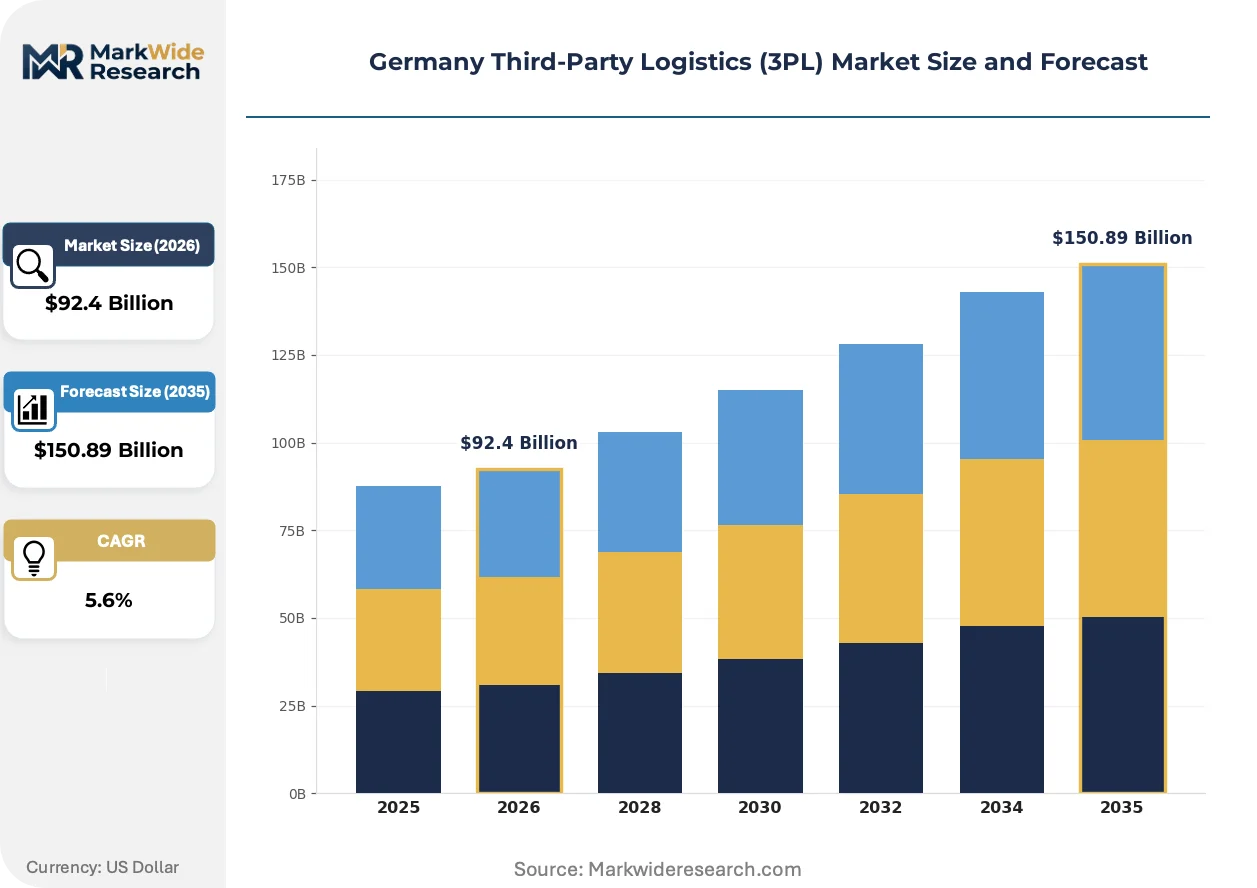
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $150.89 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation Management, Warehousing Solutions, Freight Forwarding, Distribution Services, Customs Brokerage Industry Vertical: Manufacturing Companies, E-commerce Sellers, Pharmaceutical Providers, Consumer Electronics, Food & Beverage Client Type: Large Enterprises, Small & Medium Enterprises, Startups, Government Agencies Distribution Channel: Direct Shipping, Cross Docking, Drop Shipping, Rail Freight, Air Cargo |
| Companies Covered | Hellmann Worldwide Logistics, FIEGE Logistics, DHL Supply Chain & Global Forwarding, DSV, Kuehne + Nagel, DB Schenker, Rhenus Logistics, CEVA Logistics, Dachser, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Third-Party Logistics (3PL) Market Shifts & Advancements
Digital freight platforms are consolidating previously fragmented carrier capacity, replacing phone-based brokerage with algorithmic load matching that compresses procurement cycles and exposes latent price transparency.
Artificial intelligence-driven predictive analytics is expanding into demand forecasting and dynamic route optimization. Mid-sized German manufacturers are adopting these tools to reduce safety stock buffers. The technology is expanding into inventory positioning decisions that previously relied on static reorder point systems.
REACH and EU Green Deal carbon footprint transparency mandates are forcing emissions data standardization across logistics tiers. Shippers now require Scope 3 disclosures from contracted 3PL providers. Pharmaceutical and automotive verticals in Baden-Württemberg and Bavaria are responding with dedicated sustainability procurement scorecards.
Shippers are consolidating vendor relationships toward integrated control-tower arrangements that bundle transportation, warehousing, and value-added services under single accountability. Discrete point solutions for freight forwarding or standalone warehousing are losing share to unified platform contracts. This concentration is most visible among German industrial exporters managing complex cross-border supply chains.
Germany Third-Party Logistics (3PL) Market Segmentation
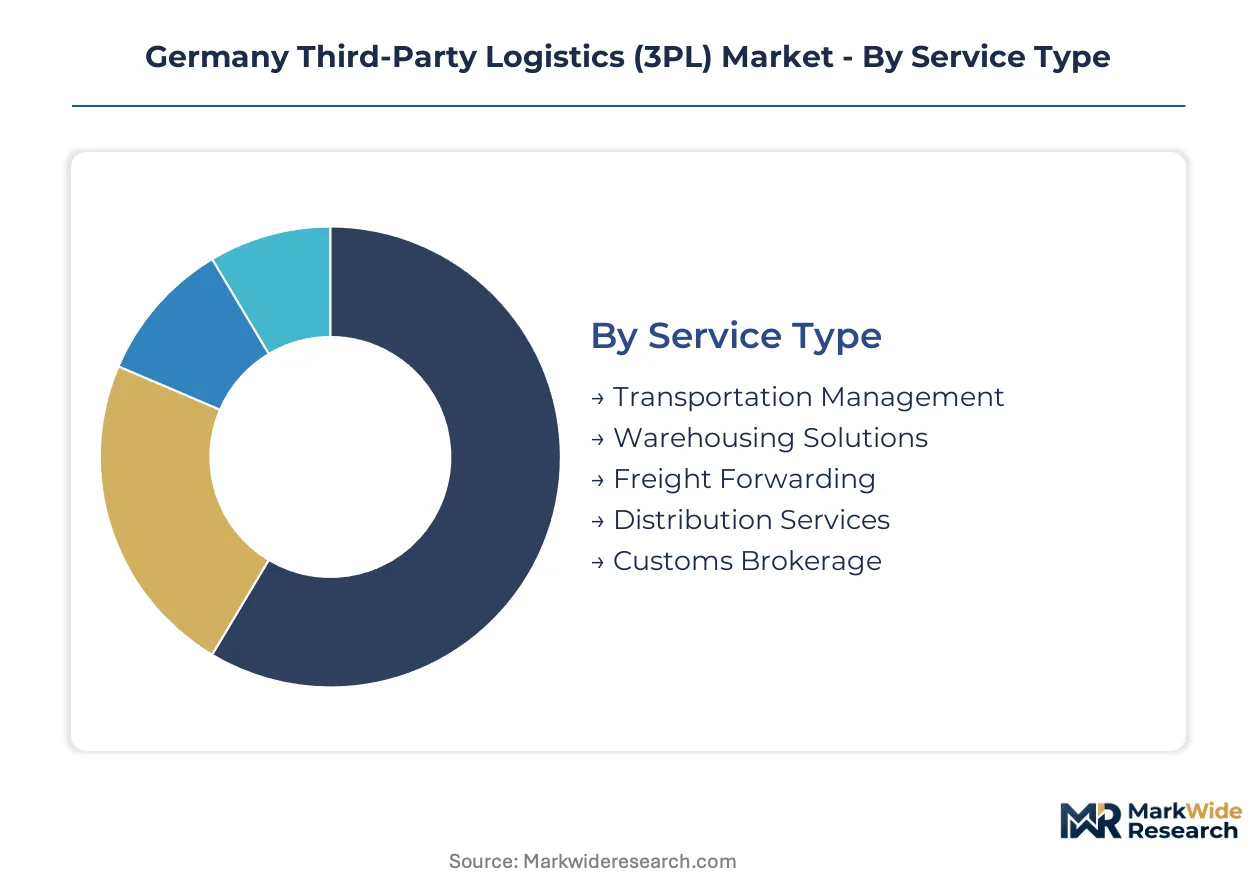
German 3PL segmentation reflects divergent margin structures across service types, with asset-heavy warehousing commanding premium pricing against transaction-based freight forwarding. Vertical specialization separates commodity logistics from defensible niches where regulatory compliance creates switching costs. Client scale determines contract structure, from enterprise control-tower arrangements to SME spot-market access.
Service Type:
Volume leadership sits with transportation execution, while warehousing captures concentrated margin pools through automation infrastructure.
- Transportation Management:Core service spans carrier procurement, freight audit, and route optimization across road-rail-air networks. Rhine-Ruhr manufacturing clusters generate dense lane density that supports dedicated fleet deployment and backhaul utilization.
- Warehousing Solutions:Encompasses inventory storage, order fulfillment, and automated sortation systems with real-time WMS integration. E-commerce fulfillment in Berlin and Hamburg demands same-day processing capabilities that justify robotics capex.
- Freight Forwarding:Cross-border documentation and multimodal coordination for international trade lanes.
- Distribution Services:Last-mile delivery networks with urban micro-hub configurations.
- Customs Brokerage:EU entry processing and duty optimization for non-European shippers.
Today's leader: Warehousing Solutions. Tomorrow's challenger: Transportation Management.
Industry Vertical:
Application intensity varies sharply, with pharmaceutical serialization requirements and automotive sequencing complexity driving specialized contract structures.
- Manufacturing Companies:Inbound supply chain coordination for just-in-time production systems. Baden-Württemberg automotive OEMs outsource sequencing operations to 3PL partners with EDI-linked assembly line synchronization.
- Pharmaceutical Providers:GDP-compliant cold chain distribution with temperature-validated handoff documentation. EMA track-and-trace mandates create defensible specialization barriers that protect margin structures.
- E-commerce Sellers:Peak-capacity fulfillment with returns processing integration.
- Consumer Electronics:High-velocity inventory turns with serial number tracking.
- Food & Beverage:Temperature-controlled distribution with shelf-life management protocols.
Pharmaceutical Providers expand most quickly on regulatory tailwinds. Manufacturing Companies retain volume dominance.
Client Type:
Contract scale determines service model, from integrated control-tower arrangements to transactional spot-market access.
- Large Enterprises:Multi-year contracts bundling transportation, warehousing, and value-added services under single accountability. Procurement teams in North Rhine-Westphalia consolidate vendor relationships toward unified platform arrangements.
- Small & Medium Enterprises:Shared warehousing and consolidated freight services that replace fixed asset investments with variable cost structures.
- Startups:Flexible fulfillment partnerships with minimal volume commitments.
- Government Agencies:Public procurement frameworks with sustainability scoring criteria.
Large Enterprises anchor current revenue. SMEs represent the steepest expansion trajectory as mid-market digital adoption accelerates.
Distribution Channel:
Modal selection reflects speed-cost tradeoffs, with rail gaining share on corridor electrification and Autobahn congestion.
- Direct Shipping:Point-to-point truckload movement bypassing intermediate handling. Bavarian industrial exporters favor direct lanes to Benelux ports for containerized export cargo.
- Cross Docking:Rapid freight consolidation with minimal inventory holding. Rhine-Ruhr hub networks enable overnight distribution across Central European markets.
- Drop Shipping:Vendor-fulfilled orders with 3PL-managed information flows.
- Rail Freight:Intermodal block trains on electrified corridors with terminal drayage.
- Air Cargo:Time-critical shipments through Frankfurt and Munich airport gateways.
Direct Shipping dominates tonnage. Rail Freight gains competitive ground on emissions compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping German logistics investment as emissions compliance costs create operational cost-of-compliance gaps between federal states, driving warehouse automation and fleet electrification toward jurisdictions with stronger grid infrastructure and subsidy density.
North Rhine-Westphalia
The Rhine-Ruhr metropolitan corridor generates Europe's densest freight lane concentration, with automotive and chemical clusters demanding synchronized inbound logistics. KBA commercial vehicle standards accelerate diesel-phaseout timelines for Cologne-based fleet operators. Duisburg's inland port anchors intermodal rail-road terminals serving Benelux export corridors.
Bavaria
Munich-Stuttgart manufacturing belt outsourcing drives contract logistics demand for precision sequencing operations. EU Green Deal funding programs support hydrogen corridor pilots along A9 Autobahn freight routes. Nuremberg's distribution hub network consolidates pharmaceutical cold chain flows for Central European markets.
Baden-Württemberg
Stuttgart automotive OEMs expand just-in-time logistics partnerships to manage powertrain component flows. REACH chemical handling mandates shape specialized warehousing requirements for Ludwigshafen industrial chemical producers. Karlsruhe's tech corridor incubates AI-driven predictive logistics platforms for SME manufacturers.
Hamburg
Port-centric logistics demand concentrates around containerized import-export flows and Scandinavian trade lanes. CSRD scope-three disclosure requirements elevate emissions-transparent providers in procurement tenders. Billwerder's urban micro-hub network enables pooled last-mile consolidation for mid-market e-commerce retailers.
Berlin-Brandenburg
E-commerce fulfillment demand drives same-day processing infrastructure investment in peripheral warehouse zones. Grid infrastructure lag delays full-electric long-haul deployment, forcing hybrid transition architectures. Schönefeld's air cargo gateway supports time-critical pharmaceutical and electronics shipments.
Germany Third-Party Logistics (3PL) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital freight brokerage and last-mile electrification niches. The vendor base stratifies across integrated control-tower operators, specialized vertical logistics providers, and asset-light platform intermediaries. Three archetypes dominate: automotive-sequencing specialists, pharma-certified cold chain operators, and digital freight marketplaces. Competitive moves concentrate on fleet electrification partnerships and warehouse automation capex cycles.
Among Germany-based integrated providers, Hellmann Worldwide Logistics, FIEGE Logistics, and DHL Supply Chain & Global Forwarding occupy positions across distinct service tiers. Hellmann exemplifies the European road-rail hub network archetype with cross-border consolidation capabilities. FIEGE represents specialized contract logistics positioning anchored in industrial manufacturing verticals. DHL Supply Chain & Global Forwarding sits within the premium infrastructure tier, with pharma-certified cold chain assets that meet GDP compliance standards for temperature-validated distribution.
| Leading Market Players |
|---|
| Hellmann Worldwide Logistics |
| FIEGE Logistics |
| DHL Supply Chain & Global Forwarding |
| DSV |
| Kuehne + Nagel |
| DB Schenker |
| Rhenus Logistics |
| CEVA Logistics |
| Dachser |
| Others |
Supply & Pricing Matrix
German automotive OEM procurement teams in Baden-Württemberg and Bavaria negotiate multi-year control-tower contracts that bundle transportation, warehousing, and sequencing services under single-accountability pricing models. This buyer concentration favors integrated providers capable of absorbing fuel cost volatility through scale-backed fuel hedging while passing automation efficiency gains through to contract renewals.
Pricing Analysis
Distributor margins for freight forwarding services compress under algorithmic load-matching platforms that expose latent price transparency across the Rhine-Ruhr corridor. Contract logistics providers command premium pricing through GDP certification tiers and automated sortation infrastructure investments that justify per-pallet handling premiums. Price erosion runs through spot-market road freight as digital brokerage platforms disintermediate traditional carrier relationships. SME shippers exhibit highest price sensitivity, while pharmaceutical manufacturers accept cost premiums for temperature-validated distribution integrity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart automotive clusters requiring synchronized inbound-to-assembly-line coordination. Battery cell supply concentrates in China, South Korea, and Japan, creating procurement bottlenecks for German fleet electrification programs. Lithium-ion cells, electric drivetrain components, and high-power charging hardware anchor critical input dependencies. Single-source vulnerability in Asian cell manufacturing threatens fleet conversion timelines. Distribution runs through intermodal rail-road terminals at Duisburg and Cologne with terminal drayage to final assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German 3PL margin expansion hinges on warehouse automation capex cycles that reduce labor intensity per pallet handled, alongside premium-tier shifts toward pharma-certified cold chain services that command defensible pricing structures.
For Market Incumbents: Extend automation infrastructure deployment in North Rhine-Westphalia to capture e-commerce fulfillment density while consolidating fragmented SME relationships through shared warehousing platforms. Digital freight brokerages threaten traditional forwarding margins; respond by deepening control-tower integration that embeds 3PL partners into shipper ERP systems. Vertical integration into last-mile electric fleet ownership creates differentiation against asset-light intermediaries. For New Entrants and Emerging Players: Enter via urban micro-hub networks in Berlin and Hamburg where mid-market retailers lack standalone fulfillment infrastructure and procurement teams prioritize flexibility over scale. Shared consolidation services for apparel and electronics returns processing represent the most penetrable white-space segment. Position through sustainability scorecard compliance that meets CSRD scope-three disclosure requirements for emissions-transparent procurement. For Investors and Strategic Acquirers: Logistics technology platforms with AI-driven predictive analytics capabilities are the most active acquirer category in this space, seeking tuck-in automation specialists and last-mile electrification assets. Long-term viability favors providers with defensible vertical specialization in pharmaceutical or automotive sequencing workflows. Monitor KBA commercial vehicle emissions standard revisions as inflection indicators for fleet replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Scale-Up | Robotics capex in Berlin fulfillment centers reduces same-day processing labor costs per order. |
| Electric Fleet Conversion Program | Battery supply agreements with Asian cell manufacturers secure powertrain allocation for Rhine-Rugh routes. |
| Pharma Certification Investment | GDP-compliant cold chain infrastructure captures EMA track-and-trace contract opportunities. |
| Digital Platform Integration | API-linked WMS synchronization embeds 3PL providers into shipper inventory planning systems. |
| Shared Urban Consolidation Network | Micro-hub pooling in Hamburg enables mid-market retailer access without fixed asset commitment. |
Research Methodology
Coverage spans Germany's federal states with primary inputs from each, combining structured interviews with logistics operations directors, procurement leads at automotive OEMs, freight forwarding brokers, warehouse automation engineers, and pharmaceutical supply chain managers with secondary validation. Trade lane data from the Federal Statistical Office, KBA commercial vehicle registration records, EU Green Deal implementation tracking, and customs declarations provided foundational inputs. Bottom-up service-type volume estimates triangulated against top-down regional economic output metrics.
Granularity-level modeling disaggregated transportation management, warehousing solutions, freight forwarding, and distribution services by industry vertical and client type across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points including CSRD disclosure mandates and KBA emissions phaseout timelines. Automotive sequencing complexity, pharmaceutical serialization requirements, and e-commerce fulfillment velocity served as sector-specific demand drivers.
Inputs from logistics provider financial disclosures and federal transport ministry datasets were available through the study window; gaps in SME spot-market transaction data introduce uncertainty bands around freight forwarding yield estimates. Forecasts reflect documented assumptions regarding electrification investment timelines and battery supply availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Latin America Air Freight Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Cold Chain Logistics Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
On-Demand Logistics Market
Logistics and Shipping
India less than Truckload Road Freight Transport Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Global Sea Air Logistics Market