
 North America Wireless Electric Vehicle Charging Market | 2026-2036
North America Wireless Electric Vehicle Charging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wireless Electric Vehicle Charging Market Analytics
High-power specification tiers above 11 kW is bifurcating the competitive landscape as fleet operators demand faster throughput. WiTricity Corporation leverages its magnetic resonance patent portfolio to dominate licensing agreements with major automakers. InductEV Inc. specializes in dynamic charging applications for transit buses, anchoring its position in the commercial fleet segment. Momentum Dynamics Corporation controls high-power inductive systems for commercial vehicles, differentiating through extreme fast-charging capabilities.
Wireless electric vehicle charging transfers electrical energy across an air gap through electromagnetic induction or magnetic resonance coupling, typically operating at frequencies between 20–85 kHz with coil alignment tolerances up to several inches. The technology eliminates physical connectors, reducing wear while enabling automated charging for autonomous and fleet vehicles. Static chargers command the largest installed base among product types, though dynamic chargers embedded in roadways represent the fastest-growing segment as highway pilot projects multiply. Commercial fleets generate the highest revenue intensity among end users due to utilization rates and total cost of ownership advantages, while residential installations remain limited by vehicle availability and price premiums.
The U.S. Department of Transportation's National Electric Vehicle Infrastructure program and the Federal Communications Commission's spectrum allocations for wireless power transfer shape deployment economics and technical standards across the region. Health Canada's radiation safety guidelines and the Society of Automotive Engineers' J2954 wireless charging standard govern product certification and interoperability requirements. Stakeholders must monitor regulatory harmonization between U.S. and Canadian technical standards, as divergence in certification pathways would fragment procurement for cross-border fleet operators and infrastructure developers.
Market Dynamics
Fleet electrification mandates from California's Advanced Clean Trucks regulation and Canada's federal zero-emission vehicle sales targets are compressing deployment timelines for inductive charging infrastructure across commercial vehicle corridors.
Growth Catalysts
- California's Advanced Clean Trucks mandate:Medium- and heavy-duty fleet operators must transition to zero-emission vehicles by 2036, creating immediate demand for automated charging solutions that minimize vehicle downtime.
- SAE J2954 standard harmonization:Interoperability specifications for ground assembly and vehicle assembly alignment are reducing technical barriers to cross-platform deployment.
- Dynamic charging pilot corridors:Highway embedded systems in Michigan's automotive testing zones and Utah's innovation districts are validating continuous power transfer for long-haul electrification.
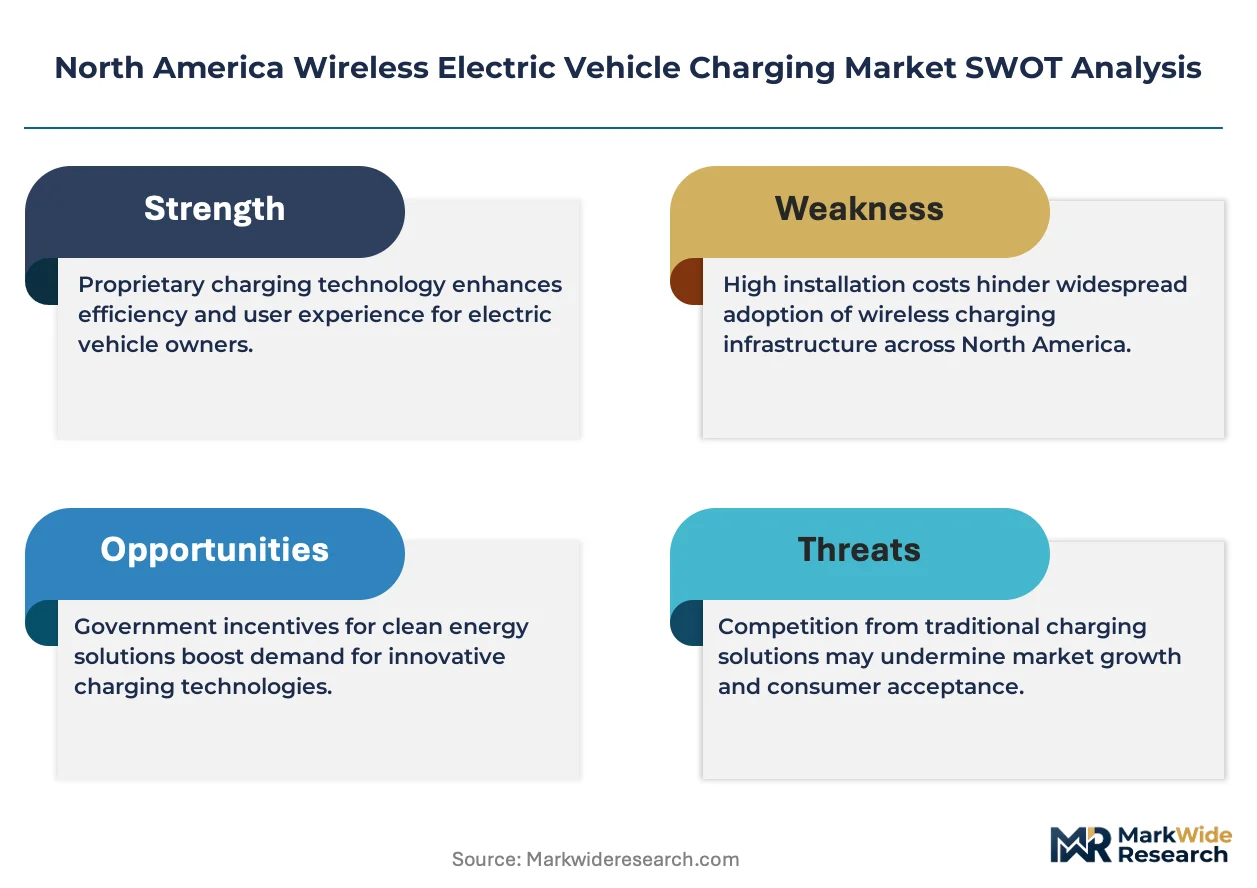
Market Restraints
- Copper and ferrite core volatility:Magnetic coupling components face raw material price swings that compress hardware margins for coil and inverter manufacturers.
- Single-source magnetics suppliers:High-frequency ferrite core production concentrates among Japanese and Chinese specialty ceramic producers, creating geographic supply risk.
- Power transfer efficiency ceiling:Air-gap losses in inductive systems cap system efficiency below conductive fast-charging benchmarks, limiting appeal to efficiency-sensitive operators.
Strategic Opportunities
- Texas freight corridors:The state's deregulated utility market and absence of winter weather infrastructure damage create favorable economics for dynamic charging highway pilots.
- Autonomous vehicle integration:Self-driving commercial fleets require fully automated energy replenishment without human connector handling.
- Inflation Reduction Act tax credits:Section 30C alternative fuel vehicle refueling property incentives now explicitly cover wireless charging hardware installation costs.
Industry Challenges
- Electromagnetic compatibility certification:FCC Part 18 industrial, scientific and medical equipment authorization timelines extend 8-14 months for novel coil geometries.
- Utility interconnection queues:Distribution system impact studies for high-power static installations in California and New York delay commercial activation by 12-24 months.
- Patent licensing fragmentation:Magnetic resonance intellectual property spreads across university-held foundational patents and corporate improvement claims, complicating royalty stacking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wireless Electric Vehicle Charging Market |
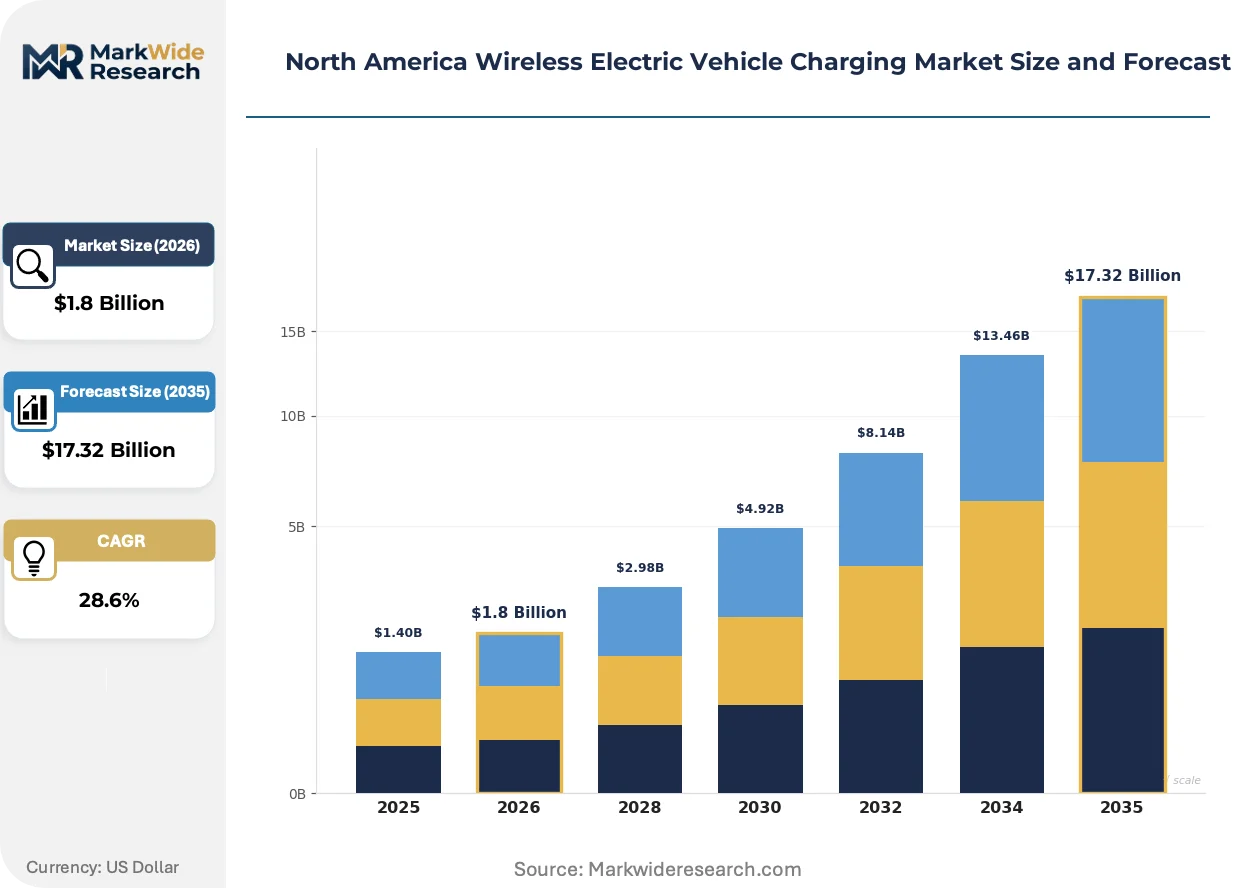
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Chargers, Dynamic Chargers, Hybrid Systems, Mobile Chargers End User: Residential Users, Commercial Fleets, Public Transport, Taxi Services Technology: Inductive Charging, Capacitive Charging, Resonant Charging, Magnetic Charging Installation Type: On-street Installation, Off-street Installation, Home Installation, Commercial Installation |
| Companies Covered | WiTricity Corporation, InductEV Inc., Plugless Power Inc., HEVO Inc., Electreon, Momentum Dynamics Corporation, Qualcomm Technologies, Evatran Group, ENRX, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wireless Electric Vehicle Charging Market Evolving Landscape
Magnetic resonance architectures are displacing earlier inductive coupling designs as power levels rise above 11 kW, while regulatory pressure on fleet emissions accelerates automated charging deployment timelines.
High-power magnetic resonance systems is bifurcating the competitive landscape as fleet operators demand faster throughput. Commercial bus operators and last-mile delivery fleets are adopting 300 kW+ ground assemblies to enable opportunity charging during route layovers. This technology compression is forcing hardware suppliers to choose between licensing premium resonance designs or competing on cost with legacy inductive architectures.
The U.S. Department of Transportation's National Electric Vehicle Infrastructure program is directing $5 billion toward corridor charging with technical standards that now incorporate wireless power transfer specifications. State transportation departments must include inductive charging readiness in highway right-of-way planning. California and Michigan DOTs are prioritizing wireless-enabled rest stop and transit hub deployments in their NEVI formula funding allocations.
Acquisition patterns among commercial fleet managers are rotating toward total-cost-of-ownership contracts that bundle charging infrastructure with vehicle procurement. Leasing companies and energy service providers are displacing direct hardware purchases as the dominant transaction structure. This shift concentrates most visibly in California's urban transit agencies and Ontario's municipal bus operators, where public-private partnerships now structure 10-15 year service agreements encompassing vehicles, charging hardware, and energy management.
North America Wireless Electric Vehicle Charging Market Segmentation
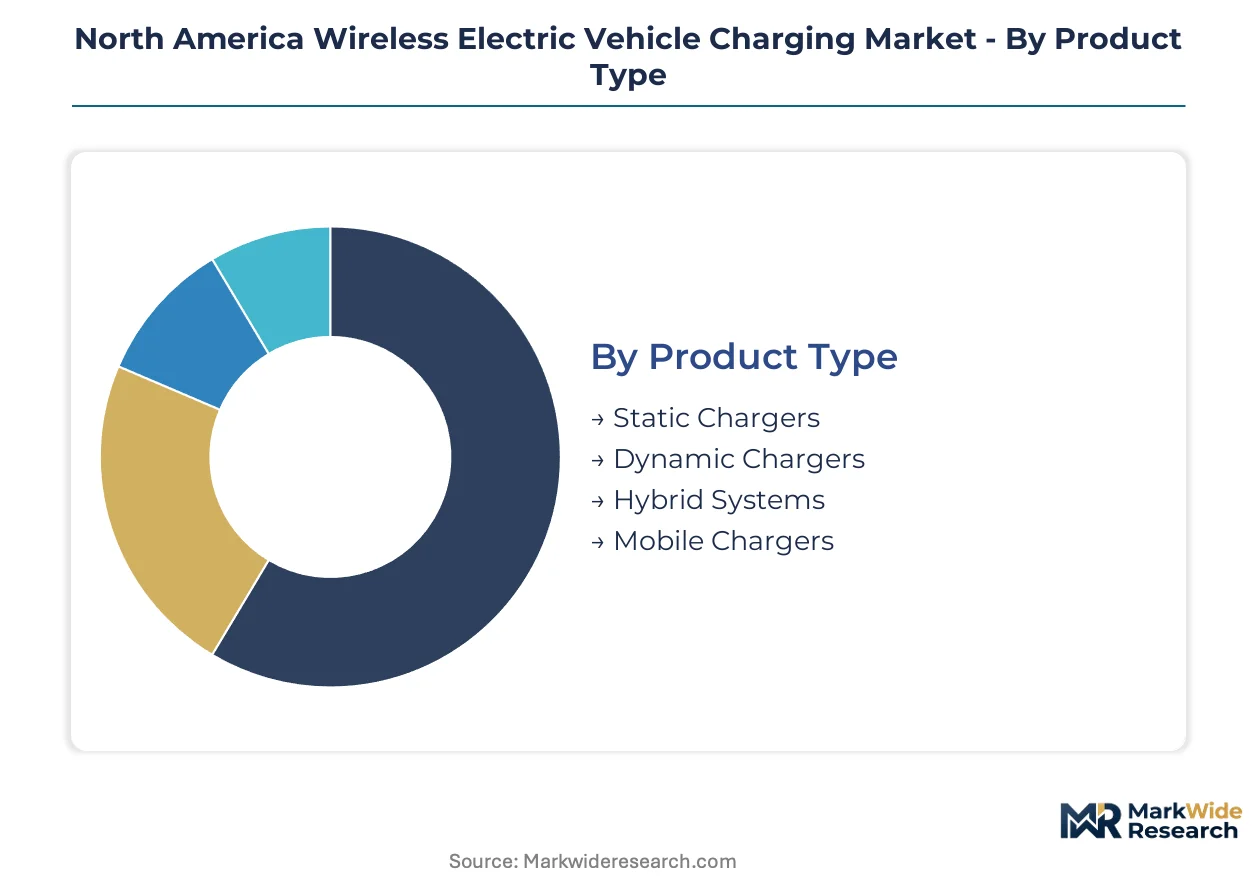
Wireless EV charging segments diverge sharply across deployment maturity and capital intensity. Product architecture and installation economics determine which configurations attract infrastructure funding versus fleet procurement.
Product Type:
Domestic demand concentrates in static systems for fleet depots, while dynamic charging pilots draw cross-border technology investment into Michigan and Utah corridors.
- Static Chargers:Stationary ground assemblies transfer power to parked vehicles through fixed coil alignment. California transit agencies and Ontario municipal bus operators anchor procurement volume through 10-15 year service agreements bundling hardware with energy management.
- Dynamic Chargers:Roadway-embedded coil arrays enable continuous power transfer to moving vehicles. The U.S. Department of Transportation's NEVI program directs corridor funding toward highway pilots validating long-haul electrification without stopping.
- Hybrid Systems:Dual-mode architectures combine static depot charging with limited dynamic capability for queue exits.
- Mobile Chargers:Portable ground assemblies relocate between temporary fleet staging areas.
Static chargers command the established base. The steepest expansion runs through dynamic chargers.
End User:
Cost tier stratification separates capital-intensive fleet operators from price-sensitive residential adopters.
- Commercial Fleets:Last-mile delivery operators and regional trucking companies generate revenue intensity through high utilization rates. California's Advanced Clean Trucks mandate compresses deployment timelines for automated charging that minimizes vehicle downtime.
- Public Transport:Electric bus operators demand 300 kW+ ground assemblies for opportunity charging during route layovers. Michigan and Ontario transit agencies structure public-private partnerships covering vehicles and infrastructure.
- Taxi Services:Ride-hail electrification programs in California and Texas urban cores pilot wireless taxi stands.
- Residential Users:Home garage installations remain limited by vehicle availability and hardware price premiums.
Commercial fleets dominate revenue contribution. Residential uptake trails pending cost reduction.
Technology:
Volume concentration favors mature inductive architectures, though magnetic resonance gains share above 11 kW power thresholds.
- Magnetic Charging:High-frequency magnetic resonance coupling operates at 20-85 kHz with coil alignment tolerances up to several inches. Fleet operators above 11 kW specifications favor this architecture for faster throughput.
- Inductive Charging:Electromagnetic induction through tightly coupled coils dominates legacy installations and lower-power residential applications.
- Resonant Charging:Tuned LC circuits optimize efficiency at specific power bands for specialized commercial deployments.
- Capacitive Charging:Electric field coupling through plate electrodes remains experimental for low-power applications.
Magnetic charging captures the fastest technology transition. Inductive systems retain the largest installed footprint.
Installation Type:
Application context determines whether utility interconnection queues or municipal permitting creates the binding constraint.
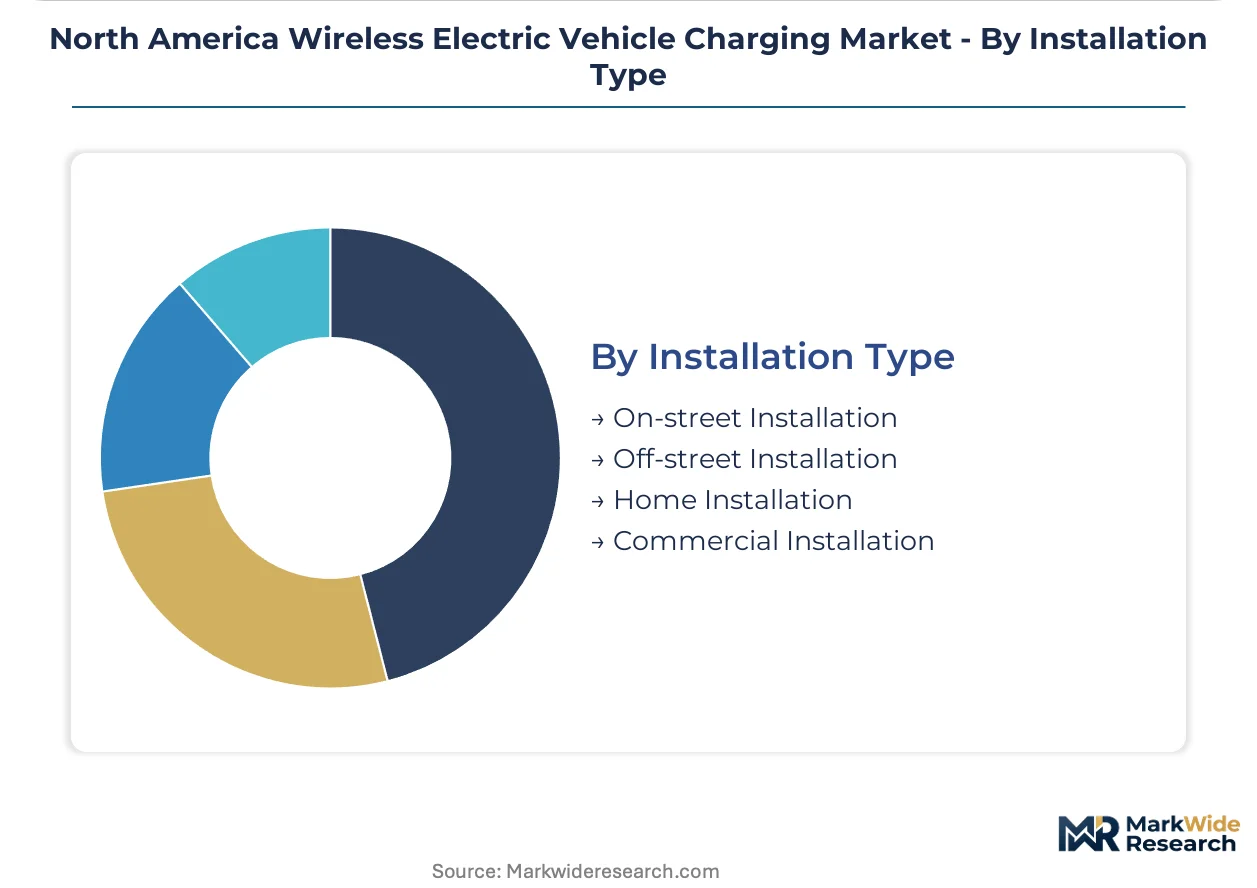
- Commercial Installation:Fleet depot and transit hub deployments face 12-24 month distribution system impact studies in California and New York. SAE J2954 standard harmonization reduces technical barriers to cross-platform deployment.
- On-street Installation:Curbside ground assemblies in urban transit corridors require municipal right-of-way agreements and FCC Part 18 equipment authorization.
- Off-street Installation:Parking structure retrofits concentrate in Michigan automotive manufacturing clusters.
- Home Installation:Residential garage systems encounter limited vehicle integration and consumer price sensitivity.
Commercial installations absorb the majority of capital deployment. Home installation penetration remains marginal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patent licensing networks and automotive manufacturing clusters concentrate wireless EV charging development across North America. The U.S. Department of Transportation's NEVI program and Health Canada's infrastructure funding shape deployment economics. California, Michigan, and Ontario transit corridors anchor commercial fleet adoption.
United States
California's Advanced Clean Trucks mandate drives medium- and heavy-duty fleet electrification with 2036 zero-emission deadlines. The FCC's Part 18 equipment authorization governs coil geometry approvals for 20-85 kHz systems. Michigan's automotive testing zones host dynamic charging pilot corridors validating continuous power transfer.
Canada
Ontario's municipal bus operators structure 10-15 year public-private partnerships bundling vehicles and charging infrastructure. Health Canada's radiation safety guidelines govern product certification alongside SAE J2954 interoperability standards. Quebec's urban transit agencies pilot wireless-enabled depot charging for electric bus fleets.
Mexico
Nuevo León's manufacturing clusters attract cross-border supply chain investment for magnetic coupling components. The country's national automotive regulator aligns technical standards with U.S. FCC and SAE frameworks to enable export compatibility. Mexico City Metro explores on-street wireless taxi stand pilots in dense urban corridors.
North America Wireless Electric Vehicle Charging Market Competitive Landscape
Concentration sits with magnetic resonance patent holders and high-power system specialists. The competitive structure bifurcates between licensing-heavy technology developers and hardware-integrated infrastructure deployers. Two strategic archetypes dominate: IP-centric resonance technology licensors and turnkey fleet charging integrators. Technology licensing agreements and long-term service contracting represent the dominant competitive moves.
Within the IP-centric tier, WiTricity Corporation exemplifies patent portfolio leverage for automaker partnerships. InductEV Inc. and Momentum Dynamics Corporation occupy positions in high-power commercial vehicle applications. These three entities represent the archetype spectrum from foundational magnetic resonance licensing through extreme fast-charging hardware deployment.
| Leading Market Players |
|---|
| WiTricity Corporation |
| InductEV Inc. |
| Plugless Power Inc. |
| HEVO Inc. |
| Electreon |
| Momentum Dynamics Corporation |
| Qualcomm Technologies |
| Evatran Group |
| ENRX |
| Others |
Value Network & Pricing Analysis
Ferrite core substitution for amorphous metal alloys in high-frequency magnetics is redrawing supplier geography toward East Asian ceramic producers while compressing hardware margins for North American coil manufacturers. This materials transition simultaneously concentrates procurement leverage among Japanese and Chinese specialty suppliers and intensifies cost pressure on ground assembly integrators bidding for California transit agency contracts.
Pricing Analysis
SAE J2954 certification tiers dictate the pricing tier structure across static and dynamic charging systems. Premium-mid-economy pricing differentiation separates resonance-based fleet installations from legacy inductive depot hardware. Cost compression in standard-tier ground assemblies is intensifying because copper and ferrite price volatility erodes inverter manufacturer margins. Municipal bus operators exhibit the highest price sensitivity due to public procurement constraints, while autonomous fleet integrators prioritize throughput over unit economics.
Supply Chain Analysis
Tsugaru Strait transit underwrites magnetics supply security for ferrite core shipments from Japanese producers to North American coil winding facilities. Component sourcing draws from Japan, China, and South Korea for high-frequency ferrite, copper litz wire, and silicon carbide power modules. Single-source vulnerability concentrates in Japanese amorphous metal ribbon production for next-generation magnetic coupling. Distribution runs through Tier 1 automotive supplier networks and direct utility infrastructure procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across California and Ontario transit agencies is shifting procurement leverage toward long-term service contract bundling. This buyer concentration compresses hardware vendor margins while elevating energy service providers.
For Market Incumbents: Fortify patent licensing revenue streams against magnetic resonance architecture commoditization by deepening backward integration into ferrite core supply. Secure captive supply agreements with Japanese ceramic producers before amorphous metal transition accelerates. Defend position by embedding hardware-software integration into 10-15 year fleet service contracts that raise switching costs for transit agency customers. For New Entrants and Emerging Players: Anchor in Texas freight corridor pilots where deregulated utility markets and absence of winter infrastructure damage create favorable dynamic charging economics. Target autonomous vehicle fleet integrators requiring fully automated energy replenishment without connector handling. Pursue white-label manufacturing partnerships with established magnetics suppliers to bypass 8-14 month FCC Part 18 authorization timelines. For Investors and Strategic Acquirers: The market sits at a standards-convergence phase that favors IP-centric technology licensors over hardware-integrated deployers. Long-term viability hinges on magnetic resonance patent portfolio breadth and utility interconnection relationship depth. Monitor SAE J2954 revision cycles as the inflection signal for interoperability-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Patent Portfolio Licensing | WiTricity's resonance IP agreements with Detroit Three automakers establish royalty revenue baselines. |
| Dynamic Charging Highway Pilots | Michigan DOT and Utah innovation district deployments validate continuous power transfer for long-haul electrification. |
| Utility Interconnection Partnerships | Direct relationships with California IOUs bypass 12-24 month distribution impact study queues. |
| SAE J2954 Certification Investment | Ground assembly interoperability compliance unlocks cross-platform procurement from fragmented fleet operators. |
| Backward Integration into Magnetics | In-house ferrite core sourcing mitigates Japanese and Chinese supplier concentration risk. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, utility interconnection planners, automotive platform engineers, and wireless charging hardware procurement leads and refined through secondary validation against SEC filings of public charging infrastructure deployers, FCC Part 18 equipment authorization databases, U.S. DOT NEVI funding allocation disclosures, and SAE technical committee meeting records. Bottom-up deployment projections triangulated against top-down addressable fleet vehicle counts.
Variance decomposition across power level tiers, installation type categories, and end-user segments shaped the analytical framework throughout the forecast period. CAGRs emerged from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs incorporated California Advanced Clean Trucks mandate compliance timelines, Inflation Reduction Act Section 30C credit utilization patterns, and magnetic resonance technology adoption curves above 11 kW thresholds.
Decision-makers should treat outputs as directional under assumptions of SAE J2954 harmonization continuity and stable copper-ferrite pricing; material deviation in regulatory alignment or raw material costs would warrant model refresh. Practitioners should keep alternative scenarios live as FCC spectrum allocation rulings and utility interconnection queue reform evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Used EV Market