
 Spain Third-Party Logistics (3PL) Market | 2026-2036
Spain Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Third-Party Logistics (3PL) Market Insights
Biodegradable packaging films are expanding their share in pharmaceutical and food-grade logistics, cutting unit-level waste costs for temperature-sensitive shipments. XPO Logistics leverages its Iberian hub network to dominate cross-border road freight into France and Portugal. DB Schenker sustains competitive positioning through specialized automotive parts sequencing for OEM plants near Pamplona and Vitoria-Gasteiz. Carcaba anchors regional competitiveness with deep expertise in perishable goods handling across Galicia's seafood export corridor.
Third-party logistics encompasses outsourced supply chain management functions including warehousing, inventory control, transportation coordination, and value-added services performed by external providers rather than in-house fleets. Temperature-controlled warehousing with multi-zone climate segmentation between two and eight degrees Celsius serves Spain's pharmaceutical and fresh produce export requirements. Transportation services command the largest value pool within service type segmentation, driven by fragmented shipper bases and fuel cost pass-through structures. E-commerce applications within the application dimension are absorbing fulfillment capacity fastest, pressuring last-mile node density around Madrid, Barcelona, and Valencia.
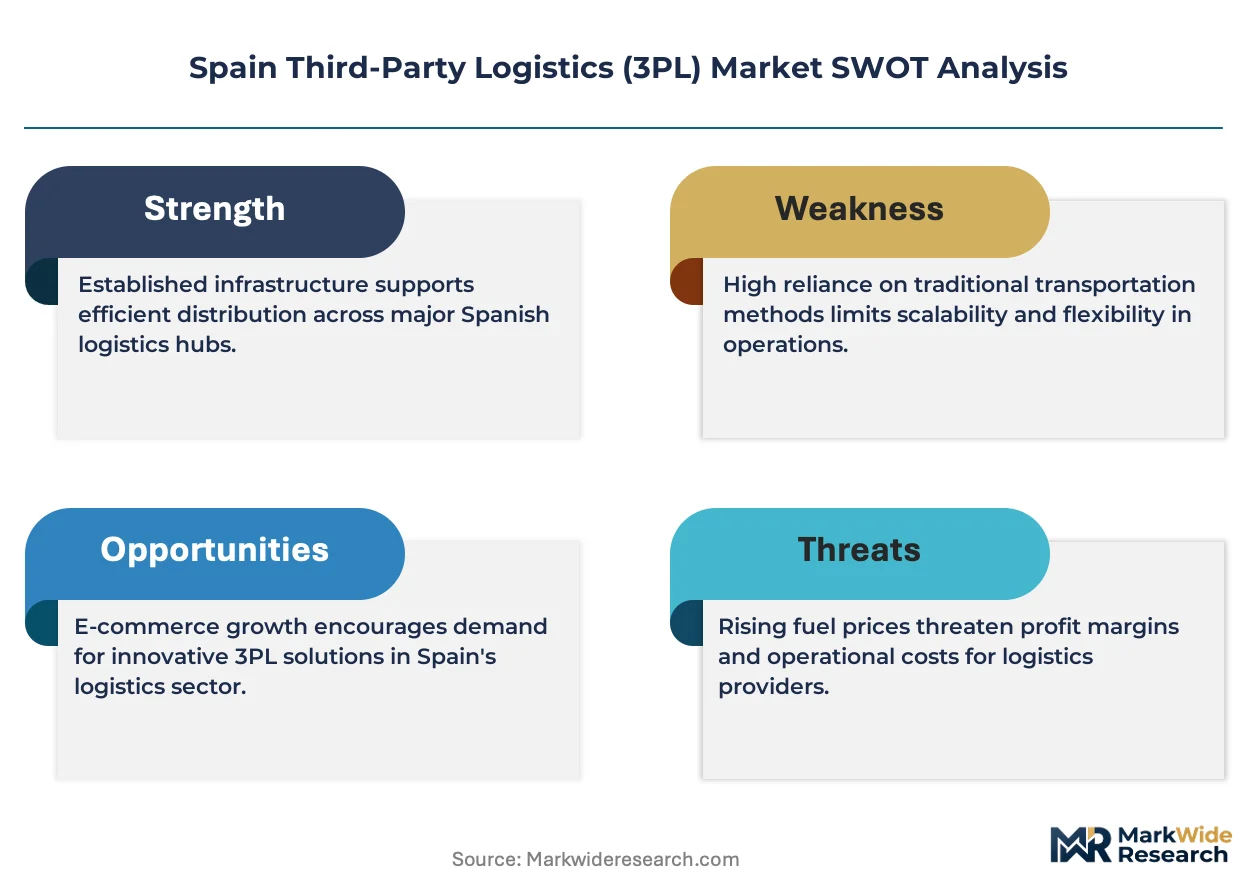
Spain's Sustainable Mobility Law and EU Green Deal emissions frameworks are mandating progressive fleet decarbonization, reshaping capital allocation toward electric and alternative-fuel vehicles. The country's national transport regulator and port authorities enforce driver hour limits and maritime emissions standards that filter directly into operator cost structures and service pricing. Stakeholders must monitor regulatory enforcement timing and charging infrastructure rollout pace to calibrate fleet investment cycles against compliance deadlines.
Market Dynamics
Spain's Sustainable Mobility Law and EU Green Deal emissions standards are forcing fleet electrification timelines that compress capital cycles and reshape operator economics across Iberian logistics corridors.
Growth Catalysts
- Cold-chain pharmaceutical outsourcing:Temperature-sensitive biologics manufacturing in Catalonia and Madrid is pulling specialized 3PL capacity for two-to-eight-degree Celsius warehousing and last-mile distribution.
- EU Green Deal fleet mandates:Progressive decarbonization deadlines under the EU Green Deal are accelerating operator investment in electric and alternative-fuel vehicle fleets.
- E-commerce fulfillment density:Online retail absorption of warehouse space is driving last-mile node construction around Madrid, Barcelona, and Valencia.
Market Restraints
- Charging infrastructure gaps:Uneven electric vehicle charging rollout across Spain's interior corridors extends payback periods for fleet electrification capex.
- Driver hour enforcement:Spain's national transport regulator enforces strict driving limits that constrain capacity expansion without proportional labor cost increases.
- Fuel cost pass-through volatility:Diesel price fluctuations transmit directly into road freight pricing, squeezing margin predictability for fixed-contract shippers.
Strategic Opportunities
- Basque Country automotive sequencing:OEM supplier parks near Pamplona and Vitoria-Gasteiz present white space for just-in-time parts logistics specialization.
- Galicia perishable exports:Seafood and fresh produce corridors from Vigo and A Coruña lack sufficient temperature-controlled consolidation capacity for Asian market expansion.
- Cross-border Iberian integration:Portugal-Spain freight corridors remain operationally fragmented, offering consolidation plays for bilingual fleet operators.
Industry Challenges
- Certified cold-chain technician scarcity:GDP (Good Distribution Practice) compliance for pharmaceutical logistics requires specialized training pipelines that lag demand growth in Madrid and Barcelona.
- Multi-zone warehouse retrofit costs:Legacy ambient facilities face steep capex burdens to install segmented climate control for pharmaceutical and food-grade coexistence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Third-Party Logistics (3PL) Market |
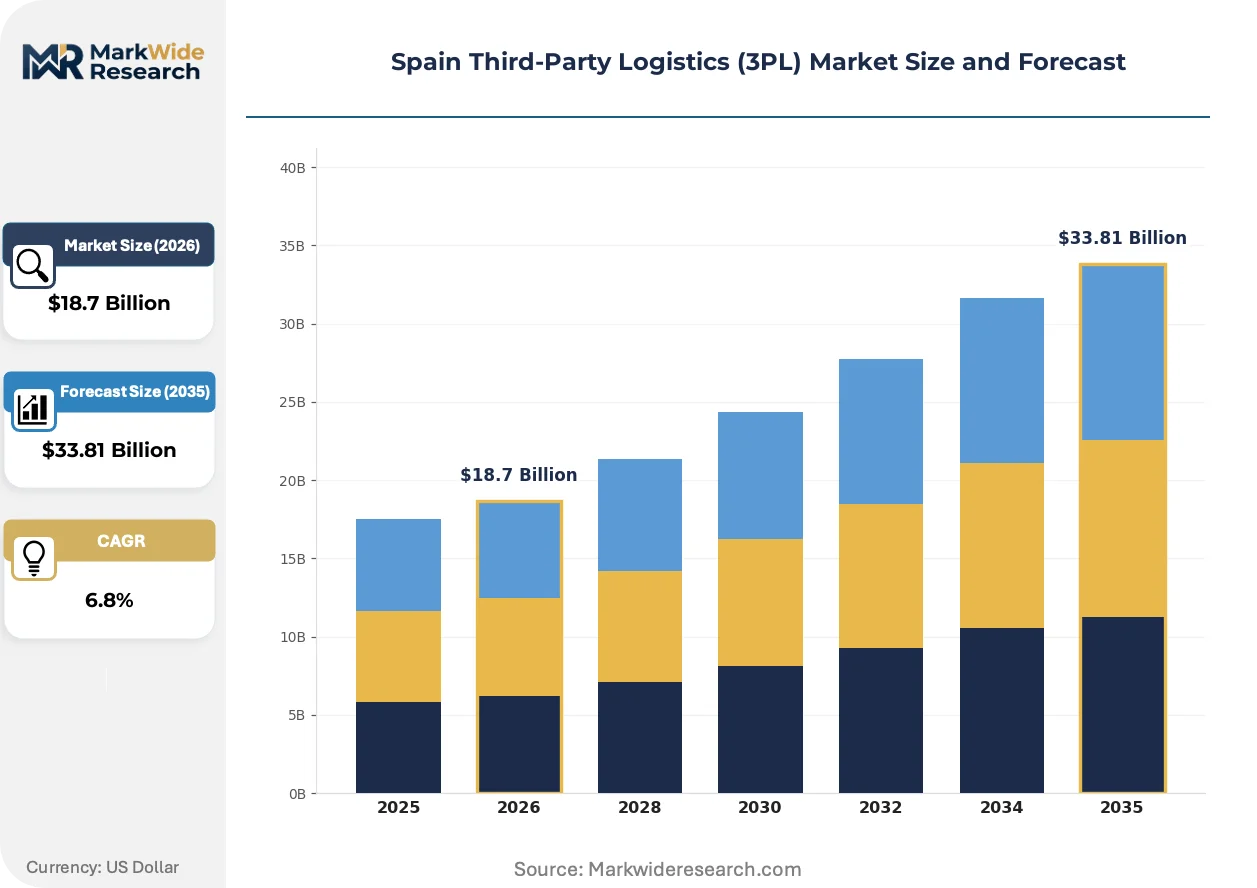
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Order Fulfillment, Cross-Docking Industry Vertical: Retail, Automotive, Healthcare, Consumer Electronics Application: Food & Beverage, E-commerce, Pharmaceuticals, Durable Goods Delivery Mode: Road, Rail, Air, Sea |
| Companies Covered | XPO Logistics, Group CAT, DB Schenker, Carcaba, Naeko, CEVA Logistics, Rhenus Logistics, TIBA, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Third-Party Logistics (3PL) Market Trends and Innovations
Digital freight platforms and warehouse automation are compressing operational response times while regulatory pressure on emissions intensifies capital allocation toward electrified assets and renewable-powered facilities.
Telematics-integrated fleet management is unifying real-time vehicle tracking, driver performance analytics, and predictive maintenance scheduling into single-platform architectures. Mid-sized road freight operators in the Barcelona-Valencia corridor are adopting these systems fastest. This convergence is unifying previously siloed dispatch and compliance functions, reducing administrative overhead per shipment.
The EU Green Deal emissions standards are tightening maritime and road transport carbon intensity thresholds that filter directly into port authority levies and fleet renewal timelines. Logistics operators must now synchronize vehicle procurement cycles with charging infrastructure deployment schedules. Pharmaceutical and fresh produce exporters face the steepest compliance cost adjustments due to temperature-controlled energy demands.
Shippers are consolidating vendor relationships around full-service 3PL partners capable of bundling warehousing, transport, and value-added services under single accountability structures. Fragmented single-service providers in Spain's interior regions are losing share to integrated operators with Iberian hub networks. Automotive suppliers in the Basque Country are driving this consolidation most aggressively through multi-year outsourcing contracts.
Spain Third-Party Logistics (3PL) Market Segmentation
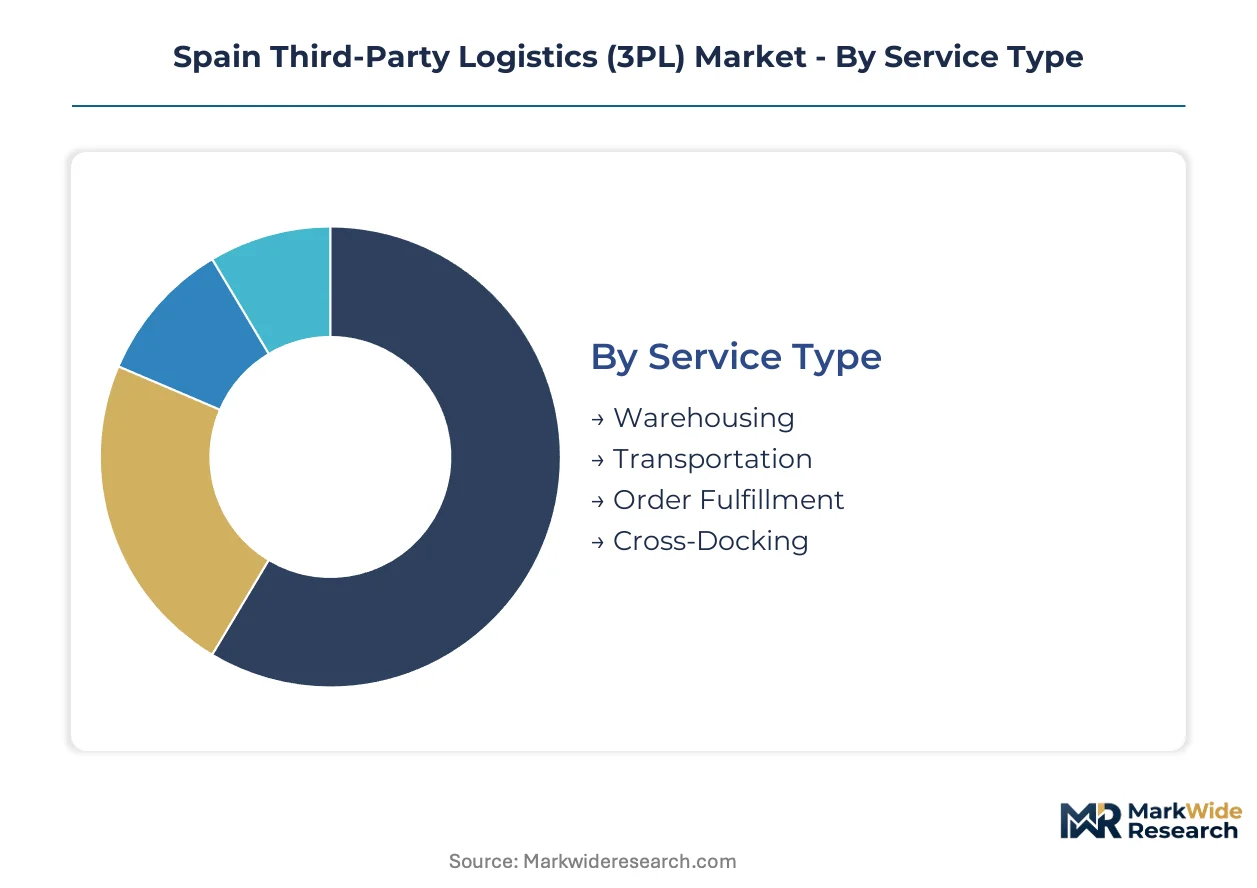
3PL segmentation in Spain reveals distinct capital intensity and margin profiles across service types, with fleet electrification mandates and cold-chain compliance reshaping where operators allocate resources. Each dimension carries specific regulatory and infrastructure dependencies that determine competitive positioning.
Service Type:
Replacement cycles for warehouse automation and fleet assets are compressing as EU Green Deal deadlines force synchronized capital deployment across service lines.
- Transportation:Road freight dominates value capture through fuel cost pass-through mechanisms and fragmented shipper bases. Fleet operators around Madrid and Barcelona face compressed electrification timelines under Spain's Sustainable Mobility Law.
- Warehousing:Multi-zone climate facilities with segmented two-to-eight-degree Celsius capabilities serve pharmaceutical and fresh produce exporters. Retrofit costs for legacy ambient sites are steep in Catalonia's dense industrial zones.
- Order Fulfillment:E-commerce absorption is driving last-mile node construction with bilingual workforce requirements for cross-border Iberian coverage.
- Cross-Docking:Port-linked consolidation near Valencia and Algeciras reduces inventory holding costs for automotive and consumer electronics flows.
Volume placements concentrate in Transportation; the faster expansion belongs to Warehousing as temperature-controlled retrofit demand accelerates.
Industry Vertical:
Margin structures diverge sharply across verticals, with automotive and healthcare commanding premium pricing for compliance-intensive services while retail operates on volume-scaled economics.
- Automotive:Just-in-time parts sequencing for OEM supplier parks near Pamplona and Vitoria-Gasteiz requires precision timing and dedicated fleet allocation. Basque Country corridors anchor specialized 3PL competitiveness.
- Healthcare:GDP-certified cold-chain handling for temperature-sensitive biologics manufacturing in Madrid and Barcelona carries technician scarcity constraints and training pipeline lags.
- Retail:Seasonal volume volatility and promotional surge capacity absorb flexible warehousing across Madrid's distribution ring.
- Consumer Electronics:High-value density shipments favor security-enhanced transport with real-time tracking integration.
Revenue concentration sits with Automotive sequencing contracts; Healthcare logistics is climbing the fastest on biologics outsourcing expansion.
Application:
End-use demand patterns are fragmenting as e-commerce fulfillment requirements diverge from traditional B2B distribution in facility specifications and labor models.
- E-commerce:Same-day and next-day delivery promises are pressuring node density around Madrid, Barcelona, and Valencia with reverse logistics complexity.
- Pharmaceuticals:Cold-chain integrity for biologics exports to Asian markets requires GDP-compliant warehousing with redundant backup power systems in Catalonia.
- Food & Beverage:Perishable consolidation capacity from Vigo and A Coruña seafood corridors lacks sufficient temperature-controlled infrastructure for export scaling.
- Durable Goods:Bulk handling and value-added assembly services concentrate in port-adjacent zones near Valencia for furniture and appliance distribution.
Facility utilization peaks in E-commerce; Pharmaceuticals application is gaining share fastest on export compliance requirements.
Delivery Mode:
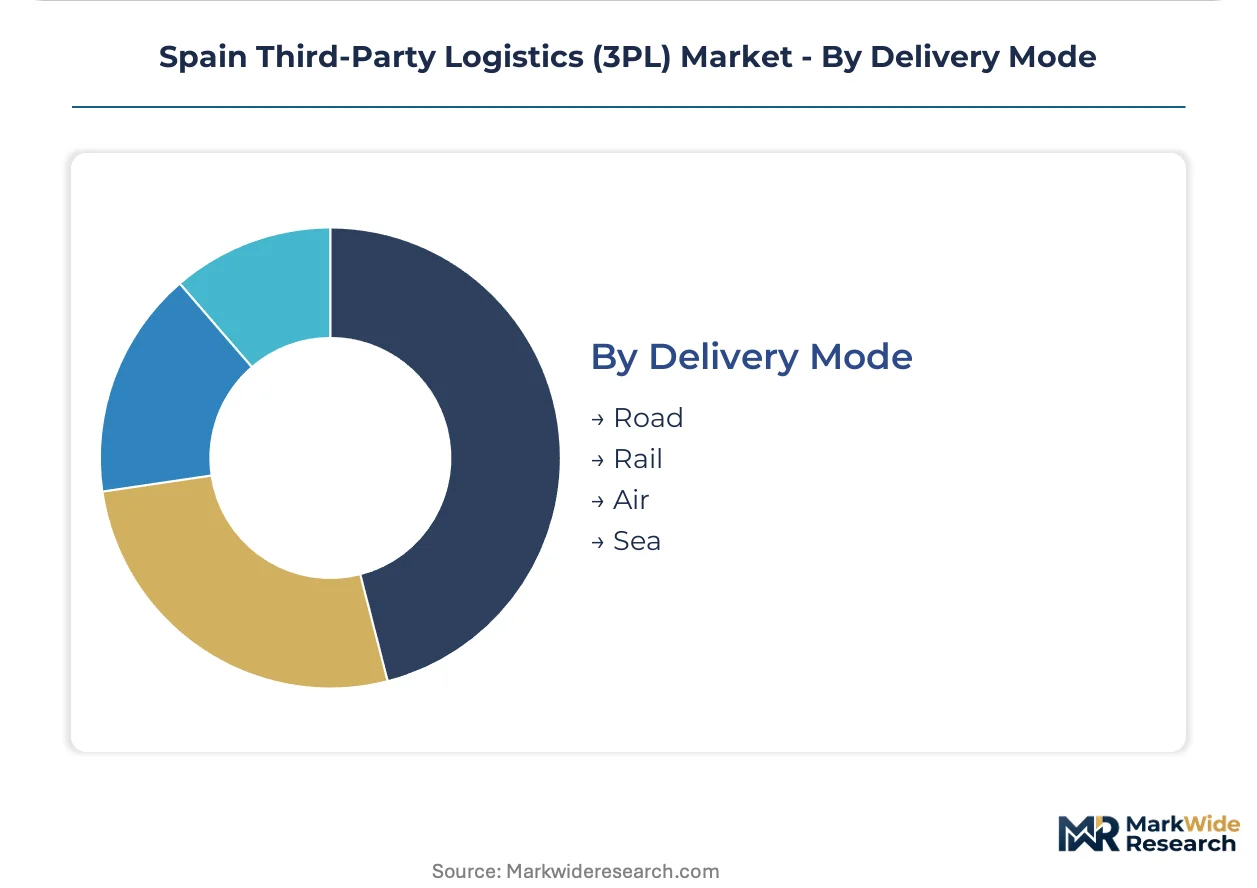
Infrastructure maturity and emissions compliance costs are rebalancing modal selection away from diesel-dependent road toward rail and short-sea alternatives on specific corridors.
- Road:Dominant mode for Iberian cross-border freight with driver hour enforcement under Spain's national transport regulator constraining effective capacity expansion.
- Sea:Short-sea shipping from Algeciras and Valencia reduces road mileage for containerized flows to Northern Europe with lower carbon intensity per ton-kilometer.
- Rail:Modal shift incentives are building on Madrid-Barcelona and Madrid-Valencia corridors with terminal handling cost barriers remaining.
- Air:Premium express and pharmaceutical cold-chain shipments concentrate at Madrid-Barajas and Barcelona-El Prat with emissions surcharges rising.
Tonnage movements center on Road; Rail is expanding most quickly on corridor electrification and modal shift subsidies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's 3PL demand concentrates in automotive corridors, pharmaceutical clusters, and port-linked industrial zones. Regulatory pressure from the EU Green Deal and Spain's Sustainable Mobility Law is redistributing logistics investment across sub-regions with uneven charging infrastructure maturity.
Madrid
Pharmaceutical biologics manufacturing and central government procurement drive specialized cold-chain demand. Spain's national transport regulator enforces strict driver hour limits that constrain last-mile capacity expansion. The Madrid distribution ring absorbs seasonal retail surges through flexible warehousing contracts.
Catalonia
Temperature-sensitive exports to Asian markets require GDP-compliant warehousing with redundant backup power systems. The EU Green Deal emissions standards accelerate fleet electrification timelines for Barcelona-anchored operators. Dense industrial zones around the city face steep retrofit costs for multi-zone climate facilities.
Basque Country
Just-in-time automotive parts sequencing for OEM supplier parks near Pamplona and Vitoria-Gasteiz demands precision timing and dedicated fleet allocation. Spain's Sustainable Mobility Law mandates progressive decarbonization that reshapes capital cycles for regional operators. The corridor anchors specialized 3PL competitiveness through multi-year outsourcing contracts.
Valencia
Port-linked consolidation for consumer electronics and automotive flows reduces inventory holding costs. Maritime emissions standards under EU Green Deal frameworks filter into port authority levies. E-commerce fulfillment node construction pressures bilingual workforce availability for cross-border Iberian coverage.
Galicia
Seafood and fresh produce export corridors from Vigo and A Coruña lack sufficient temperature-controlled consolidation capacity. The region's perishable handling expertise competes for Asian market expansion opportunities. Carcaba anchors regional competitiveness through deep specialization in this export corridor.
Spain Third-Party Logistics (3PL) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated operators capturing volume from fragmented single-service providers. The market structure favors full-service 3PL partners capable of bundling warehousing, transport, and value-added services under single accountability. Three archetypes dominate: Iberian hub-network operators, automotive sequencing specialists, and perishable goods handlers. Consolidation plays and fleet electrification capex cycles represent the dominant competitive moves reshaping operator economics.
Within the hub-network tier, XPO Logistics represents scale-driven cross-border integration, while DB Schenker occupies a position among automotive sequencing specialists serving OEM supplier parks. Carcaba exemplifies the perishable goods archetype with regional concentration in Galicia's seafood export corridor. These three companies anchor the competitive landscape across distinct service specializations.
| Leading Market Players |
|---|
| XPO Logistics |
| Group CAT |
| DB Schenker |
| Carcaba |
| Naeko |
| CEVA Logistics |
| Rhenus Logistics |
| TIBA |
| DSV |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM supplier parks near Pamplona and Vitoria-Gasteiz anchor the most concentrated buyer base, locking in multi-year sequencing contracts that favor fixed-rate pricing with fuel escalation clauses over spot-market volatility. Pharmaceutical biologics manufacturers in Madrid and Barcelona command premium GDP-certified service tiers where compliance costs outweigh price sensitivity in vendor selection.
Pricing Analysis
Volume-scaled road freight contracts absorb margin compression from diesel pass-through mechanisms, while temperature-controlled warehousing commands premium pricing tiers tied to GDP certification levels. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cold-chain from ambient retail distribution and bulk automotive sequencing. Cost compression in standard-tier road freight is intensifying because fleet electrification capex cycles compress operator returns before charging infrastructure matures. Retail e-commerce shippers exhibit highest price sensitivity; biologics exporters show least sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
GDP certification and EU Green Deal emissions compliance function as dual gating mechanisms that filter supplier eligibility for pharmaceutical and automotive verticals. Equipment manufacturing for electric fleet assets draws from Germany, China, and South Korea; cold-chain refrigeration systems rest on Danish and German component suppliers. Single-source vulnerability concentrates in battery cell supply for electrified last-mile fleets. Distribution runs through Iberian hub networks with cross-docking nodes at Valencia and Algeciras port complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain 3PL market is becoming a vertical-integration race as operators pursue captive control over charging infrastructure and cold-chain technician training pipelines to defend margin structures against compliance cost inflation.
For Market Incumbents: To counter charging infrastructure gaps that extend fleet electrification payback periods, accelerate bilateral partnerships with grid operators for depot-level fast-charging installation ahead of EU Green Deal enforcement timelines. Secure GDP-certified technician training pipelines through vocational institute partnerships in Madrid and Barcelona to preempt compliance scarcity. For New Entrants and Emerging Players: Digital freight platforms targeting cross-border Iberian fragmentation offer the most penetrable entry vector. White-space concentrates in bilingual fleet coordination for Portugal-Spain corridors and perishable consolidation capacity from Vigo and A Coruña. Galicia seafood export corridors lack sufficient temperature-controlled infrastructure for Asian market scaling. For Investors and Strategic Acquirers: The window for entry favors mid-sized automotive sequencing specialists with established OEM supplier park relationships and unencumbered fleet electrification timelines. Long-term viability hinges on operators with demonstrated compliance execution under Spain's Sustainable Mobility Law. Monitor charging infrastructure deployment pace in interior corridors as inflection indicator for fleet asset valuation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Secures depot charging infrastructure ahead of EU Green Deal deadlines in Madrid and Barcelona corridors. |
| GDP Certification Investment | Unlocks pharmaceutical biologics warehousing contracts with redundant backup power systems in Catalonia. |
| Cross-Border Iberian Integration | Captures consolidation value from fragmented Portugal-Spain freight coordination through bilingual fleet deployment. |
| Automotive Sequencing Specialization | Locks in multi-year OEM contracts near Pamplona and Vitoria-Gasteiz supplier parks. |
| Perishable Export Capacity Buildout | Addresses temperature-controlled infrastructure gaps for Galicia seafood corridor Asian market expansion. |
Research Methodology
Independent corroboration across logistics fleet operators, pharmaceutical supply chain directors, and automotive procurement leads underwrites the qualitative findings. Primary interviews with warehouse automation engineers, cold-chain compliance officers, and port authority planning staff combined with secondary validation from Spain's national transport regulator disclosures, EU Green Deal implementation documents, and customs trade flow databases. Bottom-up service line sizing and top-down macroeconomic anchoring provided cross-check triangulation.
Comparable historical periods spanning pre-pandemic baseline through regulatory transition phases anchored the projection framework across the analysis window. Segmentation dimensions modeled include service type, industry vertical, application, and delivery mode with regional regulatory cluster differentiation. CAGRs derived from logistic curve fitting to electrification adoption S-cycles and cold-chain capacity expansion timelines. Forecast inputs incorporated fleet replacement cycle compression and charging infrastructure rollout schedules without year-specific assumptions.
The model holds under steady EU Green Deal enforcement progression and diesel price pass-through stability; deviation in subsidy withdrawal timing or grid congestion at depot locations would shift fleet economics. Forecasts reflect documented assumptions around technician training pipeline scaling and multi-zone warehouse retrofit cost curves. A model refresh is warranted upon material change in Spain's Sustainable Mobility Law implementation deadlines or charging infrastructure deployment pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market