
 Intelligent Remote Terminal Unit Market | 2026-2036
Intelligent Remote Terminal Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Remote Terminal Unit Market Intelligence
A shortage of technicians skilled in both operational technology and IT network security is unwinding traditional deployment models for critical infrastructure monitoring. This creates an opening for vendors offering more integrated, user-friendly solutions. Siemens AG leverages its deep domain expertise in industrial automation to offer comprehensive iRTU systems for utilities. Rockwell Automation differentiates through its focus on secure network architecture and robust integration within its broader control systems.
An intelligent remote terminal unit (iRTU) is a microprocessor-based device that provides remote monitoring and control of distributed assets. These units feature onboard processing capabilities, often executing logic similar to a Programmable Logic Controller (PLC), to enable autonomous decision-making at the network edge. Among applications, substation automation and pipeline control command significant investment. Demand from electric utilities remains the largest end-user segment, driven by grid modernization and reliability projects.
Regulatory frameworks are increasingly focused on the cybersecurity of critical infrastructure, shaping iRTU design and deployment. Compliance with standards such as NERC CIP in the United States and the EU's NIS2 Directive mandates robust security features. These regulations compel operators to invest in devices with advanced encryption and secure boot capabilities. Future vendor differentiation will hinge on balancing enhanced edge processing capabilities with interoperability within legacy SCADA ecosystems.
Market Dynamics
The convergence of operational technology (OT) with information technology (IT) networks is the central force shaping the market. This integration, driven by the need for enhanced data analytics and remote management, concurrently introduces significant cybersecurity vulnerabilities that are redefining iRTU design priorities.
Growth Catalysts
- Grid Modernization Mandates:National-level investments in smart grid infrastructure, particularly in China and India, are creating sustained demand for iRTUs to enable automation and improve electrical grid reliability and efficiency.
- Standardization Efforts:The implementation of communication protocols like IEC 61850 for power utility automation provides a common framework, simplifying interoperability between devices from different manufacturers and accelerating project deployments.
- Renewable Energy Integration:The distributed nature of solar and wind power generation requires advanced monitoring and control points at the grid edge, a core function fulfilled by intelligent remote terminal units.
Market Restraints
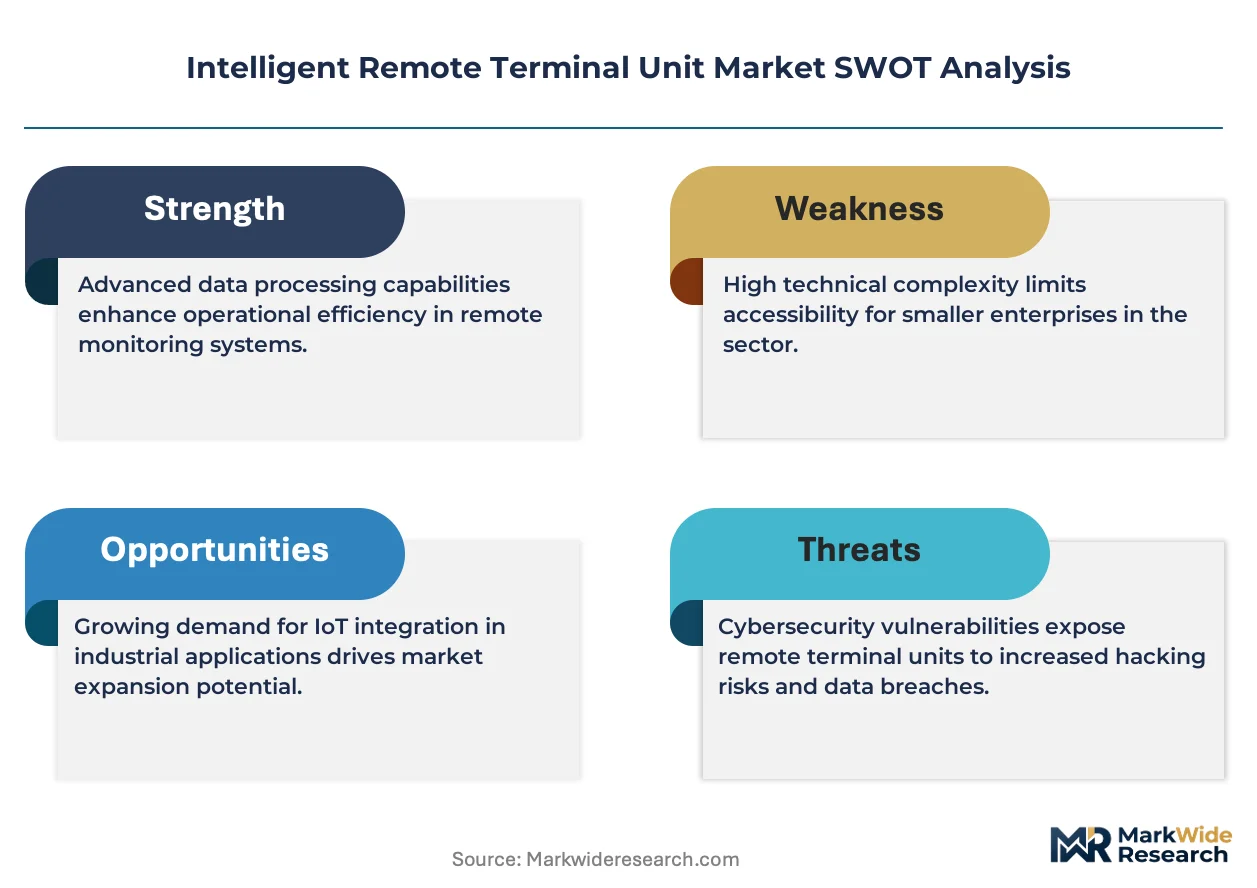
- High Initial Investment:The capital cost associated with replacing legacy RTUs with modern iRTUs, including hardware, software, and integration services, presents a significant barrier for smaller utilities and industrial operators.
- Integration with Legacy Systems:Ensuring seamless communication and data exchange between new, IP-based iRTUs and older, serial-based SCADA master stations is technically complex and can lead to project delays.
- Cybersecurity Threats:The increased connectivity of iRTUs exposes critical infrastructure to a wider range of cyber threats, creating hesitation among operators and increasing the total cost of ownership due to security requirements.
Strategic Opportunities
- Water and Wastewater Sector:Expanding iRTU applications into the water and wastewater management sector for process automation and remote asset monitoring represents a significant area for growth beyond the core electricity market.
- Edge Computing for Analytics:Developing iRTUs with embedded AI and machine learning capabilities can enable predictive maintenance and real-time anomaly detection, offering a higher-value proposition to end-users.
- Regulatory Security Tailwinds:Evolving cybersecurity regulations, such as the EU's NIS2 Directive, create a market for premium iRTUs that feature advanced, built-in security functionalities like hardware-based encryption.
Industry Challenges
- Skilled Workforce Scarcity:A persistent shortage of technicians and engineers who possess a hybrid skillset covering both industrial control systems and modern IT network security hampers deployment and maintenance efforts.
- Interoperability Hurdles:Despite the existence of standards, achieving true plug-and-play interoperability between multi-vendor devices in a substation automation environment remains a persistent operational challenge for system integrators.
- Phased Upgrade Complexity:Managing a mixed-asset environment, where new iRTUs must operate alongside aging remote terminal units with different security postures, complicates network management and security policy enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Remote Terminal Unit Market |
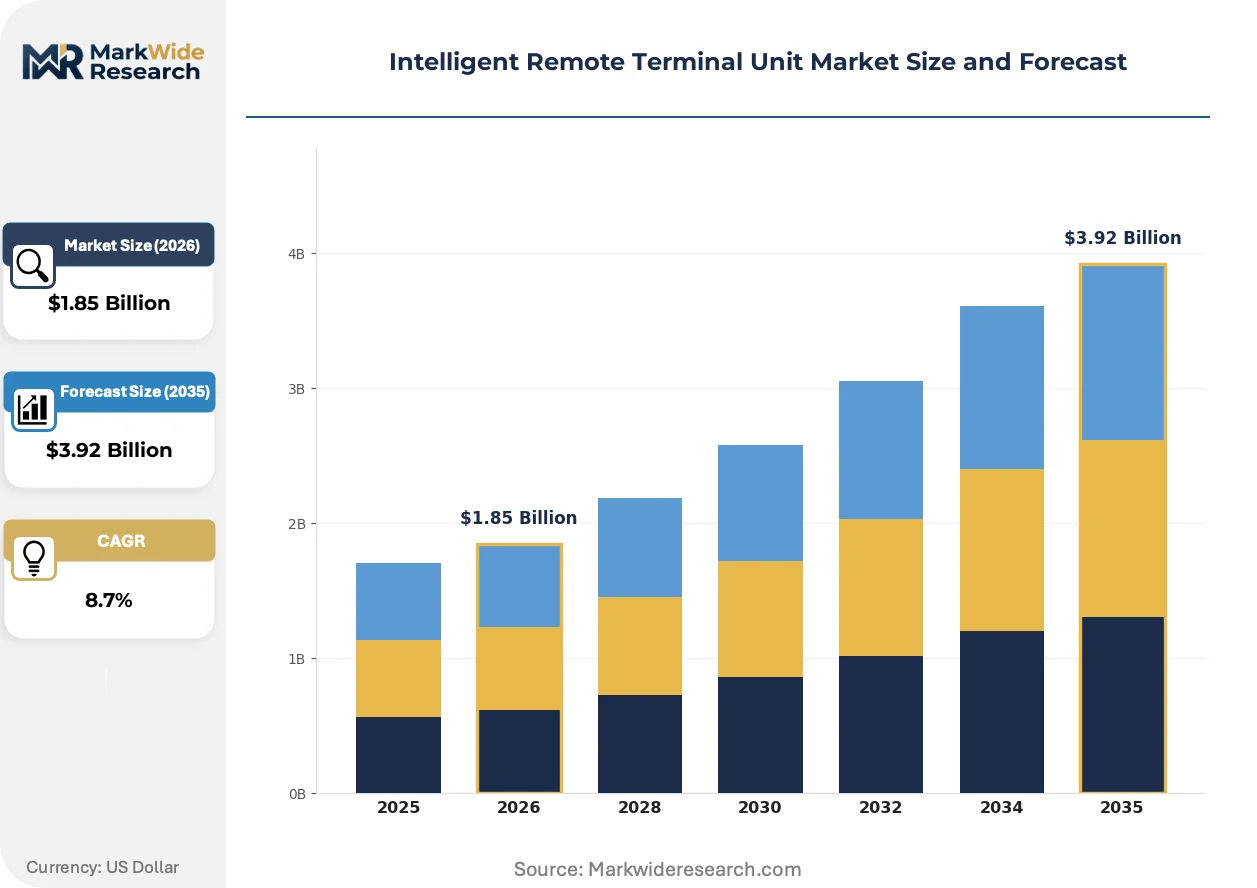
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RTU with Programmable Logic Controller, Modular RTU, Compact RTU, PC-based RTU, Wireless RTU Communication Technology: GPRS, Optical Fiber, SCADA Protocols, ZigBee, WiMAX, Ethernet Application: Water Management, Renewable Energy Monitoring, Substation Automation, Smart Agriculture, Pipeline Control, Traffic Management End User: Electric Utilities, Water Utilities, Oil & Gas Operators, Telecommunications Providers, Transportation Authorities |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Siemens AG, Rockwell Automation, Yokogawa Electric Corporation, ABB Ltd., General Electric Company, Advantech Co., Ltd., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Remote Terminal Unit Market Strategic Shifts & Innovations
The evolution of iRTU design is defined by a dual push toward greater onboard processing power and hardened cybersecurity. This shift transforms these devices from simple data collectors into autonomous decision-making nodes at the critical infrastructure edge, reshaping network architecture and control philosophies.
Onboard processing that executes logic comparable to a Programmable Logic Controller (PLC) is a defining feature of modern iRTUs. Electric utilities and pipeline operators are adopting these devices to enable faster, localized responses to grid faults or pressure fluctuations without waiting for commands from a central SCADA master. This advanced edge intelligence is displacing the reliance on centralized control for an increasing number of routine operational decisions and automated recovery sequences.
Compliance with the North American Electric Reliability Corporation's Critical Infrastructure Protection (NERC CIP) standards is profoundly influencing iRTU development. These regulations are forcing asset owners in the United States and Canada to prioritize cybersecurity in their procurement criteria. Consequently, the power transmission and distribution segment shows a clear preference for iRTUs that incorporate features like secure boot, role-based access control, and comprehensive event logging by default.
A notable shift in purchasing behavior involves moving from acquiring standalone hardware components to sourcing integrated systems. This disrupts the traditional model where utilities would self-integrate devices, favoring vendors that offer a more complete package including pre-configured software and cybersecurity services. This trend is most pronounced among municipal utilities and industrial operators that lack deep in-house expertise in OT security and network integration.
Intelligent Remote Terminal Unit Market Segmentation
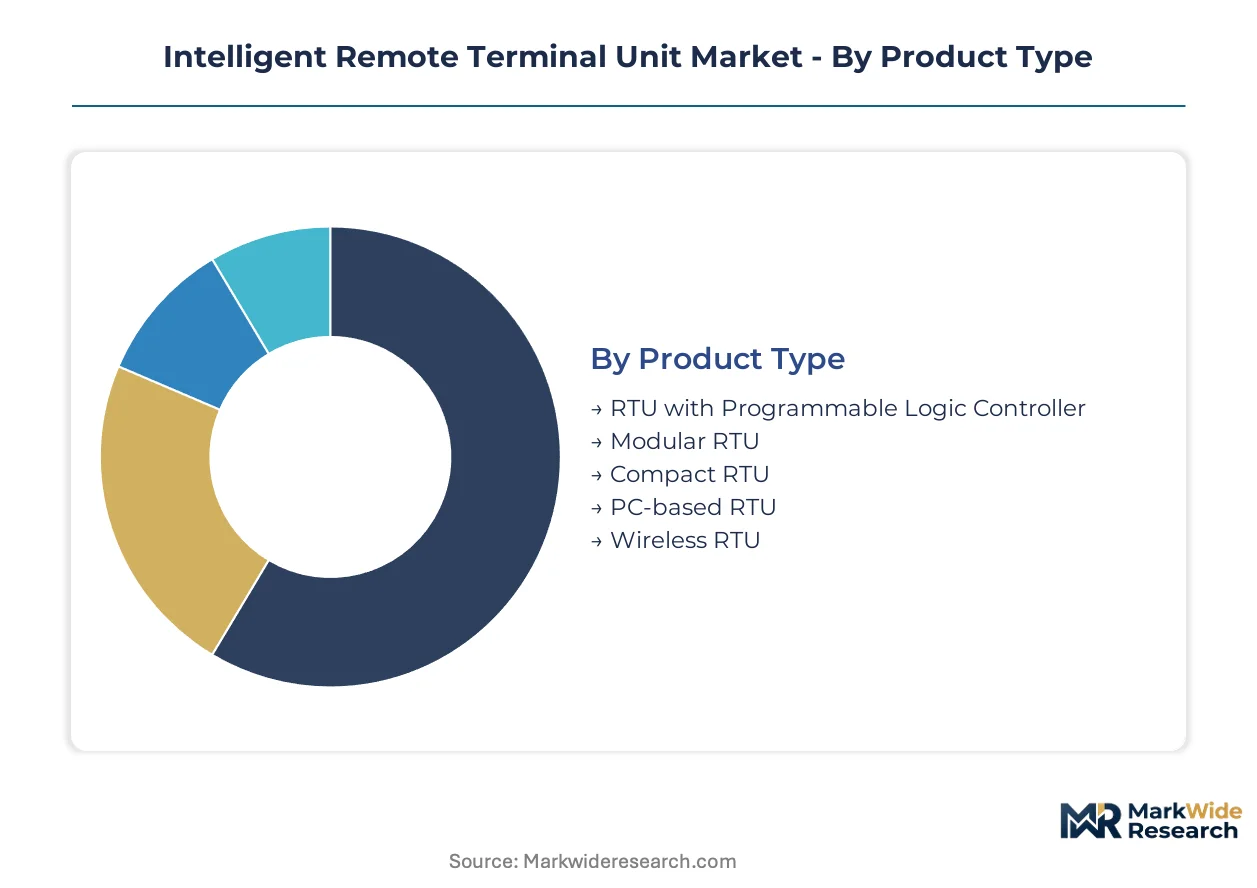
The Intelligent Remote Terminal Unit market is segmented to provide a granular understanding of how various product types, communication technologies, applications, and end-users contribute to its overall structure. This segmentation highlights the specific demands and technological preferences driving investment across different critical infrastructure sectors.
Product Type:
Regulatory frameworks often differentiate iRTU product types based on their functional safety and cybersecurity compliance requirements, influencing design and market adoption.
- RTU with Programmable Logic Controller:These units integrate a PLC's logic execution capabilities directly into the RTU, enabling autonomous decision-making and control at the network edge. Demand is concentrating in electric utilities for substation automation, driven by grid modernization mandates in China and India.
- Wireless RTU:These devices utilize cellular, radio, or satellite communication for remote data transmission, reducing cabling costs and enabling deployment in geographically dispersed areas. Renewable energy integration projects, particularly in solar and wind farms, are driving demand for flexible and scalable wireless solutions.
- Modular RTU:Modular RTUs offer configurable hardware and software components, allowing for customization to specific project requirements and future expansion.
- Compact RTU:These units provide essential monitoring and control functions in a small form factor, ideal for space-constrained applications or distributed assets.
- PC-based RTU:PC-based RTUs leverage industrial computers for enhanced processing power and software flexibility, suitable for complex data analytics at the edge.
RTU with Programmable Logic Controller handles the majority of throughput; Wireless RTU is the fastest mover on share.
Communication Technology:
The choice of communication technology for iRTUs is primarily dictated by the required data throughput, latency, and the physical environment of deployment.
- Ethernet:Ethernet provides high-speed, reliable, and standardized communication, essential for integrating iRTUs into modern IT/OT converged networks. Electric utilities are increasingly adopting Ethernet for substation automation to support IEC 61850 protocol implementation.
- Optical Fiber:Optical fiber offers superior bandwidth, immunity to electromagnetic interference, and enhanced security for long-distance and critical communications. Pipeline control systems utilize optical fiber for secure, high-integrity data transmission across vast distances.
- GPRS:General Packet Radio Service (GPRS) provides cost-effective wireless data connectivity for iRTUs in remote locations where wired infrastructure is impractical.
- SCADA Protocols:Traditional SCADA protocols like DNP3 and Modbus remain crucial for interoperability with legacy systems and master stations.
- ZigBee:ZigBee offers low-power, short-range wireless communication, suitable for monitoring numerous distributed sensors within a localized area.
- WiMAX:Worldwide Interoperability for Microwave Access (WiMAX) provides broadband wireless access for iRTUs in areas lacking fixed network infrastructure.
Ethernet connectivity is foundational for modern iRTU deployments, while specialized protocols continue to serve niche applications with specific latency or security needs.
Application:
iRTU applications span diverse critical infrastructure sectors, each demanding tailored functionalities and resilience for remote asset management.
- Substation Automation:iRTUs are central to automating power substations, enabling real-time monitoring, fault detection, and remote control of grid assets. This application is critical for grid modernization and reliability projects in countries like the United States and Germany.
- Renewable Energy Monitoring:These units monitor and control distributed renewable energy assets such as solar farms and wind turbines, optimizing generation and integration into the grid. The expansion of renewable energy capacity in India and Australia drives demand in this segment.
- Water Management:iRTUs monitor water levels, flow rates, and pump stations in water distribution networks, ensuring efficient resource management and preventing wastage.
- Smart Agriculture:In smart agriculture, iRTUs manage irrigation systems, monitor soil conditions, and control environmental factors for optimized crop yield.
- Pipeline Control:iRTUs are deployed along oil and gas pipelines to monitor pressure, flow, and leak detection, ensuring safe and efficient transport of resources.
- Traffic Management:These devices monitor traffic signals, sensors, and cameras to optimize traffic flow and respond to congestion or incidents in urban areas.
Substation automation represents the largest segment for iRTU deployment, with renewable energy monitoring showing significant expansion potential.
End User:
Different end-user segments exhibit distinct procurement cycles and technical requirements for intelligent remote terminal units, driven by their operational mandates.
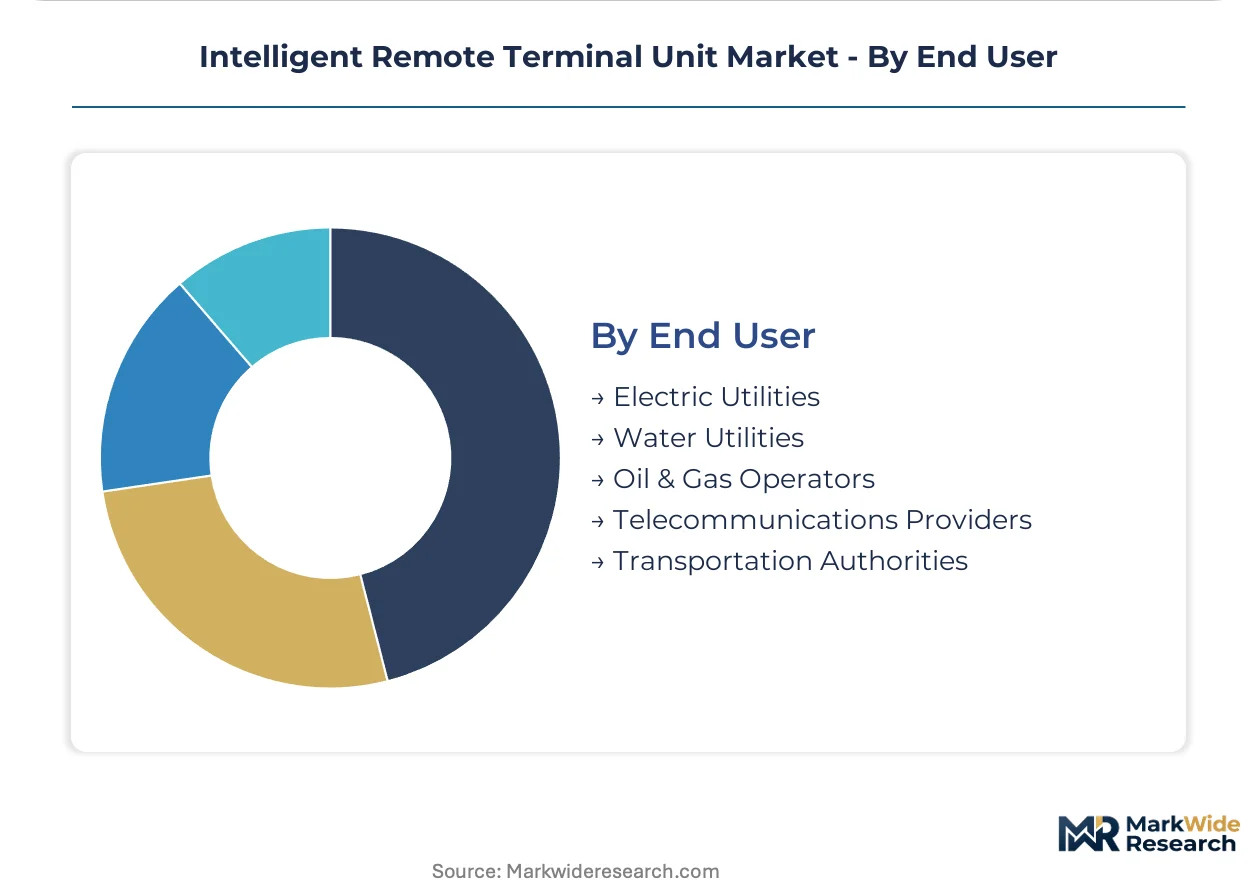
- Electric Utilities:This segment comprises national power grids, regional transmission operators, and distribution companies that use iRTUs for grid modernization and substation automation. Their demand is driven by the need for enhanced reliability and efficiency, particularly in response to NERC CIP standards.
- Oil & Gas Operators:These companies deploy iRTUs for monitoring and controlling remote assets such as pipelines, wellheads, and pumping stations, ensuring operational safety and efficiency. Investment in this sector is significant due to the distributed nature of assets and stringent regulatory requirements for environmental protection.
- Water Utilities:Water utilities utilize iRTUs for managing municipal water distribution networks, wastewater treatment plants, and remote pumping stations.
- Telecommunications Providers:Telecommunications providers employ iRTUs to monitor remote infrastructure, including cell towers and data centers, ensuring network uptime and performance.
- Transportation Authorities:This segment includes railway operators and road authorities who use iRTUs for traffic control, tunnel monitoring, and signaling systems.
Electric utilities remain the primary consumers of iRTUs, while the oil and gas sector continues to invest in advanced monitoring solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American Electric Reliability Corporation (NERC) Critical Infrastructure Protection (CIP) standards significantly influence iRTU procurement in the United States, driving demand for cyber-secure solutions. This regulatory pressure, combined with national grid modernization mandates, shapes investment priorities across key global markets. Countries with extensive power infrastructure development and renewable energy integration initiatives show particularly strong demand for intelligent remote terminal units.
United States
Grid modernization projects and the need for enhanced reliability drive iRTU demand across the United States. NERC CIP standards compel utilities to invest in devices with robust cybersecurity features. Major utilities in Texas are implementing advanced smart grid technologies, integrating iRTUs for substation automation and distributed energy resource management.
China
China's extensive investments in national power infrastructure and smart grid initiatives create sustained demand for iRTUs. The State Grid Corporation of China prioritizes automation and efficiency improvements across its vast network. Cities within the Yangtze River Delta region are leading pilot projects for advanced substation automation systems utilizing intelligent RTUs.
India
Renewable energy integration, particularly for solar and wind farms, is a significant demand driver for iRTUs in India. The Central Electricity Authority (CEA) issues guidelines for grid connectivity, emphasizing reliable monitoring and control. Gujarat, with its substantial renewable energy capacity, sees increased deployment of iRTUs for managing distributed generation assets.
Germany
Germany's energy transition (Energiewende) and substation automation projects fuel demand for advanced iRTUs. The EU's NIS2 Directive influences cybersecurity requirements for critical infrastructure, including energy systems. Bavaria, a hub for industrial automation, leverages iRTUs for optimizing local grid operations and integrating decentralized power sources.
Australia
Monitoring and control of remote assets, especially in renewable energy and mining sectors, drives iRTU adoption in Australia. The Australian Energy Market Operator (AEMO) sets standards for grid stability and reliability. Queensland's vast solar and wind projects necessitate intelligent RTUs for efficient power generation and grid integration.
Intelligent Remote Terminal Unit Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the Intelligent Remote Terminal Unit market. This structure reflects the complex interplay between deep domain expertise and specialized technological offerings. Strategic archetypes include comprehensive industrial automation providers, niche cybersecurity-focused vendors, and hardware-centric component manufacturers. Companies frequently engage in strategic partnerships to enhance integration capabilities and diversify their product portfolios.
Among the integrated solution providers, Siemens AG and Honeywell International Inc. exemplify the capabilities of large industrial conglomerates offering comprehensive iRTU systems. These entities leverage extensive portfolios spanning industrial automation, control systems, and software to deliver end-to-end solutions. Rockwell Automation, with its focus on secure network architecture, represents a vendor emphasizing robust integration within broader control system ecosystems, particularly for critical infrastructure applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Siemens AG |
| Rockwell Automation |
| Yokogawa Electric Corporation |
| ABB Ltd. |
| General Electric Company |
| Advantech Co., Ltd. |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
NERC CIP standards and the EU's NIS2 Directive gate both supply qualification and price differentiation simultaneously, compelling iRTU manufacturers to integrate advanced security features at a premium. This regulatory convergence drives product evolution and influences procurement decisions across critical infrastructure sectors.
Pricing Analysis
Geographic price variations for iRTUs reflect regional regulatory stringency and market maturity, with North America and Europe typically commanding higher prices due to stringent cybersecurity mandates. Project-based pricing dominates the market, reflecting the high customization and integration services required for critical infrastructure deployments. Price differentiation stems from the level of integrated edge intelligence and NERC CIP compliance, alongside the robustness of secure boot capabilities. Pricing pressure stems from the commoditization of basic RTU functions, particularly for non-critical applications. Smaller municipal utilities often exhibit greater price sensitivity compared to large national grid operators who prioritize reliability and compliance.
Supply Chain Analysis
Strategic stockpiling of critical components, particularly microprocessors and specialized communication modules, characterizes the iRTU supply chain to mitigate geopolitical risks. Geographic supply concentration for core electronic components centers on East Asia, with China and Taiwan serving as primary manufacturing hubs. The supply chain relies on specialized enclosures and industrial-grade power supplies sourced from diverse global suppliers. Single-source vulnerability for advanced microcontrollers represents a structural risk, impacting production timelines. Distribution for iRTUs runs primarily through direct sales channels to large electric utilities and specialized system integrators for complex substation automation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as the increasing capabilities of distributed energy resources and advanced sensors threaten to displace traditional iRTU functions. Incumbents must innovate to maintain relevance.
For Market Incumbents:
Secure long-term contracts with major electric utilities by offering comprehensive managed security services alongside hardware, mitigating the threat of in-house solutions. Deepen vertical integration into specialized microprocessor design to control critical component supply and enhance proprietary edge processing capabilities. Invest in R&D for embedded artificial intelligence to enable predictive maintenance and real-time anomaly detection, moving beyond basic monitoring. This strategy reinforces a strong competitive positioning against emerging software-defined control platforms.
For New Entrants and Emerging Players:
Service-layer gaps exist in providing user-friendly, cybersecurity-as-a-service offerings tailored for smaller industrial operators and municipal utilities. Target the water and wastewater sector, which remains underpenetrated by advanced iRTU solutions. Develop modular, cloud-native iRTU platforms that simplify integration with existing SCADA systems, offering a clear cost-benefit proposition. A go-to-market angle focusing on rapid deployment and reduced total cost of ownership through simplified security management will resonate with these underserved segments.
For Investors and Strategic Acquirers:
Carve-out targets emerge from large industrial conglomerates seeking to divest non-core automation divisions that possess strong iRTU intellectual property or established utility relationships. The long-term viability of iRTU investments hinges on the accelerating pace of grid modernization and the persistent need for critical infrastructure cybersecurity. Focus on companies demonstrating strong recurring revenue from software licenses and security updates. The signal to watch is the increasing adoption rate of IEC 61850-compliant devices outside the electric utility sector, indicating broader market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance Edge AI Capabilities | Enables autonomous decision-making and predictive maintenance at the grid edge, improving operational efficiency for electric utilities. |
| Strengthen Cybersecurity Offerings | Addresses NERC CIP and NIS2 Directive compliance, securing critical infrastructure against evolving cyber threats for operators. |
| Expand into Water/Wastewater | Diversifies revenue streams by applying proven iRTU technology to new, underserved critical infrastructure applications. |
| Form Strategic Technology Partnerships | Accelerates product development and market penetration by integrating specialized communication protocols or AI algorithms. |
| Standardize Modular Hardware Designs | Reduces manufacturing costs and allows for greater customization, meeting diverse project requirements from system integrators. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary data validation. Primary research engaged utility engineers, IT security specialists, system integrators, and product development managers across the iRTU ecosystem. This was complemented by secondary research, including NERC CIP compliance reports, IEC 61850 standard documents, government smart grid initiatives, and technical publications from leading automation vendors. Bottom-up data collection from individual projects and top-down market sizing provided comprehensive triangulation.
The forecasting boundary extended across the analysis window, utilizing a robust analytical framework that modeled market evolution. Segmentation dimensions included product type, communication technology, application, end-user, and the critical cybersecurity compliance level. Compound annual growth rates were derived through a combination of historical trend analysis and future investment projections. Key industry-specific forecast inputs included national smart grid investment levels and projected renewable energy capacity additions, particularly in developing economies.
Forecasts assume regulatory continuity in NERC CIP and EU NIS2 Directive regimes; material policy shifts would require re-modeling to assess their impact on market dynamics. The analysis acknowledges that geopolitical instability affecting semiconductor supply chains and rapid technological obsolescence of communication protocols represent significant risk factors. Practitioners should keep alternative scenarios live as global energy policies and digital security threats evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Elevator Control Market
Automation
Automation Light Grids Market
Automation
Italy Process Orchestration Market
Automation
Helpdesk Automation Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Parcel Sorting System Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Global Business Process Automation Software Market
Automation
Workflow Automation Market
Automation
Europe Marketing Automation Software Market
Automation
Data Center Automation Market
Automation
Workload Automation Software Market
Automation
Retail Automation Market
Automation
Smart Home Automation Market
Automation
Escalator Control Systems Market