
 Elevator Control Market | 2026-2036
Elevator Control Market Size, Share, and Industry Trends Forecast 2026-2036
Elevator Control Market Analysis
A widening capital-intensity gap between integrated system architects and component assemblers is reorganizing competitive dynamics in elevator controls. Otis Worldwide Corporation leverages captive manufacturing of destination dispatch algorithms to sustain margin capture across service contracts. KONE Corporation anchors its position through deep R&D allocation for regenerative drive technology, while Schindler Group competes via channel control over modernization pipelines in aging European building stock.
Elevator control systems encompass electromechanical assemblies governing vertical transport kinematics, safety interlocks, and traffic optimization, typically integrating microprocessor logic with variable frequency drives operating at 480V three-phase input to modulate motor torque and cab positioning within millimeter tolerances. PLC-based architectures lead in heavy-traffic commercial installations where fault tolerance and modular expandability command premium pricing, whereas IoT-enabled segments capture the fastest expansion as building operators demand predictive maintenance APIs and real-time occupancy analytics. Relay-based systems persist in cost-sensitive residential retrofits but face margin compression from semiconductor component obsolescence.
ASME A17.1 in the United States, EN 81-20/50 in Europe, and China's GB 7588 standard collectively shape product certification requirements, forcing control system redesigns around door-lock monitoring, emergency braking redundancy, and electromagnetic compatibility testing. Japan's METI energy efficiency benchmarks and South Korea's MFDS elevator safety directives add compliance layers for multinational suppliers. Stakeholders must monitor convergence between building codes and cybersecurity frameworks as connected elevator networks become attack surfaces for critical infrastructure.
Market Dynamics
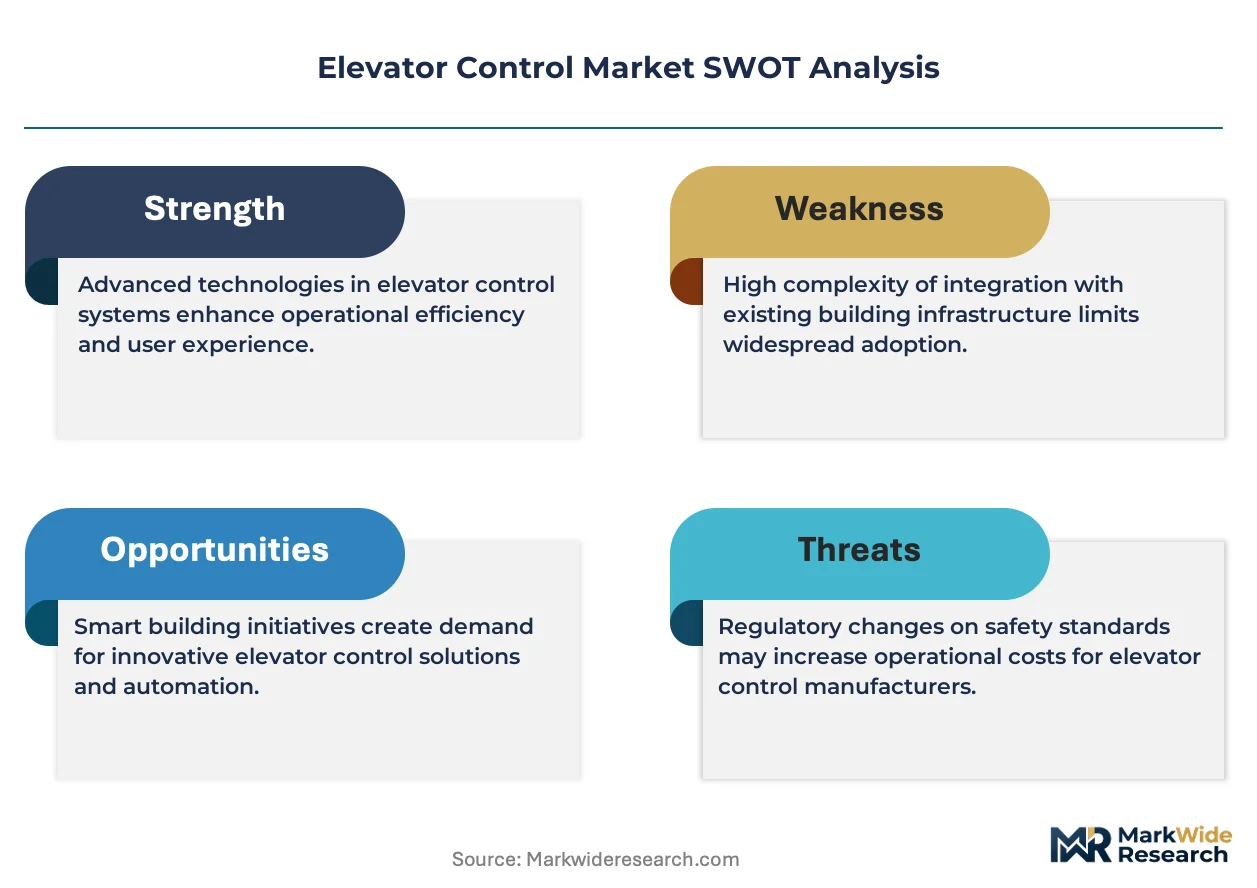
The elevator control market is experiencing structural compression from semiconductor supply reconfiguration and escalating firmware certification burdens, forcing control system manufacturers to redesign hardware architectures around chip availability rather than performance optimization alone.
Growth Catalysts
- Smart building integration mandates:China's GB 50314 standard for intelligent building design is accelerating IoT-enabled control deployment in commercial high-rises.
- Regenerative drive technology maturation:Variable frequency drives with energy recovery capabilities are capturing preference in jurisdictions with strict efficiency codes.
- Urban verticalization in Asia-Pacific:Metro rail corridor densification in India and Southeast Asian megacities is generating concentrated demand for high-rise vertical transport infrastructure.
Market Restraints
- IGBT and MCU supply concentration:Taiwan and South Korean foundry capacity constraints are extending lead times for power semiconductor components.
- ASME A17.1 compliance cost escalation:Door-lock monitoring and emergency brake redundancy requirements are inflating certification expenses for North American market entry.
- Relay system obsolescence pressure:Electromechanical control architectures face component discontinuation from European suppliers pivoting to solid-state portfolios.
Strategic Opportunities
- Predictive maintenance API monetization:Cloud-connected control systems enable recurring revenue streams through vibration analytics and wear-pattern forecasting.
- European F-Gas Regulation alignment:Hydraulic elevator phase-out timelines are creating replacement demand for electromechanical control retrofits.
- India's PLI scheme for electronics manufacturing:Domestic control panel assembly incentives are reducing import dependency for multinational system integrators.
Industry Challenges
- Embedded firmware engineering scarcity:Real-time operating system expertise for safety-critical applications commands premium compensation and extended recruitment cycles.
- Legacy system integration complexity:1990s-era relay logic installations require custom protocol bridges for IoT retrofit compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elevator Control Market |
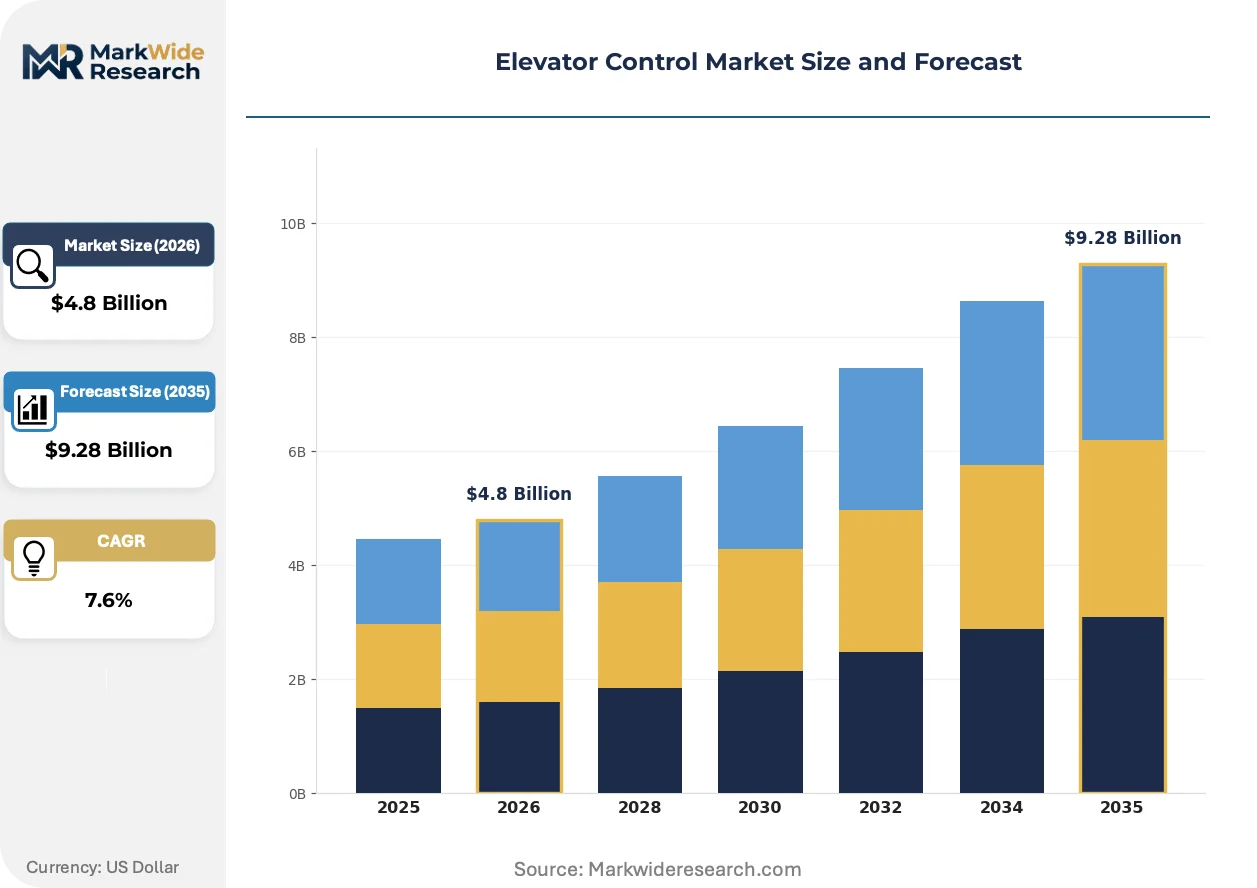
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontroller-based, Relay-based, Brushless Motors, PLC-based End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Hospitals Technology: IoT-enabled, Conventional, Smart, Hybrid Installation Type: New Installation, Modernization, Maintenance, Upgrades |
| Companies Covered | Otis Worldwide Corporation, KONE Corporation, Schindler Group, ThyssenKrupp AG, Mitsubishi Electric Corporation, Hitachi Ltd., Hyundai Elevator Co., Ltd., ABB Ltd., Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elevator Control Market Emerging Trajectories
Control system architecture is fragmenting along connectivity and autonomy axes, with divergent hardware strategies emerging between premium smart-building specifications and cost-optimized replacement markets.
Destination dispatch algorithms are bifurcating the product landscape. Group control systems using machine-learning traffic prediction command substantial premiums in Class-A office towers. Mid-market building operators are deferring upgrades due to upfront hardware costs. The technology is bifurcating vendor portfolios into high-complexity system architects versus component suppliers.
Europe's F-Gas Regulation is accelerating hydraulic elevator retirement timelines. The phasedown of fluorinated greenhouse gases in lifting equipment is compressing modernization decision windows. Building owners in Germany and France are prioritizing electromechanical control conversions to avoid stranded asset risk.
Service contract unbundling is disrupting traditional revenue models. Large commercial property managers are separating control system maintenance from cab and door servicing. This fragmentation is most advanced in North American institutional portfolios where facilities teams demand direct API access to performance data.
Elevator Control Market Segmentation
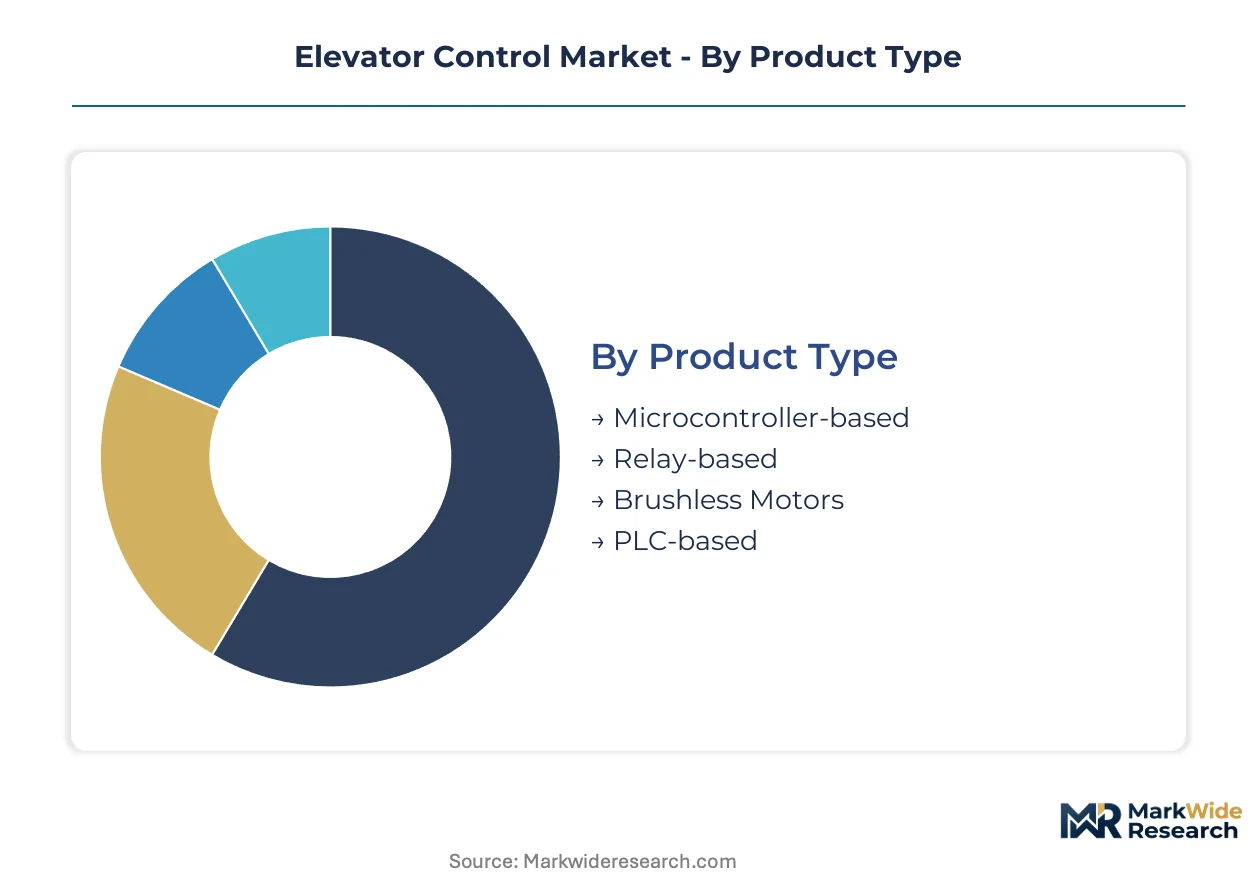
Elevator control segmentation reveals stark performance divergences between legacy electromechanical architectures and semiconductor-dependent smart systems. Procurement patterns increasingly favor segments with firmware upgrade paths over sealed-unit designs facing obsolescence risk.
Product Type:
Relay-based systems face the most acute substitution pressure as European component suppliers discontinue electromechanical portfolios for solid-state alternatives.
- Microcontroller-based:ARM Cortex and RISC-V architectures dominate new installations, executing real-time position algorithms with deterministic latency below 10 milliseconds. Demand concentrates in China's tier-1 cities where GB 7588 compliance mandates redundant processing cores for safety-critical loops.
- PLC-based:Modular ladder-logic platforms from Siemens and Rockwell Automation anchor heavy-traffic commercial installations. Metro rail corridor projects in India specify these systems for fault-tolerant group control of six-plus elevator banks.
- Relay-based:1990s-era installations in aging European building stock require custom protocol bridges for IoT retrofit compatibility.
- Brushless Motors:Permanent magnet synchronous machines paired with field-oriented control inverters achieve regenerative energy recovery.
PLC-based systems anchor the volume base in commercial high-rises while microcontroller-based architectures gain share at the steepest rate across new construction.
End User:
Cost tier stratification separates specification-intensive segments from price-sensitive replacement markets.
- Commercial Buildings:Class-A office towers demand destination dispatch with machine-learning traffic prediction and API-accessible performance analytics. China's GB 50314 intelligent building standard mandates IoT connectivity for new commercial high-rises exceeding 100 meters.
- Residential Buildings:Mid-rise apartment complexes in Southeast Asian megacities prioritize cost-optimized variable frequency drives with basic group control functionality.
- Hospitals:Bed elevator specifications require emergency power transfer protocols and infection-control surface materials on touch interfaces.
- Industrial Facilities:Freight elevators in manufacturing plants specify NEMA 4X enclosures and vibration-resistant control enclosures.
Commercial Buildings generate the highest average revenue per unit while Residential Buildings constitute the broadest installation base by unit volume.
Technology:
Connectivity maturity divides segments between cloud-native architectures and sealed legacy designs.
- IoT-enabled:MQTT and CoAP protocol stacks enable predictive maintenance APIs with vibration spectrum analysis and brake wear forecasting. Building operators in North American institutional portfolios demand direct cloud dashboard access, unbundling control maintenance from full-service contracts.
- Smart:Edge-computing nodes execute destination dispatch algorithms locally with occasional cloud synchronization for model updates.
- Hybrid:Conventional electromechanical safety circuits overlaid with IoT monitoring modules for modernization retrofits.
- Conventional:Non-connected architectures persist in cost-sensitive markets with minimal service infrastructure.
IoT-enabled systems command the steepest expansion trajectory as cybersecurity frameworks for building automation mature.
Installation Type:
Customer type segmentation separates capital-project decision-makers from operational expenditure owners.
- Modernization:Control system retrofits in Europe's aging building stock accelerate as F-Gas Regulation timelines compress hydraulic elevator replacement windows. Germany and France prioritize electromechanical conversions to avoid stranded asset risk.
- New Installation:Greenfield projects in India's PLI-subsidized electronics manufacturing zones specify domestically assembled control panels.
- Upgrades:Firmware and hardware mid-life enhancements extend system service life without full replacement.
- Maintenance:Service contract unbundling in North American institutional portfolios separates control system upkeep from cab and door servicing.
Modernization captures the fastest-growing revenue pool while New Installation provides the most predictable project pipeline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss engineering clusters while procurement volume tilts toward Chinese state-mandated efficiency programs. This asymmetry fragments margin capture across geographies. Control system vendors navigate divergent certification burdens between mature regulatory environments and volume-driven construction markets.
China
Urban verticalization in Shenzhen and Shanghai drives demand for destination dispatch systems in commercial towers exceeding 150 meters. GB 7588 safety standard revisions mandate redundant processing cores for all new high-rise installations. The Yangtze River Delta manufacturing corridor hosts domestic control panel assembly operations serving both local installation and export retrofit markets.
United States
ASME A17.1 compliance escalation inflates certification costs for door-lock monitoring and emergency brake redundancy systems. Institutional property managers in Chicago and New York Metro unbundle control maintenance from full-service contracts to secure direct API access. The Southeast construction corridor generates replacement demand as 1990s-era relay systems approach end-of-life.
Germany
F-Gas Regulation timelines compress hydraulic elevator modernization windows across aging building stock in Berlin and Munich. Electromechanical control conversions dominate procurement to avoid stranded asset classification. Baden-Württemberg engineering clusters supply precision drive components to system integrators serving Central European retrofit pipelines.
India
Metro rail corridor densification in Mumbai and Bangalore concentrates demand for group control systems managing six-plus elevator banks. PLI scheme subsidies for electronics manufacturing reduce import dependency for control panel assembly. Domestic fabrication capacity in Gujarat and Maharashtra expands to serve Southeast Asian export markets.
Japan
METI energy efficiency benchmarks drive regenerative drive adoption in Tokyo and Osaka commercial high-rises. Aging 1980s-era building stock requires protocol bridge solutions for IoT retrofit compatibility. Kanto region system integrators specialize in firmware migration paths for legacy electromechanical installations.
Elevator Control Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated system architects capture premium pricing through captive algorithm development and service contract bundling. Component assemblers compete on manufacturing scale and regional logistics proximity. Strategic moves concentrate on backward integration into semiconductor sourcing and predictive maintenance API monetization.
Among diversified industrial conglomerates, Mitsubishi Electric Corporation and Hitachi Ltd. occupy positions spanning drive electronics through full system integration. Otis Worldwide Corporation exemplifies the vertically integrated archetype, anchoring competitive positioning through algorithmic dispatch technology and service infrastructure density. KONE Corporation represents the R&D-intensive specialist model with concentrated allocation to regenerative drive portfolios.
| Leading Market Players |
|---|
| Otis Worldwide Corporation |
| KONE Corporation |
| Schindler Group |
| ThyssenKrupp AG |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Hyundai Elevator Co., Ltd. |
| ABB Ltd. |
| Toshiba Corporation |
| Others |
Supply Flow & Price Mechanics
Silicon carbide MOSFET substitution for IGBT modules in regenerative drives is redrawing procurement geography and compressing margin structures across control system tiers. This transition favors suppliers with captive semiconductor sourcing while forcing price concessions from relay-dependent assemblers facing component discontinuation.
Pricing Analysis
The customization-premium spread between configured-to-order destination dispatch systems and standard VFD packages spans three performance tiers. Project-based pricing dominates heavy-traffic commercial installations where GB 7588 certification grade and after-sales service bundling drive differentiation. Cost compression in relay-based retrofits intensifies as European electromechanical suppliers exit, while price insensitivity concentrates in Class-A office towers demanding machine-learning traffic optimization.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for ARM Cortex and RISC-V processing cores, while China's Yangtze River Delta concentrates control panel assembly. The supply chain draws from Taiwanese foundry capacity, South Korean memory components, and German precision drive electronics. Single-source vulnerability in 480V three-phase IGBT modules threatens lead time stability. Distribution runs through OEM-direct channels for new installations and authorized service networks for modernization retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering scarcity for safety-critical real-time operating systems constrains expansion timelines and inflates compensation costs across the competitive landscape. This capability gap favors incumbents with established embedded software teams while raising entry barriers for capital-constrained challengers.
For Market Incumbents: Consolidate algorithmic dispatch technology through selective acquisition of machine-learning traffic optimization specialists. Deepen backward integration into semiconductor sourcing to mitigate Taiwan foundry concentration risk. Channel control over European modernization pipelines remains essential as F-Gas Regulation timelines compress replacement windows. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized electronics manufacturing zones for cost-competitive control panel assembly. Target Southeast Asian residential mid-rise segments where basic group control functionality satisfies specification requirements. Pursue OEM private-label partnerships to bypass direct service infrastructure investment. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors R&D-intensive specialists with regenerative drive portfolios. Long-term viability hinges on predictive maintenance API monetization and cloud-connected recurring revenue streams. Watch for inflection in cybersecurity framework adoption for building automation networks as the signal for IoT-enabled valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Taiwan foundry concentration risk demands captive supply arrangements for ARM Cortex processing cores. |
| Predictive Maintenance API Development | MQTT protocol stacks enable vibration analytics monetization for North American institutional portfolios. |
| Regenerative Drive Portfolio Expansion | METI energy benchmarks in Japan and GB 50314 standards in China mandate energy recovery capabilities. |
| European Modernization Channel Control | F-Gas Regulation timelines in Germany and France compress hydraulic elevator replacement decision windows. |
| Firmware Certification Investment | ASME A17.1 compliance escalation for door-lock monitoring inflates barrier to North American market entry. |
Methodological Framework
A standing panel of elevator system integrators, facilities engineering directors at commercial property managers, semiconductor procurement leads, and regulatory compliance specialists provided ongoing calibration. Primary fieldwork combined structured interviews with secondary validation against ASME A17.1 certification databases, GB 7588 standard filings, and customs records for control panel component trade flows. Bottom-up installation data triangulated against top-down construction spending estimates across the analysis window.
Consistency checks validated volume and value outputs against metro rail corridor project announcements, intelligent building standard adoption metrics, and OEM service contract disclosures. Segmentation modeling spanned product architecture, end-use building type, connectivity technology, and installation category across the projection horizon. CAGRs derived from regression analysis of historic replacement cycles, urban verticalization rates, and regulatory compliance phase-in schedules. Forecast inputs incorporated foundry capacity utilization trends and firmware engineering labor market tightness.
Material uncertainties — semiconductor supply reconfiguration, cybersecurity framework evolution, and building code convergence — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and technology substitution elasticity. Recalibration cycles align with material shifts in ASME A17.1 revision schedules and F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Automatic Message Handling System Market
Automation
Terminal Automation Systems Market
Automation
Universal Process Control Market
Automation
Smart Home Automation Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Network Automation Market
Automation
Laboratory Automation Market
Automation
Automation Light Grids Market
Automation
Europe Data Center Automation Market
Automation
North America Home Automation Systems Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Global Warehouse Barcode System Market
Automation
Global Form Automation Software Market
Automation
North America Data Center Automation Market
Automation
Voice Picking Solutions Market