
 Helpdesk Automation Market | 2026-2036
Helpdesk Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Helpdesk Automation Market Intelligence
Generative AI integration into legacy ticketing architectures is fragmenting the traditional helpdesk stack into modular, API-first components. Zendesk anchors its position through a broad app marketplace and embedded AI layer across customer support workflows. ServiceNow dominates IT service management with deep workflow orchestration and enterprise-grade governance controls. Aisera differentiates through predictive intelligence that auto-resolves incidents before ticket creation.
Helpdesk automation encompasses software systems that apply natural language processing, robotic process automation, and machine learning to classify, route, and resolve service requests without human intervention, typically handling ticket volumes exceeding 10,000 incidents monthly per deployment. Cloud-based deployment leads solution adoption as banking institutions and telecom providers prioritize elastic scaling and reduced infrastructure overhead. Automated ticketing captures the largest margin pool due to integration complexity and data migration services, while chatbot modules represent the fastest-expanding segment as self-service portals proliferate across educational organizations and manufacturing firms.
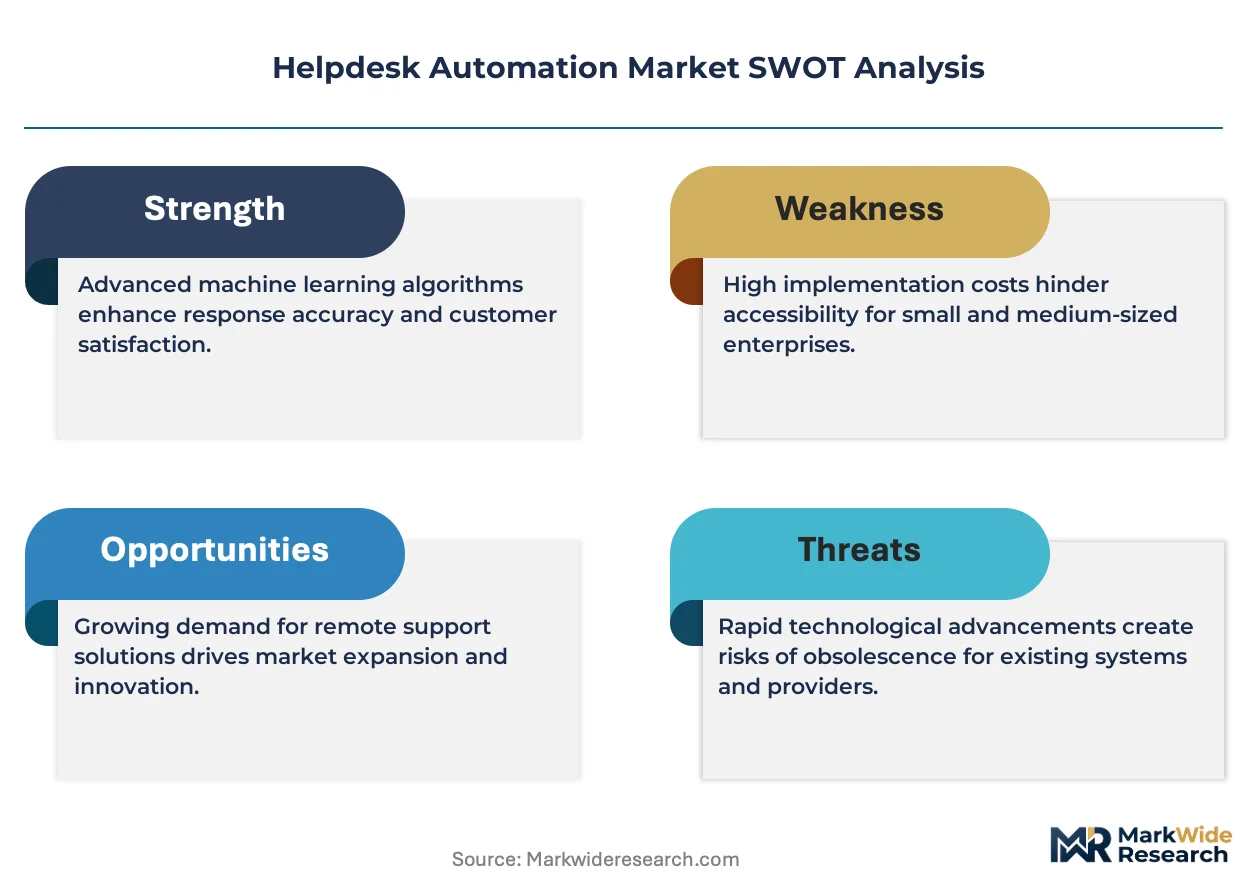
The EU AI Act and GDPR impose transparency obligations on automated decision-making in customer-facing support channels, compelling vendors to build auditable response trails and human escalation protocols. The US FTC scrutinizes AI-powered helpdesk tools for deceptive practices and unfair automated outcomes, shaping product liability frameworks. Stakeholders must weigh regulatory compliance costs against automation efficiency gains when selecting deployment architectures and vendor ecosystems.
Market Dynamics
Generative AI integration is fragmenting legacy helpdesk architectures into modular, API-first components, forcing vendors to rebuild orchestration layers around conversational intelligence rather than ticket-centric workflows.
Growth Catalysts
- EU AI Act transparency mandates:Banking institutions across Germany and France are accelerating procurement of auditable automation platforms to satisfy automated decision-making disclosure requirements before enforcement deadlines.
- Elastic cloud infrastructure:Telecom providers in the United States are migrating on-premise ticketing systems to SaaS-native deployments, prioritizing auto-scaling capacity during seasonal support surges.
- Natural language processing advances:Transformer-based models are reducing intent classification error rates below 5 percent, enabling first-contact resolution for complex technical queries without human escalation.
Market Restraints
- Data residency compliance costs:GDPR Article 44 restrictions on cross-border data transfers are forcing vendors to maintain region-specific infrastructure, inflating operational overhead by 15-25 percent for European deployments.
- Legacy system integration complexity:Mainframe-based ticketing architectures in established financial institutions require custom middleware development, extending implementation timelines and professional services dependency.
- GPU compute price volatility:Cloud-based inference for large language models exposes vendors to NVIDIA supply constraints and spot pricing fluctuations, compressing gross margins on AI-enabled tiers.
Strategic Opportunities
- India's digital public infrastructure:The country's unified payments interface and expanding internet penetration are creating first-mover advantages for vernacular-language chatbot deployments in regional banking cooperatives.
- Convergence of RPA and conversational AI:Hybrid automation stacks that combine robotic process automation with generative dialogue systems are opening new procurement categories for end-to-end service request fulfillment.
- Brazil's open banking mandate:Central Bank of Brazil regulations requiring standardized APIs are lowering integration barriers for helpdesk automation vendors targeting mid-tier financial institutions.
Industry Challenges
- Prompt engineering talent scarcity:Vendors struggle to hire specialists capable of optimizing retrieval-augmented generation pipelines for domain-specific support contexts, particularly in regulated industries.
- ISO 42001 AI management system certification:Early-stage automation providers face 12-18 month compliance timelines to establish governance frameworks for algorithmic risk management and bias monitoring.
- Technical debt in ticketing migrations:Historical ticket data quality issues and inconsistent categorization schemas impede machine learning model training, requiring expensive data cleansing engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helpdesk Automation Market |
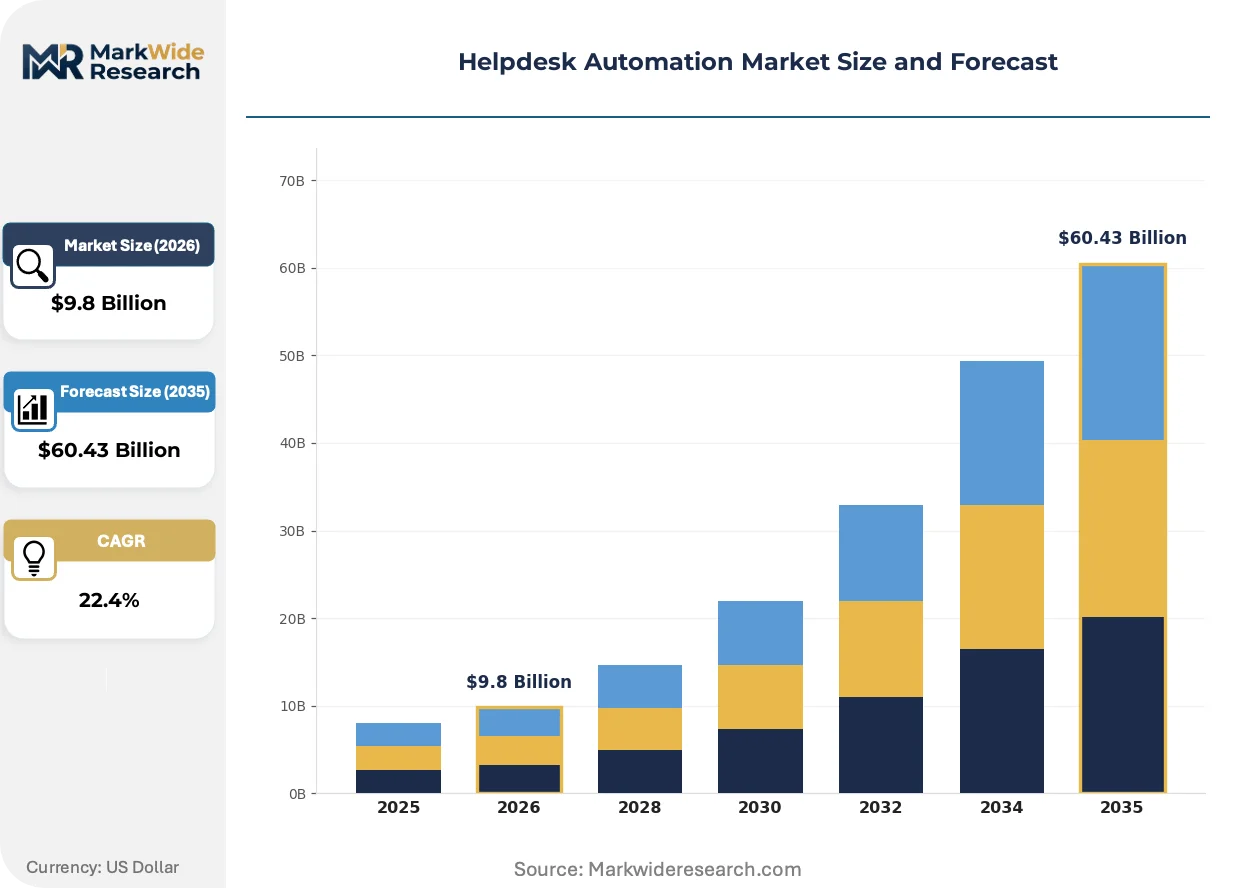
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $60.43 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Offering: Chatbots, Automated Ticketing, Workflow Automation, Knowledge Management Application: IT Service Management, Customer Support, HR Service Desk, Facilities Management End User Industry: Telecom Providers, Banking Institutions, Educational Organizations, Manufacturing Firms |
| Companies Covered | Agentforce, Aisera, Zendesk, Hiver, SearchUnify, Freshdesk, Moveworks, Fixify, ServiceNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helpdesk Automation Market Strategic Shifts & Innovations
Helpdesk automation is undergoing architectural disaggregation as vendors decouple conversational interfaces from workflow engines, enabling composable deployments that match specific enterprise maturity levels.
Large language model orchestration layers are virtualizing traditional agent desktop environments by collapsing multiple system interactions into unified conversational threads. Banking contact centers in the United Kingdom are piloting these architectures for mortgage servicing workflows. The technology is virtualizing tier-one support roles into self-healing dialogue systems that resolve inquiries without ticket creation.
The EU AI Act's risk-based classification system is compelling vendors to implement human-in-the-loop protocols for high-stakes support scenarios involving credit disputes or account access recovery. Automated decision logging and explanation generation are becoming standard contractual requirements in European procurement. Financial services deployments are responding by embedding escalation triggers and audit trails directly into conversational flows.
Enterprise buyers are consolidating vendor relationships around platform ecosystems that bundle ticketing, knowledge management, and workforce optimization. Mid-market organizations are abandoning point solutions for integrated suites with native AI capabilities. This concentration is most visible in United States SaaS procurement, where IT leaders prioritize vendor stability and roadmap continuity over best-of-breed feature depth.
Helpdesk Automation Market Segmentation
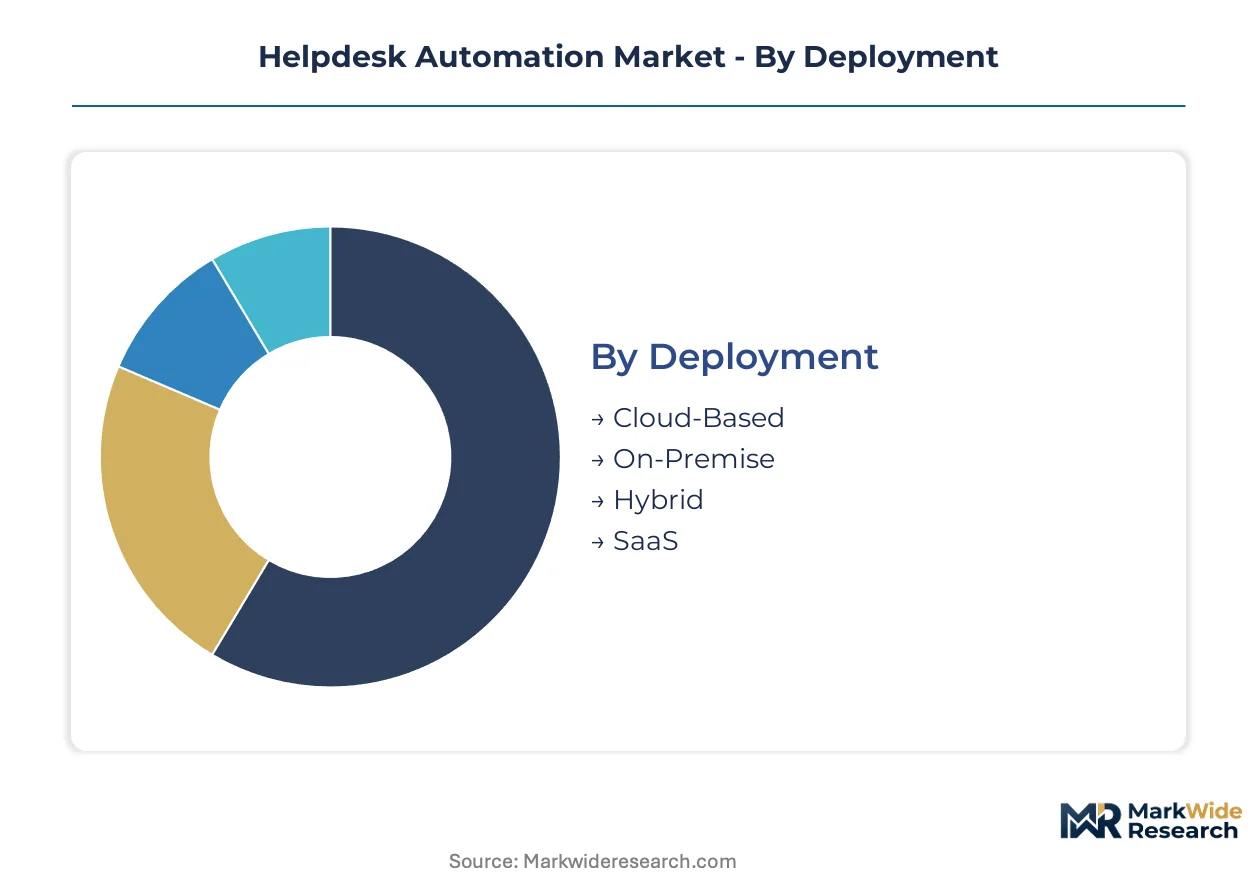
Helpdesk automation vendors structure product portfolios around deployment flexibility, solution modularity, and industry-specific compliance requirements. Segmentation reveals where margin pools concentrate and which integration architectures drive procurement decisions across enterprise IT departments.
Deployment:
After-sales service intensity varies sharply by deployment mode, with cloud-native architectures demanding continuous vendor engagement for model updates and security patching.
- Cloud-Based:Elastic infrastructure enables auto-scaling during seasonal support surges without capital expenditure. Banking institutions in the United States prioritize this model for rapid provisioning and reduced operational overhead.
- SaaS:Multi-tenant platforms accelerate time-to-value through pre-configured workflows and embedded AI capabilities. Telecom providers favor SaaS deployments for predictable subscription economics and seamless feature rollouts.
- On-Premise:Air-gapped installations serving defense contractors and classified government facilities with strict data sovereignty mandates.
- Hybrid:Split architectures keeping sensitive ticket data on-premise while leveraging cloud inference for natural language processing workloads.
By volume, Cloud-Based deployments lead. By growth pace, SaaS is expanding most quickly as mid-market organizations abandon legacy infrastructure.
Solution Offering:
Cost tier differentiation separates commodity self-service tools from premium orchestration platforms requiring extensive professional services.
- Automated Ticketing:Machine learning classifiers route and prioritize incidents based on sentiment analysis and historical resolution patterns. This segment captures the largest professional services revenue due to data migration complexity and legacy system integration.
- Chatbots:Conversational interfaces deflect routine inquiries through intent recognition and knowledge base retrieval. Educational organizations in India deploy vernacular-language variants to serve regional student populations.
- Workflow Automation:Robotic process automation engines execute cross-system tasks without human intervention, spanning password resets to provisioning workflows.
- Knowledge Management:Intelligent content repositories that auto-suggest resolutions based on ticket similarity and agent expertise matching.
By revenue concentration, Automated Ticketing leads. By expansion trajectory, Chatbots are gaining share fastest as self-service portals proliferate.
Application:
Customer maturity determines deployment complexity, with regulated industries demanding audit trails and human-in-the-loop escalation protocols.
- IT Service Management:Incident, problem, and change management workflows integrated with CMDB and discovery tools. Enterprise IT departments require deep ServiceNow or BMC Remedy interoperability.
- Customer Support:Omnichannel engagement spanning voice, chat, email, and social with unified agent desktops. Banking contact centers in the United Kingdom pilot generative AI for mortgage servicing workflows.
- HR Service Desk:Employee self-service for benefits enrollment, leave management, and policy inquiries with Workday and SAP SuccessFactors connectors.
- Facilities Management:Work order routing for maintenance requests, space allocation, and vendor dispatch in commercial real estate portfolios.
By installed base, IT Service Management leads. By procurement momentum, Customer Support shows the steepest expansion trajectory.
End User Industry:
Supply concentration among tier-one vendors shapes pricing power, with banking and telecom consolidating around platform ecosystems.
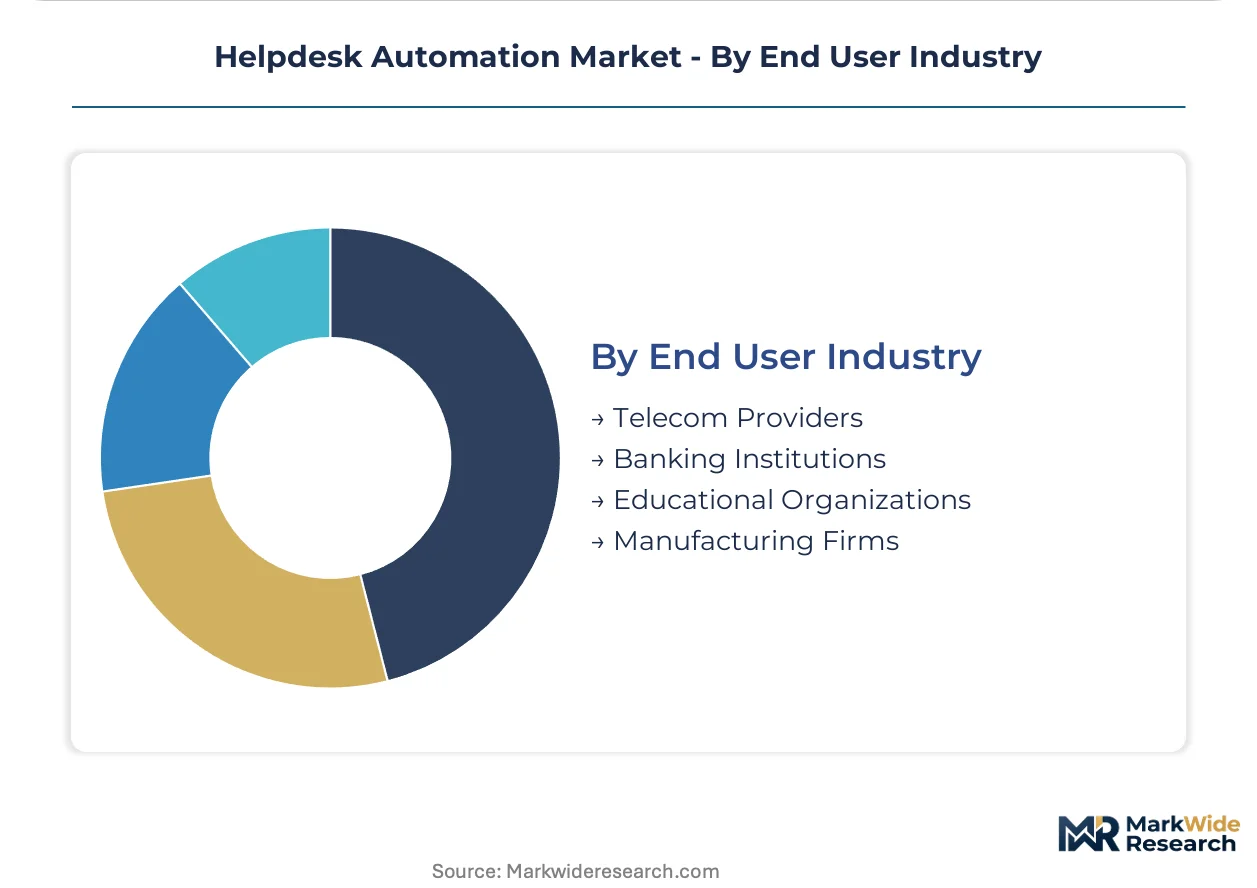
- Banking Institutions:Compliance-heavy deployments requiring EU AI Act transparency and GDPR auditability for automated credit dispute handling. German and French banks accelerate procurement ahead of enforcement deadlines.
- Telecom Providers:High-volume, seasonal support patterns demanding elastic scaling and real-time network status integration.
- Educational Organizations:Cost-constrained implementations prioritizing chatbot deflection for admissions and IT helpdesk inquiries.
- Manufacturing Firms:Shop-floor integration with ERP systems for maintenance ticketing and supply chain disruption alerts.
By spending scale, Banking Institutions lead. By activation rate, Telecom Providers are climbing the fastest as 5G deployments expand subscriber support volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IT procurement concentrates in banking and telecom sectors across five major economies, with regulatory deadlines and cloud migration timelines dicting vendor selection priorities.
United States
Telecom providers and SaaS-native enterprises drive elastic scaling demand for seasonal support surges. FTC scrutiny of AI-powered helpdesk tools shapes product liability frameworks and disclosure requirements. Silicon Valley clusters anchor development of transformer-based intent classification systems for complex technical queries.
Germany
Banking institutions accelerate auditable automation procurement ahead of EU AI Act enforcement deadlines. GDPR Article 44 data residency mandates force region-specific infrastructure investments. Frankfurt's financial services hub pilots human-in-the-loop protocols for automated credit dispute handling.
India
Regional banking cooperatives and educational organizations deploy vernacular-language chatbots for cost-constrained implementations. RBI guidelines on digital public infrastructure support unified payments interface integration. Bangalore's technology corridor concentrates development of retrieval-augmented generation pipelines for domain-specific support contexts.
United Kingdom
Banking contact centers pilot generative AI architectures for mortgage servicing workflows. FCA expectations on algorithmic accountability influence procurement of explainable automation platforms. London's fintech cluster drives consolidation around platform ecosystems bundling ticketing and knowledge management.
Brazil
Mid-tier financial institutions target helpdesk automation following Central Bank open banking mandates. Standardized API requirements lower integration barriers for cloud-native deployments. São Paulo's financial services district leads procurement of hybrid automation stacks combining RPA with conversational AI.
Helpdesk Automation Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers. The vendor ecosystem stratifies around platform breadth, with enterprise-grade orchestration suites commanding premium positioning against modular point solutions. Dominant archetypes include full-stack workflow orchestrators, AI-native disruptors, and embedded collaboration tools. Competitive intensity manifests through strategic partnerships for legacy system interoperability and geographic expansion into regulated banking markets.
Among platform-centric orchestrators, ServiceNow and Zendesk exemplify scale-driven positions anchored through app marketplaces and embedded AI layers. Aisera occupies a specialist tier representing predictive intelligence architectures that auto-resolve incidents before ticket creation. These three entities collectively illustrate how competitive positioning fragments between breadth-first platform consolidation and depth-first automation specialization.
| Leading Market Players |
|---|
| Agentforce |
| Aisera |
| Zendesk |
| Hiver |
| SearchUnify |
| Freshdesk |
| Moveworks |
| Fixify |
| ServiceNow |
| Others |
Cost & Logistics Intelligence
Bangalore's technology corridor anchors cloud-native development capacity for conversational AI components, concentrating vendor engineering talent and compressing time-to-market for SaaS-native platforms while downstream buyers in United States banking and telecom sectors extract volume discounts from this supply abundance.
Pricing Analysis
Cost-plus contracts with GPU compute indexation dominate enterprise procurement for AI-enabled helpdesk tiers. Three-tier pricing structure across premium orchestration suites, standard workflow modules, and economy self-service chatbots reflects integration complexity and professional services bundling. Pricing pressure stems from NVIDIA supply constraints and spot pricing volatility for cloud inference workloads. Educational organizations in India exhibit highest price sensitivity, while German banking institutions prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from hyperscaler cloud providers have restructured vendor working capital requirements. Engineering talent concentrates in India, United States, and United Kingdom clusters. Transformer model development draws from specialized semiconductor fabrication, high-bandwidth memory modules, and proprietary training datasets. Single-source vulnerability runs through NVIDIA's GPU supply chain. Distribution runs through direct enterprise sales teams and systems integrator partnerships for legacy system interoperability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helpdesk automation sits in early-cycle expansion as EU AI Act compliance deadlines force replacement of opaque legacy ticketing architectures with auditable automation platforms across European banking institutions.
For Market Incumbents: Build switching-cost moats through deep CMDB and discovery tool integrations that embed workflow orchestration into enterprise IT operations. Incumbents must accelerate ISO 42001 certification timelines to outpace specialist competitors on algorithmic risk governance. Defensive consolidation around app marketplaces and embedded AI layers protects against modular point-solution erosion. Capacity investment in Frankfurt and London data centers addresses GDPR Article 44 residency mandates.
For New Entrants and Emerging Players: Establish a beachhead in vernacular-language chatbot deployments for India's regional banking cooperatives and educational organizations. White-space concentration sits in hybrid RPA-conversational AI stacks for Brazil's open banking mid-tier institutions. Go-to-market leverage through Central Bank of Brazil standardized APIs lowers integration friction against entrenched platform vendors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors predictive intelligence specialists with auto-resolution capabilities over ticket-centric workflow vendors. Long-term viability hinges on retrieval-augmented generation pipeline optimization and domain-specific prompt engineering talent depth. Acquisition targets should demonstrate EU AI Act audit trail architectures and human-in-the-loop protocol maturity. Signal to monitor: enforcement action velocity from European regulators on automated decision-making transparency.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ServiceNow and Zendesk ecosystems consolidate ticketing, knowledge management, and workforce optimization into unified procurement. |
| Geographic Expansion | Frankfurt and London data center investments satisfy GDPR Article 44 cross-border transfer restrictions for EU banking deployments. |
| Acquisition of Specialist Firm | Predictive intelligence architectures like Aisera's auto-resolution engines command premium positioning against reactive ticketing workflows. |
| Strategic Partnership | Hyperscaler alliances provide elastic GPU compute and supply-chain finance facilities for cloud-native inference scaling. |
| Product Launch | Retrieval-augmented generation pipelines with domain-specific optimization address prompt engineering talent scarcity in regulated industries. |
Research Approach
A standing panel of CTOs, IT procurement officers, platform engineers, and integration specialists provided ongoing calibration across primary interviews and secondary validation. Bottom-up sizing triangulated against top-down macro indicators drew from SEC filings, hyperscaler capex disclosures, App Annie/Sensor Tower deployment metrics, and EU regulatory enforcement databases. Conversations with channel partners and systems integrators captured legacy system interoperability constraints and professional services revenue concentration.
Scenario-bracketing framed projections across the analysis window with segmentation modeling across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from weighted average of historical trajectory and technology diffusion curves incorporated transformer model advancement rates, EU AI Act compliance timeline acceleration, and cloud infrastructure elasticity demand from seasonal support surge patterns.
Sensitivities concentrate around NVIDIA GPU supply constraints, EU AI Act enforcement velocity, and legacy data migration quality issues. Forecasts reflect documented assumptions on technology adoption curves and regulatory deadline adherence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Europe Laboratory Automation Market
Automation
Global Automated Liquid Handling System Market
Automation
Automation Testing Market
Automation
Europe Data Center Automation Market
Automation
Global Warehouse Barcode System Market
Automation
Self Bag Drop Machine Market
Automation
Micro Fulfillment Market
Automation
Indonesia Automation and Control System Market
Automation
Smart Home Automation Market
Automation
Automatic Message Handling System Market
Automation
Automation-As-A-Service Market
Automation
CNC Controller Market
Automation
Global Water Automation and Instrumentation Market
Automation
Italy Marketing Automation Market
Automation
Italy Marketing Automation Software Market
Automation
Global Door and Window Automation Market