
 Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market | 2026-2036
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market Size, Share, and Industry Trends Forecast 2026-2036
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market Insights
Buyer concentration among mega-fulfillment networks is repositioning procurement leverage toward platforms that handle million-SKU variability. Manhattan Associates leverages AI-native slotting to sustain throughput guarantees for high-velocity eCommerce operators. Blue Yonder anchors its position through supply-chain-aware labor forecasting that extends planning horizons beyond conventional WMS boundaries. UKG competes by embedding compliance engines that navigate multi-jurisdiction shift rules across fragmented last-mile networks.
Task-level labor planning and workforce orchestration for fulfillment denotes software systems that decompose warehouse operations into discrete, time-bound activities, then algorithmically assign workers based on real-time inventory position, order profiles, and labor skill matrices. These systems integrate with WMS and OMS layers to synchronize human capacity with inbound shipment waves, outbound carrier cutoffs, and returns processing windows. Cloud-based deployment now leads solution delivery, though hybrid architectures capture margin pools among operators with latency-sensitive edge requirements. Workforce Scheduling dominates solution type revenue, while Productivity Analytics grows fastest as operators seek unit-economics visibility at the individual picker level.
OSHA warehouse safety standards, the EU AI Act's automated decision-making transparency requirements, and China's GB standards for logistics informatization collectively shape product roadmaps and vendor certification burdens. The EU AI Act specifically mandates human oversight protocols for algorithmic shift assignments, forcing architecture changes in European deployments. Stakeholders must monitor regulatory divergence between jurisdictions that classify workforce algorithms as managerial tools versus those subject to employment-law scrutiny.
Market Dynamics
Cloud-native workforce orchestration platforms are compressing deployment timelines from quarters to weeks, forcing incumbent WMS vendors to rearchitect their labor modules for API-first interoperability with best-of-breed scheduling engines.
Growth Catalysts
- EU AI Act transparency mandates:The regulation's algorithmic accountability requirements are accelerating procurement of audit-ready workforce platforms among European 3PLs seeking to preempt compliance penalties.
- Same-day delivery density:Urban fulfillment networks in Germany and China are deploying granular task decomposition to synchronize picker workflows with sub-two-hour delivery windows.
- Edge AI inferencing:On-premise neural processing units are enabling millisecond-level labor reallocation decisions without cloud round-trip latency.
Market Restraints
- Technical debt in brownfield WMS:Legacy warehouse management architectures lack event-streaming interfaces, forcing expensive middleware layers for labor orchestration connectivity.
- Input cost volatility in edge hardware:GPU and TPU module pricing fluctuations are compressing margins for vendors bundling on-premise inference appliances.
- Regulatory friction from OSHA:Evolving warehouse ergonomic standards are requiring continuous algorithmic retraining to ensure task assignments comply with lifting and motion limits.
Strategic Opportunities
- Underpenetrated cold chain vertical:Temperature-controlled fulfillment operators in the United States lack specialized labor platforms that account for garment-change time and zone-restricted worker movements.
- Convergence of computer vision and labor tracking:Vision-based productivity measurement is integrating with wearable task-assignment devices to create closed-loop performance optimization.
- India's logistics PLI scheme:Production-linked incentives for automated warehousing are creating first-mover advantages for vendors establishing localized cloud regions.
Industry Challenges
- Industrial engineering skill scarcity:Fulfillment operators struggle to hire analysts capable of translating time-and-motion studies into algorithmic optimization parameters.
- Integration complexity with multi-vendor automation:Labor orchestration platforms must coordinate human workers alongside AMR fleets from incompatible control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market |
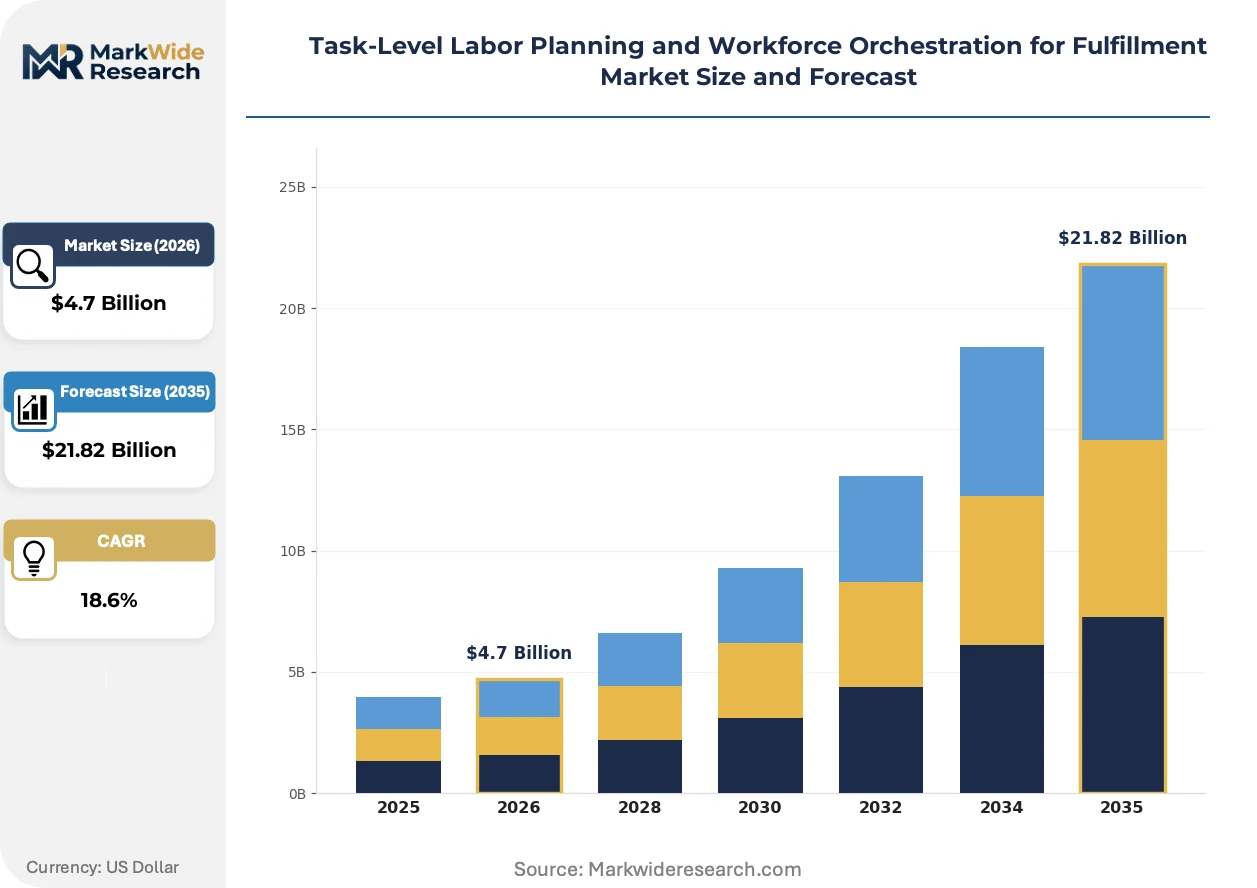
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Workforce Scheduling, Task Allocation, Labor Forecasting, Productivity Analytics, Compliance Management Deployment Model: Cloud-Based, On-Premises, Hybrid, Software as a Service, Edge Computing Industry Application: eCommerce Fulfillment, Third-Party Logistics Providers, Parcel Delivery Services, Direct-to-Consumer Operations End User Role: Warehouse Supervisors, Shift Managers, Operations Coordinators, Workforce Planners |
| Companies Covered | Manhattan Associates, Blue Yonder, UKG, SAP, Oracle, ADP, Workday, Dayforce, Legion Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market Trends and Innovations
Workforce deployment models are pivoting from schedule-based to event-driven architectures, with labor capacity becoming a dynamically priced resource responsive to real-time order volatility rather than fixed shift patterns.
Digital twin simulations of warehouse labor flows are integrating with live WMS data streams to pre-optimize picker paths before inbound shipments arrive. High-velocity eCommerce operators in the United States are deploying these synthetic environments to stress-test labor allocation algorithms against peak demand scenarios. The technology is integrating historically siloed planning horizons across workforce, inventory, and transportation teams.
The EU AI Act's human-in-the-loop requirements for automated shift assignments are mandating architectural overlays that preserve supervisor override capabilities within algorithmic decision chains. European fulfillment networks must now maintain audit trails documenting why specific workers received particular task sequences. German 3PLs are responding by procuring platforms with built-in explainability dashboards that surface the feature weights driving labor allocations.
Buyer procurement committees are consolidating vendor evaluation around unit-economics visibility rather than functional checklists. Mega-fulfillment networks now require labor platforms to attribute cost-per-touch down to individual SKU-location-worker combinations. This specification compression is most visible among China-based cross-border operators managing million-SKU catalogs across fragmented last-mile networks.
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market Segmentation
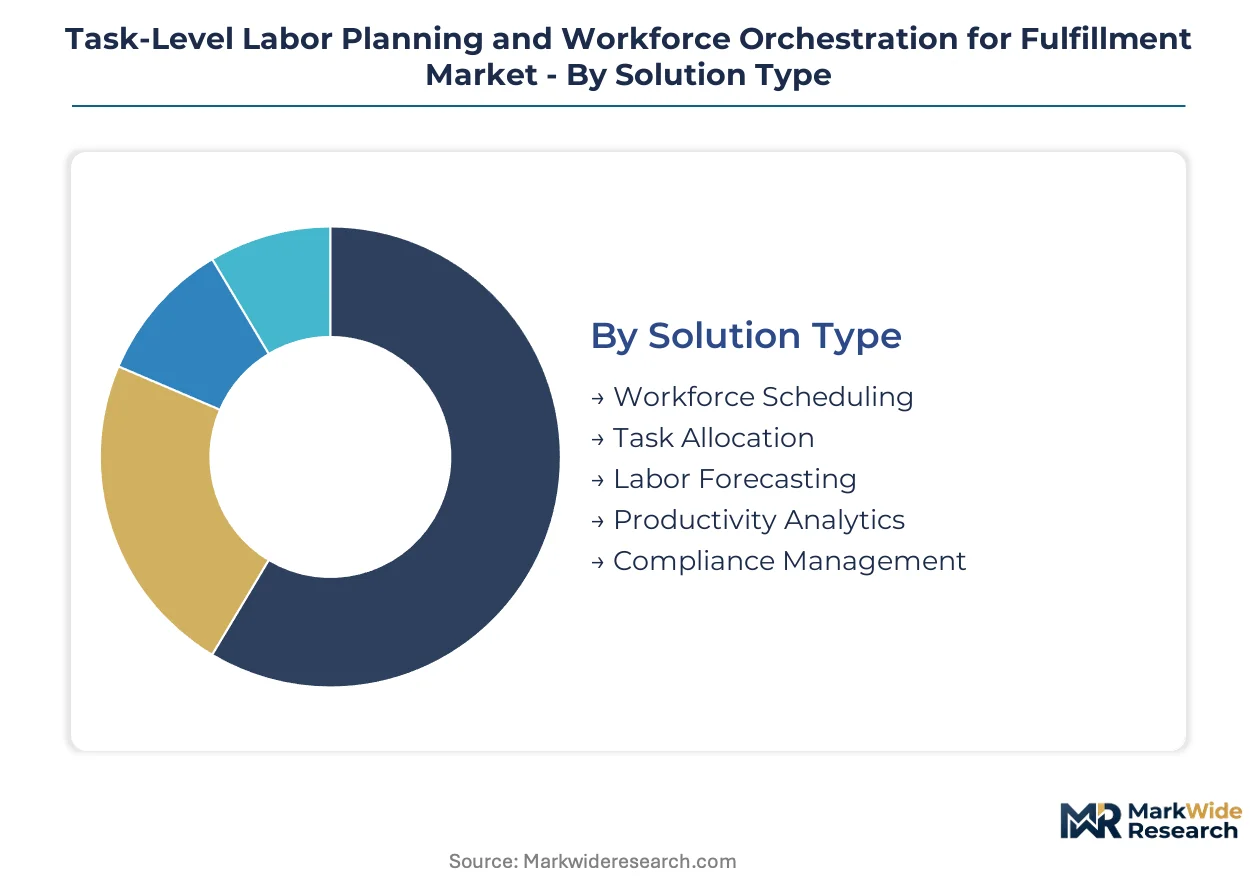
Segmentation reveals how labor orchestration platforms align with operational maturity and infrastructure constraints. Buyers select configurations based on WMS integration depth, real-time latency requirements, and workforce governance complexity.
Solution Type:
Volume deployment favors workforce scheduling modules, while premium procurement concentrates in analytics and compliance layers that deliver audit-ready transparency.
- Workforce Scheduling:Core shift-planning engines generate rosters against demand forecasts and labor availability constraints. Demand concentrates among United States eCommerce operators managing million-SKU variability across multi-warehouse networks. Cloud-native architectures now compress deployment timelines from quarters to weeks.
- Productivity Analytics:Unit-economics visibility platforms attribute cost-per-touch to individual picker-SKU-location combinations. German 3PLs are deploying these systems to satisfy EU AI Act explainability mandates for algorithmic performance scoring. Steepest expansion trajectory among all solution types.
- Task Allocation:Real-time work assignment algorithms match workers to discrete picking, packing, and staging activities based on skill matrices and proximity.
- Labor Forecasting:Demand-sensing modules project workforce requirements against inbound shipment waves and outbound carrier cutoffs.
- Compliance Management:Multi-jurisdiction shift rule engines navigate fragmented last-mile regulatory environments across state and national boundaries.
Mature deployment sits with Workforce Scheduling. Newer deployment is concentrated in Productivity Analytics.
Deployment Model:
Application latency and data sovereignty requirements fragment procurement across cloud, edge, and hybrid configurations.
- Cloud-Based:API-first platforms deliver workforce orchestration through browser-accessible dashboards with centralized model training. China-based cross-border operators favor these deployments for rapid scaling across dispersed fulfillment nodes. Dominant revenue share within the category.
- Edge Computing:On-premise neural processing units enable millisecond-level labor reallocation without cloud round-trip latency. United States cold chain operators deploy these for temperature-zone-restricted worker movements where connectivity is unreliable. Gaining share fastest as GPU module costs stabilize.
- Hybrid:Split architectures maintain sensitive compliance data on-premises while pushing optimization workloads to cloud inference.
- On-Premises:Fully captive installations serve operators with stringent data residency requirements or legacy WMS integration constraints.
- Software as a Service:Subscription models with pre-configured connectors to major WMS platforms reduce implementation overhead for mid-market 3PLs.
Established procurement favors Cloud-Based solutions. Emerging interest clusters around Edge Computing.
Industry Application:
End-use concentration tracks fulfillment network density and same-day delivery pressure intensity.
- eCommerce Fulfillment:High-velocity operators decompose warehouse operations into time-bound activities synchronized with sub-two-hour delivery windows. Demand concentrates in urban Germany and China where carrier cutoff density is highest. Largest addressable market within the segment.
- Third-Party Logistics Providers:Multi-tenant operators require platforms handling client-specific SLAs and billing attribution across shared labor pools. United States 3PLs are consolidating procurement around unit-economics visibility specifications.
- Parcel Delivery Services:Last-mile sortation hubs deploy task-level planning to synchronize induction, sort, and dispatch workflows with line-haul departure schedules.
- Direct-to-Consumer Operations:Branded fulfillment networks prioritize compliance engines that navigate OSHA ergonomic standards for repetitive-motion task assignments.
Volume concentration sits with eCommerce Fulfillment. Accelerating deployment is visible in Third-Party Logistics Providers.
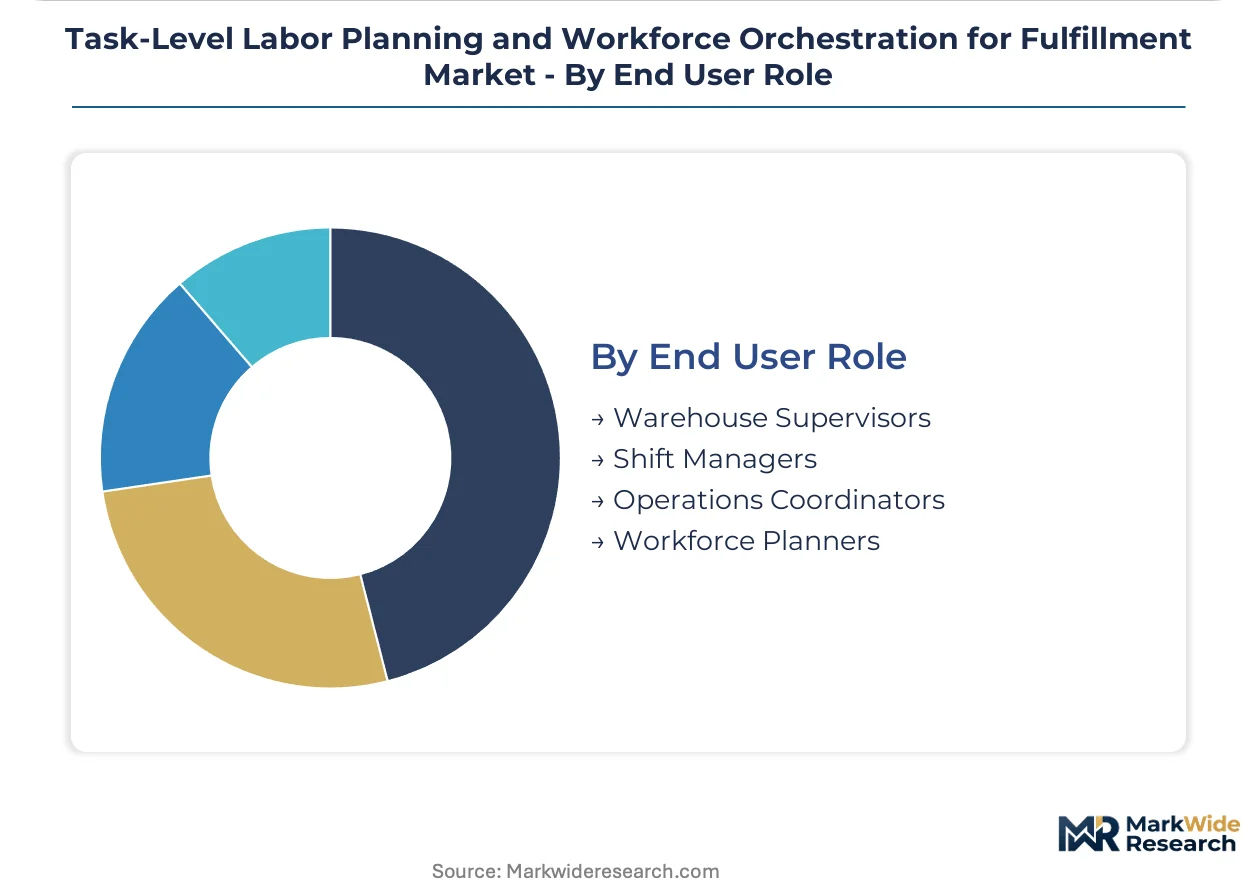
End User Role:
Platform interface design diverges based on decision authority and temporal scope of labor planning.
- Warehouse Supervisors:Floor-level oversight tools enable real-time task reassignment and exception handling during inbound wave disruptions. United States mega-fulfillment networks equip these users with override capabilities mandated by emerging algorithmic accountability frameworks.
- Workforce Planners:Strategic staffing modules project headcount requirements across seasonal demand cycles and network expansion timelines. Expanding most quickly as operators integrate labor planning with inventory and transportation horizons.
- Shift Managers:Mid-horizon scheduling interfaces balance labor supply against demand volatility within daily operating windows.
- Operations Coordinators:Cross-functional dashboards synchronize workforce deployment with AMR fleet movements and packing station capacity.
Established adoption centers on Warehouse Supervisors. Emerging procurement targets Workforce Planners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and China as fulfillment network density rises and same-day delivery pressure intensifies across urban logistics corridors.
United States
Mega-fulfillment networks in the United States are expanding adoption of granular labor orchestration platforms to manage million-SKU variability across multi-warehouse operations. OSHA warehouse safety standards are requiring continuous algorithmic retraining to ensure task assignments comply with lifting and motion limits. Urban fulfillment clusters in California and Texas are deploying event-driven workforce architectures to synchronize picker workflows with sub-two-hour delivery windows.
Germany
German 3PLs are procuring platforms with built-in explainability dashboards to satisfy EU AI Act transparency mandates for algorithmic shift assignments. The EU AI Act specifically mandates human oversight protocols for automated decision-making, forcing architecture changes in European deployments. Industrial logistics corridors around Frankfurt and Hamburg are integrating supply-chain-aware labor forecasting that extends planning horizons beyond conventional WMS boundaries.
China
China-based cross-border operators are favoring cloud-native deployments for rapid scaling across dispersed fulfillment nodes. GB standards for logistics informatization are shaping product roadmaps and vendor certification burdens for domestic deployments. The Yangtze River Delta and Pearl River Delta regions are driving cloud migration and AI-driven demand sensing that reshape workforce deployment models.
India
India's logistics PLI scheme is creating first-mover advantages for vendors establishing localized cloud regions to serve automated warehousing investments. Production-linked incentives from the central government are accelerating procurement of workforce orchestration platforms among domestic 3PLs. Maharashtra and Karnataka are emerging as concentration points for fulfillment network expansion requiring task-level labor planning capabilities.
United Kingdom
UK fulfillment operators are embedding compliance engines that navigate multi-jurisdiction shift rules across fragmented last-mile networks serving European cross-border demand. Post-Brexit regulatory divergence is forcing architecture adaptations for workforce platforms operating across UK-EU boundaries. The Midlands logistics corridor and Greater London are deploying hybrid cloud-edge configurations to balance data sovereignty requirements with real-time latency demands.
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue API-first interoperability and edge AI specializations. The vendor landscape stratifies across three maturity tiers: legacy WMS incumbents rearchitecting labor modules, cloud-native workforce specialists, and automation-integrated platform providers. Competitive positioning depends on throughput guarantee capabilities for high-velocity eCommerce operators and audit-ready transparency for European regulatory compliance. Dominant competitive moves include strategic partnerships with AMR fleet vendors and geographic expansion through localized cloud region establishment.
Within the cloud-native tier, Manhattan Associates and Blue Yonder exemplify divergent architectural approaches to labor orchestration. Manhattan Associates represents the WMS-anchored archetype extending into AI-native slotting for throughput guarantees. Blue Yonder occupies a position emphasizing supply-chain-aware labor forecasting with extended planning horizons. UKG sits within the compliance-embedded tier, navigating multi-jurisdiction shift rules across fragmented last-mile networks.
| Leading Market Players |
|---|
| Manhattan Associates |
| Blue Yonder |
| UKG |
| SAP |
| Oracle |
| ADP |
| Workday |
| Dayforce |
| Legion Technologies |
| Others |
Pricing and Supply Chain Analysis
Mega-fulfillment networks in the United States, Germany, and China command procurement leverage that compresses margins for vendors unable to deliver unit-economics visibility down to individual picker-SKU-location combinations. This buyer concentration rewards platforms with API-first interoperability and audit-ready transparency, while punishing legacy WMS incumbents with rearchitecting costs.
Pricing Analysis
Volume deployment concentrates in SaaS-tiered subscription models with pre-configured WMS connectors, while premium procurement commands value-based pricing for analytics layers delivering EU AI Act-compliant explainability dashboards. Price differentiation rests on certification depth—ISO 27001 data security tiers and SOC 2 Type II attestation separate premium vendors from standard-tier competitors. Pricing pressure stems from GPU and TPU module cost volatility compressing margins for edge-computing bundles. Mid-market 3PLs exhibit highest price sensitivity, whereas German 3PLs facing EU AI Act mandates demonstrate lowest sensitivity for audit-ready platforms.
Supply Chain Analysis
Certification gating from OSHA, EU AI Act transparency mandates, and China's GB standards for logistics informatization restricts vendor participation to those with multi-jurisdiction compliance engineering. Software development concentrates in the United States, cloud infrastructure provisioning centers on China and Germany, and edge hardware assembly feeds from Taiwan and South Korea. Raw material dependencies span neural processing units, industrial-grade sensors, and wearable task-assignment devices. Single-source vulnerability in GPU supply chains poses structural risk. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around cloud-native platforms with AI-native slotting capabilities, as technical debt in brownfield WMS forces weaker incumbents toward acquisition or exit. API-first interoperability and edge AI specializations are becoming table stakes for survival.
For Market Incumbents:Cement market position through backward integration into edge hardware supply chains, securing captive access to neural processing units amid GPU pricing volatility. Invest in explainability dashboard engineering to preempt EU AI Act compliance mandates. Defensive moves must address the threat from cloud-native workforce specialists rearchitecting deployment timelines from quarters to weeks.
For New Entrants and Emerging Players:Capture white-space in cold chain verticals where temperature-controlled operators lack specialized labor platforms accounting for garment-change time and zone-restricted worker movements. India's logistics PLI scheme offers the most penetrable geography for first-mover cloud region establishment. A vertical-specific go-to-market angle targeting pharmaceutical cold chain compliance requirements unlocks initial reference customers.
For Investors and Strategic Acquirers:The window for entry favors cloud-native workforce specialists with proven API-first interoperability and European regulatory certification. Long-term viability over the next decade hinges on convergence with computer vision and AMR fleet coordination capabilities. The signal to watch is procurement committee consolidation around unit-economics visibility specifications displacing functional checklist evaluations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first interoperability with best-of-breed WMS layers compresses deployment timelines from quarters to weeks. |
| Acquisition of Specialist Firm | Computer vision startups enable closed-loop performance optimization integrating with wearable task-assignment devices. |
| Geographic Expansion | Localized cloud regions in India capture production-linked incentive flows from automated warehousing investments. |
| Strategic Partnership | AMR fleet vendor alliances resolve integration complexity with multi-vendor automation control systems. |
| Product Launch | Explainability dashboards satisfy EU AI Act human-in-the-loop mandates for algorithmic shift assignments. |
Research Methodology
Multi-period observation of deployment model migrations, regulatory certification timelines, and procurement committee evaluation criteria anchored the trend analysis, supplemented by interviews with warehouse operations directors, workforce planning managers, WMS integration specialists, and 3PL procurement leads. Secondary validation drew from SEC 10-K filings of publicly traded logistics software vendors, OSHA enforcement databases, EU AI Act implementation guidance, and hyperscaler capex disclosures for cloud infrastructure expansion. Bottom-up sizing of individual solution type deployments triangulated against top-down market aggregation.
Segment-weighting across solution type, deployment model, industry application, and end user role dimensions informed the analytical framework throughout the projection horizon. CAGRs derived from logistic growth curve fitting against historical adoption velocity patterns, with cross-segment consistency checks ensuring coherent expansion trajectories. Industry-specific forecast inputs incorporated cloud migration timelines for brownfield WMS operators and GPU cost stabilization assumptions for edge computing penetration.
The model holds under sustained eCommerce fulfillment network expansion and stable regulatory enforcement intensity; deviation in OSHA ergonomic standard revisions or EU AI Act penalty implementation would shift vendor competitive positioning and procurement urgency. A model refresh is warranted upon material change in edge hardware input cost trajectories or AMR fleet interoperability standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Workload Scheduling and Automation Market
Automation
Pneumatic Tube System Market
Automation
Terminal Automation Systems Market
Automation
Home Automation System Market
Automation
RFID Kanban Systems Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Europe Laboratory Automation Market
Automation
Voice Picking Solutions Market
Automation
Europe Data Center Automation Market
Automation
Italy Process Orchestration Market
Automation
Micro Fulfillment Market
Automation
Modular Laboratory Automation Market
Automation
Self Bag Drop Machine Market
Automation
Marketing Automation Solutions Market
Automation
Workflow Automation Market
Automation
Global Field Force Automation Market