
 Content Intelligence Market | 2026-2036
Content Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Content Intelligence Market Analysis
The EU AI Act is consolidating compliance obligations for automated content generation, pushing enterprises toward transparent, auditable intelligence platforms. Adobe Inc. leverages its creative cloud ecosystem to anchor content intelligence within design workflows. IBM Corporation competes through Watson's natural language processing specialization for regulated industries. Google LLC dominates search-integrated content analytics, extending its data advantage into recommendation engines.
Content intelligence encompasses technologies that extract semantic meaning, predict audience engagement, and automate content optimization across digital channels. Systems typically process unstructured text, image, and video data through machine learning pipelines that score relevance, tone, and conversion probability before distribution. Natural language processing applications lead current deployment, with sentiment analysis and automated writing commanding the largest share of enterprise budgets. Cloud-based delivery is expanding fastest as marketing teams prioritize elastic scaling over on-premises infrastructure control.
The EU AI Act and GDPR jointly constrain how training data is sourced and how algorithmic outputs are explained to end users, elevating demand for explainable AI modules. The U.S. lacks federal AI legislation, yet the FTC's advertising disclosure requirements and emerging state-level privacy laws in California and Virginia create a fragmented compliance map. Stakeholders must monitor regulatory divergence between Brussels and Washington to avoid architecture lock-in that complicates multi-jurisdictional deployment.
Market Dynamics
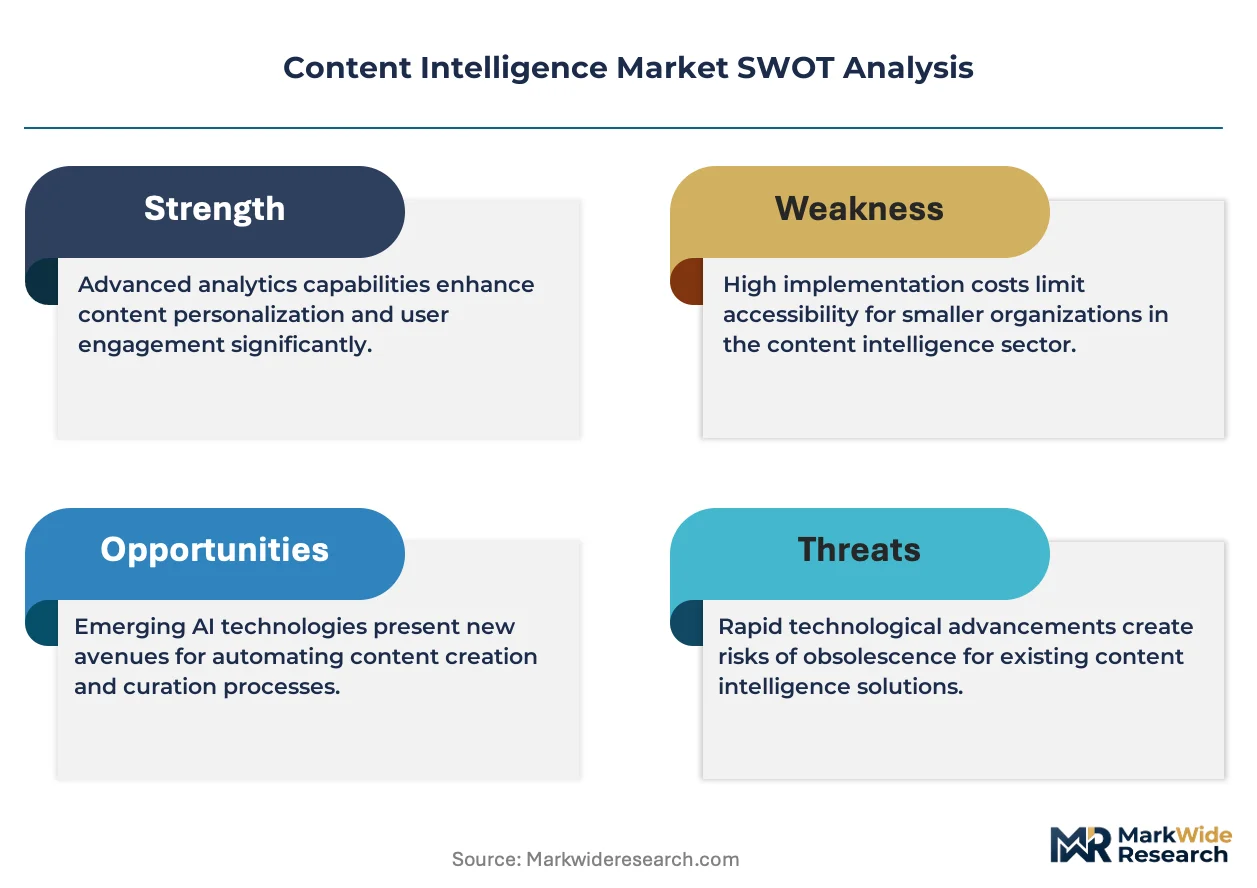
The EU AI Act's risk-classification framework is forcing enterprise content platforms to rebuild their algorithmic audit trails. This regulatory pressure is compressing vendor consolidation timelines and reshaping procurement criteria across automated content systems.
Growth Catalysts
- GDPR Article 22 mandates:European enterprises must deploy explainable AI for automated decision-making, accelerating procurement of auditable content intelligence modules that document training provenance and output logic.
- Media agency workflow automation:United States-based creative shops are embedding sentiment scoring and predictive engagement tools directly into Adobe Creative Cloud and competing design environments.
- Natural language processing maturation:Transformer architectures now enable real-time tone adjustment and multilingual optimization, reducing manual localization overhead for global brand campaigns.
Market Restraints
- Training data scarcity:High-quality labeled datasets for niche verticals command premium licensing fees, compressing margins for mid-market platform vendors without proprietary data moats.
- Compute cost volatility:GPU cluster pricing fluctuates with semiconductor foundry capacity constraints, particularly affecting on-premises deployment models dependent on NVIDIA H100 supply.
- Algorithmic bias liability:The EU AI Act's prohibited-practices list exposes vendors to fines up to 6% of global turnover for systems generating discriminatory outputs, elevating compliance insurance costs.
Strategic Opportunities
- India's digital advertising expansion:The country's programmatic media spending is outpacing infrastructure maturity, creating first-mover advantage for cloud-native content intelligence platforms with rupee-denominated pricing.
- Video-first content convergence:Multimodal models that unify text, image, and video analysis are penetrating creator economy platforms where legacy tools handled formats separately.
- CSRD disclosure requirements:European sustainability reporting mandates are spawning demand for automated ESG narrative generation and stakeholder communication optimization tools.
Industry Challenges
- MLOps talent scarcity:Enterprises struggle to hire engineers capable of maintaining production-grade NLP pipelines, particularly for systems requiring continuous retraining on fresh engagement data.
- Legacy CMS integration friction:Decade-old content management architectures lack API flexibility, forcing expensive middleware development to connect modern intelligence layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Intelligence Market |
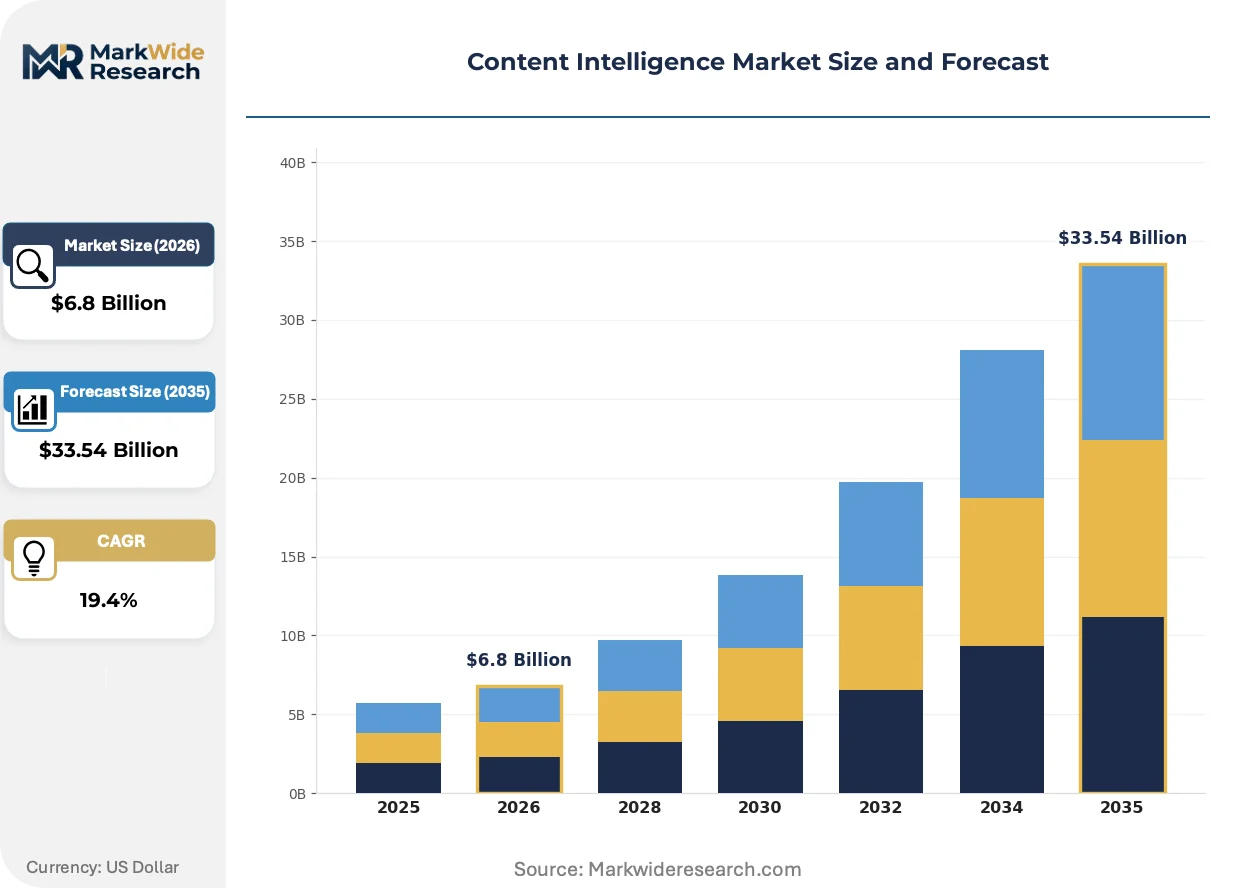
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $33.54 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Artificial Intelligence, Data Analytics Application: Content Recommendations, Sentiment Analysis, Automated Writing, Content Personalization End User: Media Agencies, Content Creators, Enterprises, Marketing Teams Deployment: Cloud-Based, On-Premises, Hybrid, Software as a Service |
| Companies Covered | Adobe Inc., Microsoft Corporation, Google LLC, IBM Corporation, OpenText Corporation, Semrush, M-Files, ABBYY, Laserfiche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Intelligence Market Emerging Trajectories
Foundation models are compressing the feature gap between specialized content tools and general-purpose AI platforms. This convergence is redrawing competitive boundaries and forcing incumbent vendors to reposition around data governance and workflow integration.
Multimodal transformer architectures is unifying text, image, and video understanding within single inference pipelines. Media agencies in Germany and France are piloting these systems for cross-format campaign optimization, collapsing what previously required three separate vendor relationships into unified workflows. The structural consequence is unifying creative production and performance analytics under shared model governance, reducing vendor fragmentation.
REACH chemical substance restrictions are extending to AI hardware supply chains, affecting data center construction for training clusters. European cloud providers must now document GPU and cooling system material compliance, adding 4-6 months to facility commissioning. German industrial AI labs are responding by pre-certifying hardware configurations and shifting some training workloads to Swiss and Norwegian facilities with established green energy credentials.
Buyer procurement committees are expanding to include chief ethics officers and legal counsel alongside traditional marketing stakeholders. United States enterprise RFPs now mandate algorithmic impact assessments and bias testing protocols before pilot authorization. This behavioral shift is most visible in financial services and healthcare verticals, where procurement cycles have lengthened but contract values have increased to cover integrated compliance tooling.
Content Intelligence Market Segmentation
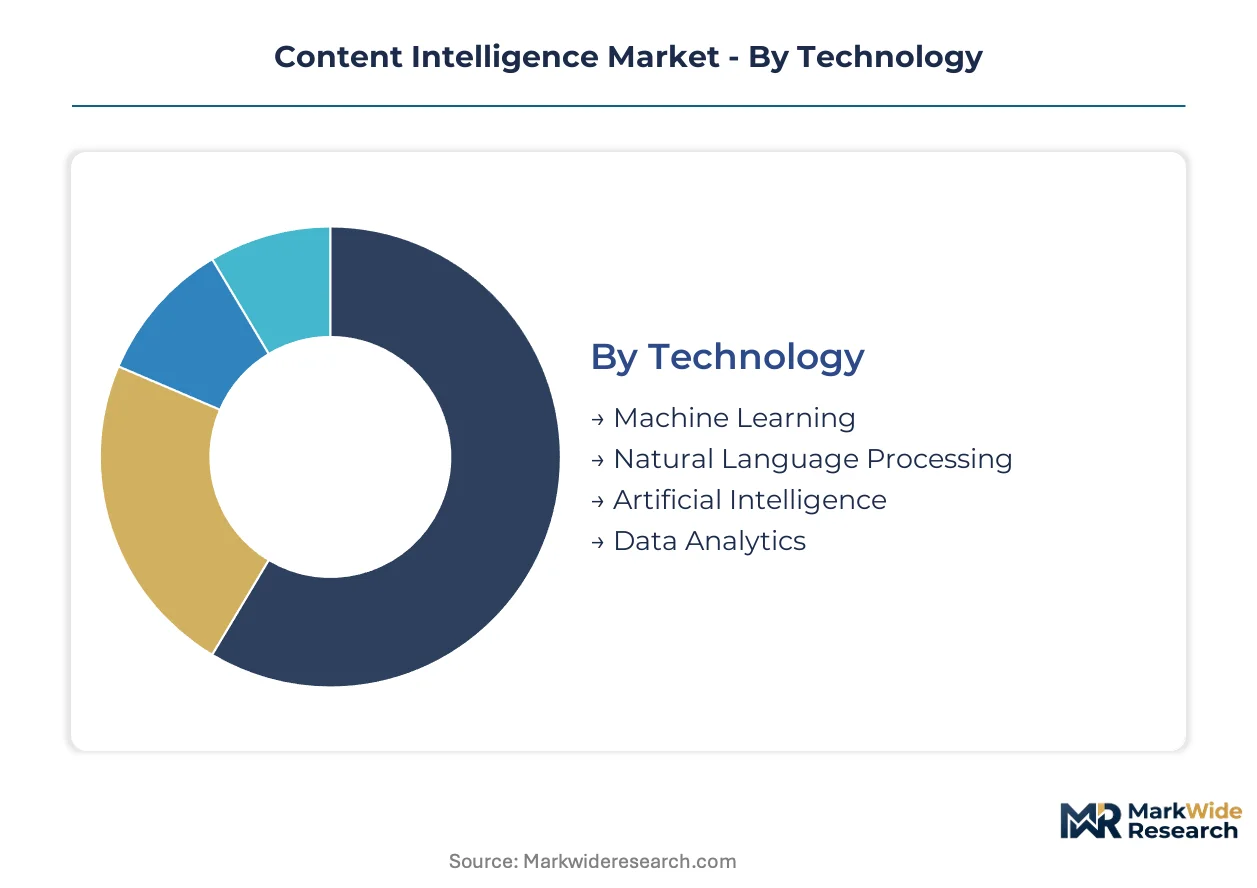
Content intelligence platforms serve divergent workflow requirements across creative production, media buying, and enterprise governance. Technology architecture, deployment model, and end-user sophistication create distinct procurement patterns that vendors must navigate.
Technology:
Technical capabilities differentiate platform performance across semantic extraction, predictive scoring, and automated generation tasks.
- Natural Language Processing:Transformer-based architectures parse sentiment, tone, and engagement probability from unstructured text. Media agencies in the United States deploy these systems for real-time campaign optimization, driven by pressure to collapse manual copy review cycles.
- Machine Learning:Supervised and reinforcement learning pipelines train on engagement feedback loops to refine content scoring models. European enterprises prioritize ML modules with documented training provenance to satisfy EU AI Act audit requirements.
- Artificial Intelligence:Broad category encompassing neural architectures for multimodal content understanding.
- Data Analytics:Descriptive and diagnostic tools aggregate performance metrics without predictive generation capabilities.
Mature deployment sits with Natural Language Processing. Newer deployment is concentrated in multimodal Artificial Intelligence architectures.
Application:
Use case specialization determines integration depth with creative workflows and martech stacks.
- Automated Writing:Large language models generate draft copy, social posts, and long-form content with adjustable tone parameters. Marketing teams at Fortune 500 enterprises embed these tools directly into Adobe Creative Cloud workflows, compressing production timelines.
- Sentiment Analysis:Real-time emotion detection scores audience reactions across social channels and customer feedback streams. Media agencies deploy sentiment dashboards to redirect live campaign spend based on shifting audience mood.
- Content Recommendations:Algorithmic curation engines match assets to user profiles for engagement maximization.
- Content Personalization:Dynamic assembly of modular content blocks tailored to individual viewer attributes.
Content Recommendations dominate current enterprise procurement volumes. Automated Writing is climbing the fastest as generative capabilities mature.
End User:
Buyer sophistication and compliance exposure shape platform configuration requirements.
- Media Agencies:High-volume creative shops require elastic scaling and multi-client data isolation. United States-based agencies lead SaaS adoption for sentiment scoring and predictive engagement tools integrated with demand-side platforms.
- Enterprises:Regulated industries demand auditable AI governance and explainable output logic. Financial services and healthcare verticals in Germany and France extend procurement cycles to embed bias testing and algorithmic impact assessments.
- Marketing Teams:Department-level buyers prioritize workflow integration over governance depth.
- Content Creators:Individual practitioners and creator economy platforms seek lightweight, low-cost tooling.
Enterprises anchor contract value with compliance-heavy configurations. Content Creators represent the steepest expansion trajectory as influencer platforms democratize access.
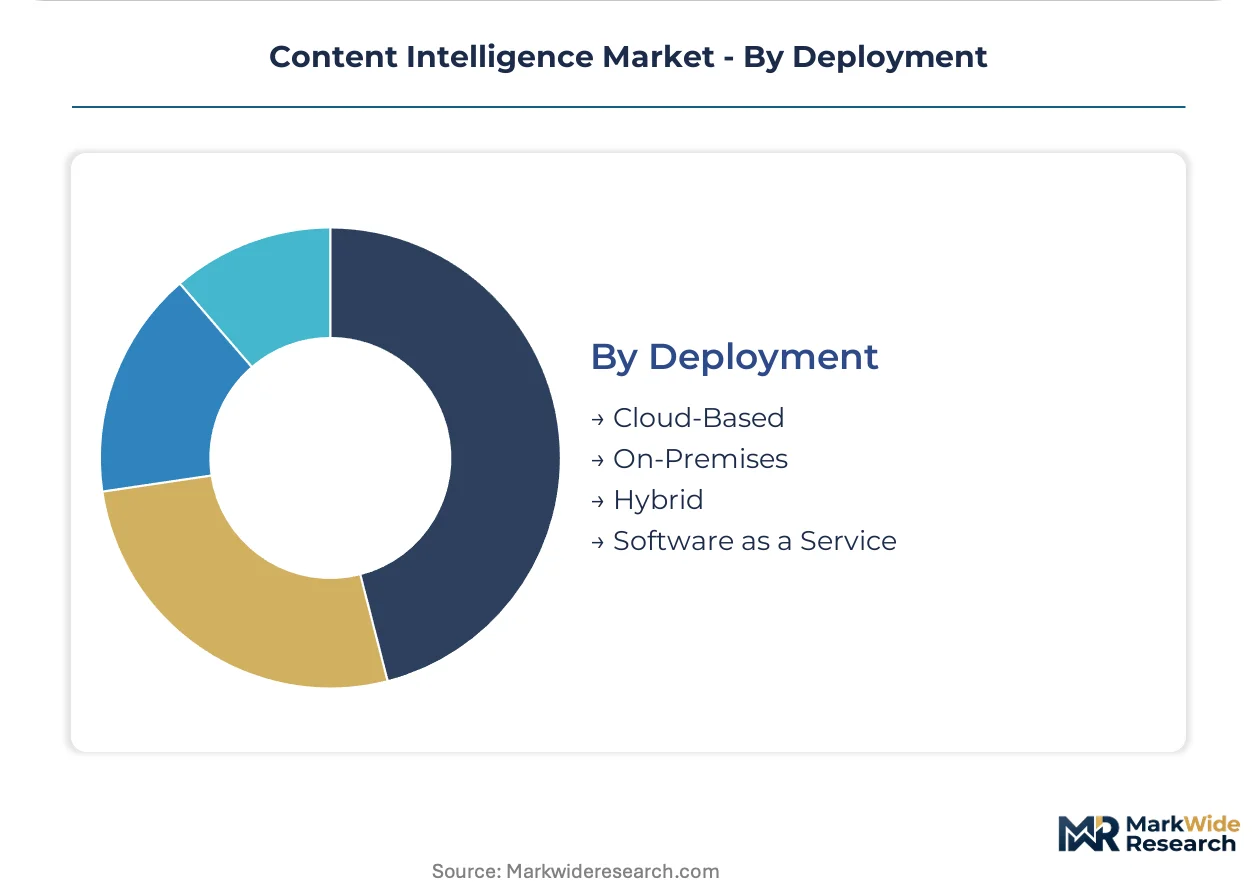
Deployment:
Infrastructure location determines data sovereignty, latency, and operational control tradeoffs.
- Cloud-Based:Elastic compute resources scale with campaign volatility without capital expenditure. Marketing teams prioritize cloud delivery for rapid deployment and automatic feature updates, particularly in media agency environments.
- Software as a Service:Managed application layers abstract infrastructure complexity while preserving configuration flexibility. European buyers scrutinize SaaS vendor data residency commitments to align with GDPR processing location requirements.
- On-Premises:Air-gapped installations serve defense, intelligence, and highly regulated financial institutions with classified content workflows.
- Hybrid:Split architectures route sensitive training data on-premises while pushing inference workloads to cloud edge nodes.
On-Premises installations concentrate in defense and classified financial sectors. Cloud-Based configurations are gaining share fastest as elastic scaling outweighs infrastructure control preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates content intelligence platform development and enterprise procurement, while demand growth accelerates faster in European and Asian markets navigating regulatory complexity and digital advertising expansion.
United States
Media agencies in New York and Los Angeles deploy sentiment analysis tools integrated with demand-side platforms for real-time campaign optimization. The FTC's advertising disclosure requirements and emerging state privacy laws in California and Virginia create fragmented compliance obligations. Silicon Valley cloud providers anchor infrastructure investment for generative content pipelines serving Fortune 500 marketing teams.
Germany
Industrial marketing teams in automotive and machinery sectors demand auditable AI governance for content personalization workflows. The EU AI Act's risk-classification framework and GDPR Article 22 mandates force algorithmic impact assessments before deployment. Munich and Frankfurt host specialized compliance consultancies helping enterprises document training provenance and output logic.
United Kingdom
London-based creative shops embed predictive engagement scoring into Adobe Creative Cloud workflows for financial services and luxury brand campaigns. The Information Commissioner's Office enforces automated decision-making transparency rules that align with Brussels standards post-Brexit. The Manchester media cluster experiments with multimodal transformer architectures for cross-format campaign unification.
India
Programmatic media spending in Mumbai and Bangalore outpaces infrastructure maturity, creating first-mover openings for cloud-native platforms with rupee-denominated pricing. The Digital Personal Data Protection Act establishes consent frameworks for training data sourcing that vendors must navigate. The Bengaluru SaaS corridor attracts venture capital for creator economy tools targeting influencer marketing automation.
France
Parisian luxury houses deploy multilingual content optimization for global brand consistency across digital channels. The CNIL interprets GDPR restrictions on automated profiling that constrain recommendation engine architectures. The Sophia Antipolis technology park hosts R&D facilities for sentiment analysis tools serving European media conglomerates.
Content Intelligence Market Vendor Landscape
The competitive structure tilts toward diversified technology conglomerates with adjacent cloud and creative software ecosystems. Adobe Inc., Microsoft Corporation, and Google LLC anchor the premium tier through workflow integration advantages, while specialized vendors compete on vertical compliance depth. Two strategic archetypes dominate: horizontal platform providers extending AI layers into existing creative suites, and vertical specialists building audit-ready systems for regulated industries. Consolidation pressure intensifies through strategic partnerships between cloud infrastructure providers and compliance-focused middleware developers, alongside geographic expansion into underpenetrated Asian markets.
Within the diversified technology tier, Adobe Inc. and Microsoft Corporation exemplify platform consolidation strategies that embed content intelligence within broader creative and productivity ecosystems. IBM Corporation occupies a specialist position serving financial services and healthcare verticals with governance-heavy configurations. These three companies represent contrasting approaches to the compliance-versus-scale tradeoff shaping procurement decisions across enterprise segments.
| Leading Market Players |
|---|
| Adobe Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| OpenText Corporation |
| Semrush |
| M-Files |
| ABBYY |
| Laserfiche |
| Others |
Supply Flow & Price Mechanics
Transformer model commoditization is collapsing inference costs while concentrating training infrastructure among hyperscalers with captive GPU supply, simultaneously democratizing access for mid-market buyers and entrenching pricing power at the infrastructure layer.
Pricing Analysis
Cost-down pressure on SaaS tiers accelerates as open-source foundation models erode proprietary model premiums, forcing vendors toward workflow integration value capture. Pricing stratifies across enterprise compliance bundles, mid-market feature tiers, and creator economy usage-based models. Brand premium and API call volume anchor differentiation. Mid-market marketing teams exhibit highest price sensitivity; regulated financial services buyers prioritize auditability over cost.
Supply Chain Analysis
Regional distribution centers for AI inference capacity cluster in Northern Virginia, Frankfurt, and Singapore to minimize latency for real-time content optimization workloads. GPU supply draws from Taiwan Semiconductor Manufacturing, NVIDIA design centers in the United States, and Samsung foundry capacity in South Korea. Single-source vulnerability concentrates in advanced packaging substrates. Distribution runs through hyperscaler marketplaces and direct enterprise licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Content intelligence is becoming a vertical-integration race as platform vendors pursue backward integration into proprietary training data pipelines to escape licensing cost spirals and establish differentiation moats.
For Market Incumbents: Hedge against open-source model disruption by embedding governance tooling deeper into Adobe Creative Cloud and Microsoft 365 workflows where switching costs compound. Acquire specialized compliance middleware vendors before EU AI Act enforcement hardens procurement criteria. Prioritize in-house data collection infrastructure over third-party training dataset licensing.
For New Entrants and Emerging Players: Enter via India's programmatic advertising expansion where rupee-denominated pricing and infrastructure immaturity create first-mover windows. Target creator economy platforms with lightweight multimodal tools that unify text, image, and video generation. Pursue channel partnerships with influencer marketing agencies rather than direct enterprise sales.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking compliance-ready AI governance layers. Long-term viability favors vendors with proprietary data flyworms and regulatory certification depth. Watch for EU AI Act enforcement actions as inflection indicators for compliance-tooling valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding sentiment scoring into Adobe Creative Cloud compresses agency workflow friction and raises switching costs. |
| Acquisition of Specialist Firm | Buying compliance middleware vendors addresses EU AI Act audit requirements before procurement cycles lengthen. |
| Geographic Expansion | Launching rupee-denominated cloud instances captures India's programmatic advertising growth ahead of infrastructure maturation. |
| Strategic Partnership | Aligning with NVIDIA for GPU allocation secures training capacity amid semiconductor foundry constraints. |
| Product Launch | Releasing multimodal transformer tools unifies creative production previously requiring three separate vendor relationships. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with chief marketing officers, MLOps engineering leads, agency creative directors, and procurement officers at media conglomerates. SEC 10-K disclosures, EU AI Act implementation guidance, and hyperscaler capex reports provided triangulation anchors. Bottom-up deployment estimates and top-down market sizing were reconciled across technology, application, and deployment model segments.
Data-stream reconciliation applied across the projection horizon, modeling natural language processing, machine learning, and multimodal AI architectures separately. Deployment patterns by organization size, vertical compliance exposure, and regional regulatory cluster shaped segment-level CAGRs. GPU supply constraints, EU AI Act enforcement timelines, and programmatic advertising spend trajectories informed scenario weighting.
Revisions become necessary when semiconductor foundry capacity constraints ease, EU AI Act enforcement actions accelerate, or foundation model commoditization outpaces workflow integration value capture. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Network Analysis Module (NAM) Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Canada Contact Center Analytics Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Patent Analytics Services Market
Analytics
Europe Network and Location Analytics Market
Analytics
Multichannel Analytics Market
Analytics
Crowd Analytics Market
Analytics
Italy ICT Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Data Wrangling Market
Analytics
Procurement Analytics Market
Analytics
Global System Monitoring Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Load (ETL) Market
Analytics
Europe Mobile Analytics Market