
 Asia-Pacific Micro Fulfillment Market | 2026-2036
Asia-Pacific Micro Fulfillment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Micro Fulfillment Market Insights
Software-defined fleet orchestration is decoupling hardware ownership from operational capability in micro fulfillment. Geek+ leverages its AMR-native architecture to anchor deployments across Chinese grocery chains. HAI Robotics sustains leadership in dense cube-storage configurations for vertical space optimization. Exotec SAS competes through modular robotic systems that navigate constrained Asian urban footprints.
Micro fulfillment denotes compact, highly automated order-assembly systems typically occupying under 10,000 square feet, utilizing shuttle-based or robotic cube storage with sub-minute retrieval cycles to position inventory within final-mile delivery range. Automated Systems and Robotics product categories currently absorb the majority of capital allocation, while Inventory Management Software captures expanding recurring revenue as operators prioritize real-time demand forecasting. E-commerce Platforms represent the fastest-growing end-user segment, though Grocery Stores retain the densest installation base due to perishable throughput requirements.
China's SAMR enforces robotics safety certifications under GB standards that govern warehouse automation deployments, while Singapore's IMDA coordinates 5G spectrum allocation to enable low-latency IoT mesh networks in fulfillment nodes. India's TRAI broadband directives and South Korea's MSIT smart logistics frameworks collectively shape connectivity prerequisites for AI-driven inventory systems. Stakeholders must weigh regulatory compliance timelines against the pace of urban real estate compression when selecting market entry sequencing.
Market Dynamics
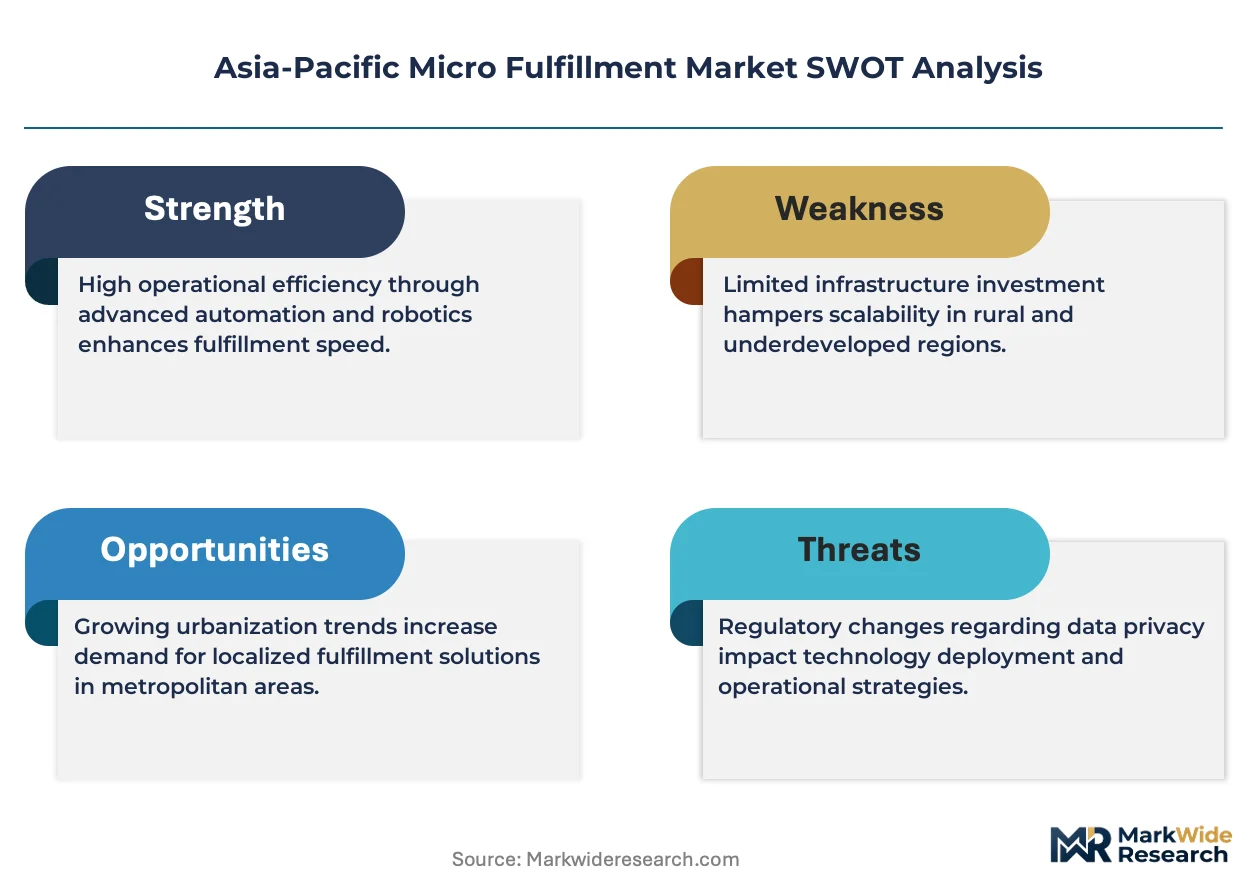
Urban land scarcity across Asia-Pacific tier-one cities is compressing fulfillment footprints into basement and backroom spaces, forcing automation density to rise while floorplates shrink below 10,000 square feet.
Growth Catalysts
- 5G spectrum allocation:Singapore's IMDA and South Korea's MSIT have released low-latency bands that enable real-time IoT mesh networks in compact fulfillment nodes, accelerating robotic deployment timelines.
- Perishable throughput mandates:Australian and Japanese grocery chains face same-day delivery SLAs that human-pick operations cannot satisfy, driving capital allocation toward sub-minute retrieval systems.
- Basement real estate conversion:Shanghai and Beijing developers are repurposing underground parking structures into automated cube-storage facilities to circumvent above-ground zoning restrictions.
Market Restraints
- Steel and servo motor cost volatility:Chinese AMR manufacturers face input price swings from rare earth magnet supply concentration in Inner Mongolia processing clusters.
- GB certification timelines:SAMR's robotics safety standards require 8-14 month validation cycles that delay deployment revenue recognition for hardware vendors.
- High-bay concrete retrofit requirements:Existing urban logistics buildings lack floor load capacity for dense cube-storage systems, forcing structural reinforcement capex that operators cannot amortize across short lease terms.
Strategic Opportunities
- India's TRAI broadband mandates:Rural fiber rollout creates edge-compute nodes that enable micro fulfillment in secondary cities previously excluded from same-day networks.
- Fresh produce consolidation:Wet market digitization in Vietnam and Indonesia creates demand for temperature-controlled robotic picking in 2,000-4,000 square foot formats.
- AI vision convergence with AMR navigation:Multi-modal sensor fusion is opening shelf-based picking for non-cuboidal inventory like bakery trays and floral arrangements.
Industry Challenges
- Mechatronics technician scarcity:Maintenance skill gaps in Indonesia and Philippines force operators to import calibration specialists from Japan and South Korea at 3-4x local wage premiums.
- Warehouse management system integration:Legacy ERP architectures in incumbent grocery chains require custom API middleware that extends commissioning timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Micro Fulfillment Market |
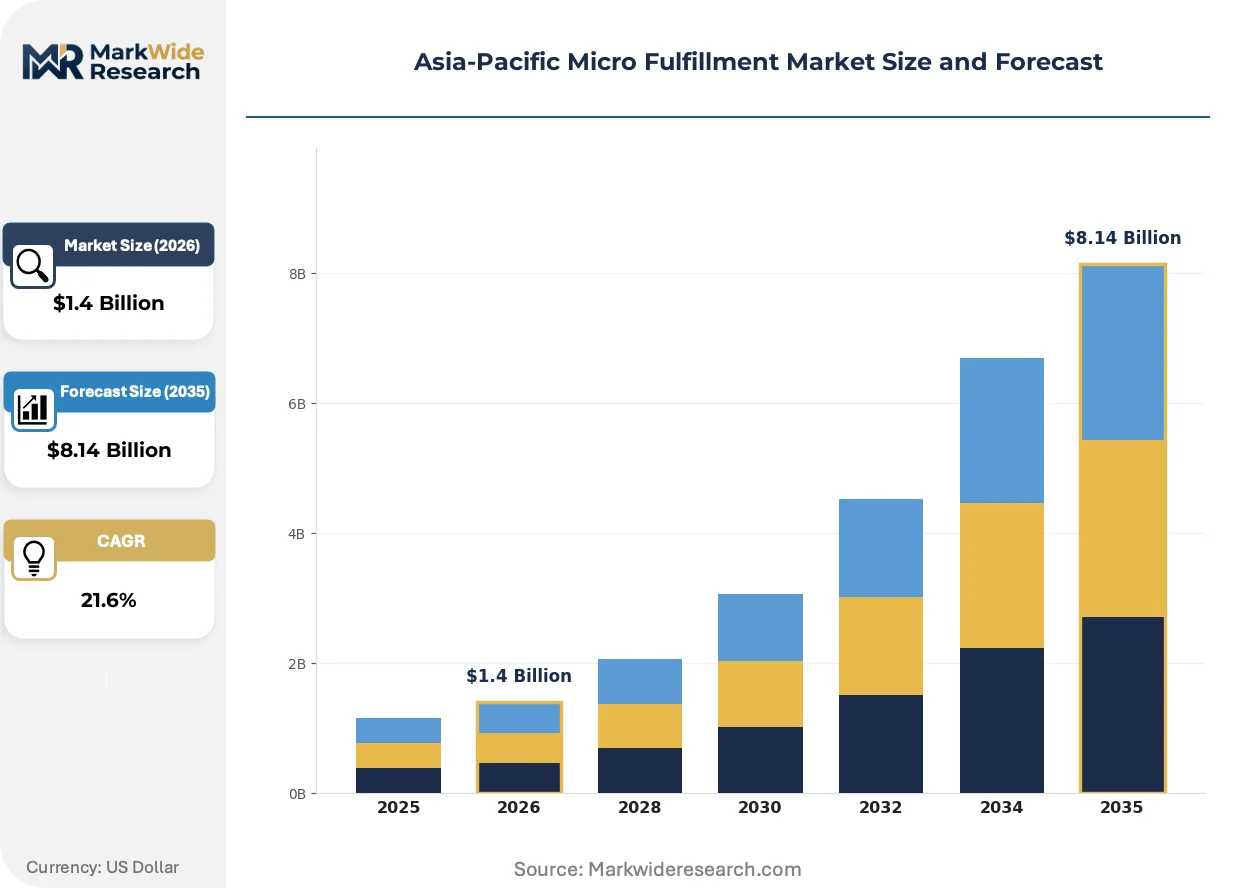
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $8.14 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Smart Lockers, Robotics, Inventory Management Software End User: Retail Chains, E-commerce Platforms, Grocery Stores, Wholesalers Technology: Artificial Intelligence, Internet of Things, Robotics Process Automation, Computer Vision Service Type: Consulting, Integration, Maintenance, Managed Services |
| Companies Covered | HIK Robotics, Exotec SAS, Geek+, Takeoff Technologies, Dematic, HAI Robotics, AutoStore, Fabric, GreyOrange, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Micro Fulfillment Market Trends and Innovations
Software-defined orchestration is decoupling automation hardware from operational control, allowing operators to swap robotic subsystems without rewiring warehouse management logic. This architectural shift is compressing technology refresh cycles and expanding vendor switching options.
Shuttle-based cube storage is electrifying vertical space utilization in constrained Asian urban footprints. Chinese grocery chains are adopting 15-20 meter high-bay configurations that triple inventory density against conventional shelving. The structural consequence is electrifying basement and backroom conversion economics, enabling positive ROI on real estate previously written off as too small for automation.
Singapore's IMDA 5G spectrum framework is mandating network slicing provisions for industrial IoT that guarantee sub-10 millisecond latency for robotic coordination. This regulatory architecture is forcing telecom operators to engineer dedicated fulfillment-node coverage maps. Japanese and South Korean logistics clusters are responding by specifying 5G-native AMR fleets in procurement tenders, locking out WiFi-dependent legacy systems.
Buyer concentration among pan-Asian e-commerce platforms is compressing vendor negotiation timelines from 18-month cycles to 90-day pilot-to-scale commitments. Grocery incumbents in Australia and Japan are responding by unbundling automation procurement from warehouse construction, awarding separate contracts to robotics specialists and real estate developers. This bifurcation is most visible in Sydney and Tokyo, where operators now lease pre-automated "robotics-ready" shell space rather than retrofitting owned facilities.
Asia-Pacific Micro Fulfillment Market Segmentation
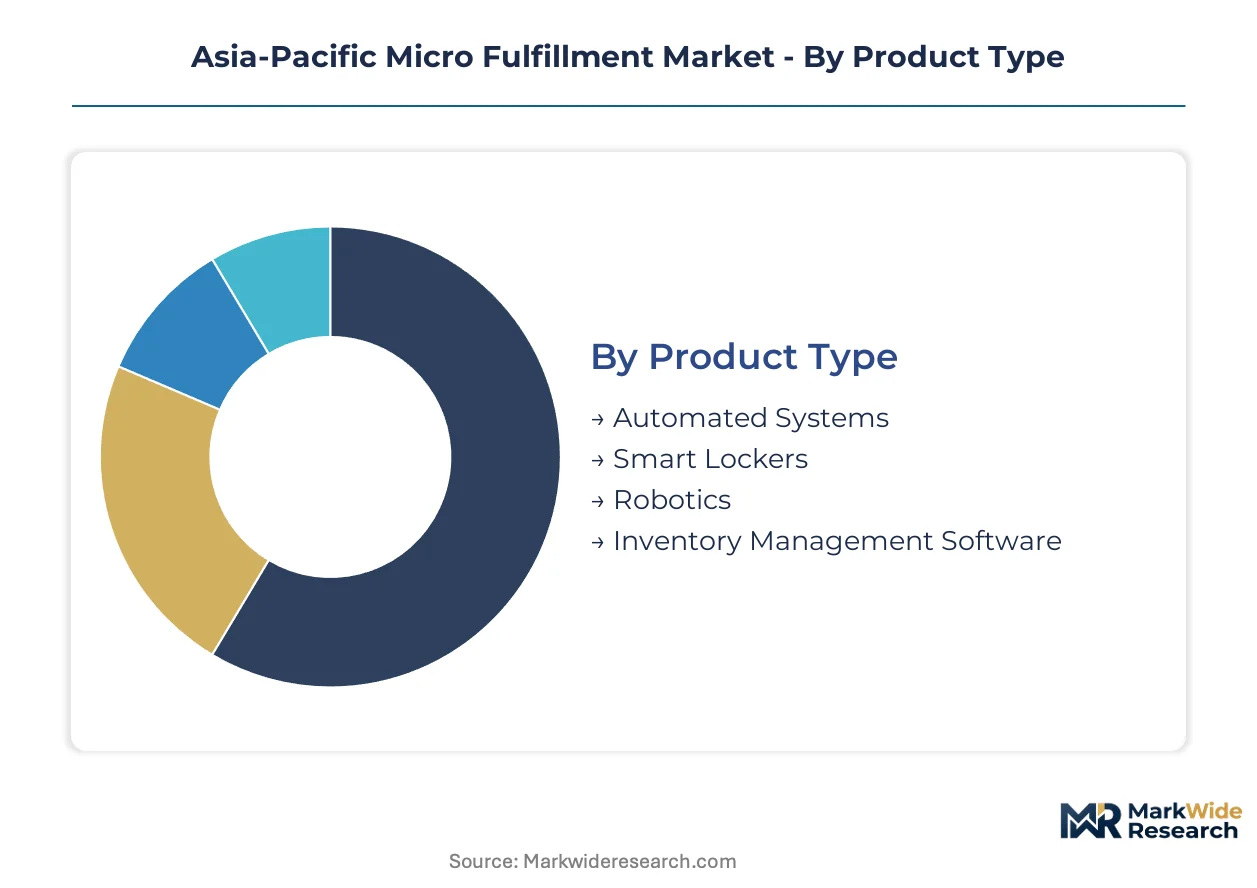
Micro fulfillment segmentation reveals how automation hardware, software intelligence, and service layers interlock to solve last-mile density constraints. Each category maps to distinct procurement patterns across grocery chains, e-commerce platforms, and third-party logistics operators competing on delivery speed.
Product Type:
Standalone automated systems dominate capital expenditure budgets, while embedded software modules penetrate through retrofit installations in existing warehouse footprints.
- Automated Systems:Shuttle-based cube storage and vertical lift modules compress retrieval cycles below 60 seconds. Australian and Japanese grocery chains deploy these in basement conversions to meet same-day SLAs without expanding above-ground footprints.
- Robotics:Autonomous mobile robots and articulated pick arms handle non-standard inventory shapes. Chinese tier-one cities concentrate deployment where labor costs intersect with 24-hour delivery mandates from platform economics.
- Smart Lockers:Temperature-controlled pickup nodes extend fulfillment reach into residential compounds. Singapore and South Korea regulate these as telecommunications infrastructure under IMDA and MSIT frameworks.
- Inventory Management Software:Real-time demand forecasting modules integrate with existing WMS architectures through API middleware. Recurring revenue models attract capital allocation from operators prioritizing operational flexibility over hardware ownership.
Automated Systems leads volumes today; Inventory Management Software is gaining share fastest.
End User:
Procurement scale and urgency separate high-velocity perishable handlers from general merchandise operators with longer fulfillment windows.
- Grocery Stores:Perishable throughput requirements drive the densest installation base. Australian chains retrofit backrooms with sub-10,000 square foot automated configurations to preserve margins on same-day delivery commitments.
- E-commerce Platforms:Pan-Asian marketplace operators compress vendor negotiation timelines to 90-day pilot-to-scale commitments. Their procurement volume forces robotics vendors to standardize modular architectures.
- Retail Chains:Apparel and electronics retailers deploy micro fulfillment for click-and-collect consolidation. Japanese department stores prioritize 5G-native AMR fleets to coordinate peak-season inventory surges.
- Wholesalers:Foodservice distributors in Vietnam and Indonesia adopt 2,000-4,000 square foot temperature-controlled formats for wet market digitization.
Grocery Stores anchor current deployment density; E-commerce Platforms are expanding most quickly.
Technology:
Connectivity infrastructure maturity determines which technology layers activate first in each national market.
- Artificial Intelligence:Demand forecasting and dynamic slotting algorithms optimize cube storage density. Indian operators leverage TRAI-mandated rural fiber rollout to deploy edge-compute nodes in secondary cities.
- Internet of Things:Sensor mesh networks track inventory condition and robotic health in real time. Singapore's IMDA 5G spectrum slicing provisions guarantee sub-10 millisecond latency for fleet coordination.
- Computer Vision:Multi-modal sensor fusion enables shelf-based picking for non-cuboidal inventory like bakery trays and floral arrangements.
- Robotics Process Automation:Orchestration software decouples hardware ownership from operational control, compressing technology refresh cycles.
Internet of Things leads current integration depth; Computer Vision shows the steepest expansion trajectory.
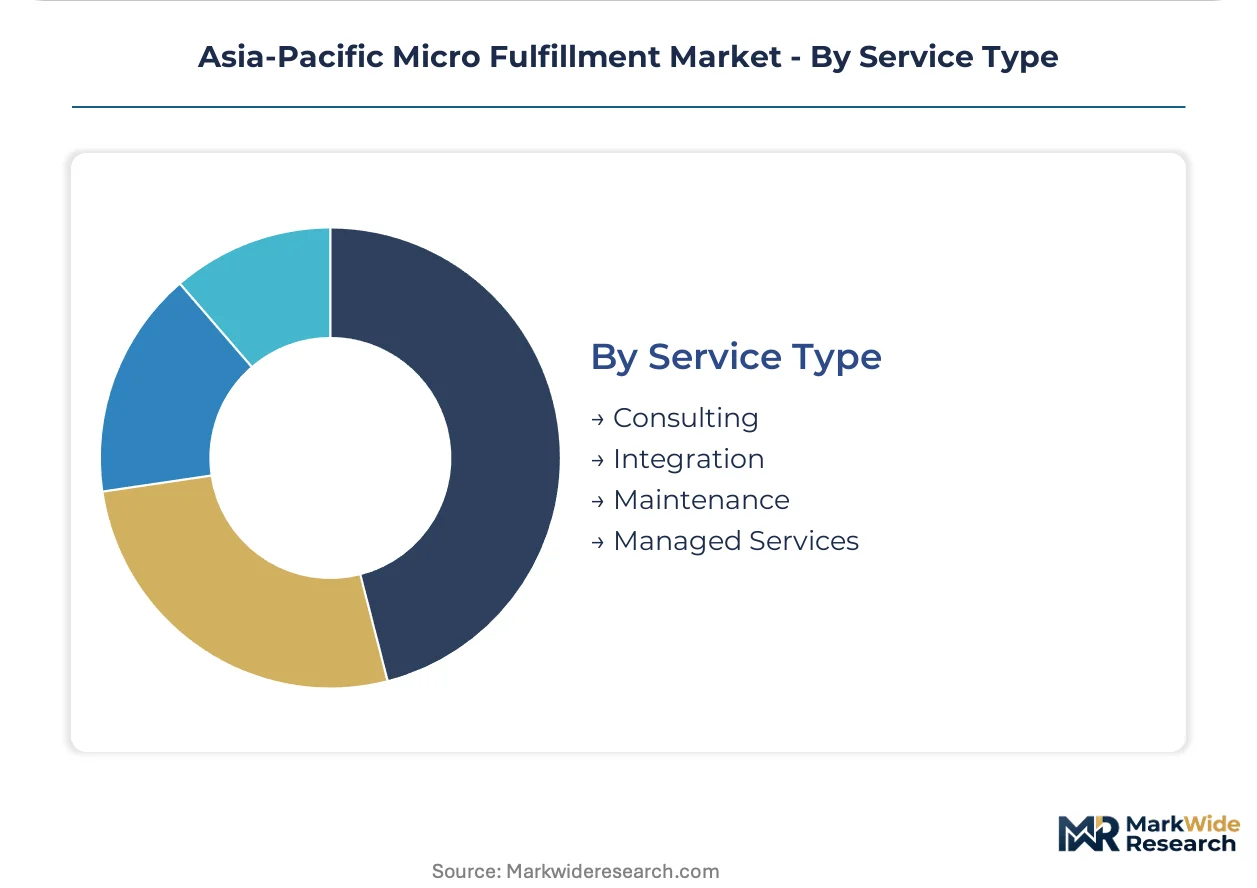
Service Type:
Revenue predictability separates recurring service models from one-time implementation contracts in vendor financial planning.
- Integration:Custom API middleware connects legacy ERP architectures to modern automation stacks. Japanese grocery incumbents face 4-6 month commissioning extensions from WMS compatibility requirements.
- Managed Services:Operators outsource fleet uptime guarantees to robotics vendors. This model spreads capital risk across multi-year contracts in markets with volatile real estate lease terms.
- Maintenance:Mechatronics technician scarcity in Indonesia and Philippines forces import of Japanese and South Korean calibration specialists at wage premiums.
- Consulting:Real estate developers in Shanghai and Beijing engage automation advisors for basement parking conversion feasibility.
Integration captures the largest project values today; Managed Services is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's basement conversion economics diverge sharply from Australia's backroom retrofit model, reflecting divergent real estate constraints and regulatory pathways across the Asia-Pacific micro fulfillment landscape.
China
Shanghai and Beijing developers repurpose underground parking structures into 15-20 meter high-bay cube-storage facilities to circumvent above-ground zoning restrictions. SAMR enforces GB robotics safety certifications requiring 8-14 month validation cycles that delay hardware deployment timelines. Yangtze River Delta grocery chains anchor the densest concentration of AMR-native architectures.
Japan
Tokyo and Osaka grocery incumbents face same-day delivery SLAs that human-pick operations cannot satisfy, driving capital toward sub-minute retrieval systems. METI coordinates smart logistics frameworks that shape 5G-native procurement specifications for peak-season inventory surges. Kanto region operators now lease pre-automated shell space rather than retrofit owned facilities.
South Korea
Seoul Capital Area e-commerce platforms compress vendor negotiation timelines to 90-day pilot-to-scale commitments, forcing robotics standardization. MSIT 5G spectrum allocation mandates network slicing provisions guaranteeing sub-10 millisecond latency for fleet coordination. Busan-Ulsan logistics clusters specify 5G-native AMR fleets that exclude WiFi-dependent legacy systems.
Singapore
IMDA regulates temperature-controlled smart lockers as telecommunications infrastructure, accelerating residential compound penetration. The city-state's 5G framework forces telecom operators to engineer dedicated fulfillment-node coverage maps. Dense urban land scarcity positions basement and backroom automation as the primary expansion vector.
Australia
Sydney and Melbourne grocery chains retrofit backrooms with sub-10,000 square foot automated configurations to preserve margins on same-day delivery commitments. TGA-equivalent safety standards govern warehouse automation deployments alongside state-level workplace regulations. Southeast Queensland operators unbundle automation procurement from warehouse construction, awarding separate contracts to robotics specialists.
Asia-Pacific Micro Fulfillment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automation hardware vendors capturing upfront capital while software orchestration providers secure recurring revenue streams. The vendor base concentrates around three strategic archetypes: AMR-native fleet operators, dense cube-storage architects, and modular robotic system integrators. Competitive positioning sharpens through technology licensing arrangements and multi-year managed service contracts that spread capital risk across volatile real estate lease terms.
Among China-based robotics developers, Geek+ and HAI Robotics occupy distinct positioning vectors within the AMR-native tier. Exotec SAS represents the modular system archetype competing across constrained Asian urban footprints. These three entities exemplify how geographic origin and structural specialization map to divergent procurement channels—Chinese grocery chains favoring domestic fleet operators, pan-Asian platforms sourcing modular configurations, and Australian incumbents evaluating both against retrofit compatibility requirements.
| Leading Market Players |
|---|
| HIK Robotics |
| Exotec SAS |
| Geek+ |
| Takeoff Technologies |
| Dematic |
| HAI Robotics |
| AutoStore |
| Fabric |
| GreyOrange |
| Others |
Pricing and Supply Chain Analysis
Pan-Asian e-commerce platforms' 90-day pilot-to-scale procurement mandates are compressing vendor negotiation cycles and forcing robotics manufacturers to absorb upfront engineering costs, reshaping how hardware suppliers price modular AMR architectures against recurring SaaS orchestration tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for AMR-native fleet deployments as Geek+ and HAI Robotics expand manufacturing scale. Three-tier pricing structure across premium certification-grade, standard GB-compliant, and economy non-certified tiers separates Japanese grocery incumbents seeking METI-backed reliability guarantees from Australian chains prioritizing rapid retrofit compatibility. Pricing pressure stems from rare earth magnet cost volatility in Inner Mongolia processing clusters, squeezing servo motor margins. E-commerce platforms exhibit lowest price sensitivity due to platform economics scale, while Vietnamese wet market digitization projects face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Shanghai, Seoul, and Singapore anchor hub-and-spoke fulfillment networks that feed last-mile micro nodes. Component sourcing draws from Japanese precision servo manufacturers, South Korean battery cell producers, and Chinese steel fabrication clusters. Rare earth magnet supply concentration in Inner Mongolia creates single-source vulnerability for AMR motor assemblies. Distribution runs through third-party logistics operators who lease pre-automated shell space rather than owning retrofitted facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific micro fulfillment operates as a geographic-arbitrage play where Australian backroom retrofit economics at TGA-equivalent safety tiers diverge sharply from China's basement conversion models under SAMR's extended certification timelines, creating divergent capital deployment windows.
For Market Incumbents: Cement fleet uptime guarantees through multi-year managed service contracts that spread capital risk across volatile urban real estate lease terms. Lock in 5G-native AMR specifications before Singapore's IMDA network slicing mandates obsolete WiFi-dependent legacy systems. Defend against modular robotics specialists like Exotec SAS by deepening software-defined orchestration layers that increase switching costs. For New Entrants and Emerging Players: Capture India's secondary city expansion as TRAI-mandated rural fiber rollout creates edge-compute nodes previously excluded from same-day networks. Target Vietnam and Indonesia wet market digitization with 2,000-4,000 square foot temperature-controlled formats where mechatronics technician scarcity has slowed incumbent deployment. Lead with AI vision convergence for non-cuboidal inventory picking as a differentiated entry wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with software orchestration providers decoupling hardware ownership from operational control, compressing technology refresh cycles and expanding recurring revenue multiples. Inventory Management SaaS vendors with API-native WMS integration capabilities offer superior long-term viability against pure hardware manufacturers facing GB certification timeline delays. Monitor 5G spectrum allocation progress across South Korea's MSIT and Singapore's IMDA as inflection indicators for IoT-enabled warehouse deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| 5G-Native AMR Fleet Deployment | IMDA network slicing provisions guarantee sub-10 millisecond latency for robotic coordination in Singapore nodes. |
| Basement Real Estate Conversion | Shanghai developers repurpose underground parking into 15-20 meter high-bay cube-storage to circumvent zoning restrictions. |
| Software-Defined Orchestration Licensing | API middleware layers decouple hardware subsystems from warehouse management logic, expanding vendor switching options. |
| Managed Services Contract Structuring | Multi-year uptime guarantees spread capital risk across volatile lease terms in Australian backroom retrofits. |
| AI Vision Sensor Fusion Development | Multi-modal systems enable shelf-based picking for bakery trays and floral arrangements in Japanese grocery chains. |
Research Methodology
Multiple input streams — robotics vendor engineering leads, grocery chain operations executives, third-party logistics procurement managers, and real estate development advisors — were reconciled against secondary validation from SAMR GB certification filings, IMDA 5G spectrum allocation records, and METI smart logistics framework documents. Bottom-up deployment tallies across Shanghai, Tokyo, Seoul, Singapore, and Sydney were triangulated with top-down capital expenditure estimates from e-commerce platform disclosures.
Data-stream reconciliation anchored analytical framework development across the projection horizon, modeling dimensions spanning automation hardware type, software deployment model, end-user segment concentration, and national regulatory cluster. CAGRs were derived from segment-level growth trajectory analysis incorporating 5G rollout timelines, perishable throughput SLA enforcement patterns, and urban land scarcity compression rates.
Steel and servo motor cost volatility, GB certification timeline extensions, and mechatronics technician availability gaps are the dominant revision risks to deployment forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Warehouse Barcode System Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Home Automation System Market
Automation
Micro Fulfillment Market
Automation
Dropshipping Automation Software Market
Automation
CNC Controller Market
Automation
Window Automation Market
Automation
Marketing Automation Solutions Market
Automation
Laboratory Automation Market
Automation
Self Bag Drop Machine Market
Automation
Global Zig-Bee Automation Market
Automation
Distribution Automation Solutions Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Escalator Control Systems Market
Automation
Global Warehouse Execution System Market
Automation
Europe Data Center Automation Market