
 Global Remote Infrastructure Management Market | 2026-2036
Global Remote Infrastructure Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Remote Infrastructure Management Market Foresight
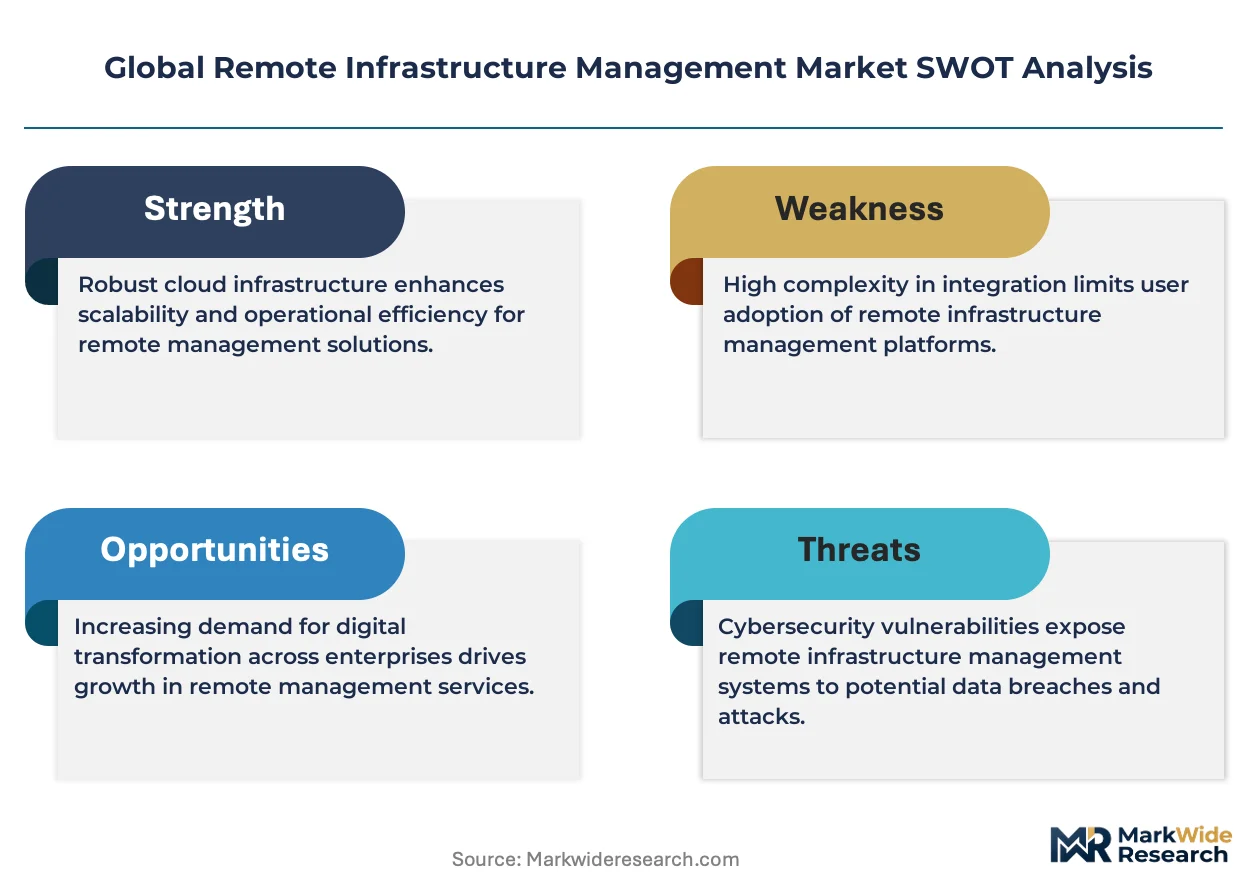
The capability gap between hyperscale platform operators and regional service providers is bifurcating competitive dynamics in remote infrastructure management. IBM Corporation leverages deep vertical integration across hybrid cloud stacks to sustain premium positioning in enterprise data center contracts. HCL Technologies Limited anchors its competitive posture through captive delivery centers in India that control labor costs and service continuity. Tata Consultancy Services Limited dominates long-term managed services engagements with government and telecommunications clients across multiple continents.
Remote infrastructure management encompasses the remote monitoring, administration, and optimization of IT infrastructure components including servers, networks, storage systems, and cloud resources through centralized command platforms operating over secure network protocols. Cloud-based service models are capturing accelerated enterprise migration budgets as organizations retire owned data center assets. Within deployment types, security management commands disproportionate margin pools due to escalating breach remediation costs and mandatory reporting obligations. Artificial intelligence integration across monitoring platforms is displacing rule-based alerting systems and compressing mean-time-to-resolution metrics for network and application incidents.
FDA oversight of diagnostic and clinical IT infrastructure in the United States, GDPR data residency requirements enforced by European regulators, and India's TRAI telecom security directives collectively shape cross-border service delivery architectures and data handling protocols. The EU AI Act imposes conformity assessments on automated decision systems embedded in infrastructure management tools, creating compliance cost tiers between certified and non-certified vendors. Stakeholders must monitor evolving algorithmic accountability standards as procurement criteria for public sector and regulated industry contracts.
Market Dynamics
The EU AI Act's conformity assessment mandate is fragmenting vendor eligibility for public sector contracts, forcing infrastructure management providers to certify automated decision systems or exit regulated procurement pools entirely.
Growth Catalysts
- GDPR data residency mandates:European enterprises are compelled to maintain localized infrastructure monitoring capabilities, creating dedicated demand for EU-based command platforms and cross-border service architectures.
- Financial services:Banks and insurance carriers are expanding remote monitoring adoption to satisfy operational resilience directives from national regulators while reducing owned data center footprints.
- Artificial intelligence integration:Machine learning-powered anomaly detection is compressing mean-time-to-resolution metrics and displacing rule-based alerting systems across enterprise network operations.
Market Restraints
- Specialized talent scarcity:Shortages of certified cloud security architects and AI-ops engineers in India and Eastern Europe are inflating wage premiums and extending service delivery timelines.
- EU AI Act compliance costs:Conformity assessments for automated infrastructure tools impose fixed cost burdens that disproportionately burden mid-tier service providers relative to hyperscale competitors.
- Legacy system entrenchment:Decades-old mainframe and on-premise server installations in government and telecommunications sectors resist cloud-native monitoring integration without costly middleware layers.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting data center equipment producers, enabling captive infrastructure management ecosystems for domestic and export markets.
- Edge computing convergence:Distributed IoT sensor networks and 5G base stations require localized monitoring nodes, opening service contracts beyond traditional centralized data center management.
- Outcome-based pricing models:Enterprise buyers are accepting uptime-guarantee contracts and penalty-clause structures that align vendor compensation with measurable infrastructure performance.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises operating across AWS, Azure, and Google Cloud environments demand unified visibility tools that few providers have engineered at scale.
- Certification timeline compression:EU AI Act conformity assessments require 12-18 month validation cycles that lag behind product development velocities and contract award deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Remote Infrastructure Management Market |
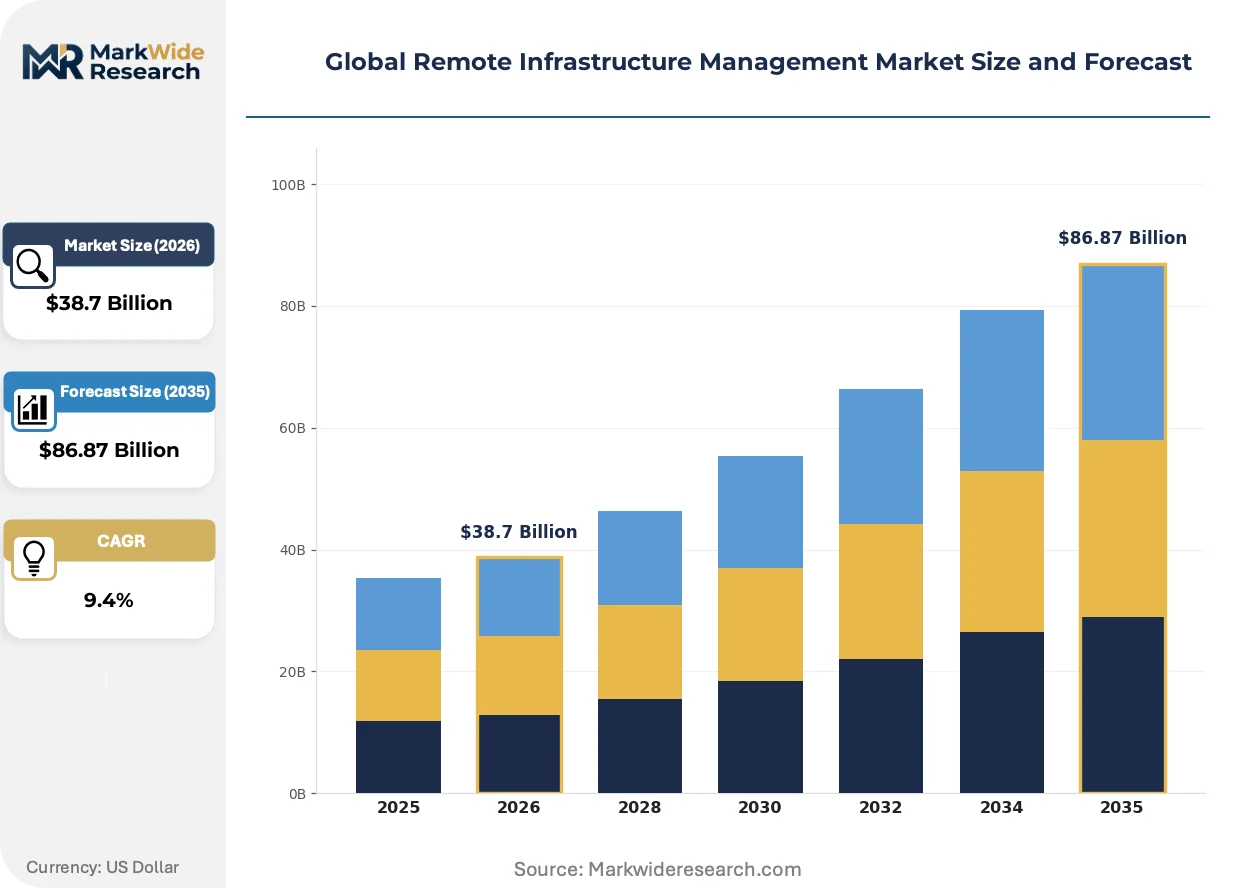
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Model: On-Premises, Cloud-Based, Hybrid, Managed Services, Self-Service Platforms Deployment Type: Data Center Management, Network Management, Application Monitoring, Security Management, Database Management End User Industry: BFSI, Telecommunications, Government Agencies, IT & Software Companies, Educational Institutions Technology Integration: Artificial Intelligence, Automation, Internet of Things, Machine Learning, Big Data Analytics |
| Companies Covered | IBM Corporation, HCL Technologies Limited, Tata Consultancy Services Limited, Capgemini, Fujitsu Limited, Cognizant Technology Solutions, Accenture Plc., Nityo Infotech, Sensiple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Remote Infrastructure Management Market Shifts & Advancements
Autonomous infrastructure remediation and predictive capacity planning are converging to redefine service level agreements, compressing the acceptable response window from hours to seconds for critical system failures.
Agentic artificial intelligence is bifurcating competitive positioning between vendors offering self-healing infrastructure platforms and those limited to passive monitoring dashboards. Large financial institutions in Germany and the United States are piloting fully autonomous patch management and resource scaling systems. This capability divide is separating certified providers capable of zero-touch operations from commodity monitoring services competing solely on price.
The EU AI Act imposes mandatory conformity assessments on automated decision systems embedded in infrastructure management platforms, creating compliance cost tiers between certified and non-certified vendors. European public sector procurement offices are embedding algorithmic accountability standards into tender requirements. Healthcare and telecommunications operators in France and Germany are prioritizing certified vendors despite 15-25% price premiums.
Enterprise buyers are unbundling after-sales support from initial infrastructure deployment contracts, creating standalone managed service agreements with specialized providers. Traditional hardware vendors are losing recurring revenue streams to independent software vendors and pure-play remote management specialists. This disintermediation is most advanced in the United States, where Fortune 500 technology procurement teams maintain separate vendor panels for equipment supply and operational support.
Global Remote Infrastructure Management Market Segmentation
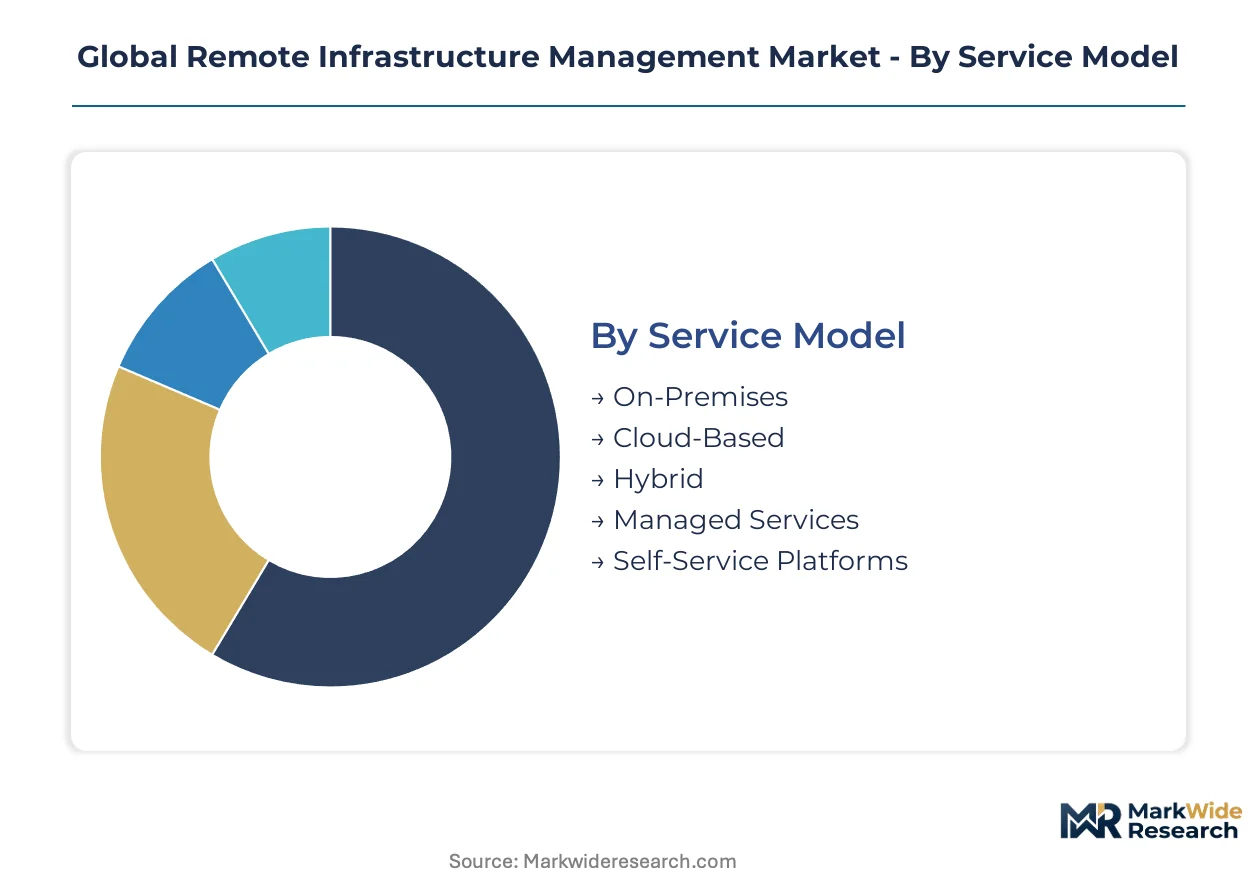
Segmentation in remote infrastructure management reveals how regulatory pressure, technology maturity, and procurement models fragment service delivery architectures across enterprise buyers. Each dimension exposes distinct margin pools and compliance burdens that reshape vendor positioning.
Service Model:
GDPR data residency mandates and FDA diagnostic IT oversight create divergent certification requirements across deployment architectures, forcing vendors to maintain parallel delivery infrastructures.
- Cloud-Based:Multi-tenant platforms with automated provisioning dominate enterprise migration budgets as organizations retire owned data center assets. Financial services firms in Germany and the United States are prioritizing these models to satisfy operational resilience directives while reducing capital intensity.
- Managed Services:Long-term engagements with dedicated personnel and customized SLAs command premium positioning through outcome-based pricing structures. Government agencies across India and telecommunications operators in France favor this model for critical infrastructure continuity.
- On-Premises:Legacy installations in defense and classified government sectors require air-gapped monitoring with localized command centers.
- Hybrid:Split architectures balancing sensitive workloads on-premise with burst capacity in public cloud environments.
- Self-Service Platforms:API-driven dashboards enabling enterprise IT teams to configure monitoring without vendor intervention.
Managed Services handles the majority of throughput; Cloud-Based is expanding most quickly on share.
Deployment Type:
Margin concentration follows breach remediation exposure and mandatory reporting obligations, with security-adjacent deployments capturing disproportionate returns.
- Security Management:Threat detection, vulnerability scanning, and compliance auditing platforms face escalating demand from EU AI Act conformity requirements. Healthcare operators in France and Germany are accepting certified vendor premiums despite higher costs.
- Network Management:Real-time traffic analysis and SD-WAN orchestration tools compress mean-time-to-resolution metrics across distributed enterprise footprints. India's TRAI telecom security directives are accelerating adoption among domestic carriers.
- Data Center Management:Server, storage, and cooling optimization across hyperconverged and traditional architectures.
- Application Monitoring:End-user experience tracking and performance bottleneck identification for cloud-native and legacy software.
- Database Management:Automated backup, replication, and query optimization across relational and NoSQL systems.
Security Management commands the widest margin spread; Network Management is climbing the fastest on new contract volume.
End User Industry:
Procurement sophistication and regulatory scrutiny determine contract structures, with regulated industries demanding certified automated decision systems.
- BFSI:Banks and insurance carriers require continuous uptime guarantees and audit trails for operational resilience compliance. German BaFin and US SEC oversight are embedding algorithmic accountability into vendor selection criteria.
- Government Agencies:Federal, state, and municipal entities mandate data sovereignty and citizen service continuity. India's state-level e-governance projects and US federal cloud-first policies are diverging on certification standards.
- Telecommunications:5G infrastructure and subscriber-facing service platforms demand sub-second failure response.
- IT & Software Companies:Technology vendors internalizing monitoring tools for productized service offerings.
- Educational Institutions:Campus networks and research computing clusters with seasonal demand fluctuations.
BFSI carries the highest contract value concentration; Government Agencies are gaining share fastest on digitization mandates.
Technology Integration:
Capability gaps between AI-enabled platforms and rule-based systems are bifurcating competitive tiers across procurement pools.
- Artificial Intelligence:Agentic systems capable of autonomous remediation and predictive capacity planning are separating certified providers from commodity monitoring services. Large financial institutions in Germany and the United States are piloting zero-touch operations.
- Machine Learning:Pattern recognition for anomaly detection and root-cause analysis displaces static threshold alerting in enterprise network operations.
- Automation:Scripted workflows for patch management, resource scaling, and incident ticketing without human intervention.
- Internet of Things:Sensor data ingestion and edge node monitoring for distributed industrial and smart city deployments.
- Big Data Analytics:Historical telemetry processing for capacity forecasting and cost optimization recommendations.
Artificial Intelligence absorbs the largest R&D allocation; Machine Learning is scaling fastest on implementation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands substantial premiums over Indian service delivery economics, creating a structural asymmetry that shapes vendor profitability across geographies. German buyers absorb certification surcharges under EU AI Act mandates while Indian procurement emphasizes cost efficiency. Demand concentrates in three distinct regulatory environments with divergent compliance burdens.
United States
Financial services firms and federal agencies drive contract volume through cloud-first modernization mandates. FDA oversight of diagnostic IT infrastructure and SEC operational resilience directives impose audit-trail requirements on automated monitoring platforms. The Greater Boston corridor hosts specialized cybersecurity clusters serving healthcare and defense sectors with air-gapped command centers.
Germany
BaFin banking supervision and EU AI Act conformity assessments elevate procurement standards for automated infrastructure tools. Industrial conglomerates in Baden-Württemberg demand predictive maintenance integration with legacy manufacturing systems. Munich-based technology parks concentrate AI-ops engineering talent for autonomous remediation platforms.
India
TRAI telecom security directives and state-level e-governance digitization create dual demand streams for domestic and export service delivery. PLI scheme incentives attract data center equipment manufacturing to Gujarat and Tamil Nadu captive zones. Bangalore and Hyderabad anchor delivery center networks controlling labor costs for global managed services contracts.
United Kingdom
GDPR-aligned data residency requirements and Financial Conduct Authority operational resilience rules shape vendor selection for banking infrastructure. London's financial district concentrates demand for sub-second failure response systems. Manchester and Edinburgh emerging technology clusters develop specialized cloud security architect pools.
France
ANSM healthcare IT oversight and CNIL data protection enforcement create certification thresholds for public sector procurement. Paris-Saclay research cluster pilots autonomous infrastructure remediation for telecommunications operators. Lyon and Grenoble industrial zones integrate edge computing monitoring with legacy manufacturing control systems.
Global Remote Infrastructure Management Market Competitive Landscape
Concentration sits with diversified technology conglomerates and specialized managed services providers operating at scale. The vendor base stratifies across three tiers: hyperscale platform operators with captive cloud stacks, India-based delivery specialists with labor-cost advantages, and regional consultancies with localized compliance expertise. Dominant competitive moves include EU AI Act certification investments and outcome-based pricing model adoption that aligns vendor compensation with infrastructure uptime guarantees.
Among diversified technology conglomerates, IBM Corporation and Fujitsu Limited occupy positions exemplifying vertical integration across hybrid cloud infrastructure stacks. Within the India-based delivery specialist tier, HCL Technologies Limited and Tata Consultancy Services Limited represent archetypes of captive center networks optimized for cost-controlled service continuity. These groupings illustrate how competitive positioning diverges between certified premium providers and scale-driven delivery specialists.
| Leading Market Players |
|---|
| IBM Corporation |
| HCL Technologies Limited |
| Tata Consultancy Services Limited |
| Capgemini |
| Fujitsu Limited |
| Cognizant Technology Solutions |
| Accenture Plc. |
| Nityo Infotech |
| Sensiple |
| Others |
Supply & Pricing Matrix
Cloud-native monitoring platforms displacing legacy on-premise toolsets are simultaneously compressing service delivery costs in India and elevating certification premiums in Germany, restructuring margin geography across vendor tiers.
Pricing Analysis
The customization-premium spread separates EU AI Act-certified autonomous remediation platforms from commodity rule-based monitoring dashboards. Subscription-tiered SaaS models dominate cloud-based deployments, while managed services contracts anchor on outcome-based uptime guarantees. Price differentiation centers on algorithmic certification grade and captive delivery center geography. Certification premiums of 15-25% persist in French and German healthcare procurement despite cost compression in Indian telecom security mandates. Financial services buyers in the United States absorb the widest premium spreads; state-level e-governance projects in India drive the sharpest price sensitivity.
Supply Chain Analysis
Just-in-time provisioning of cloud monitoring licenses contrasts with strategic stockpiling of AI-ops engineering talent in Bangalore and Hyderabad captive centers. Supply concentrates in India for labor-intensive managed services, Germany for BaFin-compliant platform engineering, and the United States for FDA-anchored healthcare infrastructure tools. Raw material dependencies include GPU clusters for machine learning inference, secure enclave hardware for data residency compliance, and proprietary automation frameworks. Single-source vulnerability sits with concentrated AI-ops certification pipelines in Eastern Europe. Distribution runs through direct enterprise sales teams for regulated contracts and channel partners for mid-market cloud migrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from agentic AI platforms capable of zero-touch autonomous operations, threatening traditional rule-based monitoring revenue pools.
For Market Incumbents: Fortify competitive moats through EU AI Act conformity investments that disqualify uncertified rivals from public sector procurement. Deepen backward integration into captive GPU infrastructure for machine learning training to control inference costs. The priority defensive lever is algorithmic certification, not price competition. For New Entrants and Emerging Players: Lead with edge computing monitoring nodes for 5G and industrial IoT deployments, the most penetrable white-space segment beyond saturated data center management. Target mid-tier financial institutions in the United States seeking autonomous remediation without hyperscale vendor lock-in. The go-to-market angle is outcome-based uptime contracts with penalty-clause structures that align vendor compensation with measurable infrastructure performance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certified autonomous platform specialists over commodity monitoring providers. Long-term viability over a multi-year window hinges on algorithmic accountability standards becoming embedded procurement criteria. Acquisition target archetypes include EU AI Act-certified AI-ops engineering teams and edge-native monitoring software stacks. The signal to watch is public sector tender requirements mandating conformity assessment documentation.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Mandatory assessments unlock public sector contracts in France, Germany, and healthcare procurement pools. |
| Captive Delivery Center Expansion | Bangalore and Hyderabad facilities control labor costs for global managed services contracts under TRAI directives. |
| Autonomous Remediation Platform Launch | Agentic AI capabilities separate certified providers from commodity monitoring services competing on price. |
| Edge Computing Monitoring Integration | 5G base stations and industrial IoT networks require localized nodes beyond centralized data center management. |
| Outcome-Based Pricing Model Adoption | Uptime-guarantee contracts with penalty clauses align vendor compensation with measurable infrastructure performance. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with infrastructure operations directors, cloud procurement officers, cybersecurity architects, and managed services delivery heads; and secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory certification databases, and TRAI security directive documentation. Bottom-up triangulation across service model deployments and top-down reconciliation against aggregate enterprise IT spending patterns anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning service model architectures, deployment types weighted by breach exposure, end-user industry regulatory intensity, and technology integration maturity tiers. CAGRs derived from elasticity-adjusted adoption curves and compliance-driven replacement cycles. Industry-specific forecast inputs included EU AI Act implementation timelines and PLI scheme capacity additions in Indian data center equipment manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of algorithmic accountability standards or accelerated cloud migration in financial services would require recalibration. Forecasts reflect assumptions about certification timeline compression and talent scarcity persistence in AI-ops engineering pools. Revision becomes warranted when EU AI Act conformity assessment backlogs exceed procurement cycle tolerances or when edge computing deployment velocities diverge from centralized infrastructure retirement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Employee Engagement Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
United States Managed Services Market