
 APAC Water Automation and Instrumentation Market | 2026-2036
APAC Water Automation and Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Water Automation and Instrumentation Market Outlook
China's GB standards for drinking water quality monitoring is expanding the addressable market for automation vendors serving municipal treatment plants. Siemens AG leverages its digital twin platforms to anchor long-term service contracts across Chinese provincial water bureaus. Yokogawa Electric Corporation dominates precision flow measurement for chemical dosing applications in Japanese desalination facilities. ABB Group competes on integrated SCADA-to-PLC architectures that reduce commissioning cycles for greenfield industrial water recycling projects.
Water automation and instrumentation encompasses sensor networks, actuated control devices, and supervisory software that measure, transmit, and regulate hydraulic parameters across treatment and distribution infrastructure. Flow meters employing ultrasonic or electromagnetic principles achieve accuracy thresholds of ±0.5% to support non-revenue water reduction programs in aging pipe networks. SCADA Systems within the Technology dimension command the largest installed base but face margin compression as cloud-native IoT Solutions capture greenfield deployments with lower lifecycle service costs. Pressure Transmitters lead the Product Type category by unit volume, while Control Valves generate disproportionate margin pools due to material requirements for corrosive effluent handling.
Japan's METI enforces equipment efficiency benchmarks that accelerate PLC replacements in industrial cooling circuits, while India's CEA mandates automated monitoring for interstate river basin allocations. Australia's TGA and state-level EPA frameworks impose calibration traceability requirements that favor established instrumentation suppliers with local certification infrastructure. Stakeholders must weigh the capital efficiency of retrofit installations against new build automation architectures as regulatory compliance windows tighten across divergent national schedules.
Market Dynamics
Digital twin architectures are compressing commissioning cycles for municipal treatment retrofits across Southeast Asia, forcing incumbent SCADA vendors to restructure service revenue models around predictive maintenance subscriptions rather than perpetual licenses.
Growth Catalysts
- China's dual carbon goals:Municipal water bureaus in Jiangsu and Zhejiang provinces must reduce distribution energy intensity by 15 percent, triggering mass flow meter replacements in pumping stations.
- Smart city mandates:India's Ministry of Housing and Urban Affairs requires automated metering infrastructure for all AMRUT cities, creating unit demand for pressure transmitters and remote terminal units.
- Desalination expansion:Australia's Western Corridor Recycled Water Scheme and Queensland's coastal plants require precision chemical dosing systems, pulling Japanese electromagnetic flow measurement technologies into procurement pipelines.
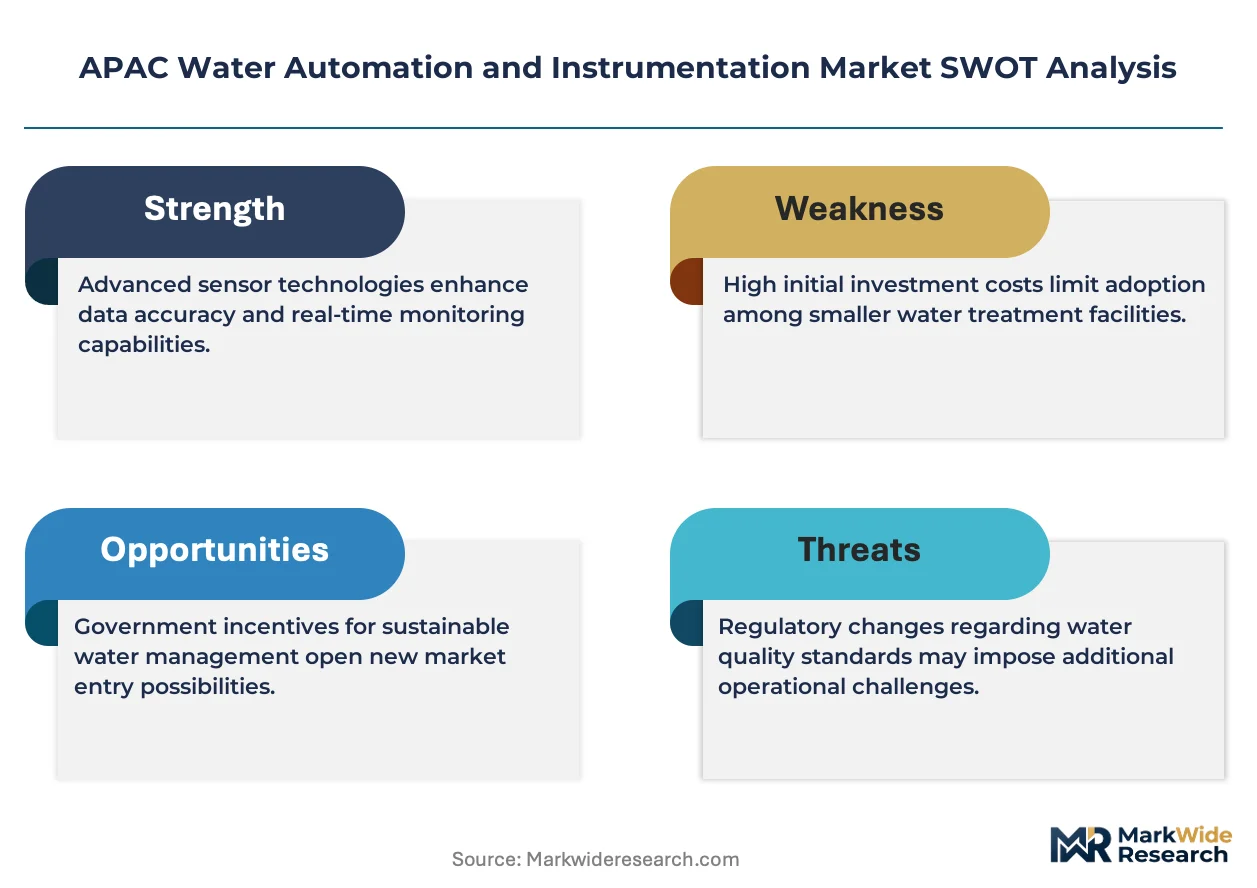
Market Restraints
- Semiconductor input volatility:PLC and RTU manufacturers face lead time uncertainty for industrial-grade microcontrollers sourced from concentrated East Asian foundry networks.
- Technical limitation of legacy protocols:Proprietary Modbus and Profibus architectures in 1990s-built plants block native cloud connectivity without expensive protocol gateway layers.
- Regulatory friction from divergent calibration standards:Australia's TGA traceability requirements and India's BIS certification timelines create duplicate testing burdens for instrumentation vendors serving both markets.
Strategic Opportunities
- Vietnam's Mekong Delta monitoring:The country's Ministry of Natural Resources and Environment is procuring basin-wide sensor networks for salinity intrusion early warning, an underpenetrated automation frontier.
- Technology convergence of edge AI and ultrasonic sensing:On-device leak detection algorithms reduce false positive rates in non-revenue water programs, opening premium pricing tiers for smart meter vendors.
- Japan's METI efficiency retrofit incentives:Industrial cooling circuit operators receive tax depreciation acceleration for PLC replacements, creating a replacement demand window distinct from greenfield cycles.
Industry Challenges
- Cybersecurity competency gaps:Municipal utilities in Indonesia and Philippines lack in-house OT security functions to harden SCADA networks against ransomware targeting water infrastructure.
- Integration complexity with mechanical assets:Actuated valve retrofits in India's 50-year-old distribution grids require custom mechanical adapters that extend project timelines and erode margin on fixed-price contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Water Automation and Instrumentation Market |
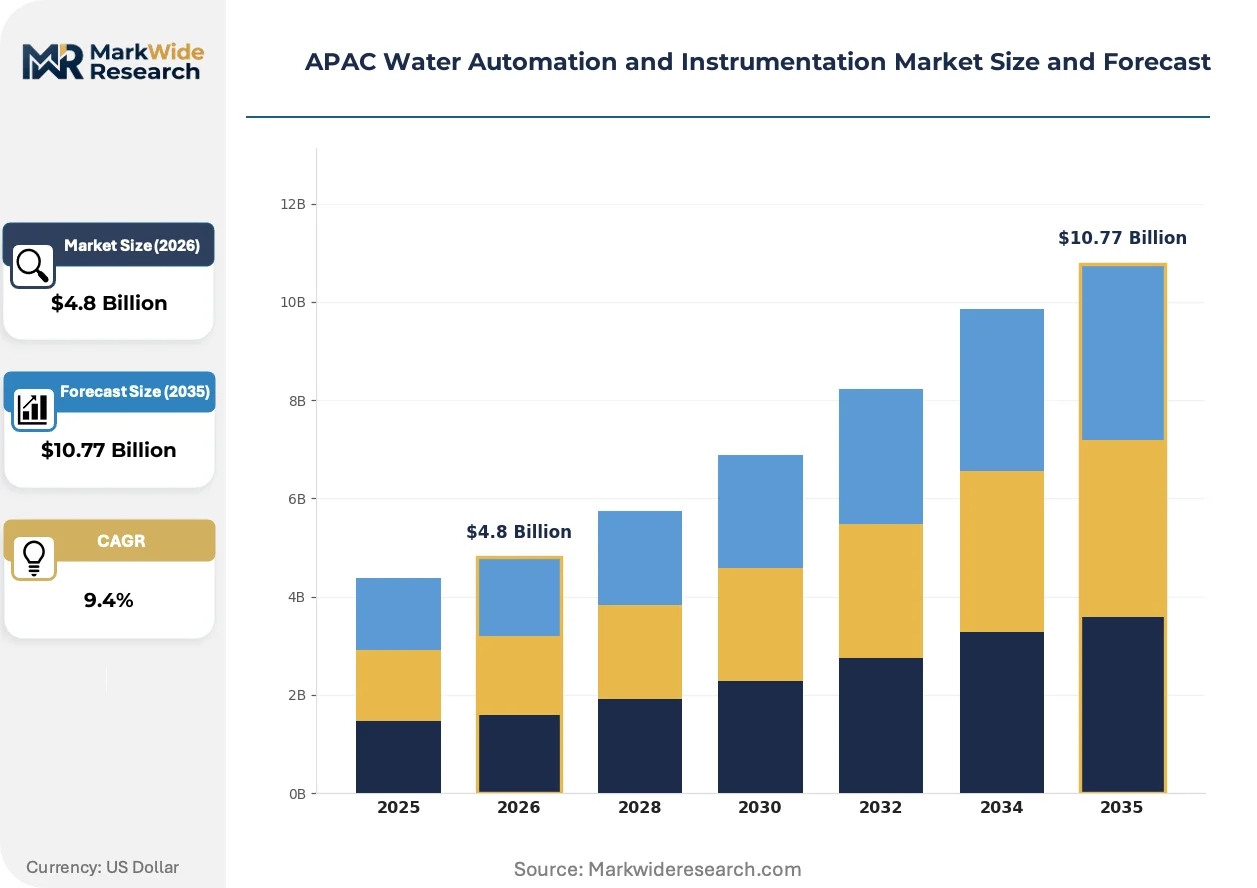
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Meters, Pressure Transmitters, Level Sensors, Control Valves End User: Municipal, Industrial, Agriculture, Wastewater Technology: IoT Solutions, SCADA Systems, PLCs, Remote Monitoring Installation: On-site, Remote, Retrofit, New Build |
| Companies Covered | ABB Group, Siemens AG, Schneider Electric SE, GE Corporation, Rockwell Automation Inc., Yokogawa Electric Corporation, Emerson Electric, Mitsubishi Electric Corporation, Endress+Hauser, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Water Automation and Instrumentation Market Strategic Shifts
Edge-native instrumentation is redrawing competitive boundaries between traditional automation hardware vendors and software-centric challengers, compressing the value capture window for proprietary protocols.
LoRaWAN-enabled pressure sensors are decentralizing network architecture for rural distribution monitoring. Australian irrigation districts in the Murray-Darling basin deploy battery-powered transmitters that eliminate trenching costs for telemetry cable. This topology is decentralizing procurement authority from central SCADA integrators to regional water user associations with direct sensor vendor relationships.
China's GB standards for drinking water quality monitoring now mandate real-time turbidity and residual chlorine reporting for plants serving populations above 500,000. Municipal operators must install automated sampling systems with data logging traceable to SAMR metrology requirements. Treatment plant engineering departments are responding by specifying instrumentation packages with embedded compliance reporting modules rather than standalone sensors.
Service unbundling is fragmenting buyer-supplier relationships in Japan's industrial water recycling sector. Chemical manufacturers now procure flow measurement hardware through distributor channels while contracting calibration and predictive maintenance directly with Yokogawa's service subsidiaries. This bifurcation is most visible in the Kanto region's petrochemical corridor, where procurement teams separate CAPEX and OPEX decisions across fiscal years.
APAC Water Automation and Instrumentation Market Segmentation
Water automation and instrumentation segments diverge sharply by integration depth. Standalone sensors serve discrete measurement points while embedded systems demand protocol compatibility across distributed architectures. Procurement patterns in APAC municipal utilities increasingly favor bundled technology stacks over component-level purchasing.
Product Type:
Integration depth varies dramatically — flow meters and pressure transmitters dominate as standalone retrofit units, while level sensors and control valves embed deeply into automated skids.
- Flow Meters:Ultrasonic and electromagnetic variants achieve ±0.5% accuracy thresholds for non-revenue water programs. Demand concentrates in China's Jiangsu and Zhejiang provincial water bureaus replacing mechanical meters under dual carbon distribution efficiency mandates.
- Pressure Transmitters:Piezoelectric and capacitive sensing elements transmit 4-20mA signals across aging pipe networks. India's AMRUT smart city programs generate unit volume for remote telemetry installations in 500+ municipal jurisdictions.
- Level Sensors:Radar and hydrostatic technologies monitor reservoir and tank volumes. Australian Murray-Darling irrigation districts specify battery-powered LoRaWAN variants to eliminate trenching costs.
- Control Valves:Actuated ball and butterfly configurations handle corrosive effluent streams. Japanese desalination facilities require Hastelloy-trimmed variants for chemical dosing loops.
Pressure transmitters lead volumes today; flow meters are gaining share fastest.
End User:
Cost tier stratification separates premium-specification industrial installations from price-sensitive agricultural deployments.
- Municipal:Treatment plants and distribution networks drive standardized procurement at scale. China's GB drinking water standards mandate real-time turbidity reporting for plants serving populations above 500,000.
- Industrial:Cooling circuits and process water recycling demand precision instrumentation. Japan's METI efficiency benchmarks accelerate PLC replacements in petrochemical corridors.
- Agriculture:Irrigation automation favors low-cost, battery-operated telemetry. Vietnam's Mekong Delta salinity monitoring programs represent an emerging demand frontier.
- Wastewater:Effluent compliance monitoring requires corrosion-resistant sensor packages. Australia's state-level EPA frameworks impose calibration traceability burdens favoring established suppliers.
Municipal dominates procurement value; wastewater is expanding most quickly.
Technology:
Application maturity separates legacy SCADA architectures from cloud-native deployments.
- IoT Solutions:Cloud-native platforms with API-first architectures reduce lifecycle service costs. Greenfield Southeast Asian utilities bypass on-premise infrastructure entirely.
- SCADA Systems:Proprietary HMI software commands the largest installed base but faces margin compression. Retrofit projects in 1990s-built plants require expensive protocol gateway layers.
- PLCs:Programmable controllers execute discrete logic for pumping station automation. Japan's tax depreciation incentives create replacement demand windows distinct from greenfield cycles.
- Remote Monitoring:Cellular and satellite telemetry extends supervision to unmanned rural assets. Indonesia's archipelago geography necessitates VSAT backup for critical infrastructure.
SCADA retains the largest footprint; IoT solutions are climbing the fastest.
Installation:
Customer type bifurcation separates owner-operated utilities from engineering-procurement-construction contractors.
- On-site:Local commissioning teams handle complex mechanical integration. India's 50-year-old distribution grids require custom valve adapters extending project timelines.
- Remote:Cloud-based configuration and diagnostics reduce travel requirements. Australian irrigation districts decentralize procurement authority to regional water user associations.
- Retrofit:Legacy protocol translation dominates brownfield economics. Proprietary Modbus and Profibus architectures block native cloud connectivity without gateway investments.
- New Build:Greenfield specifications favor integrated digital twin architectures. Siemens anchors long-term service contracts through upfront digital twin platform commitments.
Retrofit commands current spending; new build offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated in Shanghai, Tokyo, and Bangalore anchor automation deployment capacity across the region. These clusters supply the integration expertise required for smart water infrastructure rollouts.
China
Jiangsu and Zhejiang provincial water bureaus are replacing mechanical flow meters in pumping stations to meet dual carbon distribution efficiency targets. SAMR metrology requirements now mandate data logging traceability for plants serving populations above 500,000. Siemens anchors long-term service contracts through digital twin platform commitments in these provinces.
Japan
METI efficiency benchmarks are accelerating PLC replacements in industrial cooling circuits across petrochemical corridors. The Kanto region's chemical manufacturers now unbundle procurement, buying hardware through distributors while contracting calibration services directly with instrumentation specialists. Yokogawa occupies a central position in precision flow measurement for desalination facilities.
India
AMRUT smart city mandates require automated metering infrastructure across 500-plus municipal jurisdictions, generating unit demand for pressure transmitters and remote terminal units. CEA regulations mandate automated monitoring for interstate river basin allocations. Custom valve adapters for 50-year-old distribution grids in Maharashtra and Gujarat extend retrofit project timelines.
Australia
Murray-Darling irrigation districts specify battery-powered LoRaWAN level sensors to eliminate trenching costs for telemetry cable. TGA and state-level EPA frameworks impose calibration traceability requirements that favor established suppliers with local certification infrastructure. The Western Corridor Recycled Water Scheme pulls precision chemical dosing systems into procurement pipelines.
Vietnam
The Ministry of Natural Resources and Environment is procuring basin-wide sensor networks for Mekong Delta salinity intrusion early warning. This represents an underpenetrated automation frontier with limited incumbent vendor presence. Battery-operated pressure transmitters are decentralizing procurement authority to regional water user associations.
APAC Water Automation and Instrumentation Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive digital platforms. Incumbent automation vendors command the largest installed base but face margin compression as cloud-native challengers capture greenfield deployments. Three archetypes dominate: full-stack platform providers, precision measurement specialists, and regional system integrators. Strategic moves concentrate on predictive maintenance subscription restructuring and digital twin service anchoring.
Among diversified European-based conglomerates, ABB Group and Siemens AG exemplify the platform-provider archetype through integrated SCADA-to-PLC architectures and long-term service contract structures. Yokogawa Electric Corporation represents the precision-specialist tier, occupying a position in electromagnetic flow measurement for chemical dosing applications. These three entities anchor the competitive landscape across municipal and industrial water segments in the region.
| Leading Market Players |
|---|
| ABB Group |
| Siemens AG |
| Schneider Electric SE |
| GE Corporation |
| Rockwell Automation Inc. |
| Yokogawa Electric Corporation |
| Emerson Electric |
| Mitsubishi Electric Corporation |
| Endress+Hauser |
| Others |
Value Chain & Pricing Dynamics
Hastelloy and titanium alloy costs cascade through control valve pricing tiers, with corrosion-resistant trim specifications separating premium Japanese desalination procurement from standardized Southeast Asian municipal retrofits. Raw material volatility in specialty metals compresses margins on fixed-price EPC contracts while pushing buyers toward subscription-based predictive maintenance models that transfer lifecycle risk to vendors.
Pricing Analysis
Bundled hardware-service packages are displacing standalone component transactions across APAC municipal procurement. Premium-mid-economy pricing differentiation rests on calibration traceability certification and digital twin integration depth, with Australia's TGA-compliant instrumentation commanding substantial premiums over India's BIS-tier equivalents. Cost compression in SCADA licensing is intensifying because cloud-native IoT platforms undercut perpetual license models with lower total cost of ownership. Municipal utilities in Indonesia and Philippines exhibit highest price sensitivity due to constrained capital budgets, while Japanese petrochemical operators prioritize precision specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for industrial-grade microcontroller fabrication serving PLC and RTU production. Semiconductor wafer supply draws from concentrated East Asian foundry networks, with rare earth magnet dependencies for electromagnetic flow meters anchored in Chinese processing facilities. Tariff exposure on cross-border component shipments between ASEAN members creates procurement timing risks for brownfield retrofit projects. Distribution runs through authorized distributor channels in Japan and direct vendor relationships with provincial water bureaus in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on predictive maintenance subscription penetration and premium-tier specification capture in Japanese industrial cooling retrofits. Cloud-native platform displacement of legacy SCADA licensing creates recurring revenue pools that improve lifetime customer value metrics.
For Market Incumbents: Hedge against cloud-native entrant disruption by anchoring long-term service contracts through upfront digital twin platform commitments in Chinese provincial water bureaus. Accelerate certification investment for Australia's TGA traceability requirements to defend premium positioning against emerging regional competitors. Prioritize backward integration into edge AI software stacks for ultrasonic leak detection algorithms that command pricing premiums in non-revenue water programs. For New Entrants and Emerging Players: Enter via Vietnam's Mekong Delta salinity monitoring frontier, where limited incumbent presence and decentralized procurement authority to regional water user associations lower competitive barriers. Target battery-powered LoRaWAN sensor deployments in Australian Murray-Darling irrigation districts as the most penetrable greenfield segment. Pursue direct sensor vendor relationships with regional water associations rather than centralized SCADA integrator channels. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-native IoT platforms lack field service infrastructure to support predictive maintenance subscriptions at scale. Long-term viability favors platform providers with captive digital twin architectures and established calibration certification networks across multiple APAC regulatory jurisdictions. Acquisition target archetype: precision measurement specialists with electromagnetic flow measurement IP and existing Yokogawa-style service subsidiary structures. The signal to watch is unbundling acceleration in Japan's Kanto petrochemical corridor, where procurement teams increasingly separate CAPEX and OPEX decisions across fiscal years.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Restructuring | Transforms perpetual SCADA licensing into recurring revenue pools with higher lifetime value in Chinese municipal accounts. |
| Digital Twin Platform Integration | Anchors long-term service contracts through upfront infrastructure commitments in Jiangsu and Zhejiang provincial water bureaus. |
| Edge AI Ultrasonic Sensing Development | Reduces false positive rates in non-revenue water programs, opening premium pricing tiers for smart meter vendors. |
| Calibration Certification Infrastructure Expansion | Builds defensible positioning against emerging competitors under Australia's TGA and India's BIS regulatory frameworks. |
| LoRaWAN Rural Telemetry Deployment | Eliminates trenching costs for Murray-Darling basin irrigation districts, decentralizing procurement authority to regional associations. |
Study Parameters
Direct dialogue with municipal water utility engineers, industrial plant maintenance directors, EPC contractors, and instrumentation distributor technical specialists grounded the qualitative foundation. Secondary validation drew from SAMR metrology filings, METI efficiency benchmark disclosures, AMRUT program procurement documents, and customs trade data on flow meter and pressure transmitter imports. Bottom-up unit demand modeling triangulated against top-down market sizing across technology and end-user segments.
Market value and volume trajectories across the analysis window reflect integrated projections of retrofit replacement cycles, greenfield smart city deployment schedules, and efficiency mandate compliance timelines. Segmentation dimensions modeled include product type integration depth, end-user cost tier stratification, technology application maturity, and installation customer type bifurcation. CAGRs were derived from regression analysis of historical procurement patterns against regulatory compliance window schedules and capital expenditure planning cycles in key municipal jurisdictions.
The model holds under stable regulatory enforcement timelines and semiconductor supply normalization; deviation in tariff escalation or cybersecurity mandate acceleration would shift deployment trajectories. Forecasts embed assumptions regarding cloud-native platform adoption rates and unbundling trends in Japanese industrial procurement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Automatic Message Handling System Market
Automation
Playout Automation Market
Automation
Industrial Vending Machines Market
Automation
Italy Process Orchestration Market
Automation
Global Form Automation Software Market
Automation
US Workload Scheduling and Automation Market
Automation
Dropshipping Automation Software Market
Automation
Retail Automation Market
Automation
Indonesia Automation and Control System Market
Automation
CNC Controller Market
Automation
North America Marketing Automation Software Market
Automation
Automation Light Grids Market
Automation
AR Automation Market
Automation
Universal Process Control Market
Automation
Lab Automation Market
Automation
Global Warehouse Barcode System Market