
 Italy Process Orchestration Market | 2026-2036
Italy Process Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Process Orchestration Market Insights
Capability gaps in AI-infused workflow engines is bifurcating the competitive landscape between capital-heavy platform builders and lean integration specialists. IBM Corporation leverages its hybrid cloud architecture to anchor premium deployments across Italian financial institutions. SAP SE competes through deep ERP-native orchestration that sustains manufacturing client loyalty in the Emilia-Romagna region. UiPath specializes in robotic process automation bridges that extend legacy system lifecycles without full infrastructure replacement.
Process orchestration coordinates disparate software applications, data streams, and human tasks through centralized workflow engines using API mediation, event-driven triggers, and conditional routing logic to enforce business rules across enterprise operations. Workflow Automation and Integration Platform segments dominate current spending as Italian enterprises prioritize connecting siloed ERP and CRM systems over greenfield platform builds. Cloud-Based deployment is expanding fastest among mid-market manufacturers seeking to avoid on-premises capital expenditure while maintaining hybrid connectivity to legacy shop-floor systems.
Italy's AgID (Agenzia per l'Italia Digitale) mandates interoperability standards for public-sector digital services, while EU GDPR and the EU AI Act impose algorithmic transparency requirements on automated decision workflows. These frameworks force vendors to embed audit trails and explainability modules directly into orchestration layers rather than treating compliance as a peripheral add-on. Stakeholders must weigh the trade-off between platform consolidation and best-of-breed flexibility as regulatory complexity compounds technical integration debt.
Market Dynamics
Italian banking consortiums are consolidating fragmented automation estates into unified orchestration fabrics to satisfy EU AI Act auditability mandates and AgID interoperability standards.
Growth Catalysts
- EU AI Act Compliance Deadlines:Automated decision workflows in Lombardy financial services must embed explainability modules by enforcement dates, forcing platform refresh cycles.
- Emilia-Romagna Manufacturing Cloud Migration:Mid-market automotive suppliers adopt API-native orchestration to bridge legacy MES systems with cloud ERP without full infrastructure replacement.
- Event-Driven Architecture Maturation:Real-time inventory synchronization across Milan-Turin logistics corridors reduces manual reconciliation overhead in multi-site production networks.
Market Restraints
- Specialized Integration Talent Scarcity:Italy produces insufficient engineers fluent in both legacy COBOL estates and Kubernetes-native orchestration, inflating implementation timelines.
- Hybrid Cloud Connectivity Costs:Maintaining secure tunnels between on-premises shop-floor systems and public cloud orchestration layers consumes disproportionate IT budget share.
- GDPR Data Residency Constraints:Cross-border workflow automation involving non-EU cloud regions triggers complex legal review processes that delay multi-national deployments.
Strategic Opportunities
- Southern Italy Public-Sector Digitization:AgID mandates create procurement pipelines for orchestration vendors in Campania and Sicily where legacy paper workflows dominate.
- AI-Infused Predictive Maintenance:Convergence of machine learning inference engines with workflow orchestration enables autonomous shop-floor intervention in Veneto textile manufacturing.
- Subscription-Based Orchestration Services:Channel partners in Turin industrial districts pilot outcome-priced models linking platform fees to measured process efficiency gains.
Industry Challenges
- Certified Workflow Auditor Shortage:EU AI Act requires documented human oversight of automated decisions; Italy lacks sufficient professionals holding both technical and regulatory certifications.
- Fragmented ERP Integration Debt:Decades of custom SAP and Oracle extensions in family-owned manufacturers resist standard API abstraction, prolonging orchestration deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Process Orchestration Market |
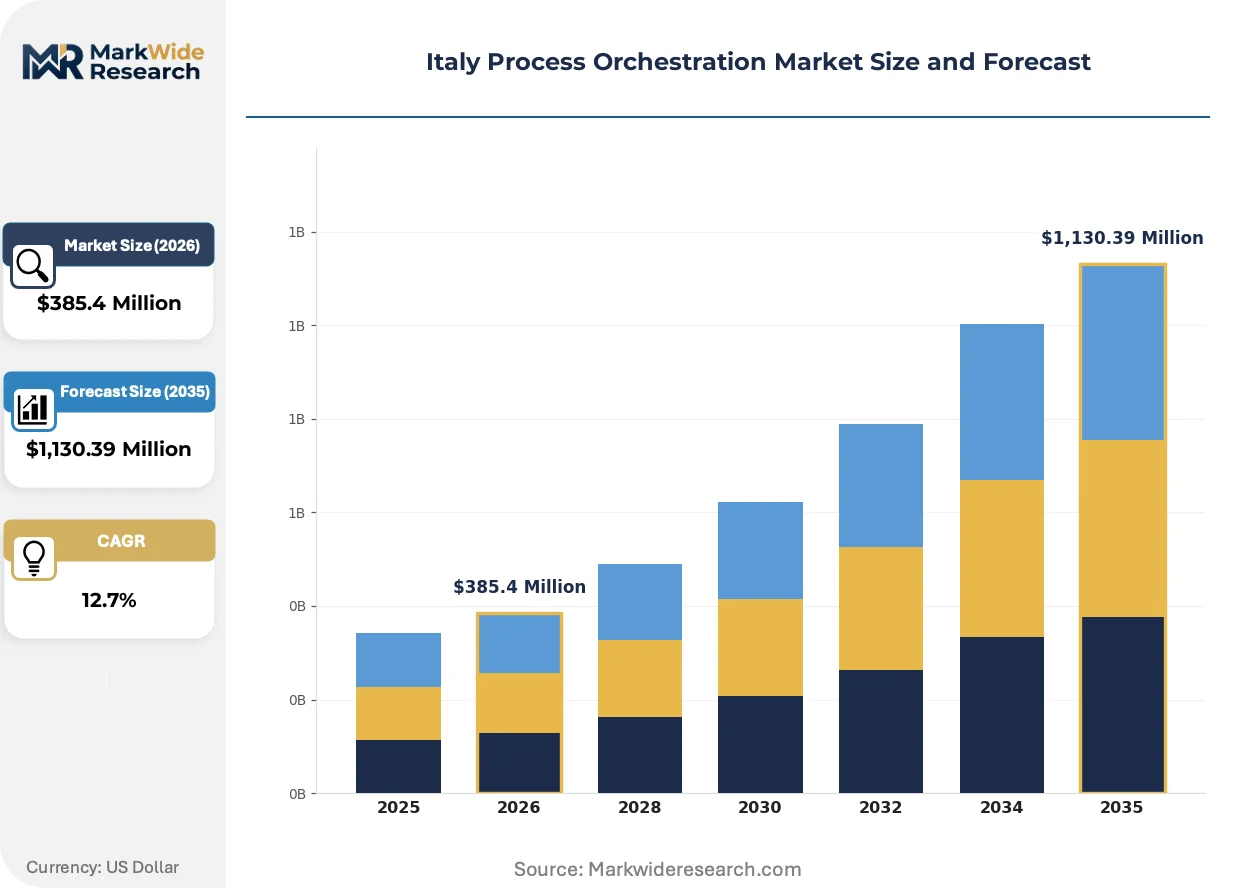
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,130.39 Million |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: API Management, Workflow Automation, Event-Driven, Integration Platform Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Manufacturing, Retail, Finance, Telecommunications Application: Customer Service, IT Operations, Supply Chain, Human Resources |
| Companies Covered | IBM Corporation, Microsoft Corporation, ServiceNow, Salesforce Inc., SAP SE, UiPath, Appian, Automation Anywhere, Accenture Public Limited Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Process Orchestration Market Trends and Innovations
Workflow engines are evolving from passive task routers into autonomous decision systems that embed compliance and observability by design rather than retrofit.
Low-code orchestration interfaces are supplanting traditional BPMN modeling tools in Italian mid-market enterprises. Procurement teams in Piedmont manufacturing clusters now demand visual workflow builders that enable business analysts to modify routing logic without Java expertise. This democratization compresses time-to-deployment from quarters to weeks while reducing dependency on scarce integration specialists.
Italy's AgID interoperability framework mandates standardized API specifications for all public-sector digital services. Vendors must now pre-certify orchestration connectors against national technical standards before qualifying for government tenders. This regulatory tailwind favors platform builders with dedicated compliance engineering teams over lean integration specialists lacking certification bandwidth.
Outcome-based platform pricing is displacing traditional per-seat licensing in Lombardy financial services. Procurement committees now negotiate contracts tying vendor payments to measurable KPI improvements in loan processing throughput or claims resolution speed. This shift transfers implementation risk to platform providers while accelerating buyer adoption of more sophisticated automation capabilities.
Italy Process Orchestration Market Segmentation
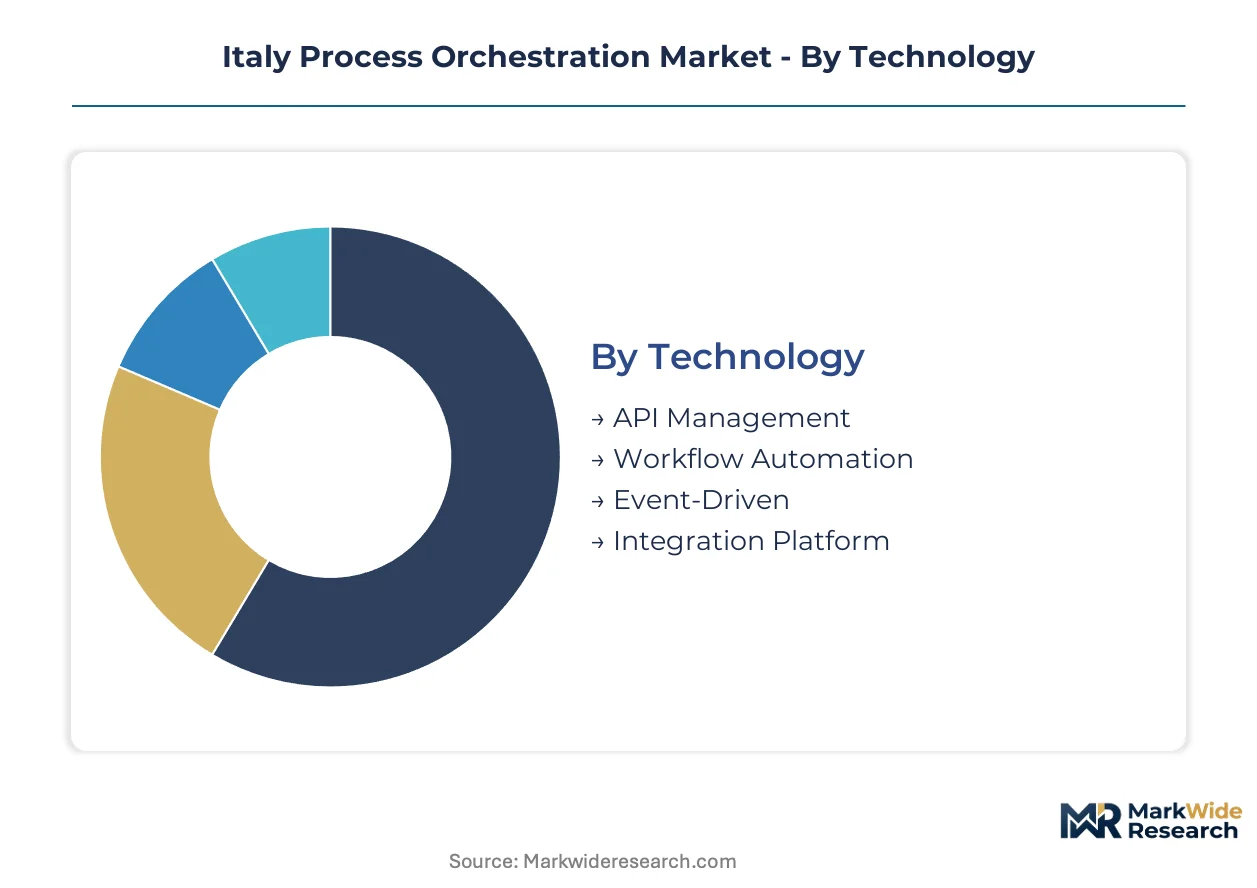
Italian enterprises deploy process orchestration across heterogeneous technology stacks, deployment models, and functional domains. Segmentation reveals where compliance mandates and legacy modernization pressures concentrate procurement budgets.
Technology:
Channel partners route API Management and Workflow Automation through systems integrators serving Lombardy financial institutions, while Event-Driven platforms flow via cloud-native specialists targeting Emilia-Romagna manufacturing clusters.
- API Management:Centralizes endpoint governance, rate limiting, and authentication protocols across distributed microservices. Lombardy banking groups prioritize this layer to satisfy AgID interoperability mandates for public-facing digital services.
- Workflow Automation:Engine coordinates sequential human tasks and system interactions through visual design interfaces. Piedmont automotive suppliers deploy these tools to bridge legacy MES systems with cloud ERP without full infrastructure replacement.
- Event-Driven:Architecture triggers process flows based on real-time state changes rather than polling intervals. Enables inventory synchronization across Milan-Turin logistics corridors.
- Integration Platform:Unified middleware abstracts connectivity across SaaS, on-premises, and edge systems. Mid-market manufacturers adopt subscription models to avoid capital expenditure.
Workflow Automation dominates installed base. Event-Driven is where expansion concentrates.
Deployment:
Cost tier stratification separates enterprise-grade Hybrid deployments from mid-market Cloud-Based adoption, with On-Premises retaining share in regulated sectors requiring data sovereignty.
- On-Premises:Infrastructure resides within client-controlled data centers. Italian defense contractors and critical infrastructure operators maintain this model to satisfy national security classifications.
- Cloud-Based:Fully managed orchestration services eliminate hardware procurement cycles. Veneto textile manufacturers adopt this tier to compress time-to-deployment from quarters to weeks.
- Hybrid:Combines on-premises workflow engines with cloud burst capacity for variable workloads. Lombardy financial institutions favor this architecture to maintain legacy core systems while modernizing customer channels.
- Multi-Cloud:Orchestration layers abstract across AWS, Azure, and Google Cloud to avoid vendor lock-in. Large manufacturing conglomerates deploy this model for geographic redundancy.
Hybrid architectures command premium pricing. Cloud-Based deployments are climbing the fastest among sub-500-employee enterprises.
End User:
Application intensity varies by sector maturity, with Finance and Manufacturing driving platform complexity while Retail and Telecommunications prioritize speed-to-deployment over customization depth.
- Manufacturing:Shop-floor orchestration connects MES, ERP, and quality management systems. Emilia-Romagna automotive suppliers lead adoption of predictive maintenance workflows.
- Finance:Loan origination and claims processing demand explainable AI integration to satisfy EU AI Act auditability requirements. Milan-based banking consortiums consolidate fragmented automation estates.
- Retail:Omnichannel order orchestration synchronizes inventory across physical and digital storefronts. Northern Italy fashion houses deploy event-driven architectures for real-time stock visibility.
- Telecommunications:Network service provisioning and customer onboarding automation reduce manual intervention. National carriers modernize legacy BSS/OSS stacks through API-native integration.
Finance dominates installed base. Manufacturing is where expansion concentrates.
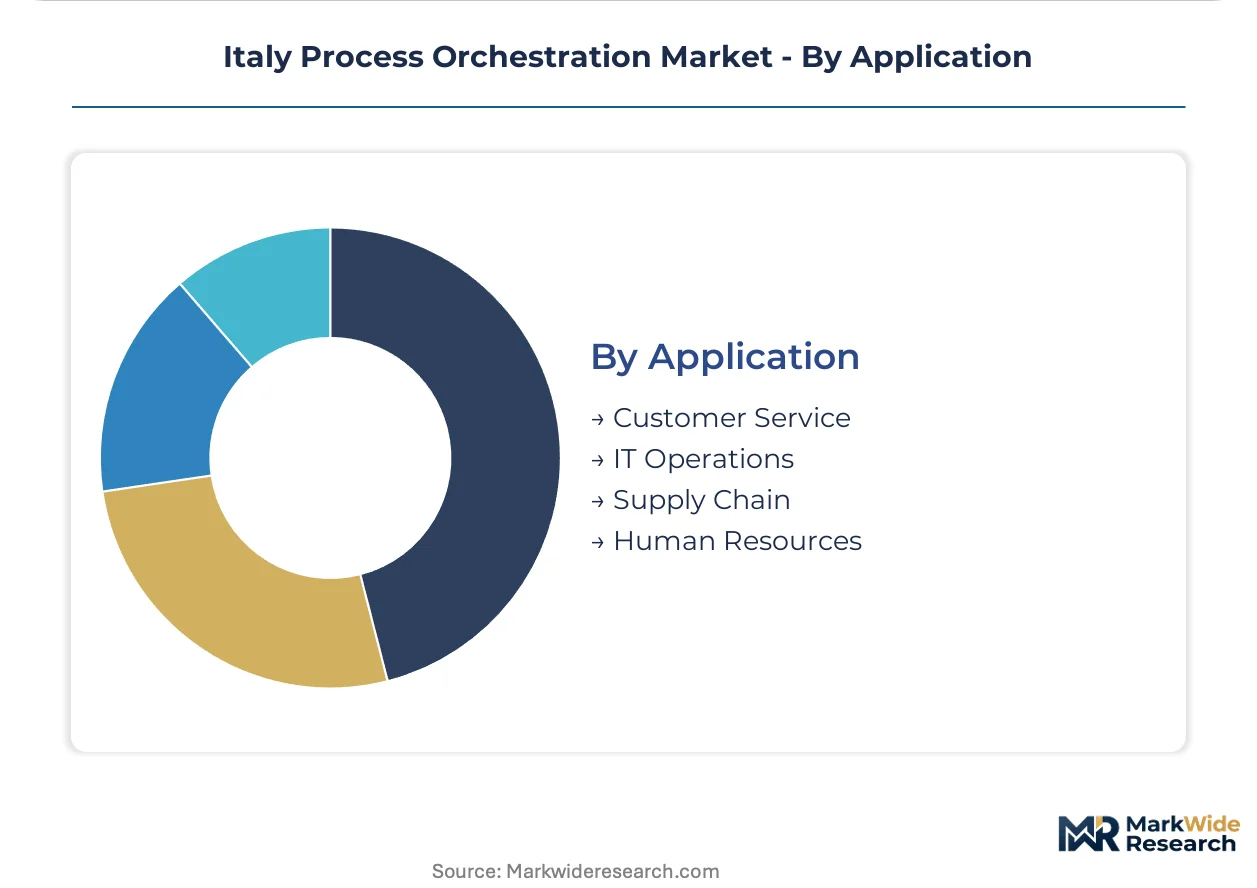
Application:
Functional deployment patterns reflect organizational digital maturity, with IT Operations and Supply Chain leading technical sophistication while Customer Service and Human Resources prioritize business-user accessibility.
- Customer Service:Case routing and resolution workflows integrate CRM, knowledge bases, and communication channels. Italian insurers deploy these systems to accelerate claims processing.
- IT Operations:Incident management and infrastructure provisioning automation reduce mean-time-to-resolution. Large enterprises adopt AIOps-infused orchestration for autonomous remediation.
- Supply Chain:Multi-tier supplier coordination and logistics optimization demand real-time visibility. Milan-Turin industrial corridor manufacturers prioritize this application for inventory synchronization.
- Human Resources:Onboarding, payroll integration, and compliance documentation workflows reduce administrative overhead. Mid-market enterprises favor low-code interfaces for HR process modification.
IT Operations dominates installed base. Supply Chain is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's process orchestration trade flows reflect a technology import dependency, with platform licensing and implementation services constituting the dominant import categories while specialized integration consulting generates modest export revenue to neighboring EU markets.
Lombardy
Milan anchors national demand for financial services orchestration as banking consortiums consolidate fragmented automation estates. The EU AI Act mandates explainability modules for automated loan decisions, accelerating platform refresh cycles. The Milan-Turin industrial corridor concentrates procurement budgets for cloud-native workflow engines serving multinational enterprises.
Emilia-Romagna
Automotive suppliers in Modena and Bologna drive manufacturing adoption of API-native orchestration bridging legacy MES with cloud ERP. AgID interoperability standards shape public-sector procurement in regional administrative centers. The Motor Valley cluster generates specialized demand for predictive maintenance workflows integrating machine learning inference.
Piedmont
Turin-based industrial districts pilot outcome-based pricing models linking platform fees to measured efficiency gains. Low-code orchestration interfaces gain traction among mid-market enterprises seeking to reduce dependency on scarce integration specialists. The region's aerospace and automotive heritage sustains demand for hybrid cloud architectures maintaining legacy core systems.
Veneto
Textile manufacturers in Vicenza and Treviso adopt event-driven architectures for real-time inventory synchronization across multi-site production networks. Cloud-based deployment climbs fastest among sub-500-employee enterprises avoiding capital expenditure. The regional fashion supply chain generates demand for omnichannel order orchestration connecting physical and digital storefronts.
Lazio
Rome concentrates public-sector digitization procurement driven by AgID mandates for standardized API specifications. Central government agencies require pre-certified orchestration connectors against national technical standards. The regional technology services ecosystem supplies implementation talent for Southern Italy expansion into Campania and Sicily.
Italy Process Orchestration Market Competitive Landscape
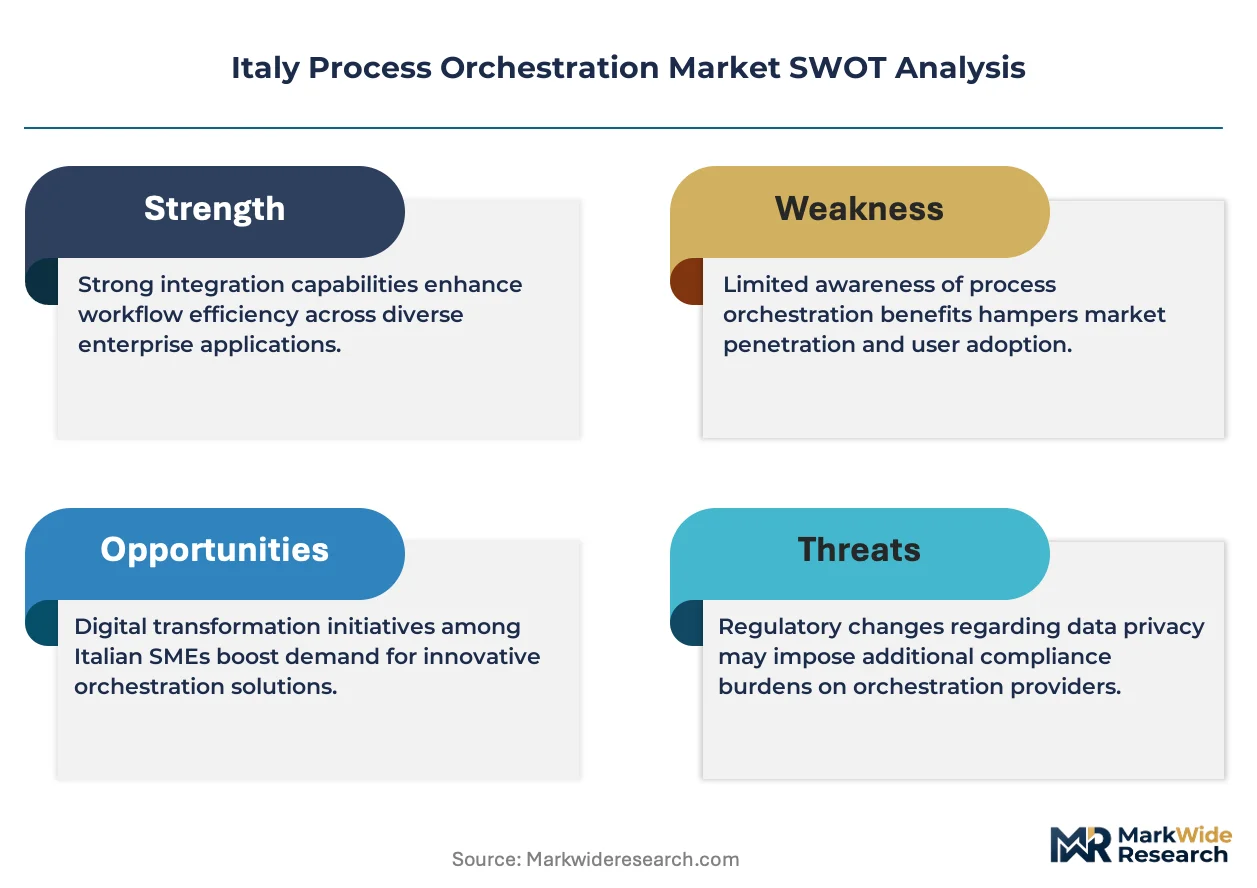
Concentration sits with capital-heavy platform builders leveraging hybrid cloud architectures and deep ERP-native integration against lean specialists in robotic process automation bridges. The vendor landscape bifurcates between premium deployment anchors and rapid-deployment integration layers. Three archetypes dominate: legacy infrastructure extenders, cloud-native workflow builders, and automation bridge specialists. Competitive moves center on compliance engineering investments for EU AI Act certification and channel partner expansion into industrial districts.
Within the platform builder tier, IBM Corporation and Microsoft Corporation exemplify capital-heavy architectures serving Lombardy financial institutions, while SAP SE occupies a position anchoring ERP-native orchestration for manufacturing loyalty in Emilia-Romagna. UiPath represents the lean integration specialist archetype extending legacy system lifecycles without full infrastructure replacement.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| ServiceNow |
| Salesforce Inc. |
| SAP SE |
| UiPath |
| Appian |
| Automation Anywhere |
| Accenture Public Limited Company |
| Others |
Pricing and Supply Chain Analysis
Platform-level scale economies in cloud-native orchestration engines compress marginal delivery costs for vendors serving multiple Lombardy banking clients simultaneously, concentrating pricing power among hybrid-cloud providers while forcing lean integration specialists toward outcome-based contracting to defend margin floors.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing across the Italian market, with three-tier pricing structure across premium, standard, and economy levels differentiating by compliance certification depth and API throughput volume. Cost compression in the mid-market tier is intensifying because AgID pre-certification requirements inflate vendor engineering overhead. Family-owned manufacturers in Emilia-Romagna exhibit highest price sensitivity, while Milan-based banking consortiums prioritize audit-trail completeness over per-seat cost.
Supply Chain Analysis
Kubernetes certification bottlenecks in Southern European training centers constrain qualified implementation partner availability, forcing Italian enterprises to source from Germany, Netherlands, and Ireland for certified integration engineers. Raw material dependencies span proprietary workflow engine IP, hyperscaler compute capacity, and legacy COBOL middleware expertise. Single-source vulnerability sits with IBM and Microsoft cloud regions for financial services deployments. Distribution runs through Turin and Milan-based systems integrators with AgID accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italian process orchestration market rewards vendors who control scarce certified engineering talent capable of bridging legacy COBOL estates with containerized workflow engines, while penalizing pure-play SaaS providers lacking compliance engineering bandwidth.
For Market Incumbents: Compound platform stickiness by embedding EU AI Act explainability modules directly into orchestration layers rather than treating compliance as peripheral add-on, and expand certified partner networks in Campania and Sicily before AgID procurement pipelines mature. Cloud-native challengers with low-code interfaces threaten mid-market manufacturing accounts currently served by SAP-anchored deployments. For New Entrants and Emerging Players: Lead with outcome-priced models in Piedmont industrial districts where Turin-based procurement committees pilot contracts linking platform fees to measured loan processing throughput or claims resolution speed. Southern Italy public-sector digitization offers the most penetrable geography, with AgID-mandated interoperability standards creating procurement pipelines where legacy paper workflows dominate. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid-cloud platform builders with dedicated compliance engineering teams capable of pre-certifying connectors against national technical standards. Over the projection horizon, acquisition targets should demonstrate proven API-native integration for manufacturing MES-to-ERP bridges. The signal to watch is AgID tender volume acceleration in Campania and Sicily as lagging indicators of vendor certification bandwidth constraints.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Engineering Investment | Embeds audit trails and explainability modules directly into orchestration layers for Lombardy financial institutions. |
| AgID Pre-Certification Expansion | Qualifies vendors for government tenders in Campania and Sicily where legacy paper workflows dominate procurement. |
| Outcome-Based Pricing Pilot Programs | Links platform fees to measured KPI improvements in loan processing throughput for Turin industrial districts. |
| Legacy COBOL Bridge Development | Extends system lifecycles for Emilia-Romagna automotive suppliers without full infrastructure replacement cycles. |
| Low-Code Interface Democratization | Compresses time-to-deployment from quarters to weeks for Piedmont mid-market enterprises reducing Java dependency. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with CTOs, IT procurement officers, platform engineers, and AgID compliance leads at Italian financial institutions and manufacturing enterprises, combined with secondary validation against SEC filings, hyperscaler capex disclosures, EU AI Act regulatory texts, and AgID interoperability framework documentation. Bottom-up deployment estimates triangulated against top-down addressable market calculations.
Across the analysis window, the analytical framework modeled value trajectories by deployment model, organization size, vertical sector, integration complexity, and regional adoption pattern within Italy. CAGRs were derived from segment-level growth rate synthesis. Forecast inputs incorporated AgID procurement pipeline velocity and EU AI Act enforcement timeline assumptions.
Forecasts assume regulatory continuity in EU AI Act implementation and AgID interoperability mandates; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as cloud sovereignty requirements and data residency enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Home Automation and Controls Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Automation-As-A-Service Market
Automation
Distribution Automation Solutions Market
Automation
Automated Cell Block Systems Market
Automation
Global Automated Sample Storage Systems Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
RFID Kanban Systems Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Global Automated Liquid Handling System Market
Automation
Workflow Automation Market
Automation
Self Bag Drop Machine Market
Automation
Process Automation Market
Automation
North America Home Automation Systems Market