
 Smart Remote Control Market | 2026-2036
Smart Remote Control Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Remote Control Market Outlook
Chinese OEM production capacity is rebalancing toward voice-controlled and app-enabled units as infrared-only assembly lines scale down. Samsung Electronics leverages its semiconductor captive supply to sustain cost advantages in Wi-Fi module integration. LG Electronics anchors premium positioning through proprietary ThinQ ecosystem lock-in. BroadLink competes aggressively on price in the Zigbee protocol segment across Southeast Asian export markets.
A smart remote control is a wireless handheld or software-embedded device that transmits command signals via infrared, Bluetooth, Wi-Fi, or Zigbee protocols to operate consumer electronics, building automation systems, or IoT endpoints, typically incorporating microcontrollers with sub-1GHz to 2.4GHz RF transceivers and voice-processing DSP cores for hands-free operation. Voice-controlled remotes now command the steepest growth trajectory as natural language processing migrates from cloud-dependent to edge-AI architectures, while infrared-based universal remotes occupy a mature, margin-compressed tier sustained by legacy television and set-top box replacement cycles. Wi-Fi technology leads value capture due to direct IP-stack integration with smart home platforms, whereas Zigbee segments specialize in low-latency mesh networking for whole-home lighting and HVAC coordination.
The FCC in the United States governs RF emission limits and spectrum allocation for 2.4GHz smart remote transceivers, while the EU Radio Equipment Directive and CE marking framework mandate interoperability and cybersecurity baselines for devices sold across member states. China's MIIT enforces GB standards for short-range wireless transmission power and protocol authentication, creating segmented compliance burdens for multi-region product portfolios. Stakeholders must monitor whether emerging Matter protocol certification requirements will consolidate previously fragmented smart home connectivity standards or perpetuate parallel SKU proliferation across regulatory jurisdictions.
Market Dynamics
The smart remote control market is restructuring around protocol consolidation as Matter certification gains traction, forcing manufacturers to abandon proprietary connectivity stacks in favor of interoperable IP-based frameworks that reduce SKU proliferation across regional regulatory boundaries.
Growth Catalysts
- EU Radio Equipment Directive:Harmonized cybersecurity baselines for wireless devices reduce testing redundancy across member states, accelerating multi-country product launches.
- Edge-AI voice processing:On-device natural language inference eliminates cloud latency, enabling responsive hands-free control in bandwidth-constrained environments.
- Shenzhen manufacturing cluster:Concentrated component supply and finished device assembly create procurement efficiency for Wi-Fi and Zigbee module sourcing.
Market Restraints
- Silicon supply concentration:RF transceiver and microcontroller fabrication depends on Taiwan and South Korea foundry capacity, exposing lead time volatility.
- Infrared legacy lock-in:Set-top box and basic television replacement cycles sustain margin-compressed universal remote tiers that cannibalize development resources.
- Fragmented certification:Parallel FCC, CE marking, and MIIT GB standard compliance multiplies testing costs for multi-region product portfolios.
Strategic Opportunities
- India residential smart home buildout:Urban middle-class housing stock lacks legacy infrared infrastructure, enabling direct Wi-Fi and Zigbee-native deployment.
- Healthcare facility automation:Voice-controlled environmental systems for patient rooms and operating suites demand hygienic, hands-free interfaces.
- Matter protocol adoption:Unified connectivity standard collapses previous Z-Wave, Zigbee, and proprietary ecosystem silos into single-SKU coverage.
Industry Challenges
- RF engineering talent scarcity:Sub-1GHz and 2.4GHz antenna design expertise concentrates in Shenzhen and Taipei, constraining in-house development outside Asia-Pacific.
- Matter certification backlog:Device interoperability testing queues at authorized labs extend product launch timelines.
- Legacy infrared integration:Backward compatibility requirements for existing television and AV receiver installed bases complicate pure-IP remote architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Remote Control Market |
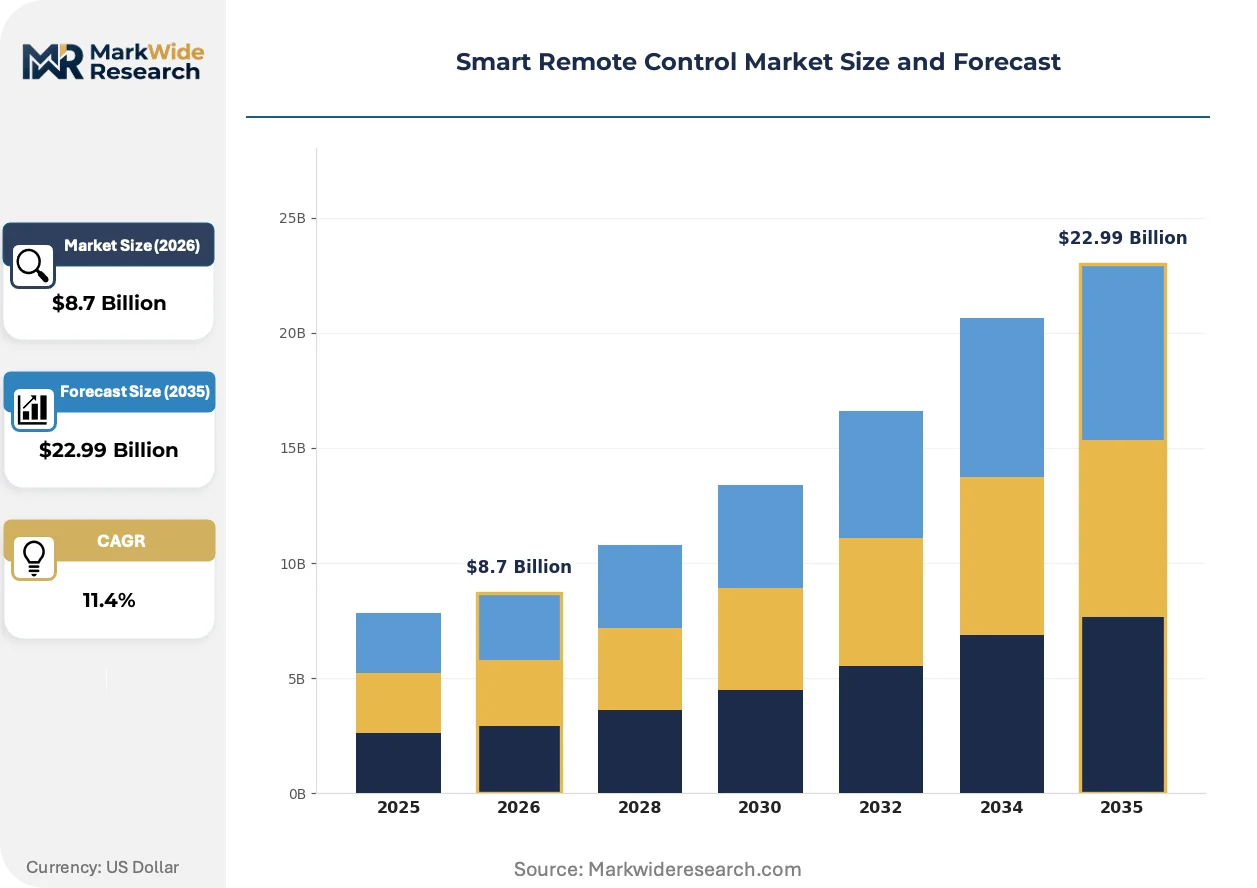
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Remote, App-Enabled Remote, Voice-Controlled Remote, Gesture-Controlled Remote Technology: Infrared, Bluetooth, Wi-Fi, Zigbee End User: Residential, Commercial, Industrial, Healthcare Functionality: Lighting Control, Entertainment Control, HVAC Control, Home Security |
| Companies Covered | Sony Corporation, Panasonic, Universal Electronics Inc., TCL, BroadLink, SMK Corporation, LG Electronics, Funai Electric, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Remote Control Market Strategic Shifts
Protocol architecture is migrating from infrared-dependent hardware toward software-defined connectivity stacks, compressing hardware BOM while expanding functional scope through firmware updates and cloud service integration.
Voice-controlled edge-AI remotes is overtaking cloud-dependent alternatives by processing natural language commands locally on DSP cores. Residential buyers in North America and Western Europe prioritize sub-100ms response latency. This shift is compressing ASP differentiation between premium voice-enabled and standard button-based units as silicon costs converge.
CE marking cybersecurity requirements under the EU Radio Equipment Directive now mandate encrypted firmware update channels and secure boot protocols for all wireless connectivity modules. Manufacturers serving European distribution channels must redesign legacy product lines or abandon the market. Smart home platform integrators in Germany and France are accelerating supplier audits to pre-validate compliance documentation.
Direct-to-consumer channel expansion is disrupting traditional retail electronics distribution for smart home peripherals. Amazon and dedicated IoT marketplaces capture growing volume from big-box electronics retailers. This pattern is most pronounced in US and UK metropolitan markets where subscription bundling with voice assistant platforms drives replacement cycle compression.
Smart Remote Control Market Segmentation
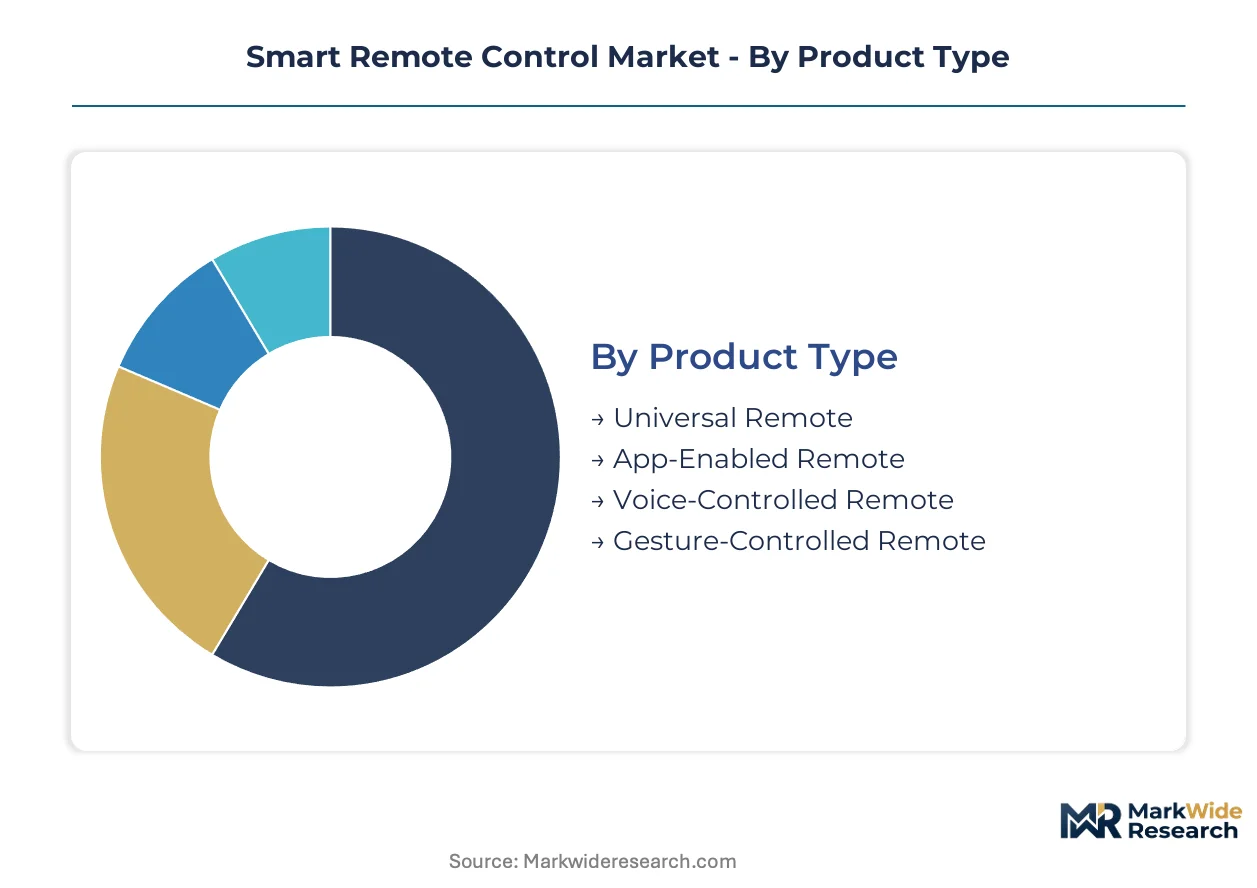
Smart remote control segmentation reveals divergent margin structures across connectivity protocols and user interfaces. Product type and technology combinations determine whether manufacturers capture premium positioning or compete on assembly cost.
Product Type:
Volume concentrates in replacement-cycle hardware while premium capture shifts toward software-embedded and AI-enabled interfaces.
- Voice-Controlled Remote:Integrates DSP cores for on-device natural language processing with sub-100ms response latency. Demand clusters in North American and Western European residential smart home installations where hands-free operation drives replacement of button-based units.
- App-Enabled Remote:Software-embedded control layer running on smartphones and tablets, eliminating dedicated hardware BOM. Growth concentrates in urban middle-class housing across India and Southeast Asia where smartphone penetration precedes dedicated smart home infrastructure.
- Universal Remote:Infrared-only hardware sustaining television and set-top box replacement cycles with compressed margins. Legacy compatibility requirements dominate procurement specifications.
- Gesture-Controlled Remote:Motion-sensing accelerometers and gyroscopes enabling spatial command input. Niche deployment in gaming and high-end entertainment systems.
Mature deployment sits with Universal Remote. Newer deployment is concentrated in Voice-Controlled Remote.
Technology:
Protocol selection determines regulatory testing burden and ecosystem integration depth.
- Wi-Fi:Direct IP-stack integration with smart home platforms enabling cloud service connectivity and firmware update channels. Value capture concentrates in whole-home automation deployments across Germany, France, and US metropolitan markets.
- Zigbee:Low-latency mesh networking protocol specializing in lighting and HVAC coordination with sub-50ms device-to-device response. Demand clusters in commercial building automation and European residential retrofit projects.
- Bluetooth:Point-to-point connectivity for proximity-based control with simplified pairing protocols. Dominates personal entertainment device control.
- Infrared:Line-of-sight transmission dependent on legacy encoding schemes. Sustained by television, set-top box, and AV receiver installed bases requiring backward compatibility.
Wi-Fi commands the steepest value capture trajectory. Infrared occupies the most mature, margin-compressed tier.
End User:
Application context shapes durability requirements, security baselines, and procurement authority structures.
- Residential:Consumer-directed purchasing through retail and direct-to-consumer channels with subscription bundling acceleration. Voice assistant platform integration drives replacement cycle compression in US and UK markets.
- Commercial:Facility management procurement with centralized deployment across office and retail footprints. Matter protocol adoption is collapsing previous ecosystem silos into unified connectivity standards.
- Healthcare:Hygienic, hands-free environmental control for patient rooms and operating suites with stringent infection prevention protocols. Voice-controlled edge-AI interfaces eliminate surface contact requirements.
- Industrial:Hardened enclosures and extended temperature range specifications for manufacturing floor deployment. Integration with building management systems and safety interlocks.
Residential channels dominate unit volume. Healthcare represents the steepest expansion trajectory for voice-enabled interfaces.
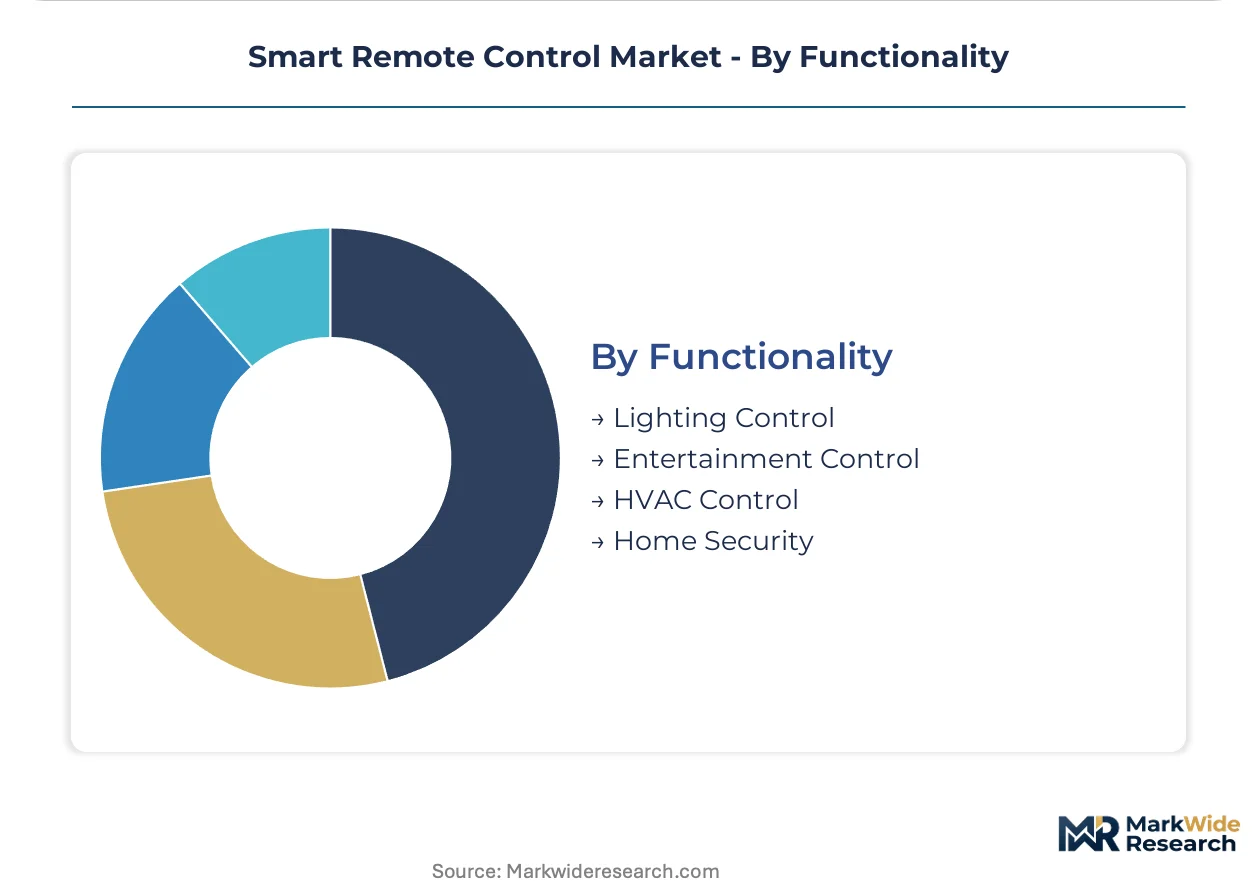
Functionality:
Use case specificity determines sensor integration requirements and platform API complexity.
- Entertainment Control:Universal command libraries for television, streaming devices, audio systems, and gaming consoles. Infrared legacy compatibility remains mandatory.
- Lighting Control:Dimming curves, color temperature adjustment, and scene programming through Zigbee mesh networks. European deployment leads under EU energy efficiency directives.
- HVAC Control:Temperature setpoint management, scheduling, and occupancy-based automation. Commercial building energy management systems drive specification authority.
- Home Security:Arming/disarming interfaces, camera control, and alert acknowledgment with encrypted command transmission. CE marking cybersecurity requirements mandate secure boot protocols.
Entertainment Control anchors established replacement cycles. Lighting Control is gaining share fastest under smart home platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing cluster anchors component supply for RF transceivers and microcontroller modules serving smart remote assembly lines worldwide. Concentrated foundry capacity in Taiwan and South Korea shapes lead time volatility across regional demand centers. Regulatory fragmentation between FCC, CE marking, and MIIT GB standards forces parallel certification tracks for multi-region product portfolios.
United States
Residential smart home adoption drives voice-controlled remote replacement cycles in metropolitan markets. FCC governs 2.4GHz RF emission limits and spectrum allocation for Wi-Fi and Zigbee transceivers. Amazon's Seattle headquarters anchors direct-to-consumer channel expansion bundling voice assistant platforms with hardware peripherals.
China
MIIT enforces GB standards for short-range wireless transmission power and protocol authentication across domestic manufacturing. Shenzhen's Pearl River Delta electronics corridor dominates Wi-Fi and Zigbee module sourcing with concentrated PCB fabrication and finished device assembly. Component suppliers are rebalancing capacity toward voice-controlled and app-enabled units.
Germany
EU Radio Equipment Directive harmonized cybersecurity baselines accelerate multi-country product launches from German distribution hubs. CE marking mandates encrypted firmware update channels and secure boot protocols for wireless connectivity modules. Berlin and Munich smart home platform integrators pre-validate supplier compliance documentation ahead of enforcement deadlines.
India
Urban middle-class housing stock lacks legacy infrared infrastructure, enabling direct Wi-Fi and Zigbee-native deployment without backward compatibility burdens. TRAI spectrum management frameworks govern 2.4GHz device certification for imported electronics. Maharashtra and Karnataka residential construction corridors represent concentrated demand for smartphone-embedded app control interfaces.
Japan
METI industrial standards shape RF device interoperability requirements for domestic smart home integration. Tokyo and Osaka metropolitan markets sustain premium positioning for gesture-controlled and edge-AI voice processing interfaces. Domestic semiconductor design houses concentrate sub-1GHz antenna expertise serving regional OEM procurement specifications.
Smart Remote Control Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent connectivity protocol specializations. Market structure fragments across three tiers: semiconductor-integrated conglomerates with captive RF module supply, dedicated remote control OEMs with concentrated manufacturing scale, and software-embedded platform providers eliminating hardware BOM. Strategic archetypes include ecosystem lock-in specialists, price-aggressive protocol pure-plays, and voice-AI edge computing integrators. Dominant competitive moves encompass Matter certification pre-positioning and backward integration into RF transceiver design.
Within the semiconductor-integrated tier, Samsung Electronics and LG Electronics exemplify captive supply chain advantages. Samsung leverages in-house Wi-Fi module fabrication to compress integration costs, while LG anchors premium positioning through proprietary ecosystem architecture. BroadLink occupies a distinct archetype as a protocol-specialist pure-play competing on price in Zigbee segments. These three manufacturers represent divergent strategic postures: vertical silicon control, ecosystem lock-in, and focused protocol cost leadership.
| Leading Market Players |
|---|
| Sony Corporation |
| Panasonic |
| Universal Electronics Inc. |
| TCL |
| BroadLink |
| SMK Corporation |
| LG Electronics |
| Funai Electric |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
EU Radio Equipment Directive cybersecurity mandates gate qualified supplier access and premium-tier pricing power for CE-marked connectivity modules. Manufacturers lacking encrypted firmware channels face market exclusion while compliant vendors capture pricing premiums across German and French distribution channels.
Pricing Analysis
Warranty and firmware-update service bundling separates premium voice-enabled remotes from unbundled infrared replacement units. Three-tier pricing structure across premium, standard, and economy levels reflects Matter certification status, edge-AI DSP integration depth, and after-sales support commitments. Pricing pressure stems from Shenzhen component oversupply compressing Wi-Fi module costs at the standard tier. Residential buyers in India and Southeast Asia exhibit highest price sensitivity, while healthcare facility procurement in Japan and Germany prioritizes latency performance over unit cost.
Supply Chain Analysis
Reverse-logistics networks for voice-controlled remotes remain underdeveloped, with limited refurbishment infrastructure outside Shenzhen and Taipei. RF transceiver fabrication concentrates in Taiwan and South Korea, while finished device assembly anchors in China's Pearl River Delta. Key component inputs include 2.4GHz Wi-Fi chipsets, Zigbee mesh networking modules, and edge-AI DSP cores. Single-source vulnerability in Taiwan foundry capacity exposes lead time volatility. Distribution runs through Amazon's direct-to-consumer channel and traditional electronics retailers, with platform bundling accelerating in US metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF engineering talent scarcity in sub-1GHz antenna design props pricing power for Asia-Pacific manufacturing clusters. Foundry capacity constraints at Taiwan semiconductor fabs sustain margin premiums for captive-supply incumbents.
For Market Incumbents: Extend Matter certification pre-positioning to collapse multi-protocol SKU proliferation into single-SKU coverage. Deepen backward integration into RF transceiver design to offset Taiwan foundry dependency. Capture voice-AI edge computing talent in Tokyo and Taipei before emerging entrants establish development presence. For New Entrants and Emerging Players: Direct-to-consumer Amazon marketplace routes bypass traditional retail gatekeepers and enable rapid voice-enabled remote launches. Target India's urban middle-class housing corridors lacking legacy infrared infrastructure for Wi-Fi-native deployment. Pursue white-label manufacturing partnerships with Shenzhen assembly houses to compress time-to-market. For Investors and Strategic Acquirers: Matter protocol certification queue clearance at authorized test labs is the leading indicator that supply-constrained interoperability testing is easing. Five-to-ten year viability favors semiconductor-integrated conglomerates with captive Wi-Fi module fabrication. Monitor CE marking enforcement deadlines for early signals of compliance-driven supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Pre-Positioning | Single-SKU coverage collapses Z-Wave, Zigbee, and proprietary protocol silos. |
| Edge-AI Voice Processing Integration | On-device NLP eliminates cloud latency for sub-100ms healthcare applications. |
| RF Transceiver Backward Integration | Captive supply insulates against Taiwan foundry lead time volatility. |
| Direct-to-Consumer Channel Expansion | Amazon bundling accelerates replacement cycles in US metropolitan markets. |
| Healthcare Facility Partnership Development | Hygienic voice interfaces address infection prevention protocols in patient rooms. |
Study Parameters
Document review covered FCC equipment authorization databases, EU Radio Equipment Directive guidance documents, and MIIT GB standard filings, complemented by interviews with RF module procurement managers, smart home platform engineers, and electronics manufacturing executives. Secondary sources included SEC 10-K disclosures from semiconductor-integrated OEMs, Shenzhen customs export records, and TRAI device certification registries. Bottom-up unit shipment estimates triangulated against top-down smart home installation forecasts.
Segment-level projections across connectivity protocol, user interface type, and end-use application generated value trajectories over the projection horizon. The analytical framework modeled Wi-Fi, Zigbee, Bluetooth, and infrared technology splits alongside voice-controlled, app-enabled, and button-based product configurations. CAGRs derived from protocol adoption curves and replacement cycle compression patterns in residential and healthcare segments.
The model holds under stable Taiwan foundry capacity and Matter certification timeline assumptions; deviation in CE marking enforcement stringency or Shenzhen labor availability would shift volume and value outputs. Practitioners should monitor authorized lab testing queue lengths and MIIT GB standard revision announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Robot Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Humanoids Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Middle East Cloud Robotics Market