
 Workstation Market | 2026-2036
Workstation Market Size, Share, and Industry Trends Forecast 2026-2036
Workstation Market Outlook
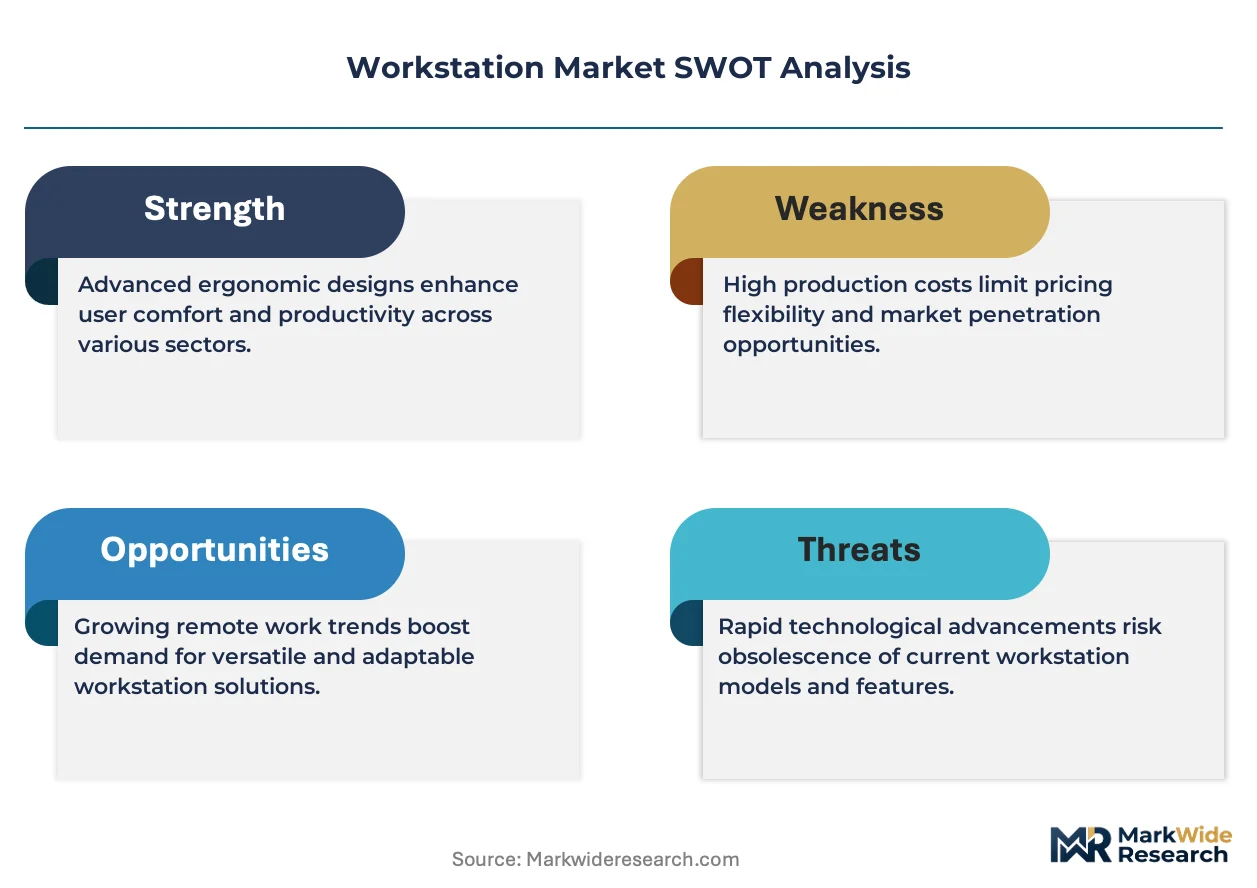
High-performance GPU specifications is redrawing competitive boundaries across the workstation landscape. NVIDIA leverages its parallel processing architecture to dominate datacenter-class visualization deployments. HP anchors enterprise procurement through integrated support channels and ISV certification breadth. Dell competes on modular chassis designs that extend service lifecycles across engineering workflows.
A workstation constitutes a specialized computing platform engineered for intensive professional tasks, typically incorporating multi-core processors, professional-grade graphics adapters with ECC memory, and advanced thermal management systems sustaining sustained 100% duty cycles. The hardware solution segment commands the largest revenue pool given component margin structures, while cloud solutions and virtual workspaces represent the fastest-expanding category as enterprises redistribute capital expenditure toward subscription models. Mobile workstations attract premium pricing among architects and video editors requiring field-deployable rendering capability without desktop-class power draw.
FCC equipment authorization requirements shape electromagnetic compatibility standards for US-bound systems, while EU CE marking and RoHS substance restrictions govern European market access and material composition. Japan's METI energy efficiency directives influence power supply and thermal design specifications for products sold into that market. Stakeholders must monitor how AI integration standards evolve across these regulatory frameworks to anticipate certification burdens and design-in requirements.
Market Dynamics
AI inference workloads are compressing hardware refresh cycles across professional visualization, engineering simulation, and content creation workflows, forcing procurement departments to reassess capital allocation timelines and vendor certification requirements.
Growth Catalysts
- Media Production Pipeline Modernization:Streaming platform content arms races are expanding render farm capacity. Production houses in the United States and Germany are deploying GPU-dense workstations for real-time virtual production stages.
- EU AI Act Compliance Deadlines:Enterprises subject to high-risk AI system documentation requirements are upgrading to hardware with verified training telemetry and audit-grade logging capabilities.
- ECC Memory Mandates:Financial services and healthcare imaging workloads are driving demand for error-correcting memory configurations in mission-critical simulation environments.
Market Restraints
- GPU Supply Concentration:Advanced accelerator fabrication depends on a single foundry geography for leading-edge process nodes, creating allocation bottlenecks during demand surges.
- RoHS Substance Substitution Costs:EU material restrictions on lead and cadmium in solder alloys are forcing redesign of thermal interface materials and power delivery subsystems.
- Cloud Rendering Substitution:Elastic compute services from hyperscale providers are capturing episodic rendering workloads that previously required dedicated on-premise hardware.
Strategic Opportunities
- India PLI Scheme Incentives:Production-linked incentives for IT hardware manufacturing are attracting assembly investments for mobile workstations targeting domestic creative professionals.
- Edge AI Model Fine-Tuning:Convergence of containerized ML pipelines and workstation-class GPU density is enabling on-device model customization without data center egress.
- Subscription Hardware Models:Device-as-a-service channels are penetrating architectural and engineering firms seeking to convert capital expenditure to operational budgets.
Industry Challenges
- ISV Certification Backlogs:Application vendor validation queues for new GPU architectures are extending deployment timelines for engineering software dependent on verified driver stacks.
- Legacy CAD Migration Complexity:Decades-old parametric modeling databases require workstation configurations maintaining backward compatibility with deprecated graphics APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workstation Market |
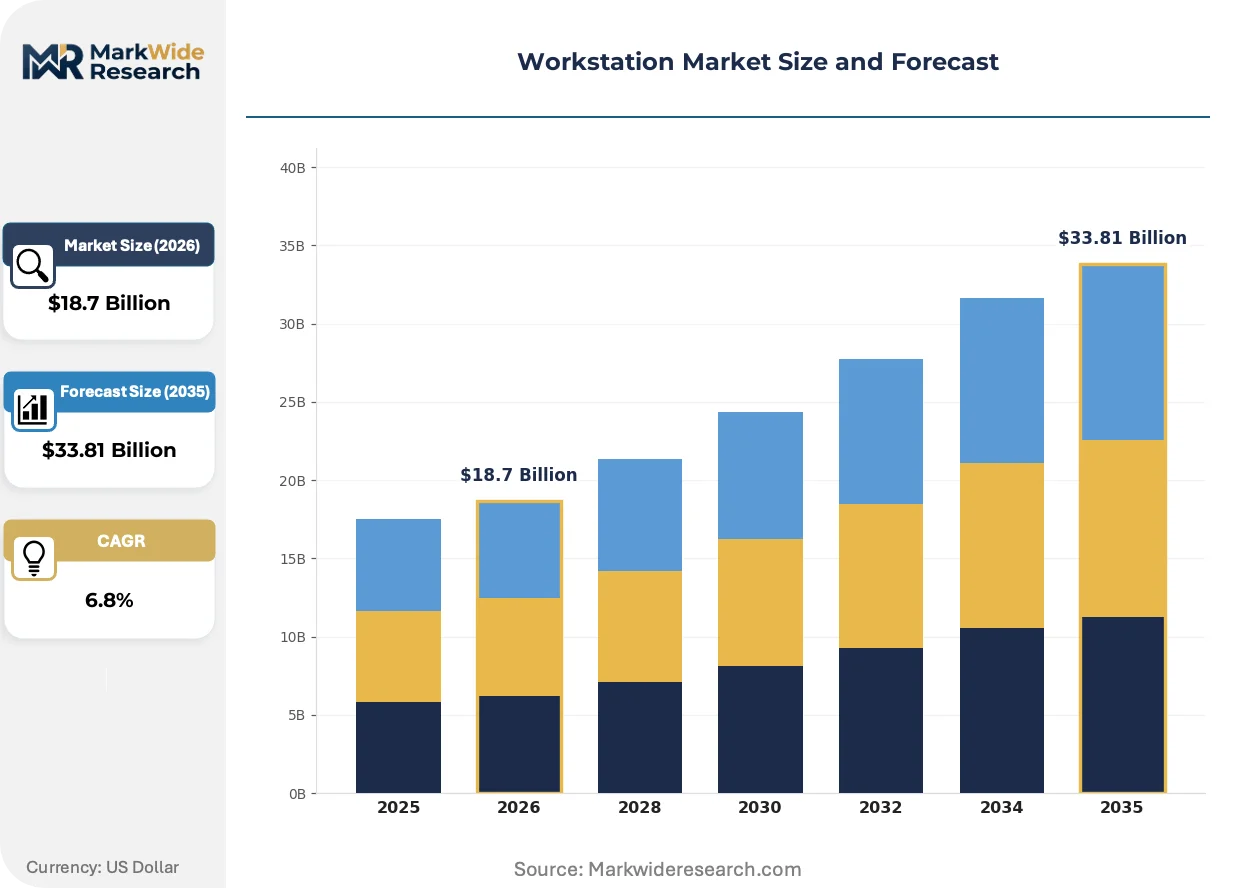
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktops, Laptops, Gaming Workstations, Mobile Workstations End User: Graphic Designers, Engineers, Video Editors, Architects Solution: Hardware, Software, Cloud Solutions, Virtual Workspaces Technology: AI Integration, High-Performance Computing, Virtual Reality, Augmented Reality |
| Companies Covered | Apple, NVIDIA, HP, Herman Miller, Steelcase, Dell, Asus, Vitra, Lenovo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workstation Market Strategic Shifts
Computational workloads are fragmenting across hybrid architectures, with software-defined resource allocation eroding the boundary between local and remote processing. This redistribution is reshaping how vendors position thermal design, memory hierarchy, and form factor trade-offs.
Chiplet-based GPU architectures are decomposing monolithic processor designs into modular compute tiles interconnected through high-bandwidth fabric. Media production studios in Japan are adopting these configurations for memory-scalable rendering pipelines. The disaggregation is decomposing traditional workstation tiering, allowing buyers to configure compute density independent of chassis thermal limits.
Japan's METI energy efficiency directives are tightening standby power and active load consumption thresholds for professional computing equipment. Manufacturers are redesigning power supply units and thermal management systems to meet these specifications. Mobile workstation SKUs bound for Japanese enterprise procurement are most affected, with vendors pre-configuring power profiles to auto-throttle under sustained thermal conditions.
Enterprise buyers are consolidating vendor relationships through single-source frameworks that bundle hardware, support, and cloud burst capacity. Systems integrators are displacing direct OEM relationships in North American architectural and engineering procurement. This concentration is most visible in United States federal contracting, where certified small-business resellers capture workstation volume through set-aside vehicles.
Workstation Market Segmentation
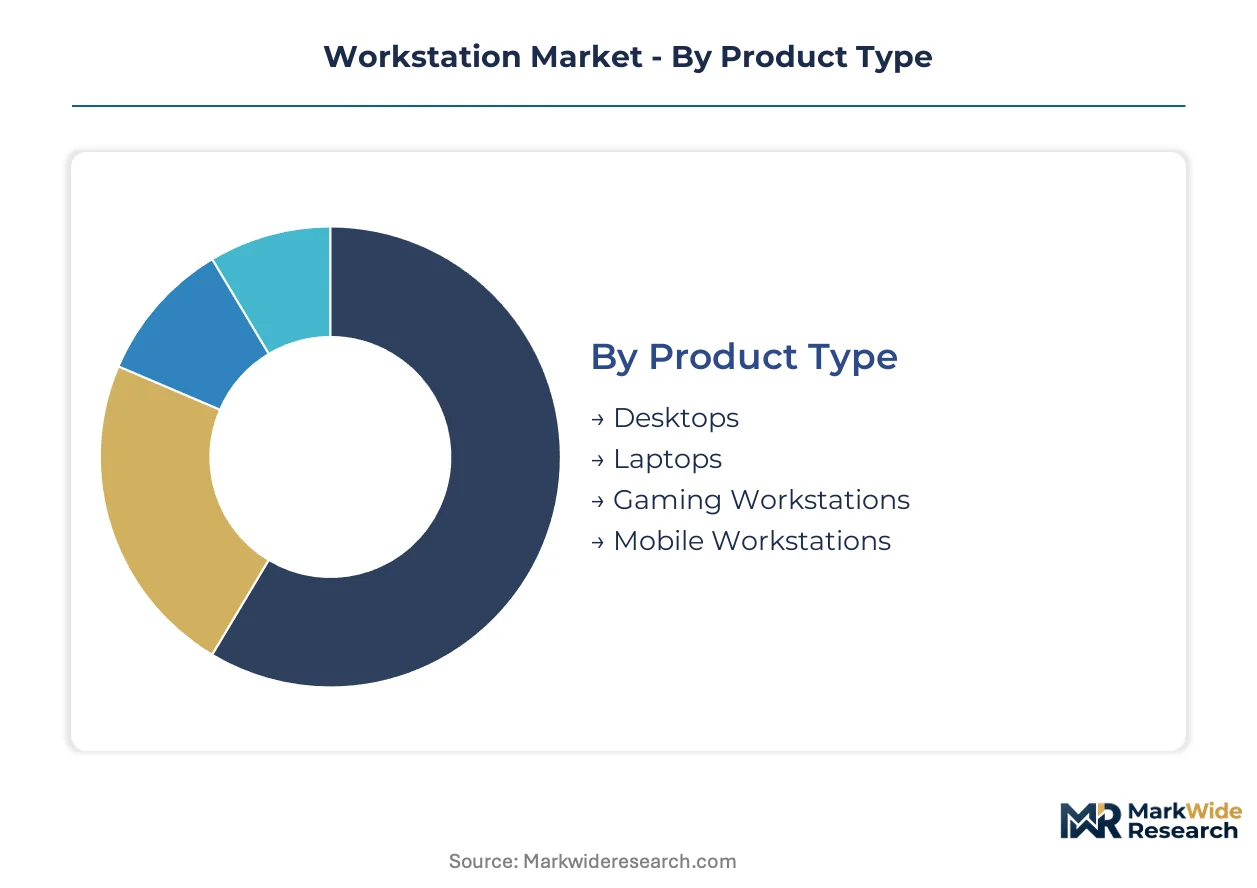
Workstation procurement patterns fragment sharply across product form factors and deployment models. Professional buyers configure specifications around thermal constraints, ISV certification requirements, and capital-to-operating-expense conversion priorities.
Product Type:
Desktop and laptop segments serve predominantly domestic enterprise procurement, while mobile workstation exports concentrate in Germany and Japan where field-deployable rendering commands premium positioning.
- Desktops:Tower and rack-mount configurations integrate multi-GPU arrays with active liquid cooling sustaining 100% thermal design power. Engineering firms in the United States anchor procurement for simulation clusters requiring ECC memory and verified driver stacks.
- Laptops:Thin-and-light mobile chassis sacrifice GPU thermal headroom for portability, attracting architects conducting client-site presentations. Japanese buyers prioritize METI-compliant power profiles that throttle under sustained load.
- Gaming Workstations:Consumer-derived platforms with professional certification overlays target entry-level content creators in India.
- Mobile Workstations:Field-deployable units with swappable battery configurations serve German construction documentation teams.
Desktops command the established base. The steepest expansion runs through mobile workstations.
End User:
Engineer procurement concentrates in high-volume annual refresh cycles, while architect buying patterns stretch replacement timelines across depreciation schedules.
- Graphic Designers:Color-calibrated display requirements and Pantone validation drive specification priorities. Adobe Creative Cloud integration demands GPU memory bandwidth scaling with project resolution.
- Engineers:Finite element analysis and computational fluid dynamics workloads stress thermal design limits. German automotive suppliers mandate ISV-certified configurations for CATIA and Siemens NX deployments.
- Video Editors:Real-time 8K playback requirements push codec-specific hardware acceleration in United States post-production houses.
- Architects:Revit model complexity and ray-traced visualization needs determine GPU vRAM minimums for Japanese design firms.
Engineers anchor volume procurement. Video editors are gaining share fastest as streaming platform content budgets expand.
Solution:
Hardware margins concentrate component supplier relationships, while cloud and virtual workspace offerings redistribute vendor power toward systems integrators.
- Hardware:CPU, GPU, and memory subsystems with professional-grade ECC configurations and extended warranty terms. United States federal contractors favor domestic assembly requirements.
- Software:ISV licensing bundles with workstation purchases include Autodesk, Dassault Systèmes, and Foundry product suites.
- Cloud Solutions:Elastic GPU rental models convert capital expenditure to subscription budgets for episodic rendering needs.
- Virtual Workspaces:Teradici and VMware-based remote workstation access extends hardware lifecycle through thin-client endpoints.
Hardware solutions retain the revenue base. Cloud solutions are climbing the fastest as hyperscale providers capture burst workloads.
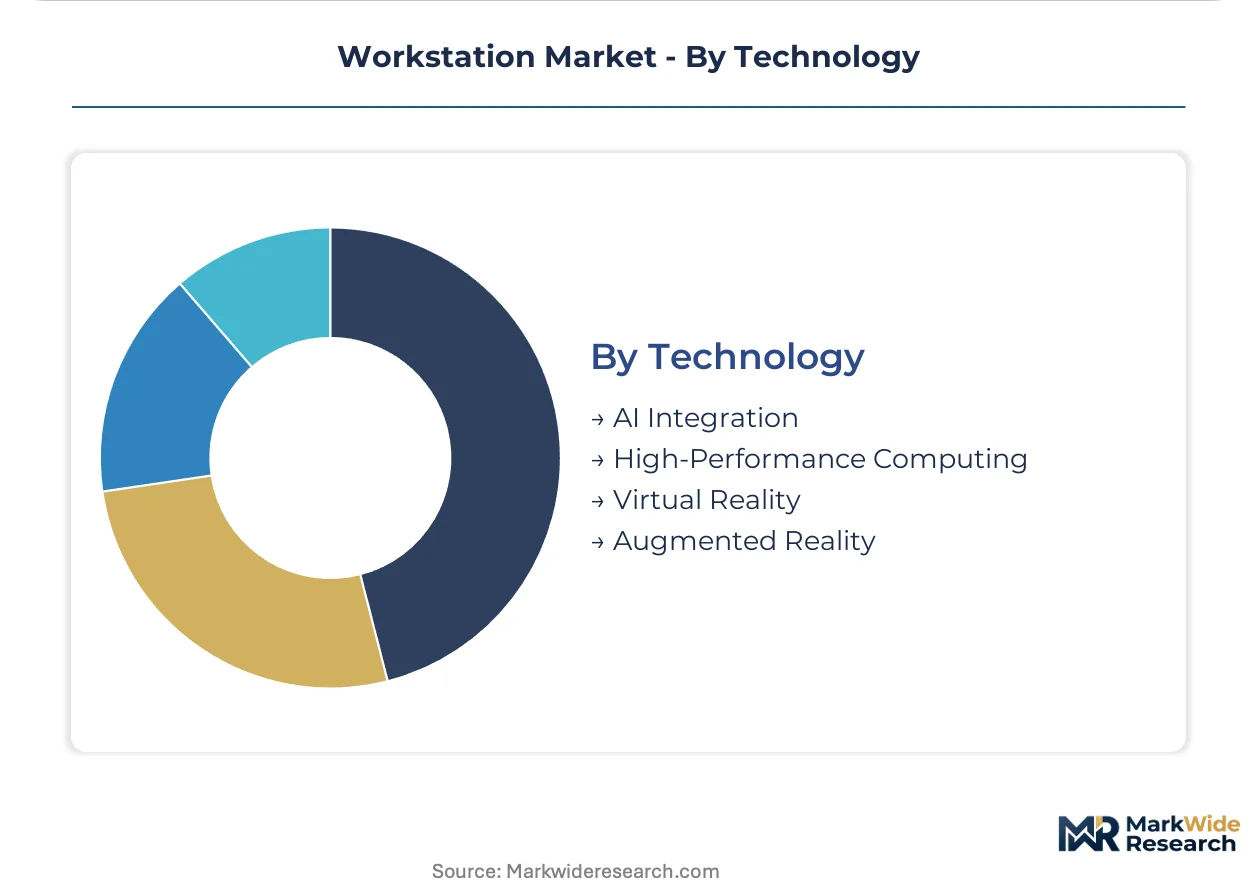
Technology:
AI integration and high-performance computing segments attract premium pricing, while immersive reality deployments remain concentrated in specialized visualization labs.
- AI Integration:Tensor core utilization for model training and inference requires CUDA-optimized software stacks. Financial services firms in the United States deploy these configurations for risk simulation under EU AI Act documentation requirements.
- High-Performance Computing:MPI-optimized multi-node configurations serve German research institutions and national laboratories.
- Virtual Reality:Varjo and HTC Vive Pro tethered configurations demand GPU frame generation consistency for automotive design review.
- Augmented Reality:HoloLens and Magic Leap integration remains nascent, concentrated in Japanese manufacturing training applications.
High-performance computing holds the installed base. AI integration is expanding most quickly as generative workflows penetrate creative software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity, absorbing premium configurations for AI-accelerated workflows. German and Japanese procurement departments enforce stricter total-cost-of-ownership thresholds, extending hardware refresh cycles.
United States
Federal contractors drive volume through certified small-business resellers, consolidating vendor relationships via single-source frameworks. FCC equipment authorization requirements shape electromagnetic compatibility standards for domestic-bound systems. Post-production houses in Los Angeles deploy GPU-dense configurations for real-time 8K virtual production stages.
Germany
Automotive suppliers mandate ISV-certified workstation configurations for CATIA and Siemens NX deployments across engineering workflows. EU CE marking and RoHS substance restrictions govern market access and material composition for solder alloys. Bavarian manufacturing clusters anchor procurement for simulation clusters requiring ECC memory verification.
Japan
Design firms in Tokyo prioritize GPU vRAM minimums for Revit model complexity and ray-traced visualization needs. METI energy efficiency directives tighten standby power and active load consumption thresholds for professional computing equipment. Osaka-based media production studios adopt chiplet-based GPU architectures for memory-scalable rendering pipelines.
India
Domestic creative professionals attract entry-level workstation configurations with professional certification overlays. Production-linked incentives for IT hardware manufacturing draw assembly investments for mobile workstations. Bengaluru technology corridors concentrate procurement for containerized ML pipeline deployments.
United Kingdom
Architectural practices stretch replacement timelines across depreciation schedules, moderating annual refresh velocity. GDPR compliance requirements influence data processing hardware specifications for financial services workloads. London post-production boutiques balance cloud burst capacity against dedicated on-premise render farm investments.
Workstation Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the workstation landscape. The vendor base organizes around three strategic tiers: silicon architects controlling GPU parallel processing, systems integrators bundling hardware with ISV certification breadth, and furniture specialists extending into ergonomic workstation enclosures. Consolidation pressures favor scale-driven procurement frameworks, while modular chassis designs extend service lifecycles across engineering workflows.
Within the silicon architecture tier, NVIDIA anchors datacenter-class visualization deployments through CUDA-optimized software stacks. HP and Dell occupy positions on the systems integration vector, with HP emphasizing enterprise support channels and Dell competing on modular thermal designs. These three exemplify the competitive tension between component margin capture and full-stack solution bundling.
| Leading Market Players |
|---|
| Apple |
| NVIDIA |
| HP |
| Herman Miller |
| Steelcase |
| Dell |
| Asus |
| Vitra |
| Lenovo |
| Others |
Value Chain & Pricing Dynamics
Foundry-scale economies at TSMC and Samsung anchor GPU wafer supply, compressing component costs at volume tiers while concentrating pricing power upstream. This concentration elevates price floors for ECC memory configurations and ISV-certified chassis, forcing procurement departments to absorb premium positioning or accept extended lead times for verified configurations.
Pricing Analysis
EU RoHS substance restrictions dictate the pricing tier structure across solder alloy redesigns and thermal interface material substitutions. Three-tier pricing structure across premium, standard, and economy levels separates ISV-certified ECC configurations from consumer-derived platforms with professional overlays. Cost compression in entry-level tiers is intensifying because India's PLI scheme incentives attract assembly investments for domestic creative professionals. Architectural and engineering firms demonstrate lowest price sensitivity, absorbing premium configurations for AI-accelerated workflows, while entry-level content creators in India face acute budget constraints.
Supply Chain Analysis
Taiwan and South Korea anchor advanced GPU wafer fabrication, while Malaysia and Vietnam concentrate motherboard assembly and chassis manufacturing. Leading-edge process nodes draw from single foundry geography for advanced accelerators, creating allocation bottlenecks during demand surges. Single-source vulnerability in EUV lithography equipment exposes procurement timelines to geopolitical disruption. Distribution runs through certified small-business resellers in United States federal contracting and direct OEM relationships for German automotive supplier frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Verified ISV certification pipelines constitute the scarcest operational asset, with validation queues for new GPU architectures extending deployment timelines and locking out unqualified competitors.
For Market Incumbents: Shield enterprise relationships through exclusive ISV pre-certification programs for chiplet-based GPU architectures before competitor validation completes. Deepen backward integration into liquid cooling subsystems to capture margin pools eroding at the component tier. Cloud rendering substitution from hyperscale providers threatens dedicated on-premise hardware volumes. For New Entrants and Emerging Players: Fast-track METI energy efficiency pre-certification for mobile workstation SKUs bound for Japanese enterprise procurement, bypassing incumbent validation backlogs. White-space concentrates in India's PLI scheme assembly investments for domestic creative professionals. Entry-level gaming workstations with professional certification overlays offer the most penetrable wedge against established tier-1 vendors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device-as-a-service providers bundling hardware, support, and cloud burst capacity for architectural and engineering firms. Long-term viability favors systems integrators consolidating vendor relationships through single-source frameworks over pure-play component suppliers. Monitor ISV certification queue lengths as the inflection indicator for vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| ISV Certification Pre-Investment | Adobe and Autodesk validation queues lock out competitors for 6-12 month windows. |
| Backward Integration into Cooling | Liquid thermal subsystem capture defends margins against commoditized GPU supply. |
| Device-as-a-Service Launch | Subscription conversion attracts capital-constrained German architectural practices. |
| India PLI Scheme Assembly | Domestic production incentives reduce landed cost for entry-tier mobile workstations. |
| Chiplet GPU Architecture Adoption | Modular compute tiles enable memory-scalable configurations for Japanese media studios. |
Study Parameters
Operator-level perspectives from workstation procurement managers, ISV certification engineers, thermal design leads, and hyperscale cloud rendering specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, hyperscaler capex disclosures, and customs/trade data for GPU and memory component flows. Bottom-up unit economics triangulated against top-down market sizing across hardware, software, cloud solutions, and virtual workspace deployment models.
Sensitivity analysis tested forecast outputs against variable GPU supply allocation scenarios, ISV certification timeline compression, and cloud substitution elasticity. Segmentation dimensions modeled include product form factor, end-user vertical, solution type, and technology integration level across the projection horizon. CAGRs derived from installed base depreciation cycles, AI workload penetration curves, and regional procurement pattern shifts. Chiplet GPU adoption rates and METI compliance cost pass-through served as workstation-specific forecast inputs.
Decision-makers should treat outputs as directional under stable foundry capacity allocation and unaltered EU AI Act documentation requirements; material deviation would warrant model refresh. Specific risks include single-source GPU fabrication disruption, RoHS substance substitution cost spikes, and hyperscale cloud rendering capture acceleration. Recalibration cycles align with material shifts in ISV certification queue dynamics and regional production incentive scheme revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Automotive Diode Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Broadcasting Equipment Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
High Current Springs Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market