
 Global Volt/VAR Management Market | 2026-2036
Global Volt/VAR Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Volt/VAR Management Market Intelligence
The direct sales channel from large equipment manufacturers to utility customers is narrowing as system integrators and specialized software vendors gain influence. Schneider Electric leverages its EcoStruxure platform to integrate software and hardware, creating a sticky ecosystem for grid management. Siemens AG competes on the strength of its comprehensive grid automation portfolio for transmission and distribution networks. Eaton specializes in power quality solutions, particularly capacitor banks for industrial and commercial end-users.
Volt/VAR management is the automated control of voltage levels and reactive power across an electrical distribution network. Systems utilize equipment like static VAR compensators and synchronous condensers to keep voltage within specific operational bands, such as the ANSI C84.1 standard in the US. Their core function is enhancing power quality and minimizing line losses. Within the technology segment, automated solutions are displacing older analog controls, while utilities remain the dominant end-user for grid stability applications.
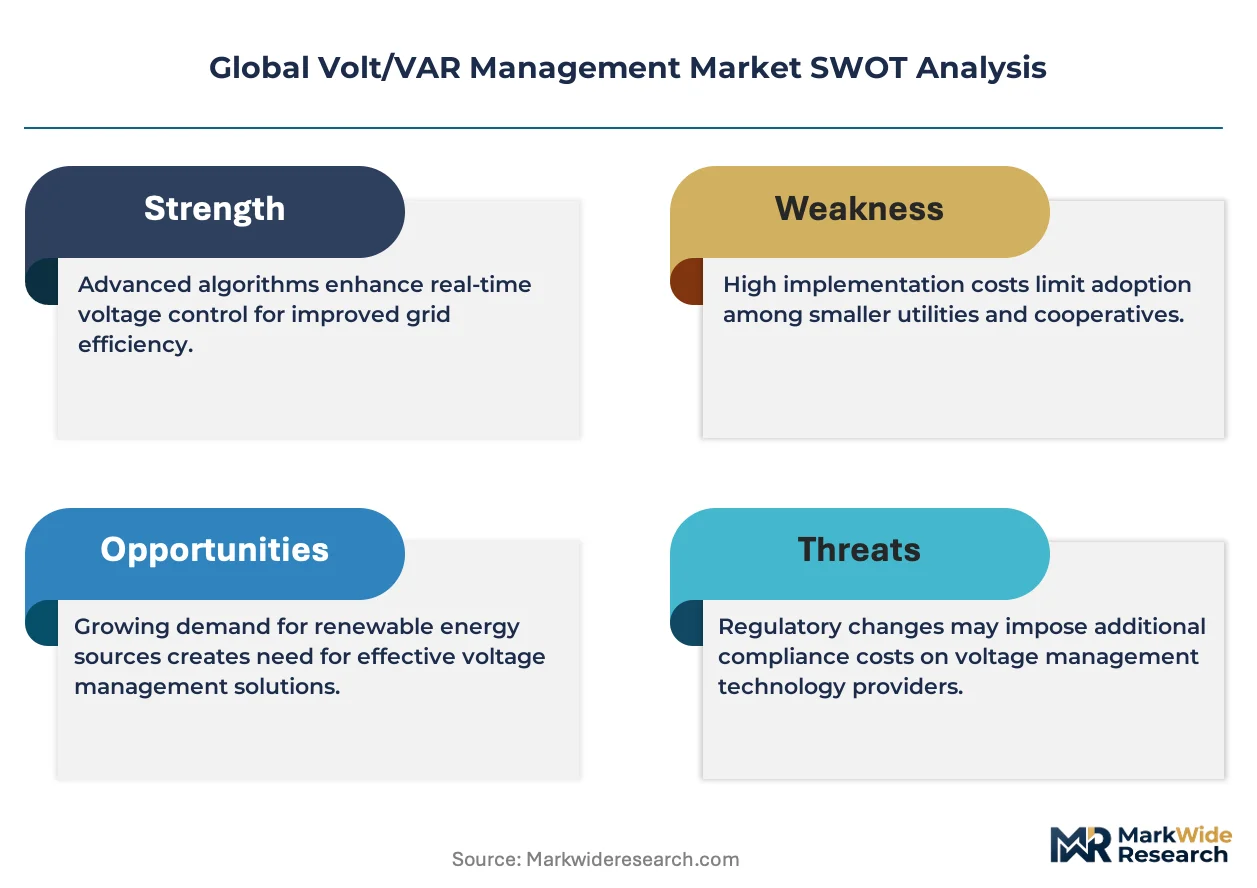
Regulatory frameworks are a significant catalyst for market development. In the United States, FERC Order 2222 encourages distributed energy resource aggregation, requiring advanced voltage management. Concurrently, the EU Green Deal and China's 'dual carbon goals' mandate extensive grid upgrades to support massive renewable integration. A utility's ability to choose between centralized and decentralized control architectures will define its operational efficiency and readiness for a decarbonized grid.
Market Dynamics
The central structural force shaping the Volt/VAR management market is the imperative for grid modernization to accommodate high-penetration renewable energy sources. This transition from centralized, one-way power flow to a decentralized, bidirectional network necessitates advanced, real-time voltage control systems.
Growth Catalysts
- Regulatory Mandates:In the United States, FERC Order 2222 encourages the aggregation of distributed energy resources, which requires more sophisticated, automated voltage management to maintain grid stability and power quality.
- Technology Adoption:The proliferation of advanced distribution management systems (ADMS) across utility networks creates a direct need for integrated Volt/VAR solutions that can provide real-time data and automated control actions.
- Grid Modernization Programs:National initiatives, such as those in Germany and India, aimed at upgrading electrical grids to support massive renewable integration and reduce line losses, are a primary driver for investment in this technology.
Market Restraints
- High Capital Costs:The significant upfront investment required for advanced components like static VAR compensators (SVCs) and synchronous condensers can deter smaller utilities or those with constrained capital budgets from adoption.
- Legacy System Integration:Integrating modern digital Volt/VAR systems with older grid infrastructure, which often lacks the necessary communication protocols and sensor density, presents significant technical and financial hurdles for utilities.
- Supply Chain Concentration:The market for critical high-voltage components is dominated by a few large multinational corporations, creating potential for supply bottlenecks and limited pricing power for utility customers.
Strategic Opportunities
- Microgrid Applications:Developing tailored Volt/VAR management solutions for campus, industrial, and community microgrids represents a significant growth area beyond traditional utility-scale deployments, enhancing local energy resilience.
- AI and Machine Learning Integration:Incorporating predictive analytics into control systems allows for proactive voltage management, anticipating fluctuations from renewable sources or demand shifts before they impact grid stability.
- Decentralized Control Architectures:The development of distributed intelligence, where control decisions are made locally by smart inverters and edge devices, offers a new operational model for managing complex distribution networks with high DER penetration.
Industry Challenges
- Vendor Interoperability:A lack of universal communication and data standards creates significant challenges in ensuring that software and hardware from different vendors can operate together seamlessly within a single control system.
- Specialized Skills Gap:Utilities face a shortage of power systems engineers and data scientists with the hybrid expertise required to design, deploy, and manage sophisticated, software-defined grid control platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Volt/VAR Management Market |
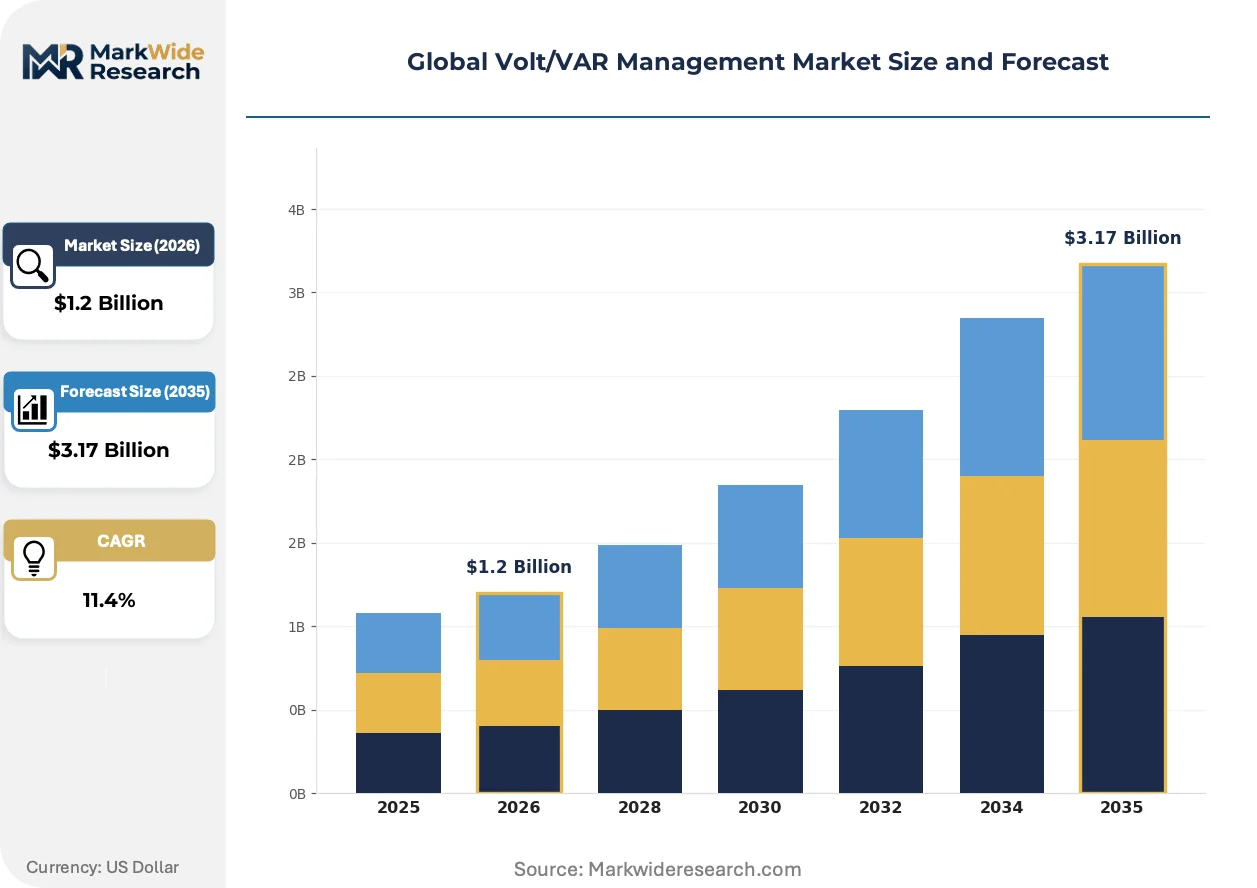
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static VAR Compensators, Dynamic VAR Compensators, Capacitor Banks, Synchronous Condensers End User: Utilities, Industrial Sector, Commercial Buildings, Renewable Energy Facilities Technology: Analog Control, Digital Control, Hybrid Systems, Automated Solutions Application: Voltage Regulation, Power Quality Improvement, Load Shaping, Grid Stability |
| Companies Covered | GE Vernova, ABB, Eaton, Schneider Electric, Siemens AG, Hitachi Energy, S&C Electric Company, Landis+Gyr, Beckwith Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Volt/VAR Management Market Strategic Shifts & Innovations
The market is fundamentally transforming from passive, localized voltage correction to active, network-wide optimization. This evolution is driven by the necessity of managing bidirectional power flows from distributed resources and improving overall grid efficiency through intelligent automation.
Automated Volt/VAR control technology delivers real-time adjustments to maintain voltage levels and manage reactive power across the distribution network. Utilities are adopting these systems at an accelerated pace to handle the grid instability caused by large-scale solar and wind power integration. The market is migrating from older, electromechanical devices with localized logic to centralized, software-driven platforms that provide network-wide visibility and coordinated control.
The EU Green Deal creates a powerful regulatory impetus for grid modernization across member states. This policy framework compels utilities to make substantial investments in technologies that support a decarbonized energy system, including advanced voltage management. Transmission and Distribution System Operators are most affected, requiring significant upgrades to their networks to accommodate variable renewable energy while adhering to strict stability standards set by bodies like ENTSO-E.
A clear shift in buying behavior sees utilities increasingly partnering with specialized system integrators and software vendors. This pattern disrupts the traditional direct-sales channel dominated by large electrical equipment manufacturers, creating a more layered and service-oriented ecosystem. The trend is most pronounced in North America and Europe, where complex grid modernization projects demand a combination of multi-vendor hardware and sophisticated software integration expertise.
Global Volt/VAR Management Market Segmentation
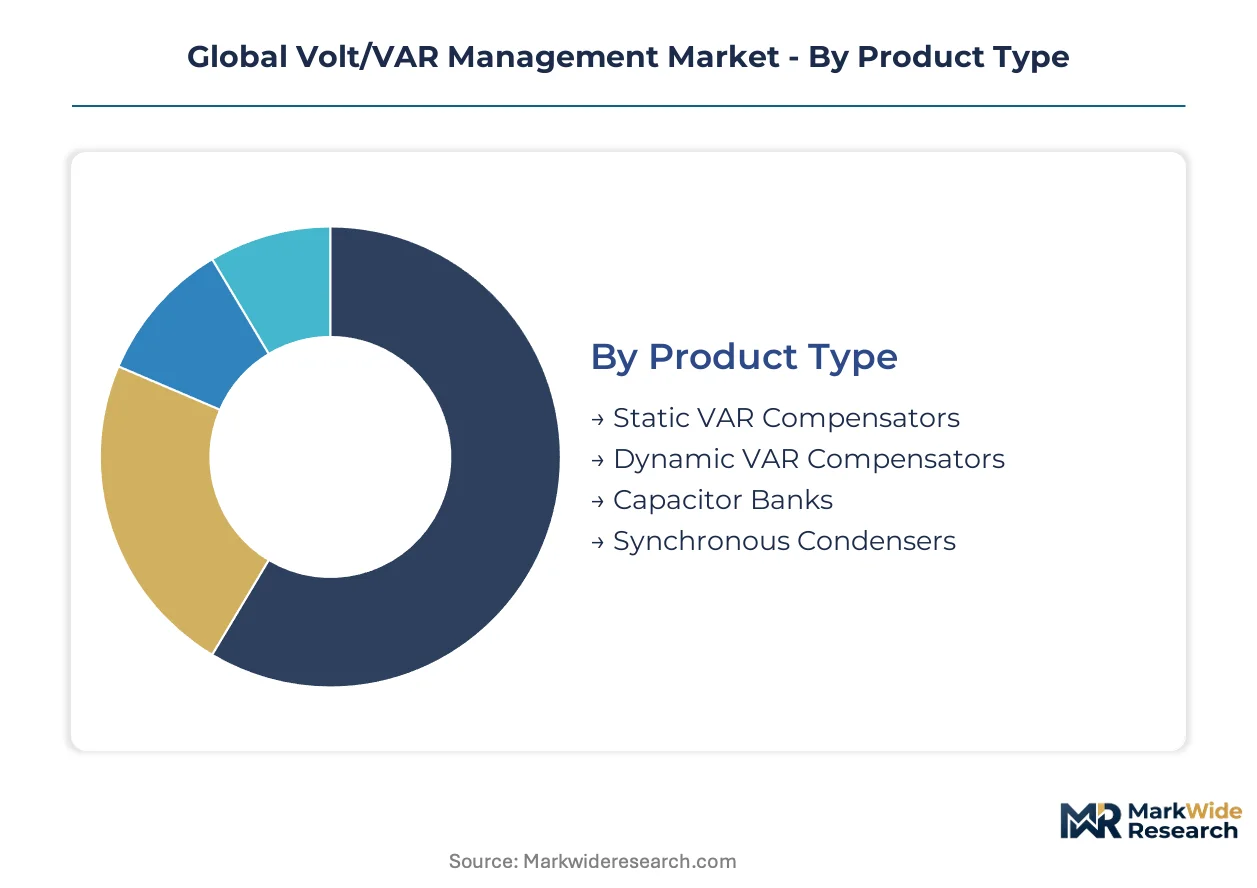
The Volt/VAR management market segmentation highlights the diverse solutions addressing grid stability and power quality. Categorization by product type, end-user, technology, and application reveals distinct operational requirements. This granular view helps understand specific demand patterns across the electrical network.
Product Type:
Product types in Volt/VAR management exhibit varying turnover rates, from rapidly evolving digital solutions to long-lifecycle electromechanical components.
- Static VAR Compensators:These devices use thyristor-controlled reactors and capacitor banks to provide rapid reactive power compensation. Demand concentrates in transmission and sub-transmission networks in Germany and India, driven by the need for flexible grid support.
- Dynamic VAR Compensators:Utilized for high-speed reactive power control, these systems leverage power electronics like STATCOMs for precise voltage regulation. Utilities in the United States increasingly adopt them to manage intermittent renewable energy sources and ensure grid stability.
- Capacitor Banks:These are cost-effective solutions for reactive power compensation and voltage support, primarily used in distribution networks and industrial facilities.
- Synchronous Condensers:Rotating electrical machines provide inertia and reactive power, often deployed in areas with high renewable penetration to maintain grid strength.
Capacitor Banks anchor the volume base while Dynamic VAR Compensators gain share at the steepest rate.
End User:
End-user segments for Volt/VAR solutions span from extensive grid-wide optimization to localized power quality enhancement.
- Utilities:These operators of transmission and distribution networks are the primary consumers, deploying Volt/VAR systems for system-wide voltage control and loss reduction. Grid modernization initiatives in the United States and EU Green Deal mandates drive utility investment.
- Renewable Energy Facilities:Solar farms and wind power plants require specialized Volt/VAR management to maintain grid code compliance and inject stable power. Demand is accelerating in countries like India, supporting extensive renewable integration.
- Industrial Sector:Manufacturing plants and heavy industries utilize Volt/VAR solutions to improve power quality, reduce energy costs, and protect sensitive equipment.
- Commercial Buildings:Office complexes, data centers, and large retail establishments deploy localized systems to ensure stable power for critical operations and energy efficiency.
Utilities represent the largest deployment segment, with renewable energy facilities showing significant expansion.
Technology:
Technology segments reflect a continuum from established, mature control methods to advanced, rapidly developing automation platforms.
- Automated Solutions:These advanced systems integrate real-time data from across the grid with sophisticated algorithms for proactive voltage and reactive power control. Adoption is driven by the proliferation of ADMS platforms in Europe and North America.
- Digital Control:Modern digital controllers replace older analog systems, offering enhanced precision, remote monitoring capabilities, and integration with SCADA systems. Utilities globally are transitioning to these solutions for improved network management.
- Analog Control:Older, electromechanical systems provide basic, localized voltage and reactive power correction, still present in legacy grid infrastructure.
- Hybrid Systems:These solutions combine elements of both analog and digital control, often representing transitional upgrades in utility networks.
Automated Solutions are driving system intelligence, moving beyond traditional analog deployments.
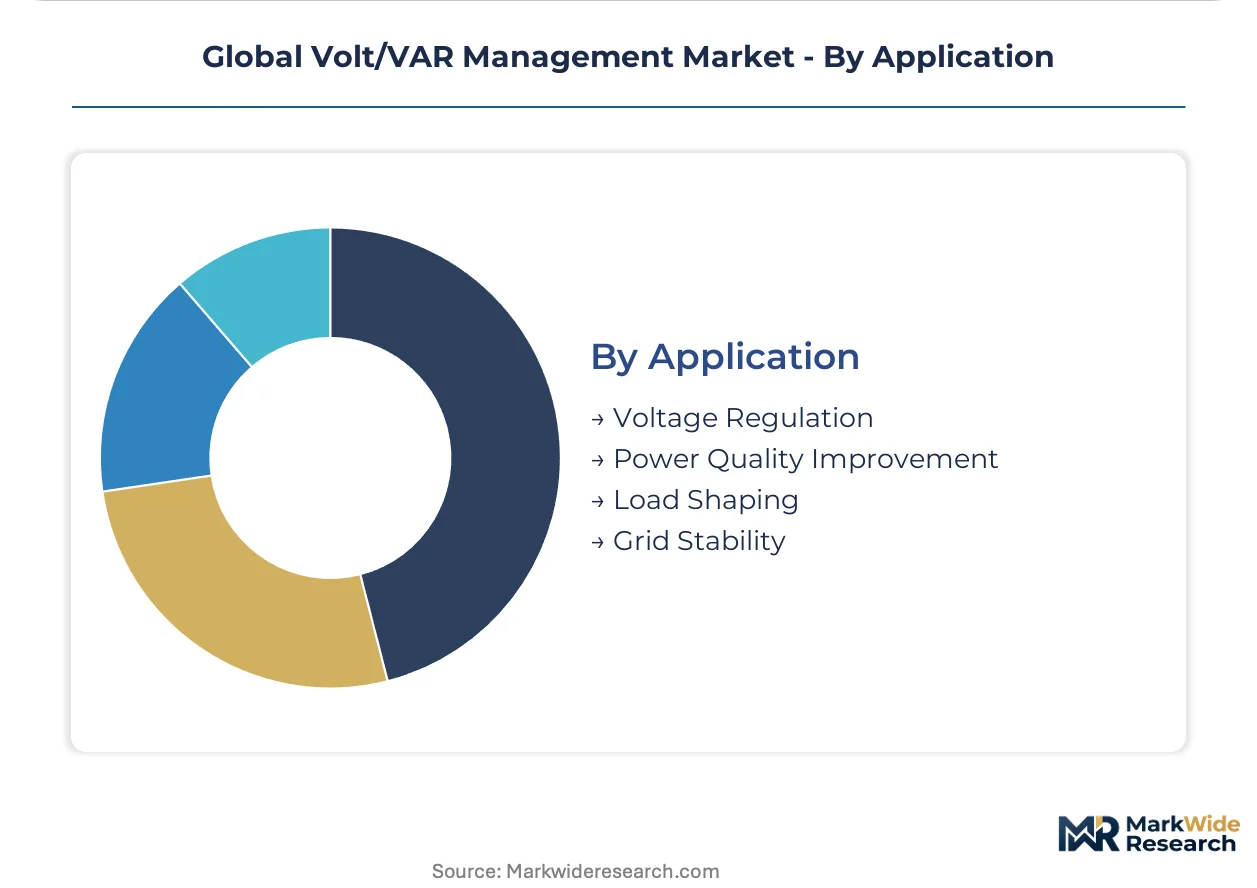
Application:
Applications for Volt/VAR management range from fundamental grid stability functions to sophisticated power quality optimization.
- Voltage Regulation:This core application ensures that voltage levels remain within specified operational bands across the distribution network. FERC Order 2222 in the US mandates robust voltage regulation for distributed energy resource integration.
- Grid Stability:Volt/VAR systems contribute to overall grid resilience by managing reactive power, preventing blackouts, and supporting system inertia. China's 'dual carbon goals' necessitate significant investment in grid stability technologies.
- Power Quality Improvement:This application addresses issues like sags, swells, and harmonics, ensuring reliable and clean power delivery to sensitive loads.
- Load Shaping:Volt/VAR management can indirectly support load shaping by optimizing reactive power flow, influencing apparent power demand and reducing peak loads.
Voltage Regulation forms the foundational requirement, with Grid Stability becoming increasingly critical for modern networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vast global electrical transmission and distribution networks underwrite diverse regional demand for Volt/VAR management solutions. Grid modernization, driven by renewable integration and distributed energy resources, accelerates investments. These efforts ensure grid stability and power quality.
United States
Grid modernization efforts in the United States drive significant demand for dynamic VAR compensators. FERC Order 2222 encourages distributed energy resource aggregation, requiring advanced voltage management. Utilities in California are heavily investing in these systems to integrate large-scale solar power and enhance grid resilience.
Germany
Europe's largest economy, Germany, requires sophisticated Volt/VAR solutions to manage high renewable energy penetration. The EU Green Deal mandates extensive grid upgrades, compelling utilities to invest in advanced voltage management. Northern German states, with their numerous wind farms, are particularly active in deploying static VAR compensators.
India
Massive renewable energy targets in India fuel substantial demand for Volt/VAR management, particularly in solar and wind power integration. The country's Central Electricity Authority (CEA) mandates grid code compliance for renewable energy facilities. States like Gujarat and Rajasthan are seeing significant deployments of synchronous condensers to maintain grid strength.
China
Beijing's ambitious decarbonization goals necessitate advanced Volt/VAR technologies for grid stability across China. The nation's 'dual carbon goals' compel extensive investments in smart grid infrastructure. The Yangtze River Delta region, with its dense industrial load and renewable integration, is a key area for automated solutions.
Australia
High solar penetration and long transmission lines in Australia create substantial demand for voltage regulation solutions. The Australian Energy Market Operator (AEMO) implements policies to ensure grid stability with intermittent renewables. South Australia, a leader in renewable energy, is a critical testbed for decentralized control architectures.
Global Volt/VAR Management Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical hardware. The Volt/VAR management market exhibits a tiered structure, with large multinational conglomerates offering comprehensive grid solutions alongside specialized software and hardware providers. Key strategic archetypes include integrated solution providers, pure-play software vendors, and niche component manufacturers. Dominant competitive moves involve strategic partnerships for software-hardware integration and portfolio diversification into advanced automation platforms.
Integrated solution providers such as GE Vernova and Siemens AG exemplify the comprehensive approach, offering extensive portfolios across transmission and distribution. Schneider Electric, another global entity, represents a strong ecosystem play, leveraging its platform for grid management. These multinational corporations often anchor the market's premium segment, providing end-to-end solutions for complex grid modernization projects. Their offerings span from core hardware to sophisticated software applications, addressing diverse utility requirements for voltage and reactive power control.
| Leading Market Players |
|---|
| GE Vernova |
| ABB |
| Eaton |
| Schneider Electric |
| Siemens AG |
| Hitachi Energy |
| S&C Electric Company |
| Landis+Gyr |
| Beckwith Electric |
| Others |
Cost & Logistics Intelligence
Concentration in critical high-voltage component manufacturing by a few multinational corporations directly influences margin pools for system integrators and specialized software vendors downstream. This structural dynamic shapes both pricing power and supply chain resilience within the Volt/VAR management market.
Pricing Analysis
Tiered pricing separates premium integrated solutions from standard component sales and economy-level analog controls. Price differentiation stems from the complexity of software integration and the level of after-sales service offered by vendors. Pricing pressure stems from increased competition among system integrators vying for large utility contracts. Utilities represent the most price-sensitive segment for basic components, while those requiring complex grid modernization projects are less sensitive to advanced automated solution costs.
Supply Chain Analysis
Extended payment terms and specialized supply-chain finance facilities are common, particularly for large-scale utility projects. Geographic supply concentration for power electronics and high-voltage components largely resides in Germany, China, and Japan. Raw material dependencies include rare earth elements for advanced power electronics and copper for conductors. Single-source vulnerability for highly specialized components represents a key structural risk. Distribution runs through a hybrid model, combining direct sales from large equipment manufacturers with specialized system integrators for complex projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's evolution is constrained by a significant skill gap, specifically in power systems engineers and data scientists capable of managing sophisticated, software-defined grid control platforms.
For Market Incumbents: Insulate core market share by investing heavily in the integration of AI and machine learning capabilities into existing EcoStruxure and comprehensive grid automation platforms. This defends against the threat posed by agile specialized software vendors. Leverage existing customer relationships to offer comprehensive platform integration as a key lever for long-term contracts. Strategic partnerships with niche AI firms can accelerate product development.
For New Entrants and Emerging Players: Pursue white-space opportunities in microgrid applications and decentralized control architectures, which remain underpenetrated by traditional players. The industrial and commercial sectors represent a highly penetrable segment for localized Volt/VAR solutions. A go-to-market angle focused on predictive analytics and edge computing for real-time, autonomous voltage management offers a distinct competitive advantage.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the automated solutions sub-segment due to advanced power electronics and software development costs. The long-term viability of Volt/VAR management is strong, driven by decarbonization mandates and grid modernization imperatives. Acquire specialized software vendors or system integrators with strong intellectual property in AI-driven grid optimization. A signal to watch is the increasing regulatory clarity around distributed energy resource aggregation and market participation rules.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Enhances interoperability between diverse hardware and software components for utility customers. |
| AI/ML Product Development | Enables proactive voltage management and anticipates grid fluctuations from renewable sources. |
| Strategic Partnership | Combines hardware manufacturing strength with specialized software integration expertise. |
| Microgrid Solution Expansion | Addresses growing demand for local energy resilience in campus and industrial settings. |
| Decentralized Control Architecture | Supports efficient management of complex distribution networks with high DER penetration. |
Research Approach
The analysis maps Volt/VAR product types, end-user segments, and technology applications, each validated through primary interviews with utility planning officers, renewable energy project developers, and system integrators. Secondary data sources, including FERC filings, EU Green Deal reports, and Central Electricity Authority mandates, supported bottom-up and top-down triangulation. This ensured comprehensive coverage and cross-validation of market insights.
The forecast framework assumes continued regulatory stability and consistent technology adoption rates across the modeling period. Segmentation dimensions modeled include product type, end-user, technology, application, and regional market maturity. Compound annual growth rates were derived from historical data trends and projected investment patterns. Industry-specific forecast inputs include national renewable energy installation targets and grid modernization investment plans.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large equipment manufacturers or specialized software vendors would shift outcomes. The analysis reflects assumptions regarding the pace of grid modernization and regulatory enforcement. Unforeseen regulatory changes, major supply chain disruptions for critical components, or rapid technological obsolescence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
AV Surge Protectors Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Automotive Diode Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Electronic Load Market