
 High Current Springs Market | 2026-2036
High Current Springs Market Size, Share, and Industry Trends Forecast 2026-2036
High Current Springs Market Analytics
Copper-nickel-silicon alloy formulations is rewriting material selection protocols for high-current contact applications. NHK Spring leverages proprietary heat-treatment processes to sustain performance thresholds in EV inverter assemblies. Mubea anchors European supply through integrated coil-to-spring manufacturing in Germany. Barnes Group competes on aerospace qualification breadth, occupying positions across multiple OEM approved-vendor lists.
High current springs are precision-engineered elastic components manufactured from conductive alloys, typically exhibiting resistivity below 5 micro-ohm-centimeter and force ratings exceeding 500 Newtons to maintain electrical continuity under thermal and mechanical load. Compression springs dominate automotive busbar assemblies where space constraints and normal-force consistency determine contact reliability. Flat springs represent the fastest-growing configuration in solid-state circuit breaker designs, while alloy steel retains margin concentration in heavy machinery retrofit channels.
FDA oversight of diagnostic imaging equipment shapes spring material biocompatibility requirements for MRI coil manufacturers. EPA REACH-aligned substance restrictions in Europe and California compel copper alloy suppliers to document full material declarations. NHTSA crash-safety protocols for high-voltage enclosures drive force-retention testing standards. Stakeholders must monitor how battery-electric commercial vehicle platforms recalibrate current-density specifications against existing spring fatigue models.
Market Dynamics
Powertrain electrification is forcing copper alloy suppliers to recalibrate fatigue-life specifications against current-density thresholds that legacy spring designs cannot sustain. Tier-one automotive procurement teams now mandate ISO 9001 certification alongside material traceability documentation as non-negotiable entry criteria.
Growth Catalysts
- EV Inverter Assemblies:Battery-electric commercial vehicle platforms require high-current springs maintaining contact force above 500 Newtons across thermal cycling ranges that exceed internal combustion engine specifications.
- EPA REACH-Aligned Substance Restrictions:California and European regulators compel full material declarations from copper alloy suppliers, accelerating substitution of legacy cadmium-bearing formulations in diagnostic imaging equipment.
- Solid-State Circuit Breaker Designs:Flat spring configurations are capturing design wins in next-generation electrical protection systems where space constraints and arc-quenching performance determine component selection.
Market Restraints
- Copper Price Volatility:Raw material cost swings in copper-nickel-silium alloy feedstock compress margin predictability for precision spring manufacturers serving long-term automotive contracts.
- German Supply Concentration:Integrated coil-to-spring production capacity clusters in Baden-Württemberg and Bavaria, creating geographic vulnerability to regional energy cost spikes or logistics disruptions.
- Alloy Steel Substitution:Heavy machinery retrofit channels retain margin concentration in lower-conductivity steel springs where current-density requirements remain below electrification thresholds.
Strategic Opportunities
- Japan Medical Imaging Expansion:MRI coil manufacturers under PMDA oversight seek biocompatible copper alloy springs with resistivity below 5 micro-ohm-centimeter for next-generation diagnostic platforms.
- US NHTSA High-Voltage Safety Mandates:Crash-safety protocols for battery enclosures create certified-supplier scarcity that qualified spring manufacturers can exploit for multi-year OEM contracts.
- Additive Manufacturing Convergence:Hybrid production combining conventional coil winding with selective laser melting enables topology-optimized spring geometries for aerospace busbar applications.
Industry Challenges
- Heat-Treatment Expertise Scarcity:Proprietary precipitation-hardening processes for copper-nickel-silicon alloys require metallurgists with EV-specific thermal cycling knowledge that traditional spring engineers lack.
- Multi-Standard Certification Timelines:Simultaneous pursuit of ISO 9001, IATF 16949, and aerospace AS9100 approvals extends qualification cycles beyond 18 months for tier-two suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Current Springs Market |
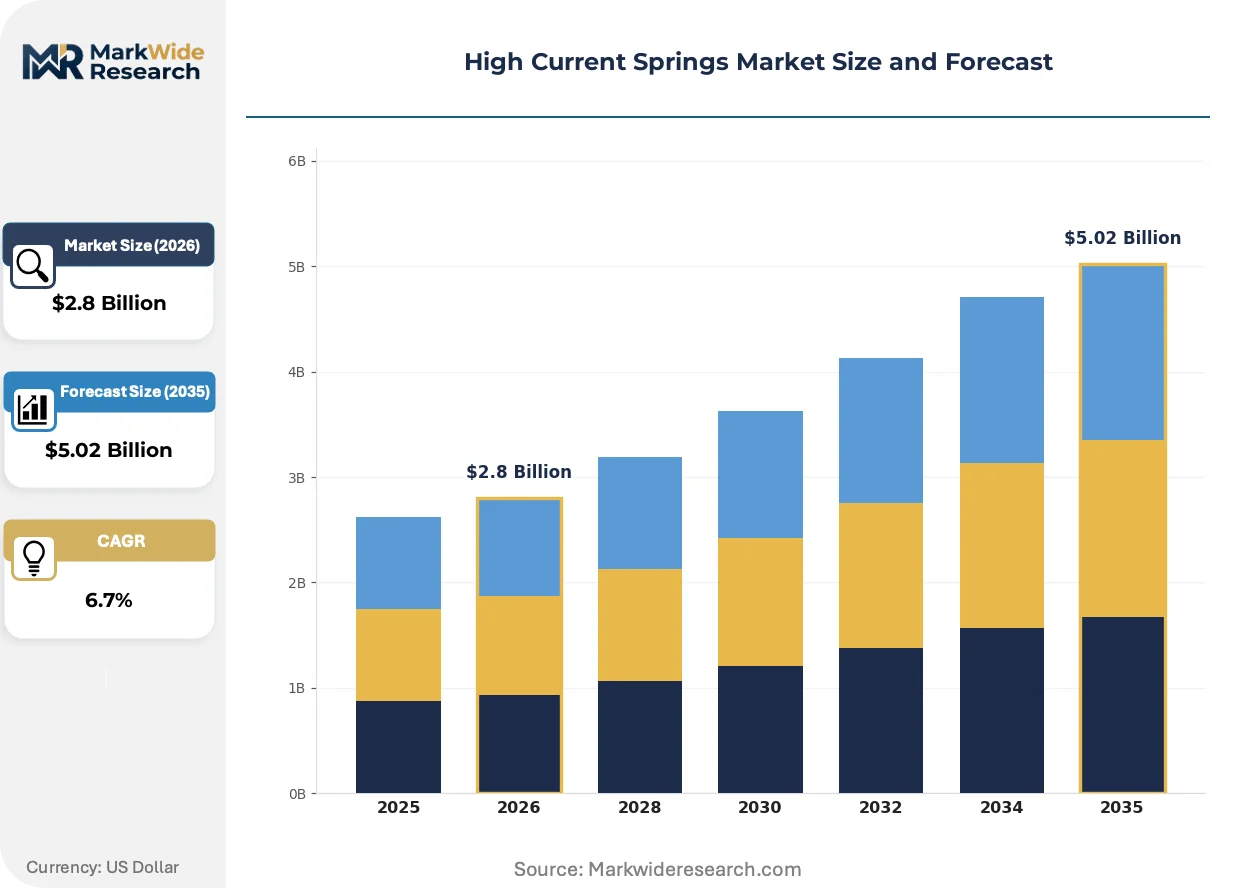
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tension Springs, Compression Springs, Extension Springs, Flat Springs Material: Carbon Steel, Stainless Steel, Alloy Steel, Copper Application: Automotive, Aerospace, Electrical Equipment, Heavy Machinery End User: Manufacturers, OEMs, Maintenance Providers, Aftermarket Suppliers |
| Companies Covered | Barnes Group, NHK Spring, Mubea, Thyssenkrupp, Associated Spring, Lee Spring Company, Bal Seal Engineering, GALA GROUP, Hendrickson USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Current Springs Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine performance benchmarks for conductive elastic components. Electrification is compressing design cycles while expanding the addressable application set beyond traditional automotive and industrial domains.
Copper-nickel-silicon-chromium formulations is hybridizing the trade-off between electrical conductivity and mechanical strength that previously forced designers to choose between pure copper and beryllium copper alloys. EV inverter manufacturers in Germany and Japan are adopting these formulations at accelerated qualification paces. The technology is hybridizing procurement specifications across tier-one supplier bases that previously maintained separate material standards for automotive and aerospace channels.
REACH substance restrictions and California Proposition 65 enforcement are eliminating cadmium and lead-bearing spring coatings from approved material lists. Full material declaration requirements now extend through tier-three suppliers in European medical device and automotive supply chains. MRI coil manufacturers face the most acute compliance pressure, driving substitution toward nickel-silicon alloys with documented biocompatibility under FDA 21 CFR oversight.
Consolidated procurement functions at major automotive OEMs are compressing approved-vendor lists and demanding lifecycle cost guarantees rather than unit-price contracts. Tier-one suppliers are responding by qualifying dual-source spring manufacturers with identical metallurgical capabilities. This concentration is most visible in United States-based EV powertrain sourcing, where single-source risk mitigation now outweighs historical price optimization criteria.
High Current Springs Market Segmentation
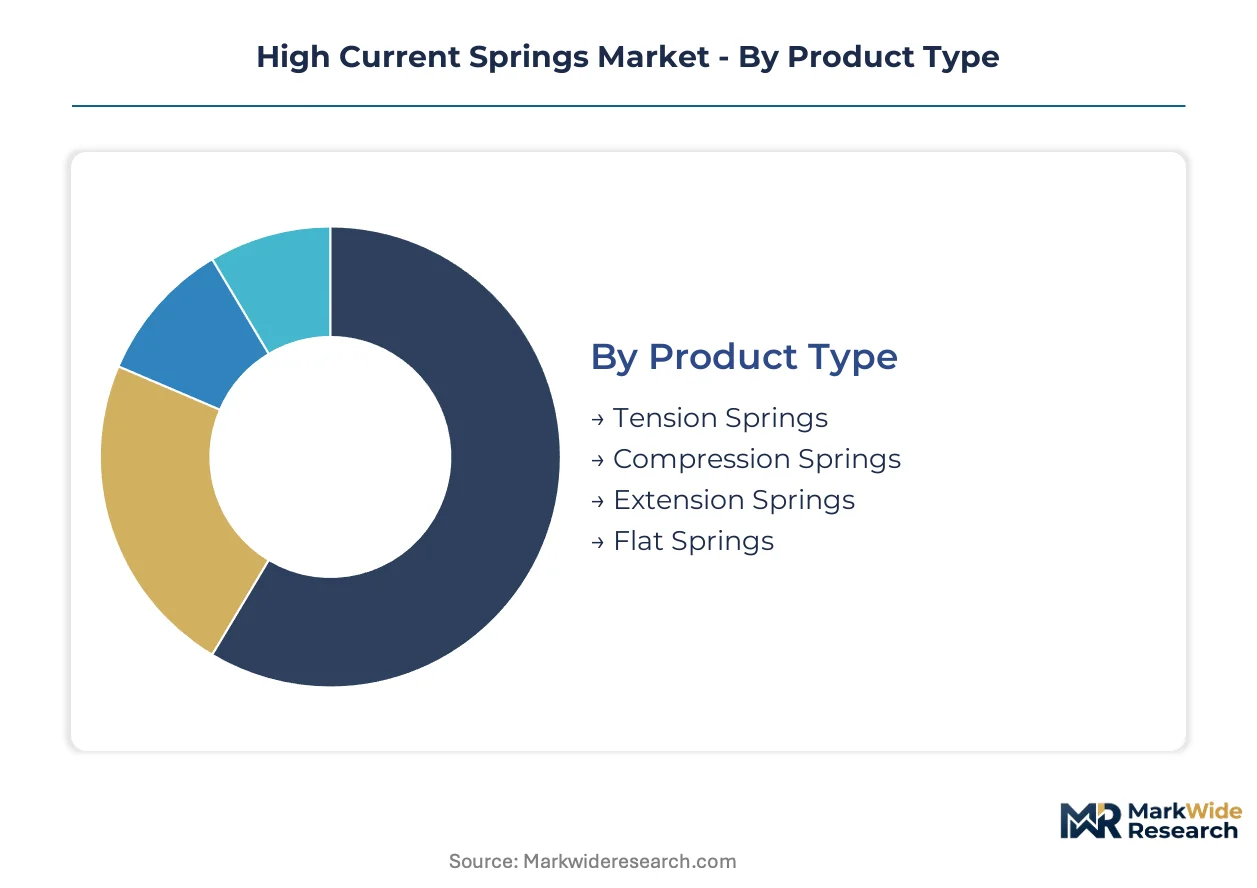
High current springs serve divergent performance regimes across electrification and legacy mechanical applications. Segment boundaries reflect material conductivity thresholds, force-retention specifications, and certification requirements that separate automotive EV procurement from industrial retrofit channels.
Product Type:
Mature coil configurations dominate established automotive and industrial channels, while emerging flat geometries capture design wins in next-generation electrical protection systems.
- Compression Springs:Helical coils engineered for axial load bearing sustain normal forces exceeding 500 Newtons in EV busbar assemblies. German tier-one suppliers specify these for battery-electric commercial vehicle inverters where thermal cycling resistance determines warranty terms.
- Flat Springs:Rectangular or contoured strip configurations integrate into solid-state circuit breaker housings with severe space constraints. Japan-based electrical equipment manufacturers are adopting these for arc-quenching applications where traditional coil geometries fail.
- Tension Springs:Helical designs with hooked or looped terminations maintain cable tension in heavy machinery power distribution systems.
- Extension Springs:Close-wound coils with external hooks provide return-force functionality in aerospace actuation mechanisms.
Compression springs retain volume leadership; flat springs hold the steepest expansion curve.
Material:
Cost tiers separate commodity steel feedstock from premium copper alloys with documented traceability.
- Copper:Copper-nickel-silicon formulations achieve resistivity below 5 micro-ohm-centimeter while sustaining precipitation-hardened yield strength. EV powertrain manufacturers in Germany and Japan mandate these alloys for high-voltage contact applications under ISO 9001 traceability protocols.
- Alloy Steel:Chromium-vanadium and silicon-manganese grades deliver fatigue life in heavy machinery retrofit channels where current-density requirements remain below electrification thresholds. United States-based maintenance providers specify these for cost-sensitive industrial rebuild programs.
- Carbon Steel:Plain or lightly alloyed grades serve general-purpose mechanical applications with minimal conductivity requirements.
- Stainless Steel:Austenitic and martensitic grades provide corrosion resistance in marine or chemical exposure environments.
Copper commands premium positioning; alloy steel maintains volume concentration in legacy channels.
Application:
Customer type segmentation separates specification-driven OEM procurement from price-sensitive aftermarket channels.
- Automotive:Battery-electric and hybrid powertrain electrification drives specification intensity for springs maintaining contact force across thermal cycling ranges exceeding internal combustion engine norms. NHTSA crash-safety protocols for high-voltage enclosures create certified-supplier scarcity.
- Electrical Equipment:Circuit breaker, switchgear, and transformer manufacturers specify flat spring configurations for arc-quenching and current-interruption functions. REACH-aligned substance restrictions compel full material declarations through tier-three suppliers.
- Aerospace:AS9100 qualification requirements and force-retention testing at temperature extremes govern procurement for busbar and actuation systems.
- Heavy Machinery:Retrofit and rebuild channels prioritize unit economics over conductivity specifications in lower-current industrial applications.
Automotive commands specification intensity; electrical equipment shows the steepest technology-driven substitution.
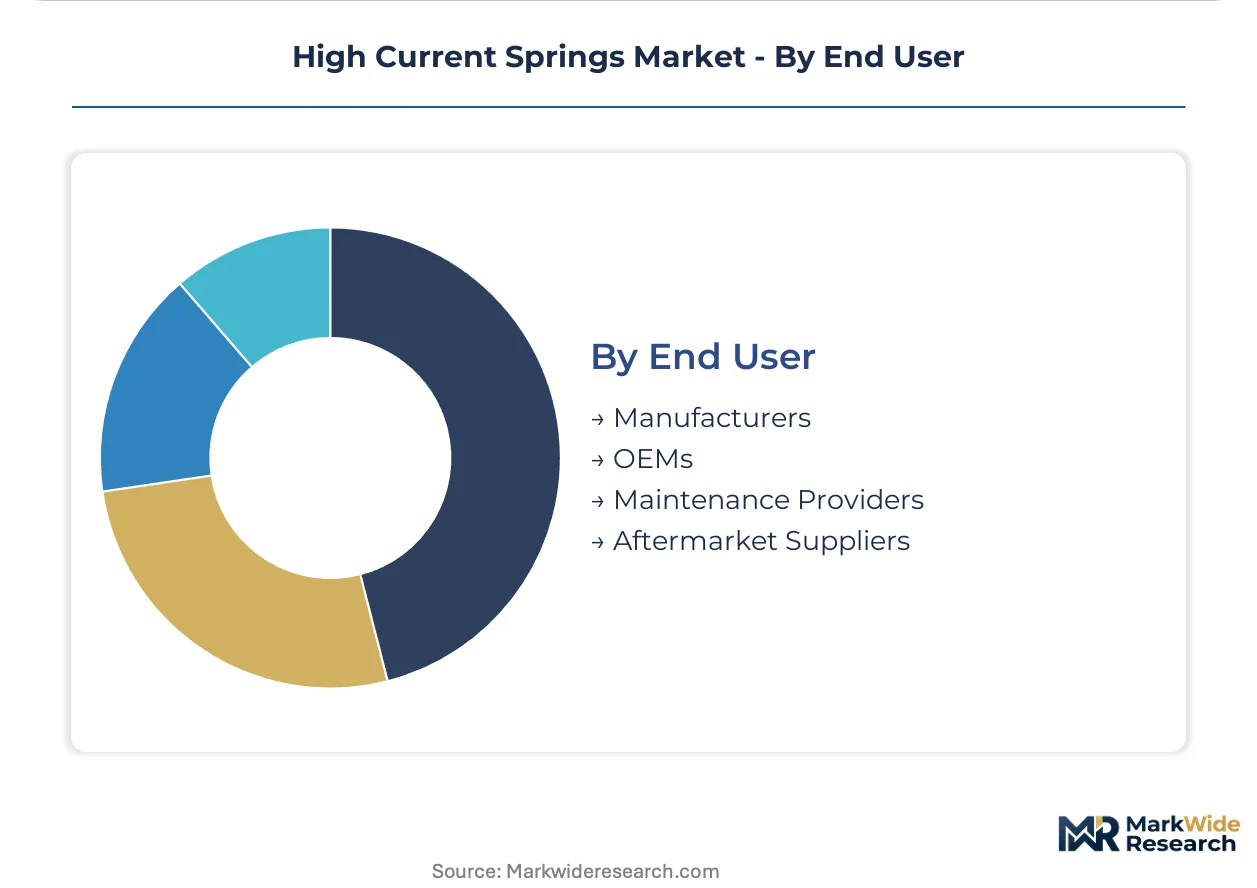
End User:
Supply concentration varies sharply between captive OEM supply and fragmented aftermarket distribution.
- OEMs:Consolidated procurement functions at major automotive and aerospace manufacturers compress approved-vendor lists and demand lifecycle cost guarantees. United States-based EV powertrain sourcing now prioritizes single-source risk mitigation over historical price optimization.
- Manufacturers:Tier-one component suppliers maintain dual-source spring qualifications with identical metallurgical capabilities to satisfy OEM contractual requirements.
- Maintenance Providers:Industrial rebuild specialists specify alloy steel alternatives where electrification-grade conductivity remains unnecessary.
- Aftermarket Suppliers:Distributors serving fragmented repair channels compete on inventory breadth and logistics responsiveness rather than material certification depth.
OEMs concentrate procurement leverage; aftermarket suppliers face margin compression from steel price volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German integrated coil-to-spring manufacturers export precision copper alloy components to Japanese EV powertrain assemblers, establishing a trans-Eurasian trade corridor that channels high-specification springs into battery-electric commercial vehicle platforms.
United States
NHTSA crash-safety protocols for high-voltage battery enclosures create certified-supplier scarcity that qualified spring manufacturers exploit for multi-year OEM contracts. The Inflation Reduction Act's domestic content incentives accelerate reshoring of copper alloy component production. Michigan and Ohio-based automotive clusters concentrate EV powertrain sourcing where procurement teams now prioritize single-source risk mitigation.
Germany
Baden-Württemberg and Bavaria host integrated coil-to-spring production capacity that anchors European supply for tier-one automotive electrification programs. REACH-aligned substance restrictions compel full material declarations through tier-three suppliers in copper alloy feedstock channels. Stuttgart-area metallurgical facilities recalibrate precipitation-hardening processes to sustain force-retention thresholds across expanded thermal cycling ranges.
Japan
PMDA oversight of diagnostic imaging equipment drives biocompatibility requirements for MRI coil manufacturers seeking copper-nickel-silicon alloys with resistivity below 5 micro-ohm-centimeter. METI industrial policy supports domestic heat-treatment expertise development for EV-specific thermal cycling applications. Nagoya-area electrical equipment manufacturers adopt flat spring configurations for solid-state circuit breaker designs.
China
MIIT dual carbon goals and NEV subsidy programs accelerate domestic battery-electric commercial vehicle deployment requiring high-current contact components. GB standards for high-voltage electrical systems establish force-retention testing protocols that approach NHTSA equivalence. Yangtze River Delta manufacturing clusters absorb technology licensing from German and Japanese precision spring specialists.
High Current Springs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where automotive OEM procurement consolidation compresses approved-vendor lists. The vendor base separates into three strategic archetypes: integrated metallurgy-to-spring manufacturers with captive alloy production, precision spring specialists with proprietary heat-treatment IP, and diversified industrial component suppliers leveraging aerospace qualification breadth. Dominant competitive moves include backward integration into copper alloy feedstock and qualification for multi-standard certification portfolios spanning ISO 9001, IATF 16949, and AS9100.
Among Japanese precision spring specialists, NHK Spring exemplifies the proprietary heat-treatment archetype, while German GmbH-structured manufacturers Mubea and Thyssenkrupp anchor European integrated production. Barnes Group occupies a position representing diversified industrial component suppliers with qualification breadth across multiple OEM approved-vendor lists.
| Leading Market Players |
|---|
| Barnes Group |
| NHK Spring |
| Mubea |
| Thyssenkrupp |
| Associated Spring |
| Lee Spring Company |
| Bal Seal Engineering |
| GALA GROUP |
| Hendrickson USA |
| Others |
Value Network & Pricing Analysis
Copper price volatility in nickel-silium alloy feedstock compresses margin predictability for precision spring manufacturers and simultaneously widens pricing tier spreads between electrification-grade and legacy steel alternatives. Tier-one automotive procurement teams leverage this uncertainty to extract lifecycle cost guarantees that reshape supplier qualification criteria across German and Japanese supply bases.
Pricing Analysis
Next-generation copper-nickel-silicon-chromium formulations command substantial premiums over legacy beryllium copper and plain copper grades in EV inverter sourcing. Three-tier pricing structure across premium electrification-grade, standard industrial-grade, and economy steel-grade levels separates procurement channels by certification intensity. Pricing pressure stems from consolidated OEM procurement functions demanding documented traceability under ISO 9001 protocols. Aftermarket maintenance providers exhibit highest price sensitivity, while aerospace-qualified OEMs absorb premium differentials for AS9100-certified supply security.
Supply Chain Analysis
Integrated coil-to-spring manufacturing concentrates in Germany, Japan, and the United States among tier-one automotive suppliers with captive heat-treatment capabilities. Raw material procurement draws from Chilean copper concentrate, Indonesian nickel processing, and domestic silicon feedstock channels. Single-source vulnerability clusters in Baden-Württemberg precipitation-hardening facilities where EV-specific metallurgical expertise remains scarce. Distribution runs through tier-one component suppliers maintaining dual-source qualifications for OEM risk mitigation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High current springs demand tracks battery-electric commercial vehicle production cycles, with procurement intensity rising as platform volumes scale beyond prototype phases. This cyclical recovery favors suppliers with pre-qualified certification portfolios over price-competitive challengers.
For Market Incumbents: Pre-empt margin compression by securing backward integration into copper alloy feedstock through long-term offtake agreements with documented REACH compliance. Accelerate capacity expansion in Ohio and Michigan automotive clusters before NHTSA-certified supplier scarcity intensifies. Invest in proprietary precipitation-hardening IP to defend against emerging Asian competitors licensing European technology.
For New Entrants and Emerging Players: Pursue white-space opportunities in solid-state circuit breaker flat spring configurations where Japanese electrical equipment manufacturers seek arc-quenching performance beyond legacy coil geometries. Target medical imaging coil applications under FDA 21 CFR oversight where biocompatibility documentation creates qualification barriers for established automotive-centric suppliers. Lead with metallurgical certification depth rather than unit-price positioning.
For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors precision specialists with multi-standard certification portfolios over diversified industrial conglomerates. Long-term viability hinges on heat-treatment expertise scarcity that will persist through the electrification transition. Monitor battery-electric commercial vehicle platform announcements as the primary inflection signal for spring specification intensity.
| Strategic Initiative | Industry Significance |
|---|---|
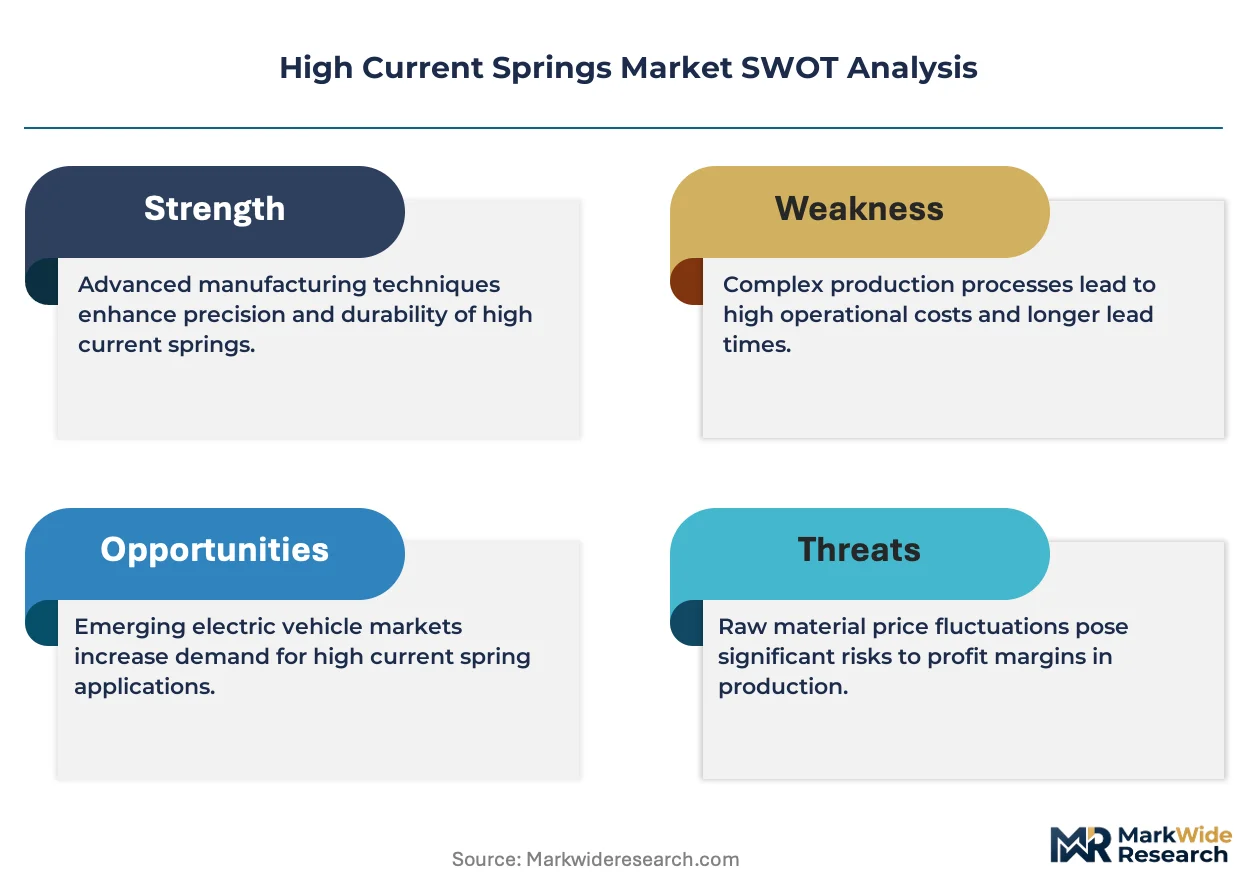
| Backward Integration into Copper Alloy Feedstock | REACH-aligned material declarations secure tier-one automotive qualification access. |
| Multi-Standard Certification Investment | Simultaneous ISO 9001, IATF 16949, and AS9100 approvals compress competitor entry timelines. |
| Heat-Treatment Process Patenting | Proprietary precipitation-hardening IP locks in EV thermal cycling performance thresholds. |
| Regional Manufacturing Footprint Expansion | Michigan and Ohio proximity satisfies Inflation Reduction Act domestic content incentives. |
| Dual-Source Qualification Partnerships | Identical metallurgical capabilities satisfy OEM contractual risk-mitigation requirements. |
Research Methodology
A spread of perspectives from tier-one automotive procurement directors, precision spring metallurgists, EV platform engineers, and copper alloy feedstock traders converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Barnes Group and NHK Spring, customs data tracking German-Japanese component trade flows, and NHTSA regulatory docket analysis. Bottom-up segment sizing triangulated against top-down electrification penetration models.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning product configuration, material conductivity tier, application intensity, and end-user procurement archetype. CAGRs derived from fitted adoption curves incorporating EV inverter assembly growth, circuit breaker design substitution rates, and aerospace platform refresh cycles. Industry-specific inputs included battery-electric commercial vehicle production schedules and MRI coil manufacturer capital expenditure plans.
Sensitivities concentrate around copper price volatility, REACH substance restriction expansion, and heat-treatment expertise migration patterns that could accelerate or delay supplier consolidation. Forecasts reflect documented assumptions regarding electrification penetration and certification timeline compression. Quarterly review of OEM approved-vendor list changes and battery platform announcement cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Global Hybrid Devices Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Automotive Diode Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Digital Instrument Transformer Market