
 Ultra Low Power Microcontroller Market | 2026-2036
Ultra Low Power Microcontroller Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Low Power Microcontroller Market Intelligence
The integration of on-chip AI accelerators and advanced security cores into microcontroller architectures is reshaping product development for edge computing devices. This shift enables more complex processing directly on battery-powered products. STMicroelectronics leverages its deep relationships within the consumer electronics ecosystem. Meanwhile, Texas Instruments competes with a broad portfolio targeting demanding industrial automation and automotive applications.
Ultra low power microcontrollers are specialized processors engineered for minimal energy consumption, often featuring sleep modes with current draws in the nanoampere range. They are essential for extending battery life in connected devices and enabling energy-harvesting applications. While legacy 8-bit and 16-bit options persist, the market's value is migrating toward 32-bit architectures for enhanced processing capabilities. Bluetooth and Wi-Fi are the primary connectivity technologies integrated for smart home and wearable device applications.
Market access is governed by stringent electronics and wireless communication standards. The EU's Radio Equipment Directive (RED) and FCC rules in the United States dictate RF performance and safety protocols. In parallel, compliance with China's GB standards is necessary for market entry there. Consequently, vendor selection increasingly depends on the ability to provide certified hardware and comprehensive software support to simplify customer compliance.
Market Dynamics
The imperative to embed greater intelligence directly into battery-powered devices creates the central dynamic for the ultra low power microcontroller market. This pressure forces a fundamental engineering trade-off between advanced processing capabilities, like on-chip AI, and the non-negotiable requirement for minimal energy consumption.
Growth Catalysts
- Wearable Health Monitoring:The expansion of consumer health and fitness tracking devices, which require continuous sensor data processing and long battery life, directly fuels demand for highly efficient 32-bit microcontrollers.
- EU Radio Equipment Directive (RED):This European Union mandate standardizes performance for wireless communication, compelling device makers to adopt compliant microcontrollers with integrated and certified radio technologies like Bluetooth, thereby boosting the value of qualified components.
- China's Manufacturing Clusters:The high concentration of consumer electronics and smart device manufacturing in Chinese industrial regions like the Pearl River Delta creates a massive, geographically focused demand center for ultra low power components.
Market Restraints
- Advanced Fabrication Costs:Achieving nanoampere-level sleep currents requires leading-edge semiconductor manufacturing processes, the high cost of which can make these advanced microcontrollers prohibitive for mass-market, price-sensitive applications.
- Power-Performance Trade-off:A fundamental physical limitation exists between the computational performance of a microcontroller and its power consumption, constraining the complexity of algorithms that can run on battery-powered edge devices.
- Foundry Concentration:The production of the most advanced low-power silicon is concentrated among a small number of specialized semiconductor foundries, creating a potential bottleneck and supply chain risk for the entire market.
Strategic Opportunities
- Energy Harvesting Applications:The extreme efficiency of these microcontrollers enables the development of batteryless devices that are powered by harvested ambient energy from light, vibration, or thermal gradients, opening new markets in maintenance-free IoT sensors.
- AI and MCU Convergence:Integrating dedicated neural processing units (NPUs) onto ultra low power microcontroller architectures creates opportunities in new intelligent edge devices, such as predictive maintenance sensors for industrial machinery.
- Smart Agriculture Expansion:Underpenetrated markets like smart agriculture in India and Brazil present a significant opportunity for MCUs with long-range, low-power wireless connectivity to enable remote soil and crop monitoring.
Industry Challenges
- Regulatory Fragmentation:Navigating disparate international standards for wireless devices, including FCC rules in the United States, RED in the EU, and GB standards in China, complicates product design and delays market entry.
- Specialized Talent Scarcity:There is a shortage of engineers with the dual expertise in both low-level, power-optimized hardware design and the implementation of machine learning models on resource-constrained embedded systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Low Power Microcontroller Market |
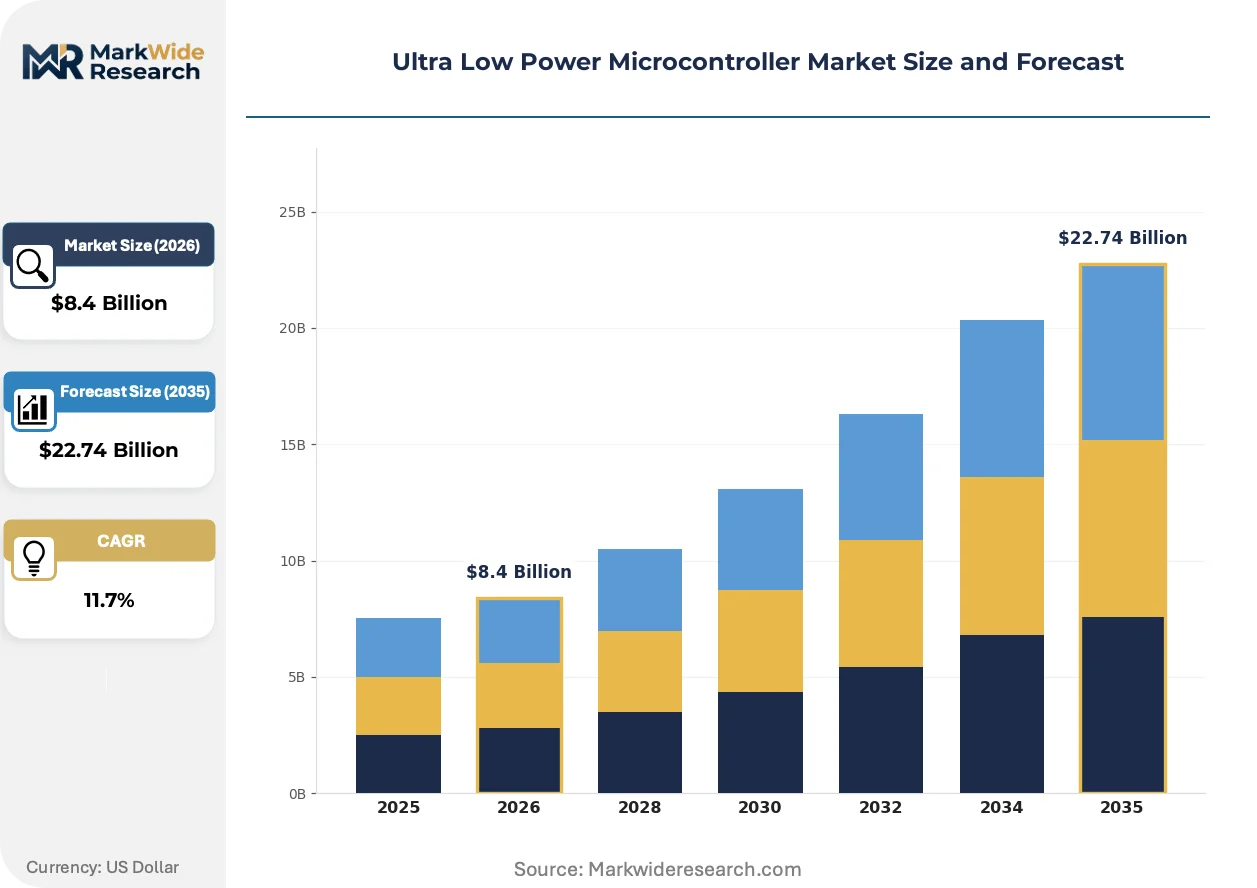
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-bit, 16-bit, 32-bit, FPGA End User: Consumer Electronics, Automotive, Industrial Automation, Healthcare Technology: Wi-Fi, Bluetooth, Zigbee, LoRa Application: Wearable Devices, Smart Home, Smart Grid, Industrial IoT |
| Companies Covered | Infineon Technologies, NXP Semiconductors, Texas Instruments, STMicroelectronics, Microchip Technology, Renesas Electronics, Nordic Semiconductor, Analog Devices, Silicon Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Low Power Microcontroller Market Strategic Shifts & Innovations
Architectural innovation is enabling a significant shift of processing from the cloud to the device edge. This migration is defined by the integration of more complex features, such as AI acceleration and enhanced security, without compromising the core value proposition of ultra-low power consumption.
On-Chip AI Acceleration
The integration of dedicated neural processing units or AI accelerators directly onto the microcontroller die is a defining technological evolution. These specialized cores are being adopted rapidly by developers of smart home devices and industrial sensors. This architectural shift is rendering obsolete the reliance on cloud-only processing for many real-time, battery-powered edge applications by enabling local inference.
Certified Wireless Integration
The European Union's Radio Equipment Directive (RED) sets stringent requirements for radio performance, security, and safety. This regulation forces manufacturers to ensure their products are compliant before entering the EU market. The segment most affected is smart home and wearable device manufacturers, who now prioritize microcontrollers with pre-certified Bluetooth and Wi-Fi software stacks to de-risk and shorten their own compliance testing cycles.
Platform-Based Procurement
A notable behavioral change is the move by original equipment manufacturers (OEMs) from sourcing individual components to procuring complete platform solutions. This disrupts the business of component-level distributors by favoring vendors who offer a bundled package of the microcontroller, certified wireless modules, and a supporting software development kit (SDK). This trend is most prominent in the consumer wearables sector, where speed-to-market is a critical competitive factor.
Ultra Low Power Microcontroller Market Segmentation
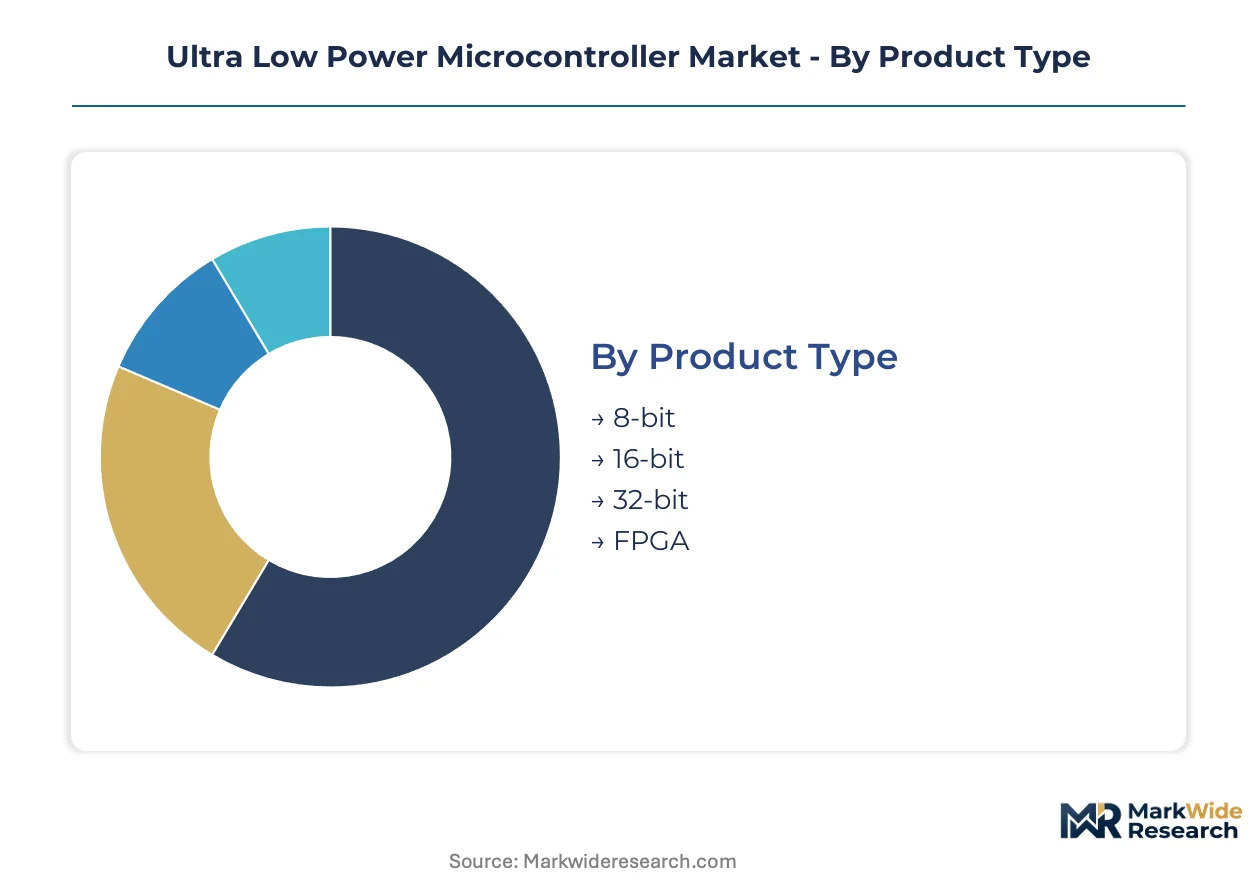
Understanding the Ultra Low Power Microcontroller Market requires disaggregation into its constituent parts. This segmentation reveals the underlying technological currents and application-specific demands driving product development. Each category reflects distinct engineering challenges and market opportunities for manufacturers.
Product Type:
The after-sales-service intensity for ultra low power microcontrollers varies significantly across product types, reflecting the complexity of integration and the longevity requirements of end-user products.
- 32-bit:These microcontrollers offer enhanced processing power and memory capacity, crucial for complex algorithms like on-chip AI. Demand concentrates in wearable devices and smart home applications, driven by the need for sophisticated local data processing.
- 8-bit:These are foundational architectures, optimized for extreme low power consumption and cost-sensitive applications. Their demand persists in basic sensor nodes and simple control systems, particularly in emerging markets where BOM cost is paramount.
- 16-bit:These components bridge the gap between 8-bit simplicity and 32-bit performance, finding use in applications needing moderate computational power.
- FPGA:Field-Programmable Gate Arrays offer custom hardware acceleration and flexibility for specific, high-performance ultra low power applications.
By volume, 8-bit architectures still hold significant share. By growth pace, 32-bit options are expanding most quickly, driven by advanced feature integration.
End User:
Application complexity dictates microcontroller selection for various end-user industries, influencing feature sets from security protocols to integrated peripherals.
- Consumer Electronics:This segment encompasses devices like wearables, smart home gadgets, and personal health monitors, requiring high energy efficiency and integrated wireless connectivity. Demand is strong in China's manufacturing clusters, driven by rapid product iteration cycles.
- Industrial Automation:These applications demand robust microcontrollers with extended temperature ranges, long-term reliability, and advanced communication interfaces for factory and process control. Predictive maintenance sensors for industrial machinery represent a key growth area.
- Automotive:Microcontrollers in automotive systems manage various functions from infotainment to advanced driver-assistance systems, requiring stringent safety certifications.
- Healthcare:This sector utilizes ultra low power microcontrollers for medical wearables, diagnostic equipment, and remote patient monitoring, prioritizing precision and data security.
The consumer electronics segment demonstrates high market maturity with rapid product cycles. Industrial automation, conversely, shows a longer adoption curve with emphasis on component longevity.
Technology:
Supply concentration patterns influence the availability and pricing of integrated wireless technologies within ultra low power microcontrollers, particularly for certified modules.
- Bluetooth:This short-range wireless technology is ubiquitous in wearable devices and smart home ecosystems, valued for its low power consumption and robust ecosystem. Compliance with the EU Radio Equipment Directive is a significant factor in its adoption.
- Wi-Fi:Offering higher bandwidth and broader range, Wi-Fi is critical for smart home devices requiring substantial data transfer or cloud connectivity. Its integration into microcontrollers demands careful power management.
- Zigbee:This mesh networking protocol is favored for its reliability and low power in smart lighting and building automation applications.
- LoRa:Long Range (LoRa) technology enables wide-area connectivity for remote IoT sensors, particularly in smart agriculture and industrial monitoring.
Bluetooth and Wi-Fi integration carry substantial regulatory compliance burdens due to their widespread use across multiple international standards. LoRa faces fewer such challenges in its niche applications.
Application:
Customer type significantly influences the procurement strategies and feature demands for ultra low power microcontrollers, ranging from large OEMs to niche solution providers.
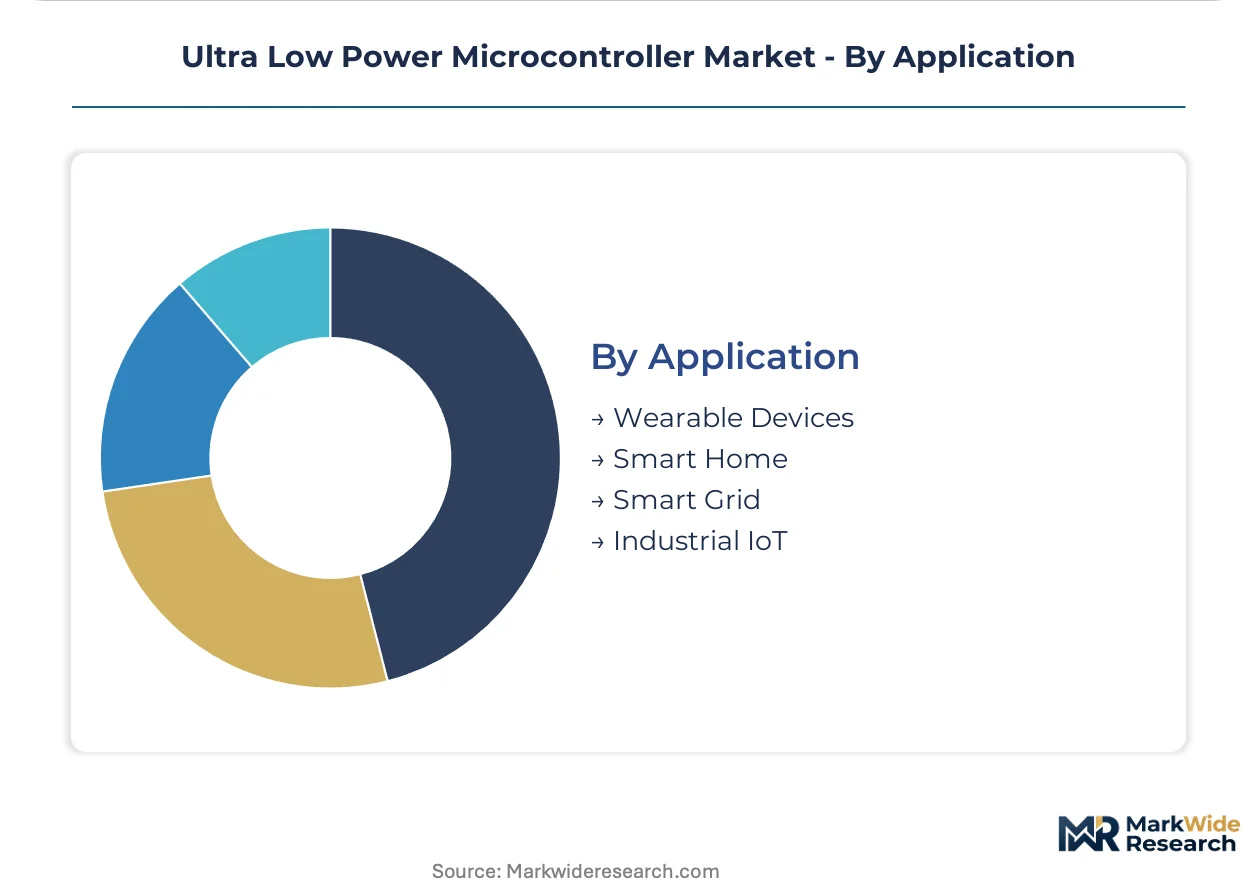
- Wearable Devices:This application area drives demand for highly integrated, energy-efficient microcontrollers with compact footprints for continuous health monitoring. Consumer trends in health and fitness tracking fuel this segment's expansion.
- Smart Home:Microcontrollers in smart home applications manage interconnected devices, requiring robust wireless connectivity and often on-chip AI for local intelligence. Ease of integration and platform support are paramount for OEMs.
- Smart Grid:These applications involve monitoring and control of energy distribution, demanding secure, reliable, and often long-range communication capabilities.
- Industrial IoT:Microcontrollers in Industrial IoT enable sensor networks for asset tracking, predictive maintenance, and process optimization in harsh environments.
Wearable devices present acute integration challenges due to size and power constraints. Smart Grid applications, conversely, emphasize data security and network robustness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ultra Low Power Microcontroller market exhibits strong demand concentration among specific buyer archetypes. Consumer electronics manufacturers in Asia drive significant volume, particularly for wearable devices and smart home applications. Industrial automation integrators in Europe and North America also represent substantial demand for robust, energy-efficient solutions.
China
China's vast electronics manufacturing base drives substantial demand for ultra low power microcontrollers in consumer electronics and smart device production. Compliance with China's GB standards is essential for market entry. The Pearl River Delta region, a major industrial cluster, serves as a significant demand center for these components.
Germany
Germany demonstrates strong demand for ultra low power microcontrollers within its advanced industrial automation and automotive sectors. The EU Radio Equipment Directive standardizes wireless communication performance. Industrial regions like Bavaria are centers for developing sophisticated factory and process control systems utilizing these efficient components.
United States
American consumer electronics and smart home markets fuel demand for energy-efficient microcontrollers, especially in health monitoring and connected devices. Adherence to FCC rules is mandatory for wireless communication products. Technology hubs such as Silicon Valley foster innovation in edge computing devices, integrating advanced low-power silicon.
India
India's smart agriculture sector presents a strategic opportunity for ultra low power microcontrollers, enabling remote soil and crop monitoring solutions. National regulatory frameworks guide product specifications for wireless and embedded systems. Bengaluru, a prominent technology hub, is seeing increased development of IoT solutions tailored for agricultural efficiency.
Japan
Japanese manufacturers seek ultra low power microcontrollers for their high-precision industrial IoT applications and sophisticated automotive electronics. Compliance with JIS standards ensures product quality and reliability. The Kanto region, including Tokyo, remains a critical hub for advanced electronics design and manufacturing, driving demand for specialized components.
Ultra Low Power Microcontroller Market Key Industry Players
Channel-controlling players compete with product-specialist players within the Ultra Low Power Microcontroller market. The market structure exhibits consolidation among leading integrated device manufacturers, alongside fragmentation from numerous niche component providers. Key archetypes include broad-portfolio semiconductor giants and specialized low-power wireless solution providers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and integrate new technologies.
Among the established integrated device manufacturers, STMicroelectronics N.V. (a European-based company) and Texas Instruments Incorporated (a US-based company) occupy significant positions. These companies represent broad portfolio offerings that cater to diverse end-user applications, from consumer electronics to industrial automation. Nordic Semiconductor ASA (a Norwegian-based company) exemplifies a specialized low-power wireless solution provider, focusing on specific connectivity technologies like Bluetooth. These entities collectively anchor different strategic segments, ranging from general-purpose microcontrollers to advanced wireless-enabled components, influencing market direction through their respective technology specializations and market access.
| Leading Market Players |
|---|
| Infineon Technologies |
| NXP Semiconductors |
| Texas Instruments |
| STMicroelectronics |
| Microchip Technology |
| Renesas Electronics |
| Nordic Semiconductor |
| Analog Devices |
| Silicon Laboratories |
| Others |
Cost & Logistics Intelligence
Global semiconductor foundry overcapacity is currently influencing pricing dynamics, forcing manufacturers to optimize production efficiency and negotiate more aggressively for wafer allocations. This utilization rate directly impacts the cost structure for ultra low power microcontrollers.
Pricing Analysis
Cost-plus contract patterns, often indexed to silicon wafer prices and manufacturing process node costs, define much of the pricing for ultra low power microcontrollers. Price differentiation arises from certification levels, particularly for EU RED compliance, and the volume scale of OEM orders. Pricing softness stems from intense competition among 32-bit MCU providers and the ongoing decline in material costs for some legacy architectures. Consumer electronics OEMs represent the most price-sensitive segment, while industrial automation clients prioritize long-term reliability over initial cost.
Supply Chain Analysis
Upstream polysilicon and rare earth element availability significantly impacts the cost and lead times for ultra low power microcontroller fabrication. Geographic supply concentration for advanced process nodes is centered in Taiwan and South Korea, creating potential single-source vulnerability. Logistics chokepoints, particularly for air freight, represent a structural risk for timely component delivery. Distribution runs through a hybrid model, combining direct sales to large OEMs with component-level distributors serving smaller integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultra low power microcontroller market is entering a cyclical recovery phase, driven by renewed consumer spending on connected devices. This upswing creates strategic opportunities for all market participants.
For Market Incumbents: Entrench existing market leadership by investing heavily in next-generation 32-bit architectures with integrated AI accelerators. This move counters the threat from specialized AI chip startups and enhances product differentiation. Deepen vertical integration into advanced packaging solutions to control costs and improve performance. Focus R&D on developing comprehensive software development kits that simplify customer compliance with global standards like EU RED.
For New Entrants and Emerging Players: India's smart agriculture sector represents a significant underpenetrated market for ultra low power microcontrollers. Focus on providing low-cost, long-range wireless solutions for remote monitoring. Develop application-specific integrated circuits (ASICs) tailored for energy harvesting applications, offering batteryless operation. A go-to-market angle emphasizing bundled hardware-software solutions with local support will facilitate rapid adoption.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform solution providers offering bundled hardware, certified modules, and software development kits. This market offers long-term viability due to the pervasive need for energy-efficient edge processing across diverse applications. Target acquisition archetypes include specialized low-power wireless solution providers with strong IP portfolios. The signal to watch is the increasing adoption rate of on-chip AI accelerators in mass-market consumer devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand 32-bit MCU Portfolio | Addresses growing demand for enhanced processing power in wearable devices and smart home applications. |
| Invest in AI/NPU Integration | Enables complex local inference on battery-powered edge devices, reducing cloud dependency for OEMs. |
| Secure EU RED Certification | Facilitates market entry and accelerates time-to-market for wireless-enabled microcontrollers in Europe. |
| Develop Energy Harvesting Solutions | Unlocks new batteryless device markets in industrial IoT and remote sensor applications for niche providers. |
| Form Strategic Partnerships in China | Accesses massive electronics manufacturing clusters and navigates GB standards for local market penetration. |
Research Approach
A standing panel of microcontroller design engineers, product managers, procurement leads, and regulatory compliance officers provided ongoing calibration for market trends. Primary interviews with industry stakeholders complemented secondary validation from industry reports, academic publications, and patent databases. This approach ensured bottom-up market insights were cross-referenced with top-down strategic perspectives.
Scenario-bracketing informed the quantitative modeling, incorporating various market growth trajectories for ultra low power microcontrollers. The analytical framework segmented the market by product type, end user, technology, application, and regional regulatory clusters across the analysis window. Compound annual growth rates were derived from historical data analysis, projected demand drivers, and semiconductor fabrication capacity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated device manufacturers would shift outcomes. Forecasts reflect assumptions documented, acknowledging geopolitical tensions as a specific risk factor. Cross-checking against government technology reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
Japan Semiconductor Device Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Semiconductor Wafer Frame Market