
 Electrical and Electronic Computer-Aided Design (ECAD) Market | 2026-2036
Electrical and Electronic Computer-Aided Design (ECAD) Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical and Electronic Computer-Aided Design (ECAD) Market Foresight
Automotive electrification is realigning ECAD procurement priorities as OEMs consolidate electrical and mechanical design workflows. Siemens EDA dominates automotive PCB verification through its integrated chip-to-system toolchain. Cadence Design Systems leverages high-speed signal integrity simulation to anchor aerospace and defense contracts. Zuken specializes in wire harness engineering, occupying a defensible position in Japanese and European automotive supply chains.
Electrical and Electronic Computer-Aided Design encompasses software systems that model, simulate, and validate circuit behavior, physical layout, and thermal performance across integrated circuits, printed circuit boards, and electromechanical assemblies. These tools process geometric data, material properties, and netlist connectivity to generate manufacturing-ready outputs including Gerber files, drill maps, and bill-of-materials documentation. Cloud-based deployment is capturing the fastest expansion as engineering teams distribute simulation workloads across elastic compute resources. PCB Design technology leads current revenue contribution given its centrality to consumer electronics and telecommunications infrastructure. FPGA Design tools are gaining share among defense and satellite contractors requiring radiation-hardened verification.
FCC equipment authorization rules in the United States and EU CE marking under the Radio Equipment Directive shape electromagnetic compliance testing workflows embedded in ECAD suites. ECHA REACH substance restrictions further constrain material libraries within component databases, forcing database updates across user bases. NIST cybersecurity frameworks are beginning to influence data exchange protocols between ECAD and product lifecycle management platforms. Stakeholders must monitor how export control expansions affect semiconductor IP libraries accessible through cloud-hosted design environments.
Market Dynamics
Automotive electrification is collapsing the historical separation between electrical and mechanical design teams, forcing ECAD vendors to rebuild their architectures around unified data models that synchronize circuit behavior with 3D thermal and structural simulation.
Growth Catalysts
- EU CE marking under the Radio Equipment Directive:Electromagnetic compatibility verification now mandates integrated simulation workflows, compelling tool upgrades across European electronics supply chains.
- Semiconductor packaging investments:Advanced packaging geometries in China, Germany, and the United States require multi-physics co-simulation capabilities that legacy point solutions cannot deliver.
- Cloud-native deployment architectures:Engineering teams distribute compute-intensive signal integrity analysis across elastic infrastructure, reducing hardware capital requirements for mid-tier design houses.
Market Restraints
- Specialized talent scarcity:Electromagnetic field simulation expertise concentrates among aging practitioner pools in Germany and Japan, constraining adoption velocity for complex verification tools.
- Legacy data migration costs:Decades of proprietary component libraries and design rule databases resist automated conversion to modern platform architectures.
- Input cost volatility:Cloud compute pricing fluctuations and semiconductor IP licensing escalation compress margins for subscription-based ECAD vendors.
Strategic Opportunities
- Indian electronics manufacturing expansion:Production-linked incentive schemes attract PCB fabrication facilities, creating demand for localized design tools and compliance documentation systems.
- Digital twin convergence:ECAD-MCAD integration platforms capture value from aerospace and defense contractors requiring traceable electromechanical validation across program lifecycles.
- Subscription model penetration:Perpetual license holders in mature markets convert to recurring revenue arrangements, unlocking predictable cash flows and continuous feature delivery.
Industry Challenges
- Multi-domain simulation integration:Thermal, electromagnetic, and mechanical solvers operate on incompatible meshing algorithms, forcing manual data translation that introduces validation gaps.
- IP contamination risk in cloud environments:Design data co-residency with competitor workloads triggers export control scrutiny and customer resistance in defense-facing segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical and Electronic Computer-Aided Design (ECAD) Market |
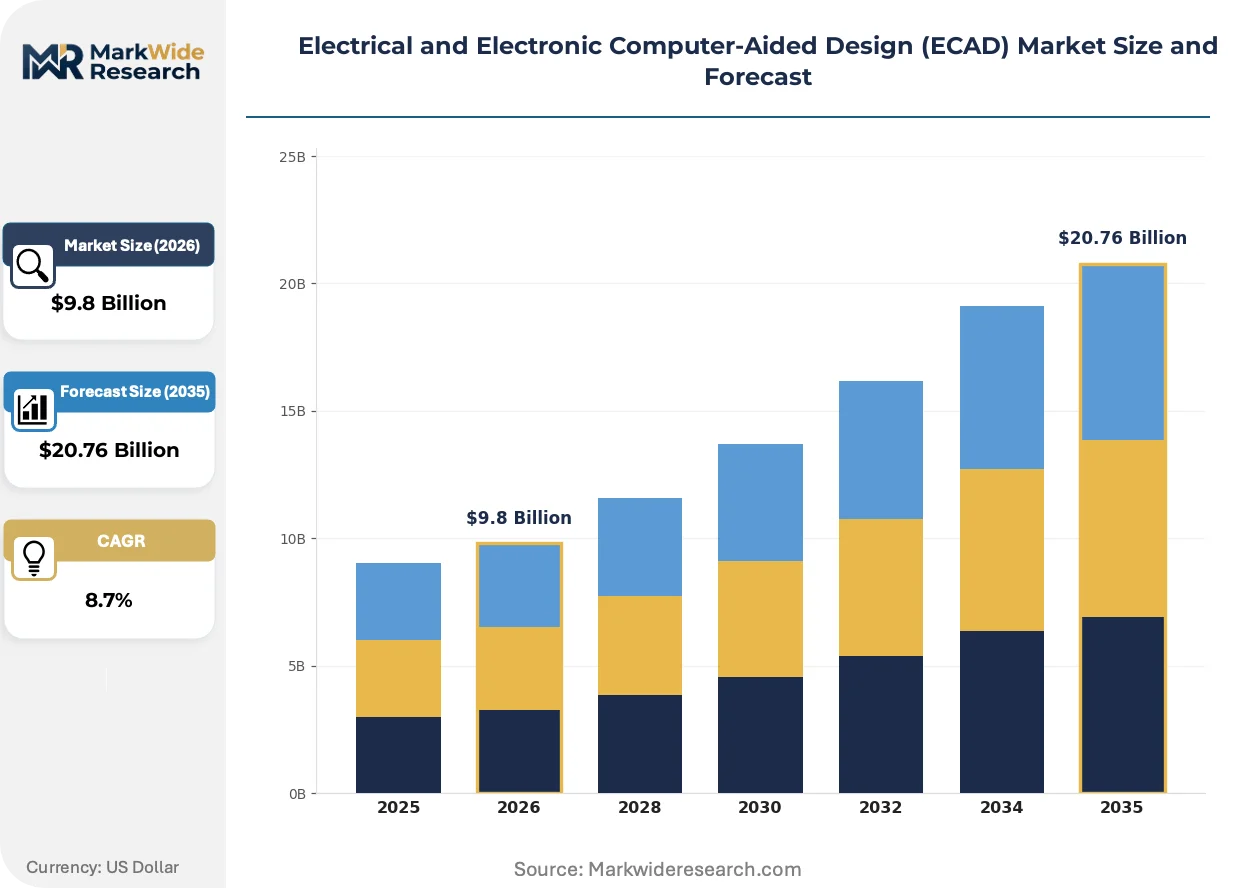
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Tools, Simulation Software, Layout Tools, Schematic Capture Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: OEMs, Tier-1 Suppliers, Design Firms, Academia Technology: FPGA Design, PCB Design, Circuit Simulation, 3D Modeling |
| Companies Covered | Altium, Zuken, Siemens EDA, Autodesk, Ansys, Cadence Design Systems, Mentor Graphics, EPLAN Software & Service, Synopsys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical and Electronic Computer-Aided Design (ECAD) Market Shifts & Advancements
Artificial intelligence is penetrating ECAD workflows at the constraint-satisfaction layer, compressing placement and routing cycles while raising questions about deterministic verification standards.
Machine learning-based component placement is automating the translation of schematic netlists into optimized physical layouts. Tier-one automotive suppliers in Germany and Japan deploy these tools for high-density power electronics where manual iteration previously consumed weeks. The technology is automating rule-checking sequences that previously required dedicated hardware engineers, reallocating human capital toward architecture decisions.
EU F-Gas Regulation phase-down schedules are forcing thermal simulation recalibration across HVAC-integrated electronics. Equipment manufacturers must validate cooling performance under restricted refrigerant chemistries, embedding new material property databases within ECAD thermal modules. Aerospace suppliers with European certification obligations face the steepest workflow adaptation requirements.
Consolidated enterprise procurement is displacing departmental tool selection autonomy. Centralized engineering operations groups in United States defense contractors now mandate approved vendor lists, compressing the addressable market for specialized point solutions. This concentration is most visible in satellite and avionics programs where NIST cybersecurity frameworks govern supply chain qualification.
Electrical and Electronic Computer-Aided Design (ECAD) Market Segmentation
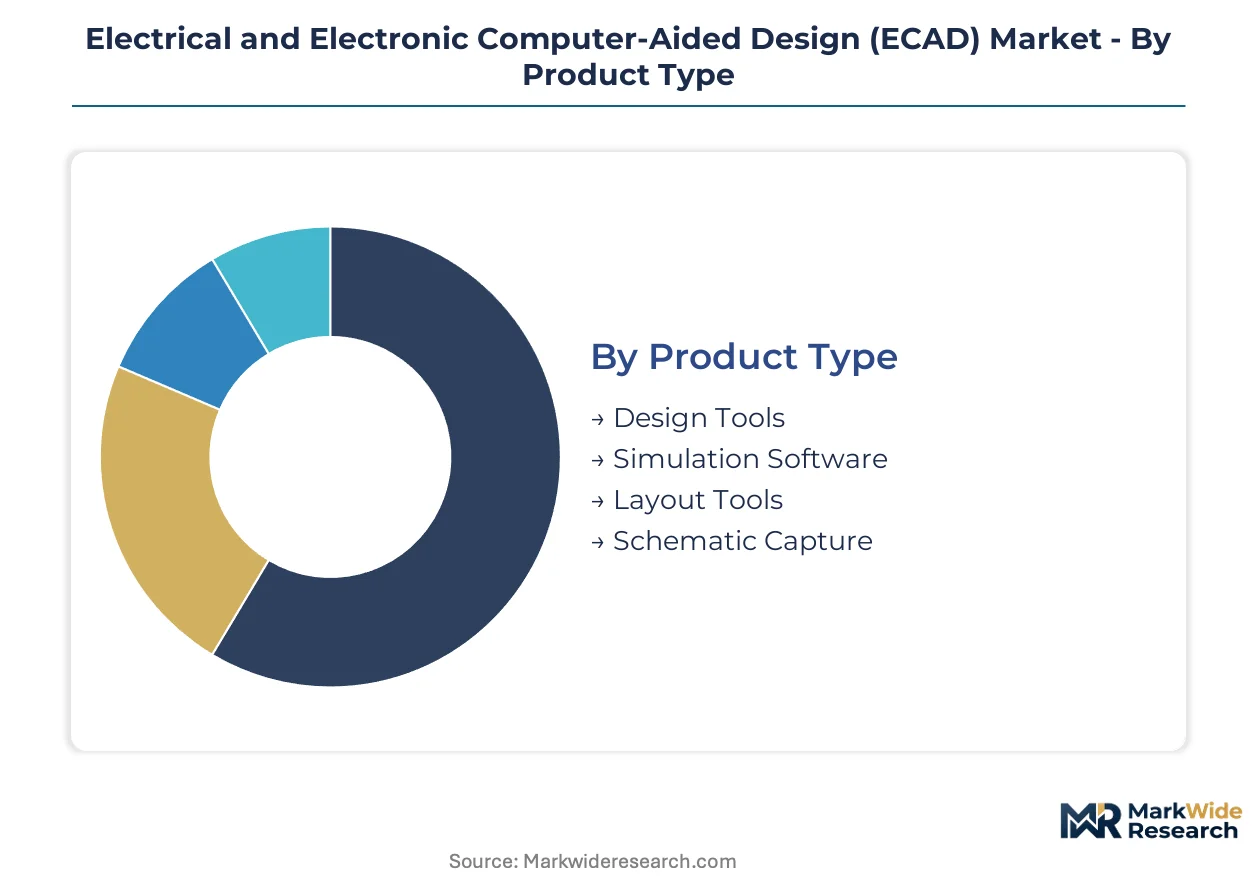
ECAD procurement patterns diverge sharply across deployment models and user sophistication levels. Capital allocation, compliance obligations, and team scale dictate which segments capture budget priority in automotive, aerospace, and semiconductor verticals.
Product Type:
Simulation Software commands the heaviest upfront capital commitment given its dependency on high-performance compute infrastructure and specialized electromagnetic solver licensing.
- Design Tools:Core schematic-to-layout environments integrate component libraries, design rule checking, and manufacturing output generation. German automotive OEMs consolidate procurement around unified toolchains that span electrical and mechanical domains. These platforms absorb the bulk of installed capacity.
- Simulation Software:Multi-physics solvers model signal integrity, thermal behavior, and electromagnetic compatibility across chip-package-board hierarchies. China-based semiconductor packaging investments drive demand for co-simulation capabilities that legacy point solutions cannot deliver. This segment is expanding most quickly.
- Layout Tools:Physical placement and routing engines optimized for high-density interconnect geometries.
- Schematic Capture:Front-end netlist creation with component database integration and cross-referencing capabilities.
Design Tools absorb the bulk of installed capacity; Simulation Software is expanding most quickly.
Deployment:
Cloud-Based architectures minimize capital expenditure while maximizing elastic compute access for distributed engineering teams.
- Cloud-Based:Elastic infrastructure distributes signal integrity and electromagnetic simulation workloads without on-premises hardware ownership. Mid-tier design houses in India leverage consumption-based pricing to access capabilities previously reserved for multinational corporations. This segment is climbing the fastest.
- On-Premises:Perpetual-licensed software running on customer-controlled hardware dominates defense-facing segments where NIST cybersecurity frameworks and export control concerns restrict data residency. United States aerospace contractors mandate air-gapped environments for classified programs. On-Premises retains the largest installed base.
- Hybrid:Mixed environments partition sensitive design data locally while pushing compute-intensive simulation to cloud resources.
- SaaS:Fully managed subscription offerings with automated updates and collaborative workspace provisioning.
On-Premises retains the largest installed base; Cloud-Based is climbing the fastest.
End User:
OEMs concentrate the highest per-seat software expenditure given their demand for integrated chip-to-system verification platforms.
- OEMs:Original equipment manufacturers mandate enterprise-wide tool standardization to synchronize electrical and mechanical design workflows across global engineering centers. Japanese automotive electrification programs consolidate ECAD procurement under centralized operations groups. OEMs command the dominant share of license volume.
- Tier-1 Suppliers:Subsystem specialists in German and Japanese automotive supply chains require wire harness engineering and power electronics verification tools. These firms face procurement pressure from OEM-approved vendor lists that compress point solution opportunities. Tier-1 Suppliers are gaining procurement sophistication fastest.
- Design Firms:Specialized contract engineering houses serving multiple clients with project-based tool requirements.
- Academia:University research programs and vocational training institutions with discounted educational licensing.
OEMs command the dominant share of license volume; Tier-1 Suppliers are gaining procurement sophistication fastest.
Technology:
PCB Design represents the most mature capital deployment category with established vendor relationships and entrenched workflow integration.
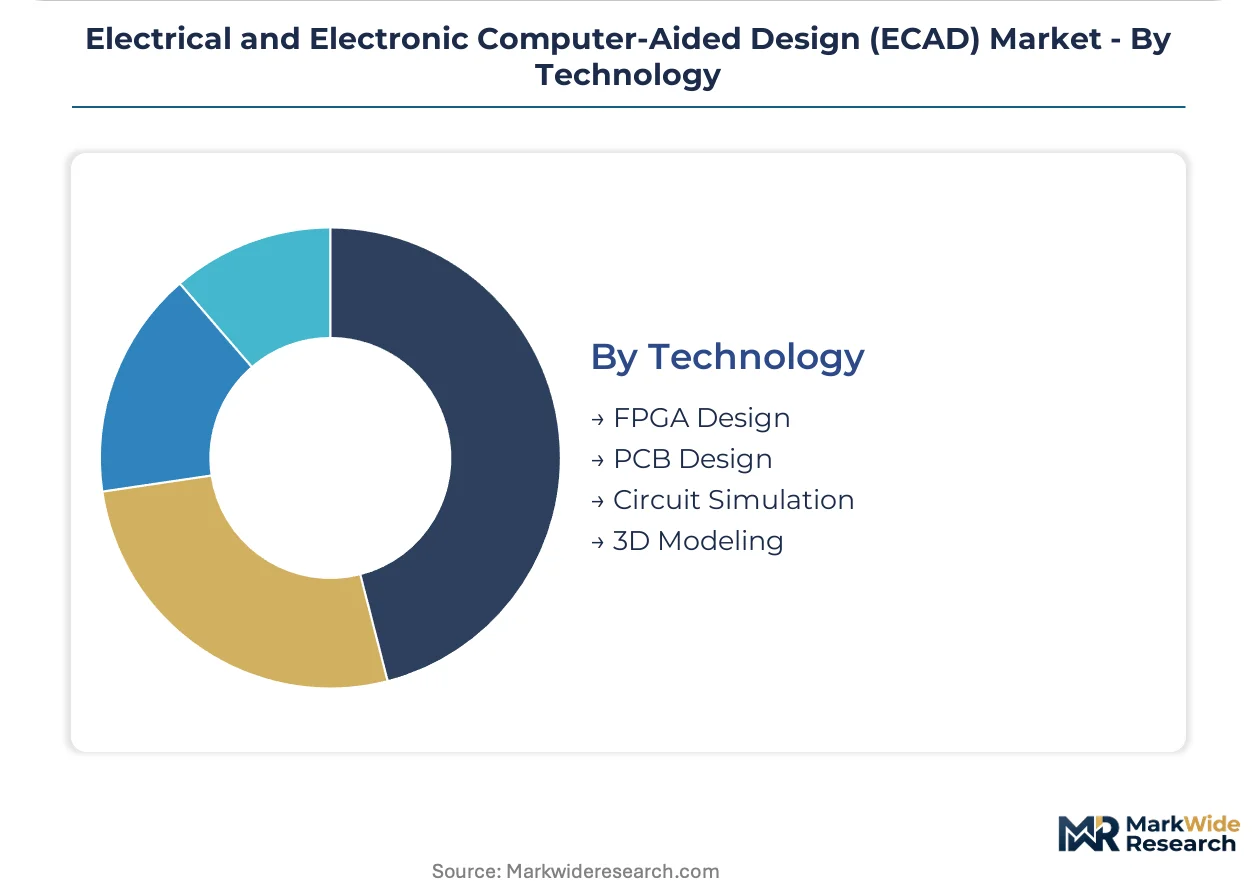
- PCB Design:Printed circuit board layout, routing, and manufacturing output generation remains the foundational ECAD capability. Consumer electronics and telecommunications infrastructure in China, Germany, and the United States sustain the largest user base. This technology category holds the deepest installed base.
- FPGA Design:Field-programmable gate array synthesis, place-and-route, and bitstream generation tools serve defense and satellite contractors requiring radiation-hardened verification. United States aerospace programs under FCC equipment authorization and NIST cybersecurity frameworks drive specialized demand. FPGA Design is accelerating fastest among emerging technology segments.
- Circuit Simulation:Analog and mixed-signal behavioral modeling with SPICE-based analysis engines.
- 3D Modeling:Electromechanical integration enabling thermal and structural co-simulation with MCAD platforms.
PCB Design holds the deepest installed base; FPGA Design is accelerating fastest among emerging technology segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China, Germany, and the United States concentrate ECAD procurement through semiconductor packaging investments and automotive electrification programs. These jurisdictions anchor demand through distinct regulatory frameworks governing electromagnetic compatibility and data residency.
China
Yangtze River Delta semiconductor foundries drive demand for multi-physics co-simulation tools. MIIT GB standards for electromagnetic compatibility mandate integrated verification workflows. Shanghai and Suzhou engineering centers deploy cloud-native ECAD architectures for advanced packaging design.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg consolidate electrical-mechanical design workflows. EU CE marking under the Radio Equipment Directive compels electromagnetic compatibility tool upgrades. Stuttgart and Munich host the densest concentration of wire harness engineering and power electronics verification talent.
United States
Defense contractors and aerospace clusters in California and Texas mandate air-gapped ECAD environments. FCC equipment authorization rules shape signal integrity simulation requirements. Greater Boston and Pacific Northwest semiconductor design centers push cloud compute adoption for elastic simulation workloads.
Japan
Tier-1 automotive suppliers in Aichi and Kanagawa prefectures specialize in high-density power electronics layout. METI industrial standards influence thermal simulation calibration for electrified powertrains. Nagoya and Yokohama engineering centers deploy machine learning-based component placement for compressed design cycles.
India
Production-linked incentive schemes attract PCB fabrication to Gujarat and Tamil Nadu. BIS certification requirements for electronic equipment create localized compliance documentation demand. Bangalore and Hyderabad design houses leverage cloud-based ECAD pricing to access enterprise-grade simulation capabilities.
Electrical and Electronic Computer-Aided Design (ECAD) Market Competitive Landscape
Top-tier vendors anchor enterprise-wide procurement decisions, while mid-tier specialists occupy defensible niches in wire harness engineering and high-speed signal integrity. The vendor base stratifies across integrated platform providers, point-solution specialists, and cloud-native entrants. Three archetypes dominate: chip-to-system toolchain integrators, electromagnetic simulation pure-plays, and mechanical-electrical convergence platforms. Competitive moves concentrate on strategic partnerships with semiconductor foundries and vertical integration into manufacturing data exchange protocols.
Within the integrated platform tier, Siemens EDA and Cadence Design Systems exemplify chip-to-system verification archetypes. Zuken occupies a position among wire harness engineering specialists serving Japanese and European automotive supply chains. These three entities represent distinct strategic postures: unified data model consolidation, high-speed simulation anchoring, and subsystem-focused defensible positioning.
| Leading Market Players |
|---|
| Altium |
| Zuken |
| Siemens EDA |
| Autodesk |
| Ansys |
| Cadence Design Systems |
| Mentor Graphics |
| EPLAN Software & Service |
| Synopsys |
| Others |
Supply & Pricing Matrix
Electromagnetic field simulation expertise concentrated in Stuttgart and Munich sustains German labor-cost premiums that widen pricing-tier spreads between premium verification suites and entry-level layout tools.
Pricing Analysis
Lead-time-driven pricing stratification rewards immediate availability with premium positioning while spot inventory clearance commands discounted terms. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume scale. Cost compression in the mid-market tier is intensifying because cloud compute pricing fluctuations compress vendor margins. Tier-1 automotive suppliers in Japan exhibit the highest price sensitivity, whereas United States defense contractors prioritize NIST cybersecurity compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States aerospace contractors force ECAD vendors to qualify redundant semiconductor IP libraries across geographically dispersed data centers. Software development concentrates in Germany, the United States, and India, while high-performance compute infrastructure draws from Taiwan, South Korea, and Ireland. Single-source vulnerability in specialized electromagnetic solver licensing creates supply chain risk. Distribution runs through direct enterprise sales teams for OEM accounts and value-added resellers serving mid-tier design houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent scarcity in electromagnetic simulation constrains vendor capacity expansion, propping pricing power for qualified practitioners.
For Market Incumbents: Deepen vertical integration into cloud infrastructure ownership to offset compute cost volatility threatening subscription margins. Consolidate component library databases through acquisition of specialized electromagnetic material data providers. Cloud-native entrants with consumption-based pricing pose the primary substitution threat. Certification investment in EU CE marking and FCC equipment authorization workflows anchors enterprise retention. For New Entrants and Emerging Players: Machine learning-based constraint satisfaction algorithms offer a technology-first wedge into high-density power electronics layout currently dominated by manual iteration cycles. White-space targets include Indian PCB design houses migrating from perpetual licenses to SaaS consumption models, and European aerospace subcontractors requiring simplified thermal simulation calibration under F-Gas Regulation phase-down schedules. Freemium tier penetration with automated cloud-based simulation workloads provides the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with electromagnetic simulation pure-plays given semiconductor packaging investment acceleration across China and Germany. Long-term viability over the analysis window favors vendors with chip-to-system toolchain integration depth rather than point-solution positioning. Acquisition target archetypes include wire harness engineering specialists with entrenched Japanese automotive relationships. The signal to watch is cloud-native deployment velocity among mid-tier design houses as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies electrical-mechanical data models for Stuttgart automotive OEMs consolidating procurement. |
| Strategic Partnership | Semiconductor foundry alliances in Yangtze River Delta anchor advanced packaging co-simulation capabilities. |
| Acquisition of Specialist Firm | Wire harness engineering targets in Nagoya supply chains defensible against OEM vendor list compression. |
| Geographic Expansion | Localized compliance documentation systems capture Indian PLI scheme-driven PCB fabrication demand. |
| Product Launch | Radiation-hardened FPGA verification tools address United States aerospace FCC authorization requirements. |
Research Methodology
Independent corroboration across primary interviews with ECAD product managers, electromagnetic simulation specialists, automotive platform engineers, and defense procurement officers underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings of publicly traded design automation vendors, MIIT GB standards documentation, EU Radio Equipment Directive implementation guidance, and hyperscaler cloud infrastructure capex disclosures. Bottom-up segment sizing triangulates against top-down vendor revenue attribution across deployment models and end-user categories.
Comparable-period anchoring to historical license renewal cycles and perpetual-to-subscription conversion trajectories structures the projection horizon. The analytical framework models deployment architecture, end-user sophistication tier, technology category, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from elasticity-adjusted adoption curves and semiconductor packaging investment trajectories. Industry-specific forecast inputs include electromagnetic compatibility standard revision timelines and cloud compute pricing volatility indices.
Several conditions sit outside the modeled scope, including export control expansion affecting semiconductor IP library accessibility and unannounced vendor consolidation transactions. Forecasts reflect documented assumptions regarding talent pipeline replenishment in electromagnetic simulation and cloud infrastructure cost stabilization. Deviation in EU F-Gas Regulation enforcement intensity or NIST cybersecurity framework adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Automotive Diode Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Global Hybrid Devices Market