
 Portable Charger Market | 2026-2036
Portable Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Charger Market Outlook
Asset-light contract manufacturing and white-label leasing arrangements is rewriting competitive entry economics in the portable charger industry. Anker Innovations Technology leverages its direct-to-consumer channel dominance and in-house GaN R&D to sustain pricing power across premium tiers. Baseus competes through aggressive SKU proliferation and ecosystem bundling with cables and hubs. Ambrane India anchors its position in offline retail across tier-two and tier-three Indian cities, where brand recognition outpaces online discovery.
A portable charger is a self-contained electrochemical energy storage device with DC-DC conversion circuitry, typically housing lithium-polymer or lithium-ion cells rated between 3.7V and 3.85V nominal, designed to replenish depleted batteries in mobile electronics via USB-A, USB-C, or inductive Qi interfaces. Power bank units dominate unit economics due to universal compatibility across smartphones, tablets, and wireless earbuds, while solar charger configurations occupy niche outdoor and emergency-preparedness applications where grid access is unreliable. USB-C and Quick Charge technology segments are capturing margin pools as OEMs phase out proprietary connectors and consumers prioritize rapid replenishment protocols.
FCC Part 15 emissions compliance in the United States, CE marking under the EU Low Voltage Directive, and China's GB 31241 cell safety standard collectively shape product certification costs and market access timelines for cross-border suppliers. India's BIS compulsory registration scheme for lithium-ion cells adds another compliance layer for brands targeting that subcontinent. Stakeholders must monitor evolving battery passport requirements under the EU Battery Regulation, as traceability mandates will soon determine which suppliers retain shelf presence in Europe.
Market Dynamics
GaN semiconductor adoption is compressing power adapter footprints and enabling multi-port architectures that redefine portable charger form factors and thermal management requirements across the supply base.
Growth Catalysts
- USB-C harmonization:The EU's Common Charger Directive mandates USB-C across mobile devices by 2024, eliminating proprietary connector fragmentation and expanding addressable unit volumes for universal power banks.
- Lithium-polymer energy density gains:Silicon-anode cell chemistries from Shenzhen suppliers are pushing volumetric density thresholds, enabling 20,000mAh capacities in pocket-sized enclosures previously limited to 10,000mAh.
- Live-streaming creator economy:Mobile gaming and outdoor content production are generating sustained demand for 65W+ output units capable of sustaining laptop and camera simultaneous charging.
Market Restraints
- Cobalt and lithium carbonate volatility:Cell input costs fluctuate with DRC mining output and Chilean brine processing capacity, compressing assembler margins during commodity spikes.
- Shenzhen supply concentration:Over 70% of lithium-ion cell production and finished-goods assembly clusters in Guangdong province, creating single-point vulnerability to regional logistics disruptions or power rationing.
- IEC 62133 certification escalation:Tightening thermal runaway testing protocols under the international safety standard are extending product development cycles and raising third-party laboratory costs.
Strategic Opportunities
- India offline retail penetration:Tier-two and tier-three city consumers exhibit low brand awareness but high price sensitivity, rewarding localized distribution partnerships over pure e-commerce plays.
- EU Battery Regulation traceability:Digital battery passport requirements create first-mover advantage for assemblers with pre-integrated supply chain visibility software and cell-level serialization.
- GaN + silicon carbide convergence:Hybrid power architectures combining both wide-bandgap semiconductors enable 100W+ outputs in sub-200g enclosures, opening premium positioning above current 65W ceilings.
Industry Challenges
- Thermal engineering talent scarcity:Miniaturization demands expertise in computational fluid dynamics and multi-layer PCB stack design that outpaces vocational training pipeline output in key manufacturing regions.
- Multi-jurisdiction certification parallelism:Simultaneous FCC Part 15, CE marking, and BIS registration timelines create inventory staging complexity and working capital lockup for cross-border brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Charger Market |
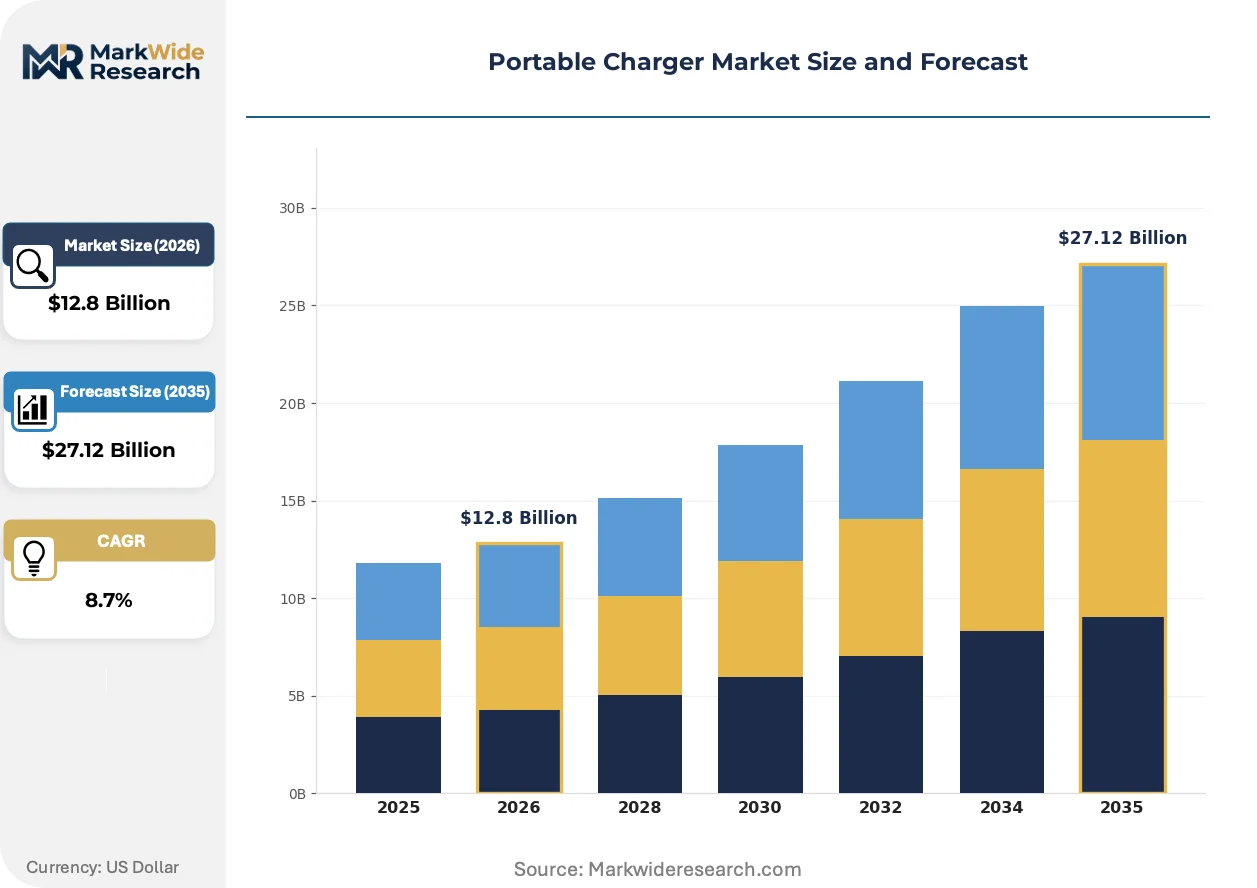
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Charger, Power Bank, Battery Case, Wireless Charger Capacity: 5000mAh, 10000mAh, 20000mAh, 30000mAh Technology: USB-C, Quick Charge, Lightning Input, Qi Charging End User: Travelers, Students, Professionals, Outdoor Enthusiasts |
| Companies Covered | ADATA Technology, BioLite, Anker Innovations Technology, Zendure, Lion Energy, Baseus, Ambrane India, Elecom, Mophie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Charger Market Strategic Shifts
Portable charger evolution is pivoting from capacity arms races toward integration density and intelligent power negotiation, with semiconductor architecture and regulatory traceability emerging as the primary axes of differentiation.
GaNFast integrated circuits from Navitas and Infineon are hybridizing traditional silicon MOSFET topologies, collapsing switching losses by 40% and enabling 100W outputs in enclosures under 150cc. Mobile workstation users and professional creators are adopting these units fastest, compressing the premium tier definition from 65W to 100W thresholds within eighteen months.
China's GB 31241 cell safety standard and the EU Battery Regulation are converging on mandatory cell-level traceability and second-life disclosure requirements. Manufacturers must now embed digital passports and carbon footprint data at the cell procurement stage, favoring vertically integrated assemblers with direct cathode material sourcing relationships.
Direct-to-consumer subscription models for power bank access are displacing outright ownership in urban mobility corridors, with Berlin and Singapore pilot programs offering unlimited swaps for fixed monthly fees. This behavior shift is most pronounced among smartphone-dependent gig workers who prioritize uptime over asset possession, forcing traditional retail channels to unbundle warranty and replacement services.
Portable Charger Market Segmentation
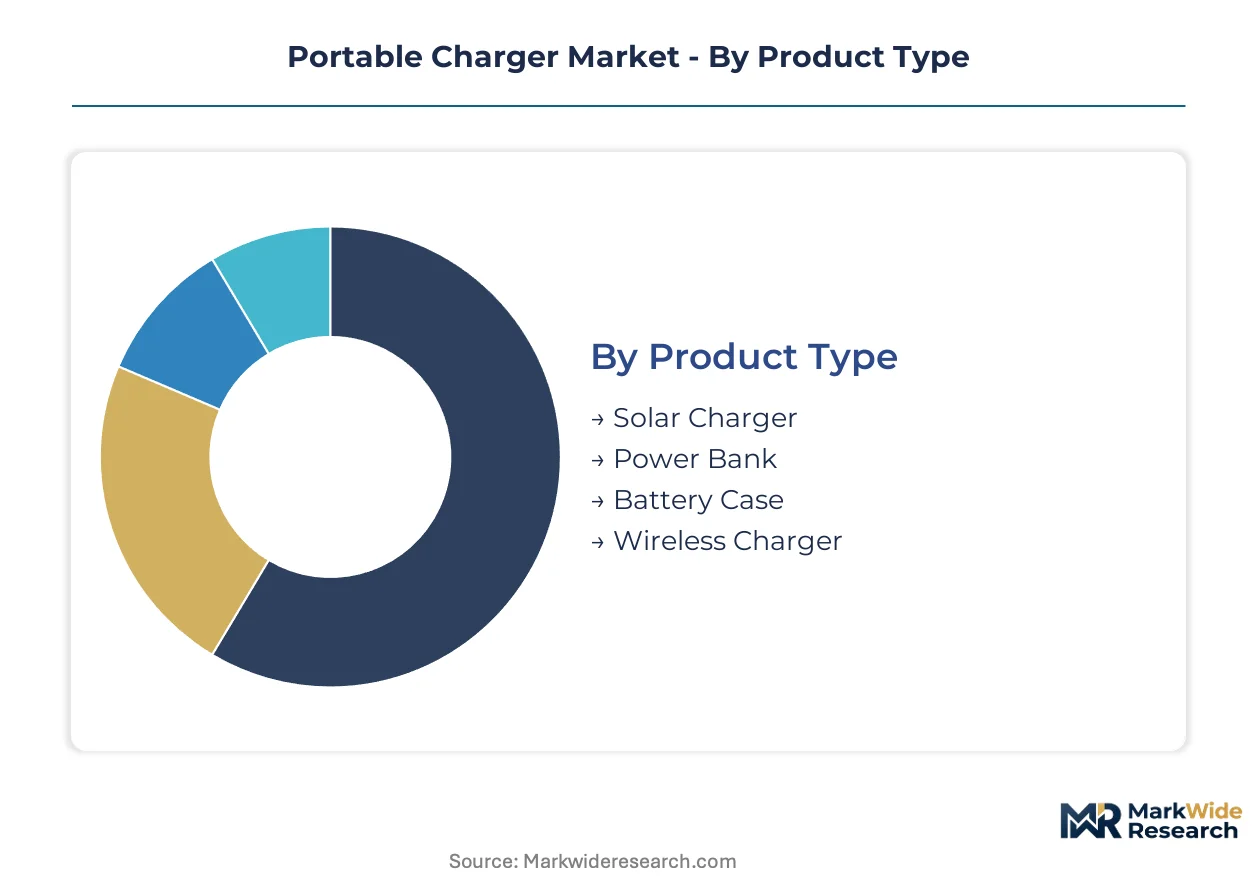
Portable charger segmentation tracks divergent power requirements across mobility patterns and device ecosystems. Manufacturers configure cell architectures and port selections to match distinct usage intensities and replenishment speed expectations.
Product Type:
Cost tier separates mass-market units from specialized configurations with premium positioning potential.
- Power Bank:Self-contained lithium-ion or lithium-polymer cells with DC-DC conversion circuitry deliver 5V-20V output through USB-A and USB-C interfaces. Travelers and mobile professionals in China and India concentrate demand for 10000mAh-20000mAh units as smartphone dependency deepens across gig economy workflows.
- Wireless Charger:Inductive Qi coil assemblies enable cable-free replenishment for compatible smartphones and earbuds. Urban consumers in Singapore and Berlin pilot subscription-based swap programs that displace ownership models for daily-carry accessories.
- Solar Charger:Photovoltaic-integrated enclosures target emergency preparedness and off-grid applications where grid access is unreliable.
- Battery Case:Form-fitted cell integration extends smartphone runtime without separate carry items.
Power Bank holds installed capacity. Wireless Charger is rotating up the share rankings.
Capacity:
Volume requirements scale with device count and away-from-grid duration across user archetypes.
- 20000mAh:Silicon-anode cell chemistries from Shenzhen suppliers now enable pocket-sized enclosures previously limited to 10000mAh. Live-streaming content creators and mobile gaming professionals in China generate sustained demand for laptop-sustaining output.
- 10000mAh:Single-day smartphone replenishment dominates commuter and student use cases with optimal weight-to-runtime ratios.
- 5000mAh:Ultra-compact emergency reserves fit wallet or keychain form factors for minimal-carry scenarios.
- 30000mAh:Multi-device workstation support and extended outdoor expeditions drive bulk-tolerant acceptance.
20000mAh holds installed capacity. 10000mAh is rotating up the share rankings.
Technology:
Interface standardization and power delivery protocols determine compatibility breadth and replenishment velocity.
- USB-C:The EU's Common Charger Directive mandates universal adoption across mobile devices, eliminating proprietary connector fragmentation. Cross-border suppliers must align port configurations with IEC 62680 specifications to retain European market access.
- Quick Charge:Qualcomm's variable voltage negotiation enables 0-50% replenishment in under 30 minutes for compatible chipsets.
- Qi Charging:Inductive pad and stand configurations serve desk-bound and automotive-integrated scenarios.
- Lightning Input:Apple's proprietary connector retains relevance for legacy device installed bases in North American and European markets.
USB-C holds installed capacity. Quick Charge is rotating up the share rankings.
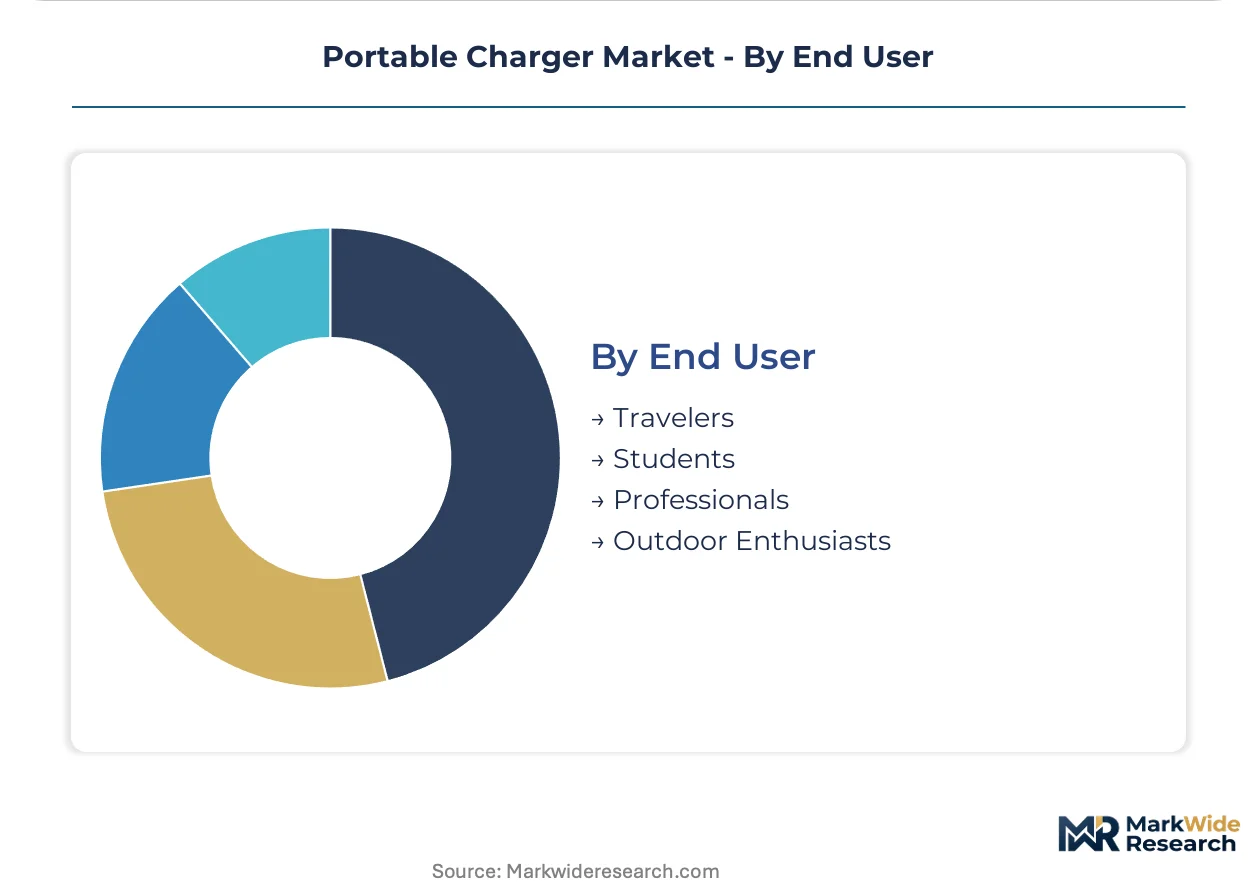
End User:
Customer type dictates capacity thresholds, durability specifications, and price sensitivity across distribution channels.
- Professionals:Multi-device laptop-and-smartphone simultaneous charging demands 65W-100W output units with GaN semiconductor architectures. India's tier-two and tier-three city distribution partnerships reward localized offline retail presence over pure e-commerce plays.
- Travelers:Aviation-compliant 100Wh limits and compact form factors prioritize TSA-friendly dimensions for carry-on compliance.
- Outdoor Enthusiasts:IP ratings and ruggedized enclosures withstand moisture and impact exposure in remote terrain.
- Students:Price-sensitive campus demographics favor 10000mAh economy tiers with basic USB-A output.
Professionals hold installed capacity. Travelers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in portable chargers tilt heavily toward surplus economies with integrated cell manufacturing. Import-dependent markets absorb finished units while regulatory divergence shapes compliance costs and shelf access timelines.
China
Shenzhen and Dongguan host over seventy percent of global lithium-ion cell production and finished-goods assembly. The GB 31241 cell safety standard and MIIT oversight tighten product certification thresholds for domestic circulation and re-export. Guangdong province's Pearl River Delta corridor concentrates silicon-anode R&D with suppliers pushing 20000mAh capacities into pocket-sized form factors.
United States
Mobile gaming professionals and live-streaming content creators drive demand for 65W-100W GaN-enabled units capable of laptop-and-smartphone simultaneous charging. FCC Part 15 emissions compliance and FAA 100Wh aviation limits shape product specifications and carry-on eligibility. California's Bay Area and Austin, Texas anchor distributor headquarters and direct-to-consumer brand operations.
India
Tier-two and tier-three city consumers exhibit low brand awareness but acute price sensitivity, rewarding localized offline retail partnerships over pure e-commerce penetration. BIS compulsory registration for lithium-ion cells adds compliance layers for cross-border suppliers targeting the subcontinent. Maharashtra and Karnataka host assembly operations and distribution hubs serving the western and southern regional markets.
Germany
Berlin pilots subscription-based power bank swap programs displacing outright ownership among smartphone-dependent gig workers. CE marking under the EU Low Voltage Directive and evolving Battery Regulation traceability mandates determine market access and shelf presence. Bavaria's industrial corridor hosts logistics operations and regional headquarters for brands serving Central European distribution networks.
Japan
Urban commuters prioritize ultra-compact 5000mAh-10000mAh units with optimal weight-to-runtime ratios for daily carry. METI efficiency standards and PSE certification requirements filter product entries into the domestic retail channel. Tokyo-Osaka logistics corridors concentrate e-commerce fulfillment and electronics retail chain procurement operations.
Portable Charger Market Competitive Environment
On the supply side, the industry is bifurcated between Shenzhen-anchored contract manufacturers and brand-holding entities with direct-to-consumer channel control. Assembly capacity clusters in Guangdong province while design ownership and pricing power concentrate with firms capturing GaN semiconductor integration and certification expertise. Three archetypes dominate: vertically integrated cell-to-shelf operators, brand licensors leveraging white-label manufacturing, and component specialists supplying power management semiconductors. Capacity expansion and strategic partnerships with offline retail distributors constitute the primary competitive moves across tiers.
Within the brand-holding tier, Anker Innovations Technology and Baseus occupy positions exemplifying divergent channel strategies, while Ambrane India anchors the India-focused offline retail archetype. These entities represent contrasting approaches to geographic penetration and product portfolio configuration without implying specific operational or financial performance.
| Leading Market Players |
|---|
| ADATA Technology |
| BioLite |
| Anker Innovations Technology |
| Zendure |
| Lion Energy |
| Baseus |
| Ambrane India |
| Elecom |
| Mophie |
| Others |
Value Chain & Pricing Dynamics
Shenzhen cell suppliers and Guangdong assembly corridors concentrate upstream capacity, anchoring margin pools downstream with brand-holding entities that command GaN semiconductor integration and multi-jurisdiction certification expertise.
Pricing Analysis
Live-streaming content creators and mobile gaming professionals anchor premium tier pricing for 65W-100W GaN-enabled units. Pricing stratifies across premium, standard, and economy tiers based on wattage output and IEC 62133 certification grade. Cost compression in the 10000mAh mass-market tier is intensifying because silicon-anode cell chemistries from Shenzhen suppliers expand pocket-sized capacity envelopes. Students and tier-three Indian city consumers exhibit highest price sensitivity, while professional creators show lowest sensitivity due to uptime dependency.
Supply Chain Analysis
Contract manufacturers in Shenzhen, Dongguan, and surrounding Pearl River Delta clusters hold dominant assembly capacity for finished-goods production. The supply chain draws from lithium carbonate brine processing in Chile, cobalt mining output from the DRC, and silicon-anode R&D concentrated in Guangdong province. Single-source vulnerability to Guangdong power rationing or logistics disruptions constitutes the primary structural risk. Distribution runs through direct-to-consumer brand channels, offline retail partnerships in India, and subscription-based swap programs piloted in Berlin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal engineering expertise in computational fluid dynamics and multi-layer PCB stack design sits in acute shortage, constraining product miniaturization roadmaps and compressing development timelines for premium tier entrants.
For Market Incumbents: Entrench GaN semiconductor R&D leadership through captive power management IC sourcing relationships, while accelerating IEC 62133 pre-certification investments to extend product development cycle advantages against emerging white-label competitors. Defend channel control in India's tier-two and tier-three offline retail corridors through exclusive distribution partnerships that block e-commerce pure-plays. For New Entrants and Emerging Players: India's tier-two and tier-three city offline retail presents the most penetrable geographic whitespace, with localized distribution partnerships offering faster traction than saturated direct-to-consumer channels. Target 10000mAh economy tiers with basic USB-A output for price-sensitive student demographics, leveraging white-label manufacturing arrangements to compress capital requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers seeking exit liquidity amid certification cost escalation and working capital intensity. Five-to-ten year viability hinges on battery passport traceability software integration and direct cathode material sourcing relationships. Monitor EU Battery Regulation implementation velocity as the critical inflection signal for shelf-preservation capability.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Integration | Enables 100W outputs in sub-200g enclosures for professional creator segments. |
| EU Battery Regulation Compliance | Digital passport mandates favor assemblers with pre-integrated supply chain visibility software. |
| India Offline Retail Expansion | Tier-two and tier-three city partnerships outpace e-commerce discovery in brand-building. |
| Silicon-Anode Cell Procurement | Direct cathode material sourcing relationships compress input cost volatility exposure. |
| Subscription Service Launch | Berlin and Singapore pilots demonstrate gig worker willingness to swap ownership for uptime. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with product managers at Shenzhen contract manufacturers, certification laboratory directors, India offline retail distributors, and GaN semiconductor procurement leads; alongside secondary validation through MIIT production filings, BIS registration databases, EU Battery Regulation draft texts, and FCC Part 15 equipment authorization records. Bottom-up unit shipment estimates triangulated against top-down value reconstructions.
Forecast inputs span product type segmentation across power banks, wireless chargers, solar chargers, and battery cases; capacity tiers from 5000mAh through 30000mAh; technology protocols including USB-C, Quick Charge, and Qi charging; and end user categories distinguishing professionals, travelers, outdoor enthusiasts, and students. CAGRs were derived from elasticity-adjusted demand curves across the projection horizon, incorporating silicon-anode energy density improvement trajectories and EU Common Charger Directive adoption timelines.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by mid-tier assemblers or accelerated GaNFast adoption by new entrants would shift outcomes beyond modeled ranges. Quarterly review of IEC 62133 certification queue lengths and Guangdong province power rationing announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Digital Instrument Transformer Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market