
 Rugged Handheld Electronic Devices Market | 2026-2036
Rugged Handheld Electronic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Rugged Handheld Electronic Devices Market Outlook
The capital-intensity divergence between vertically integrated manufacturers and assembly-dependent competitors is collapsing as semiconductor packaging and precision enclosure fabrication consolidate under fewer rooflines. Zebra Technologies leverages captive supply chain control over thermal management subsystems to sustain margin structures that smaller rivals cannot replicate. Panasonic dominates the mil-spec certification pipeline, anchoring its position through direct relationships with defense procurement agencies across multiple continents.
Rugged handheld electronic devices are portable computing terminals engineered to withstand MIL-STD-810 shock and vibration parameters, IP65 or higher ingress protection ratings, and operating temperature extremes from -20°C to 60°C, primarily serving field personnel who require uninterrupted data access in hazardous or remote environments. The smartphones segment leads volume shipments due to its versatility across military patrol and field service workflows, while the asset tracking application commands premium pricing because it demands integrated UHF RFID readers and real-time GPS telemetry. Tablets compete most intensely in construction and manufacturing end-use settings where larger display formats support blueprint rendering and machine interface tasks.
FCC Part 15 emissions compliance governs radio frequency modules in US-bound units, while the EU Radio Equipment Directive and REACH substance restrictions shape material selection and market access for European deployments. Military buyers increasingly require NSA-approved Suite B cryptography and Common Criteria EAL4+ certification, filtering vendor eligibility to a narrow tier with dedicated security engineering capacity. Stakeholders must monitor how NIST's post-quantum cryptography migration timelines will force hardware refresh cycles and redesign investments across installed defense fleets.
Market Dynamics
Defense procurement agencies are consolidating vendor pools around Common Criteria EAL4+ certification holders, compressing supplier diversity while amplifying contract values for qualified manufacturers who can absorb multi-year security engineering cycles.
Growth Catalysts
- EU Radio Equipment Directive:CE marking mandates for electromagnetic compatibility are filtering out uncertified competitors and concentrating contract awards among pre-qualified vendors with established testing pipelines.
- Industrial automation:German manufacturing facilities are deploying hardened tablets for machine interface tasks, creating pull-through demand for MIL-STD-810 certified hardware in non-military settings.
- UHF RFID integration:Asset tracking workflows in logistics and defense supply chains require integrated readers, expanding the addressable market for devices with embedded radio modules.
Market Restraints
- Semiconductor packaging concentration:Advanced thermal management substrates depend on a handful of East Asian foundries, exposing margin structures to input volatility and geopolitical disruption.
- REACH substance restrictions:European chemical regulations are forcing material substitutions in enclosure fabrication, extending redesign timelines and recertification costs.
- Consumer smartphone durability:IP68-rated commercial devices are encroaching on low-end rugged applications, pressuring pricing for entry-tier hardened hardware.
Strategic Opportunities
- Post-quantum cryptography migration:NIST timeline pressures will force hardware refresh cycles across NATO defense fleets, opening replacement windows for vendors with NSA-approved Suite B engineering capacity.
- Construction digitization:Blueprint rendering on larger tablet formats remains underpenetrated in Central European building sites, offering volume expansion for MIL-STD-810G certified displays.
- Direct defense procurement:Bypassing systems integrators to contract directly with national procurement agencies is compressing channel margins while capturing full product lifecycle value.
Industry Challenges
- Security engineering talent scarcity:Common Criteria certification expertise concentrates in a narrow labor pool, constraining vendor scaling and extending bid preparation timelines.
- Multi-standard compliance:Simultaneous FCC Part 15, EU RED, and MIL-STD-810 validation creates testing bottlenecks that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rugged Handheld Electronic Devices Market |
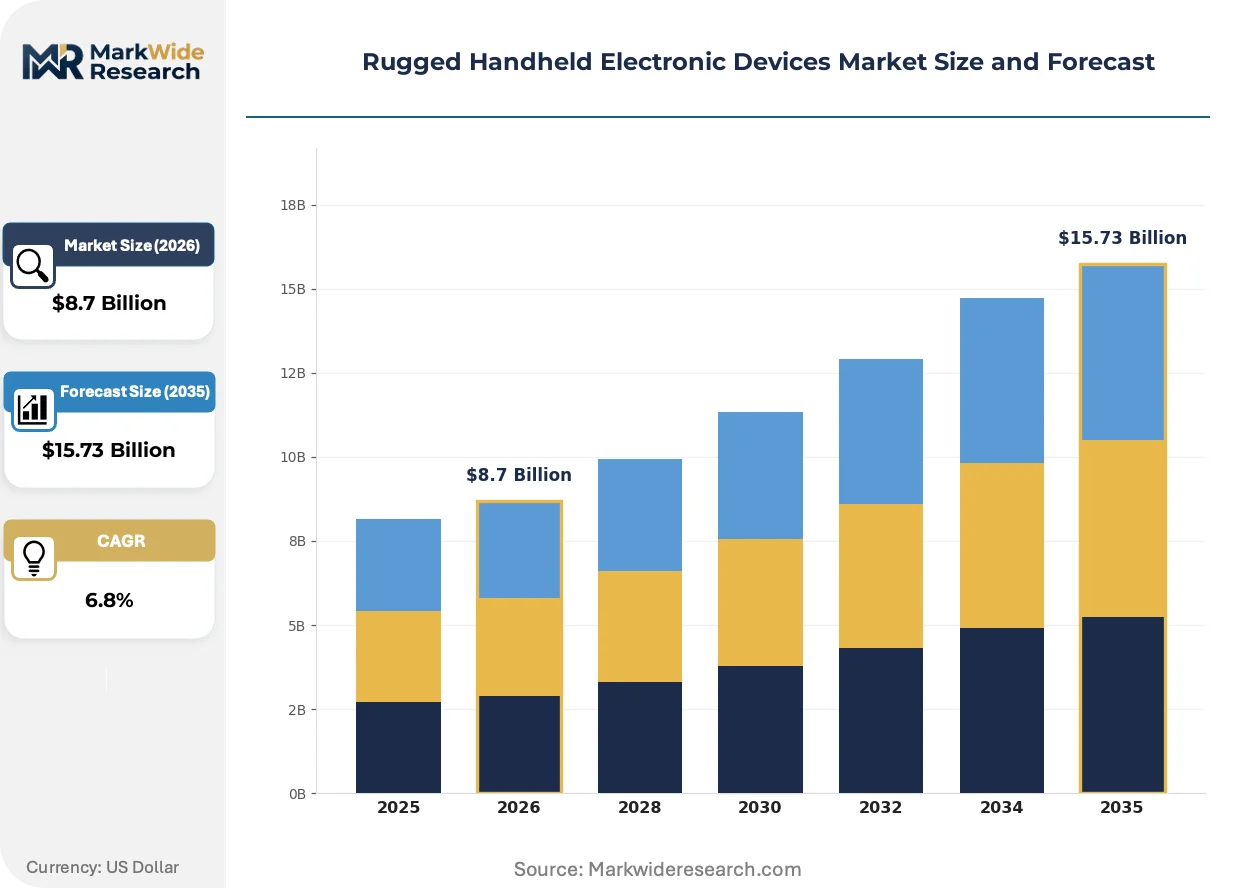
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Laptops, PDAs End User: Military, Construction, Field Services, Manufacturing Technology: Wi-Fi, Bluetooth, GPS, RFID Application: Data Capture, Asset Tracking, Mobile Communication, Inventory Management |
| Companies Covered | Getac Holdings Corp., Samsung Electronics Co., Zebra Technologies Corporation, Trimble Inc., Datalogic S.p.A., Honeywell International Inc., Juniper Systems Inc., Kyocera Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rugged Handheld Electronic Devices Market Strategic Shifts
Thermal management architectures and cryptographic hardware modules are undergoing simultaneous reinvention, reshaping how rugged devices balance computational density with environmental survivability.
Micro-encapsulated phase-change materials are displacing traditional graphite spreaders in thermal subsystems. Defense contractors in Germany and the United States are specifying these substrates for patrol computing loads exceeding 15W TDP. The shift is compressing vendor qualification lists to manufacturers with captive packaging capabilities or exclusive foundry relationships.
REACH substance restrictions are forcing halogen-free flame retardant adoption in enclosure polymers. European manufacturers face material reformulation costs while Asian competitors without EU market exposure maintain cost advantages. German industrial buyers are now demanding pre-certified halogen-free supply chains, transferring compliance burden upstream.
Defense procurement officers are consolidating multi-year fleet contracts around single-vendor cybersecurity architectures. Systems integrators who previously specified heterogeneous device pools are losing influence to agencies requiring uniform cryptographic modules. This concentration is most visible in NATO member state modernization programs, where Common Criteria EAL4+ certification has become a binary eligibility filter.
Rugged Handheld Electronic Devices Market Segmentation
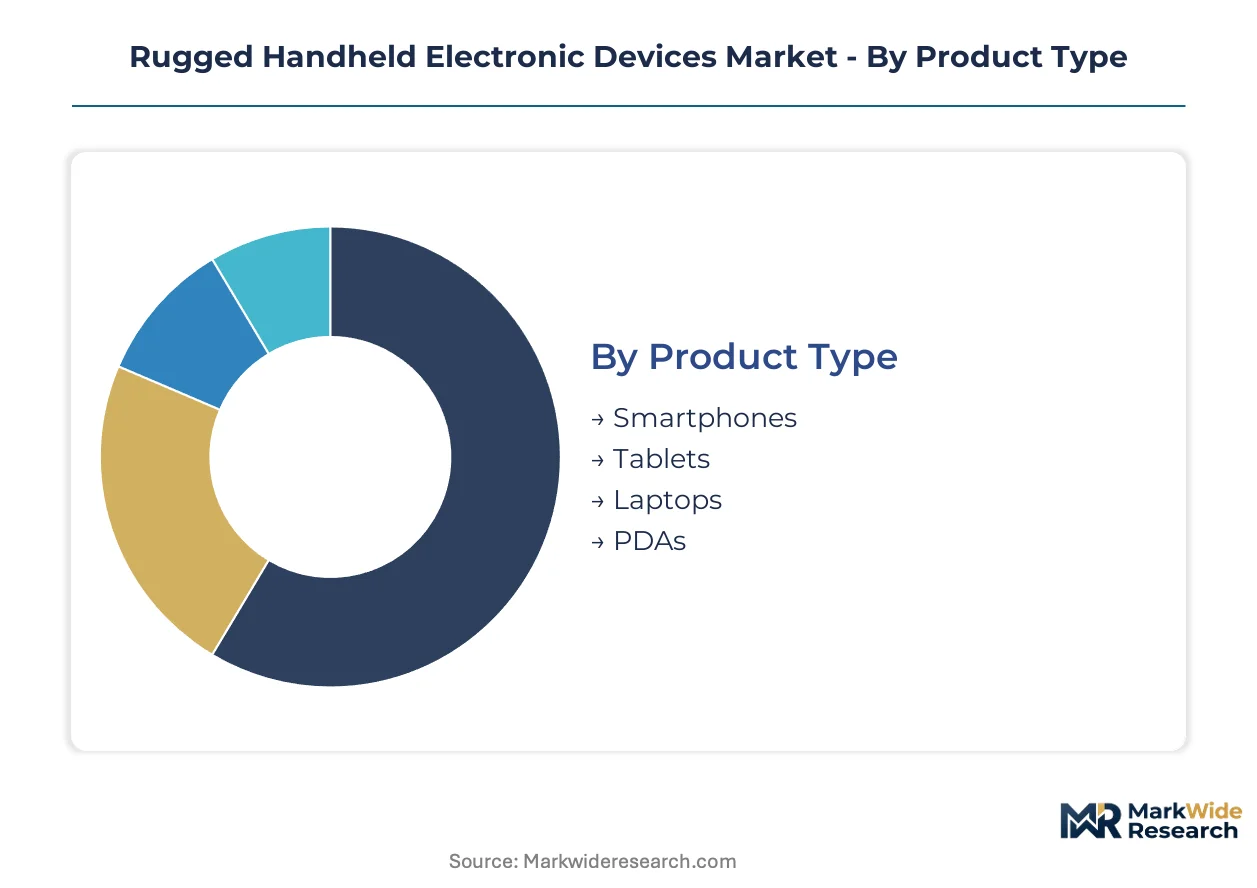
Rugged handheld devices fragment across four distinct taxonomies that shape procurement workflows and certification requirements. Product type governs thermal design and enclosure engineering. End-user verticals dictate security protocols and durability specifications. Technology integration determines radio compliance burdens. Application use cases set sensor and peripheral requirements.
Product Type:
FCC Part 15 emissions testing and MIL-STD-810 shock validation create divergent compliance timelines across form factors, with larger displays demanding more complex thermal management substrates.
- Smartphones:Compact form factors integrate MIL-STD-810H shock absorption with IP68 sealing in sub-300g packages. Patrol computing and field service workflows in Germany and the United States concentrate volume here, driven by NATO defense modernization programs requiring NSA-approved Suite B cryptography in pocketable devices.
- Tablets:10-inch and larger displays support blueprint rendering and machine interface tasks with 15W+ TDP processors. German manufacturing facilities and construction sites are pulling hardened tablets into non-military settings, expanding addressable demand beyond traditional defense procurement channels.
- Laptops:Full-keyboard rugged notebooks serve command center and vehicle-mounted applications with extended I/O port configurations. Military buyers specify these for forward operating base deployments.
- PDAs:Legacy form factors persist in warehouse inventory workflows requiring integrated barcode scanning and compact单手 operation. Logistics operators in Central Europe maintain installed bases.
Smartphones handle the majority of throughput; tablets are climbing the fastest on share.
End User:
Customer procurement authority fragments between defense agencies with multi-year security engineering cycles and industrial buyers with compressed decision timelines.
- Military:Common Criteria EAL4+ certification and NSA-approved cryptographic modules filter vendor eligibility to a narrow tier. NATO member state procurement agencies are consolidating vendor pools around qualified manufacturers, amplifying contract values for compliant suppliers.
- Construction:Blueprint rendering and site documentation drive demand for MIL-STD-810G certified tablets with sunlight-readable displays. Central European building sites remain underpenetrated for digitized workflows.
- Field Services:Utility inspection and telecom maintenance crews require uninterrupted connectivity across remote terrain. GPS and cellular redundancy specifications dominate procurement criteria.
- Manufacturing:German industrial automation investments are deploying hardened tablets for machine interface tasks, creating pull-through demand for military-grade hardware in factory floor settings.
Military commands the premium pricing tier; manufacturing is expanding most quickly as industrial automation accelerates.
Technology:
Radio module integration determines electromagnetic compatibility testing burdens and REACH substance restrictions on enclosure materials.
- Wi-Fi:Dual-band 802.11ax modules support high-throughput data sync in warehouse and manufacturing environments. EU Radio Equipment Directive CE marking mandates filter out uncertified competitors.
- Bluetooth:Low-energy protocols enable peripheral pairing with barcode scanners and biometric sensors. Field service workflows depend on reliable short-range connectivity.
- GPS:Multi-constellation receivers (GPS, GLONASS, Galileo) provide positioning redundancy for defense patrol and remote asset tracking applications.
- RFID:Integrated UHF readers command premium pricing in logistics and defense supply chains requiring real-time inventory visibility.
Wi-Fi anchors baseline connectivity configurations; RFID is gaining share fastest through asset tracking adoption.
Application:
Use case requirements stratify across sensor integration density and real-time telemetry demands.
- Data Capture:Integrated imagers and barcode engines support forms-based field documentation. Utility and inspection workflows drive specification requirements.
- Asset Tracking:UHF RFID readers combined with GPS telemetry enable real-time supply chain visibility. Defense logistics and commercial warehousing concentrate demand here.
- Mobile Communication:Push-to-talk and secure voice applications require hardened audio subsystems and encrypted radio modules. Military patrol computing prioritizes these capabilities.
- Inventory Management:Warehouse management system integration demands reliable wireless connectivity and ergonomic scan triggers. Third-party logistics providers specify these for fulfillment center deployments.
Data Capture handles the majority of installed base volume; Asset Tracking carries the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies in Germany absorb price premiums for Common Criteria EAL4+ certification without volume elasticity, while Indian logistics operators demand hardened smartphones at entry-tier price points where IP68 consumer devices compete aggressively.
Germany
Bundeswehr modernization programs and industrial automation investments in manufacturing facilities drive MIL-STD-810 certified tablet deployments. The EU Radio Equipment Directive tightens CE marking requirements for electromagnetic compatibility, filtering vendor eligibility. Bavarian defense contractors and Baden-Württemberg automotive suppliers anchor regional demand for machine interface hardware.
United States
NATO patrol computing requirements and NSA-approved Suite B cryptography mandates concentrate military procurement authority. FCC Part 15 emissions compliance governs radio frequency modules for domestic-bound units. Defense procurement agencies in Virginia and Texas consolidate multi-year fleet contracts around qualified vendors with dedicated security engineering capacity.
China
Domestic logistics operators and state-owned construction enterprises deploy hardened tablets for site documentation and inventory management. MIIT certification requirements and GB standards for electromagnetic compatibility shape product development timelines. Shenzhen-based electronics manufacturers and Beijing defense contractors represent distinct demand clusters with divergent security specifications.
United Kingdom
Ministry of Defence procurement programs require Common Criteria EAL4+ certification for field-deployed hardware, compressing supplier diversity. UKCA marking transitions post-Brexit create parallel testing obligations alongside residual CE marking requirements. Defence contractors in Bristol and London anchor demand for secure mobile communication terminals.
Japan
Construction digitization and utility inspection workflows pull hardened tablets into civil infrastructure applications. METI industrial standards and JIS certification requirements govern electromagnetic compatibility and environmental durability testing. Osaka-based industrial equipment suppliers and Tokyo metropolitan construction authorities drive specification requirements for sunlight-readable displays.
Rugged Handheld Electronic Devices Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated manufacturers commanding premium positioning through captive thermal management capabilities while assembly-dependent competitors compete on volume pricing. The vendor base concentrates around defense-certified specialists and industrial automation suppliers with overlapping but distinct certification pipelines. Two strategic archetypes dominate: full-stack manufacturers with in-house semiconductor packaging, and modular assemblers leveraging outsourced enclosure fabrication. Competitive moves center on direct defense procurement relationships and upstream integration into precision enclosure manufacturing.
Among diversified electronics conglomerates, Panasonic Corporation and Samsung Electronics Co. exemplify scale-driven archetypes with broad certification portfolios spanning consumer and industrial segments. Zebra Technologies Corporation anchors the specialized industrial tier with concentrated exposure to logistics automation and field service workflows. Getac Holdings Corp. and Trimble Inc. occupy positions within the defense-priority segment where Common Criteria EAL4+ certification serves as a binary market access filter. These named entities represent strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Getac Holdings Corp. |
| Samsung Electronics Co. |
| Zebra Technologies Corporation |
| Trimble Inc. |
| Datalogic S.p.A. |
| Honeywell International Inc. |
| Juniper Systems Inc. |
| Kyocera Corporation |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Multi-year defense procurement contracts lock in supply access for thermal management substrates while anchoring price visibility against semiconductor foundry volatility. These structures insulate qualified vendors from spot-market fluctuations in East Asian packaging capacity, transferring input risk to buyers through fixed-price escalation clauses tied to REACH compliance costs.
Pricing Analysis
After-sales service revenue streams including firmware security updates and extended warranty coverage drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by Common Criteria certification grade and integrated RFID capability. Pricing pressure stems from IP68-rated consumer smartphones encroaching on entry-tier rugged applications. Industrial automation buyers in Germany exhibit lowest price sensitivity due to downtime cost exposure, while Indian logistics operators prioritize unit economics over durability specifications.
Supply Chain Analysis
Taiwan and South Korea anchor advanced semiconductor packaging for thermal management substrates, while China dominates precision aluminum enclosure fabrication. Raw material dependencies span halogen-free flame retardant polymers, MIL-STD-certified shock absorption gaskets, and multi-constellation GPS modules. Single-source vulnerability concentrates in East Asian foundries producing micro-encapsulated phase-change materials. Distribution runs through defense systems integrators and industrial equipment distributors with certified installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment through Common Criteria EAL4+ certification creates switching costs that freeze out unqualified competitors. Procurement consolidation around NATO security architectures amplifies contract values for incumbent vendors.
For Market Incumbents: Secure captive foundry relationships for thermal management substrates to defend margin structures against input volatility from East Asian packaging concentration. Deepen Common Criteria engineering capacity ahead of NIST post-quantum cryptography migration timelines to capture hardware refresh cycles across defense fleets. For New Entrants and Emerging Players: Anchor in Central European construction digitization workflows where blueprint rendering tablets remain underpenetrated and certification requirements are less stringent than defense procurement. Target German manufacturing facilities deploying hardened tablets for machine interface tasks, leveraging industrial automation pull-through demand without military security engineering overhead. For Investors and Strategic Acquirers: Defense-certified component specialists with established NSA-approved Suite B engineering pipelines represent the highest-conviction acquisition archetype. Monitor NIST post-quantum cryptography standardization announcements as the inflection signal for hardware replacement cycle acceleration across NATO member states.| Strategic Initiative | Industry Significance |
|---|---|
| Common Criteria EAL4+ Certification Investment | Locks in NATO defense procurement eligibility and compresses supplier diversity. |
| Captive Thermal Management Subsystem Integration | Insulates margin structures from East Asian foundry concentration and geopolitical disruption. |
| Direct Defense Procurement Channel Development | Bypasses systems integrators to capture full product lifecycle value and compress channel margins. |
| Post-Quantum Cryptography Hardware Engineering | Positions vendors for NIST-mandated refresh cycles across installed defense fleets. |
| Halogen-Free Supply Chain Pre-Certification | Transfers REACH compliance burden upstream and filters out Asian competitors without EU market exposure. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of defense procurement databases, FCC equipment authorization filings, and EU CE marking registries. Interviews with defense procurement officers, industrial automation engineers, thermal management subsystem suppliers, and logistics operations directors inform demand-side validation. Customs trade data, SEC 10-K filings from diversified electronics conglomerates, and NATO standardization agreements provide supply-side triangulation. Bottom-up shipment estimates by product type and end-use vertical cross-validate against top-down market sizing by geographic defense expenditure.
Segmentation dimensions modeled span product type, end-user vertical, integrated technology module, and application use case across the analysis window. CAGRs derive from regression analysis of historical procurement cycles and projected defense modernization program spend. Forecast inputs incorporate REACH substance restriction phase-in timelines and NIST post-quantum cryptography migration schedules as structural demand drivers.
Material uncertainties — geopolitical disruption to East Asian semiconductor packaging capacity, accelerated consumer smartphone durability improvement, and unilateral regulatory shifts in electromagnetic compatibility standards — sit outside the modeled envelope. Forecasts reflect assumptions about certification pipeline durations and defense budget continuity. Recalibration cycles align with material shifts in NATO procurement consolidation patterns and NIST cryptographic standardization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Broadcasting Equipment Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Digital Instrument Transformer Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Global Hybrid Devices Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market