
 Blu-Ray Media and Devices Market | 2026-2036
Blu-Ray Media and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Blu-Ray Media and Devices Market Outlook
Japanese optical disc manufacturing is rebalancing around premium-tier output as mainstream streaming displaces volume sales. Sony Corporation leverages its studio content library to sustain hardware-disc ecosystem loyalty. Panasonic Corporation anchors professional archival disc production for broadcast and enterprise clients. Samsung Electronics competes in select regional markets where smart Blu-Ray player integration retains relevance.
Blu-Ray media and devices encompass optical storage systems utilizing 405nm blue-violet laser technology to read and write data on polycarbonate discs with 25GB to 128GB capacity per layer, designed for high-definition video distribution and long-term data archiving. Ultra HD Blu-Ray technology leads the premium tier with 4K HDR playback capability, while disc-based storage segments serve institutional archiving needs where magnetic media degradation poses unacceptable risk. Home entertainment application remains the largest addressable base, though commercial use segments command higher per-unit margins through specialized durability specifications.
FCC equipment authorization requirements govern US-market player electromagnetic compatibility, while RoHS substance restrictions shape European disc and component material compliance. Japan's METI administers JIS standards for optical media longevity testing that manufacturers must satisfy for domestic certification. Stakeholders must weigh physical media's niche persistence against streaming platform exclusivity strategies when allocating R&D and distribution resources.
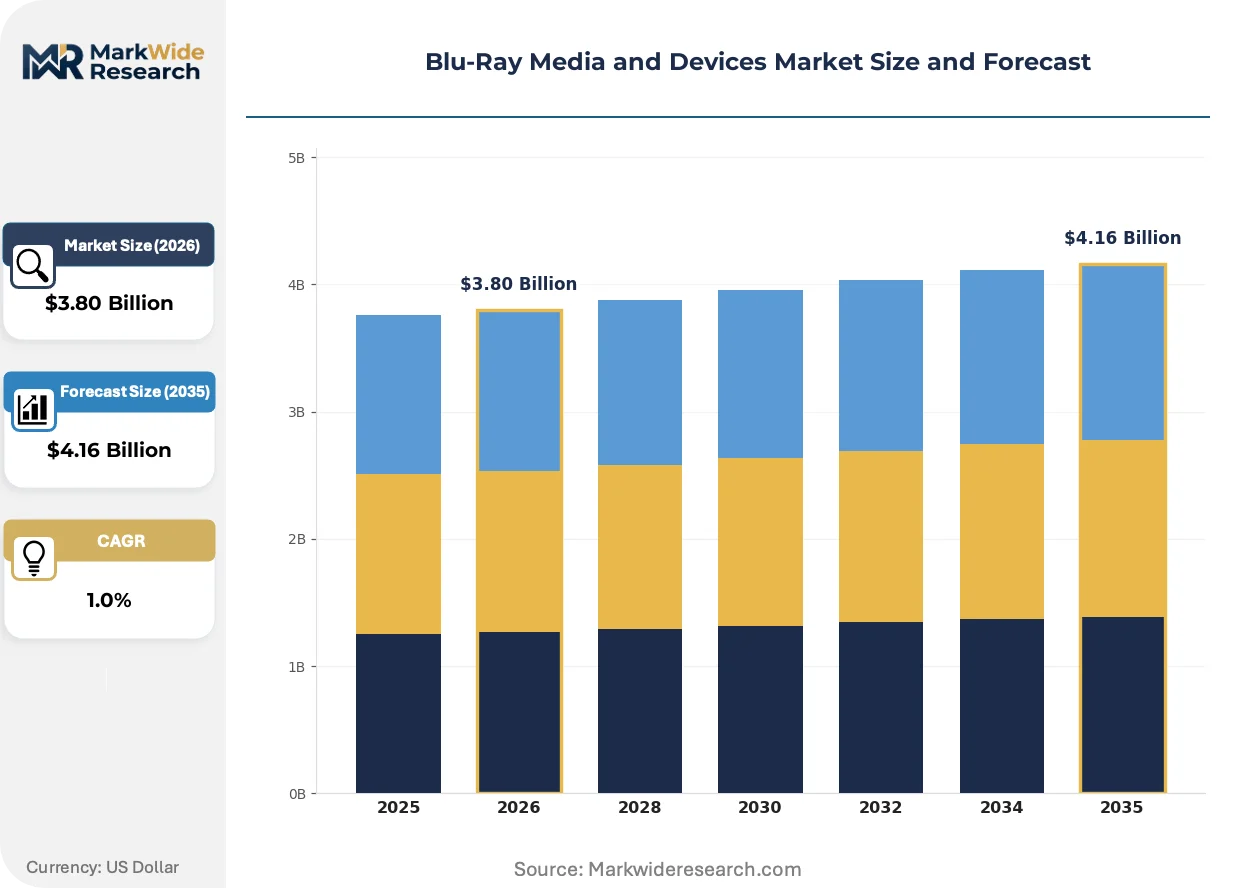
Market Dynamics
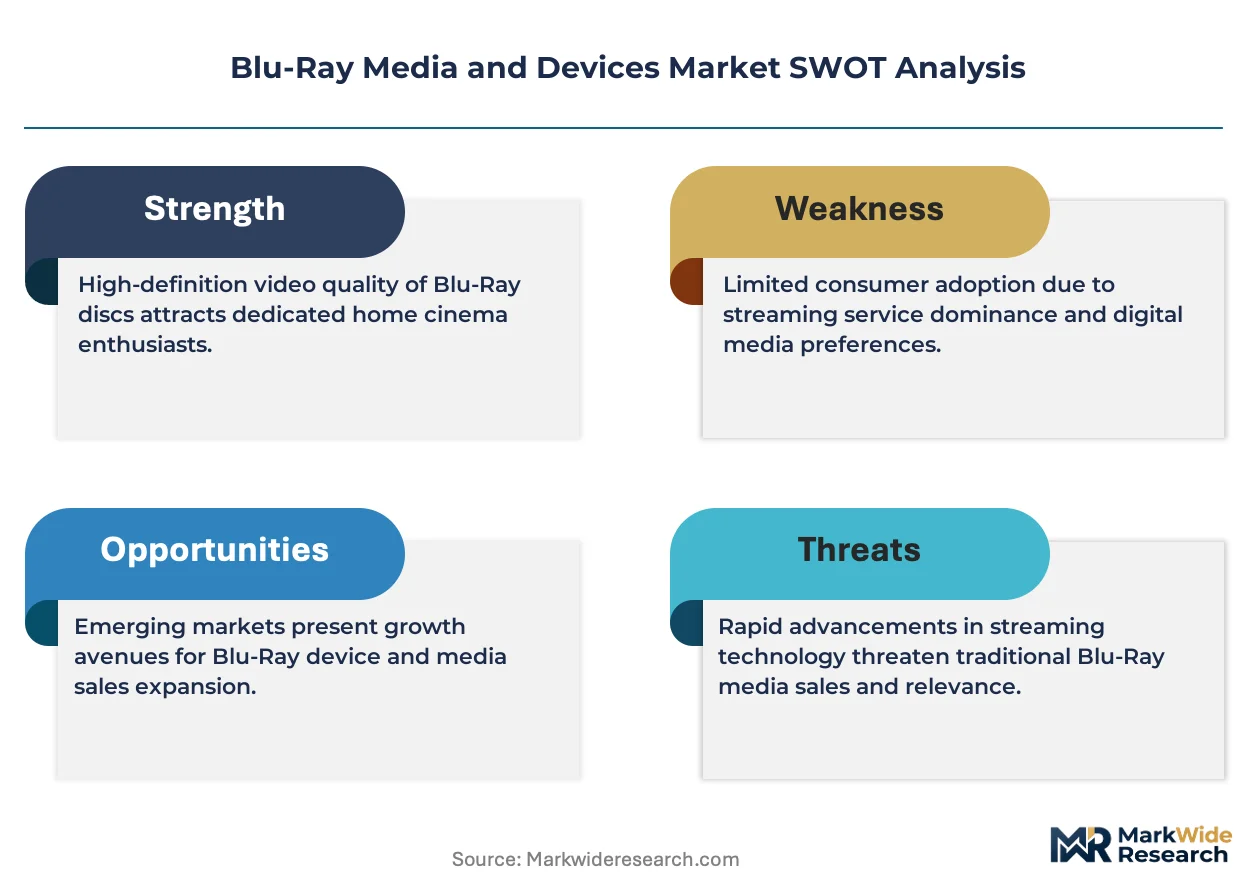
Streaming platform exclusivity strategies are fragmenting content libraries and forcing collector communities toward physical media ownership as a hedge against digital revocation. This structural tension between access models and permanence preferences defines competitive positioning for Blu-Ray hardware and media manufacturers.
Growth Catalysts
- Collector Community Persistence:Home theater enthusiasts in Japan and North America sustain demand for premium physical editions with exclusive artwork and bonus content unavailable on streaming services.
- Archival Mandates:Broadcast and enterprise clients in Japan face METI durability standards that optical disc formats satisfy more reliably than magnetic tape alternatives for long-term asset preservation.
- Ultra HD Format Differentiation:4K HDR playback capability on Ultra HD Blu-Ray offers bitrate advantages that compressed streaming cannot match, preserving a technical moat for discerning viewers.
Market Restraints
- Polycarbonate Supply Concentration:Optical-grade polycarbonate resin production concentrates among Asian petrochemical suppliers, exposing margins to feedstock volatility and freight cost spikes.
- Streaming Substitution:Subscription video-on-demand platforms now control exclusive distribution for major studio releases, compressing the theatrical-to-physical window and reducing impulse purchase occasions.
- Laser Diode Import Dependencies:405nm blue-violet laser component manufacturing clusters in specific East Asian manufacturing zones, creating single-source vulnerability for player assembly lines.
Strategic Opportunities
- Professional Archival Expansion:Cold storage data centers in Germany and Japan are evaluating optical disc libraries for compliance with GDPR and METI retention mandates that prohibit magnetic media degradation risks.
- Hybrid Physical-Digital Bundles:Studio packaging strategies combining Blu-Ray discs with digital redemption codes are capturing dual-preference households unwilling to commit exclusively to either format.
- Specialized Retail Channel Development:Direct-to-consumer specialty retailers in Osaka and Los Angeles are building curated inventory systems for out-of-print catalog titles and import editions.
Industry Challenges
- Mastering Engineer Scarcity:Video compression and color grading expertise for HDR10+ and Dolby Vision optical disc authoring now concentrates among retiring specialists in Tokyo and Burbank.
- Replication Equipment Obsolescence:Stampers and injection molding lines for dual-layer disc production face parts availability constraints as original equipment manufacturers exit the market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blu-Ray Media and Devices Market |
| Market Size in 2026 | $3.80 Billion |
| Market Size in 2035 | $4.16 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blu-Ray Players, Blu-Ray Discs, Players with Streaming, Home Theater Systems Technology: 3D Blu-Ray, Ultra HD Blu-Ray, Disc-Based Storage, Digital Copy Application: Home Entertainment, Gaming, Educational Content, Commercial Use Customer Type: Individual Consumers, Retailers, Educational Institutions, Businesses |
| Companies Covered | Sony Corporation, Panasonic Corporation, Samsung Electronics, LG Electronics, Koninklijke Philips N.V., Pioneer Corporation, Toshiba Corporation, Sharp Corporation, RITEK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blu-Ray Media and Devices Market Strategic Shifts
Physical media manufacturers are pivoting toward premium-tier positioning as volume economics deteriorate, emphasizing durability certification and exclusive content packaging over mass-market penetration strategies.
Ultra HD Blu-Ray technology is absorbing the highest-margin segment of home video distribution as studios release collector editions with expanded color gamut and immersive audio formats. Archival institutions and broadcasters in Japan are adopting 100GB triple-layer discs for master file preservation, recognizing that this format is absorbing functions previously served by LTO tape in climate-controlled vaults.
Japan's METI has tightened JIS standards for optical media longevity testing, requiring manufacturers to demonstrate 50-year archival stability under accelerated aging protocols. Disc producers must now submit polycarbonate formulations and reflective layer compositions for third-party verification before domestic certification. European manufacturers exporting to Japan are reconfiguring material sourcing to satisfy these durability specifications, diverting engineering resources from cost reduction initiatives.
Collector purchasing patterns are fragmenting across multiple acquisition channels as specialty retailers develop subscription curation services for genre-specific enthusiasts. Japanese consumers increasingly preorder limited steelbook editions through boutique e-commerce platforms rather than mass-market electronics chains. North American buyers are rotating toward direct-from-studio storefronts for out-of-print restorations, compressing the traditional wholesale distribution tier.
Blu-Ray Media and Devices Market Segmentation
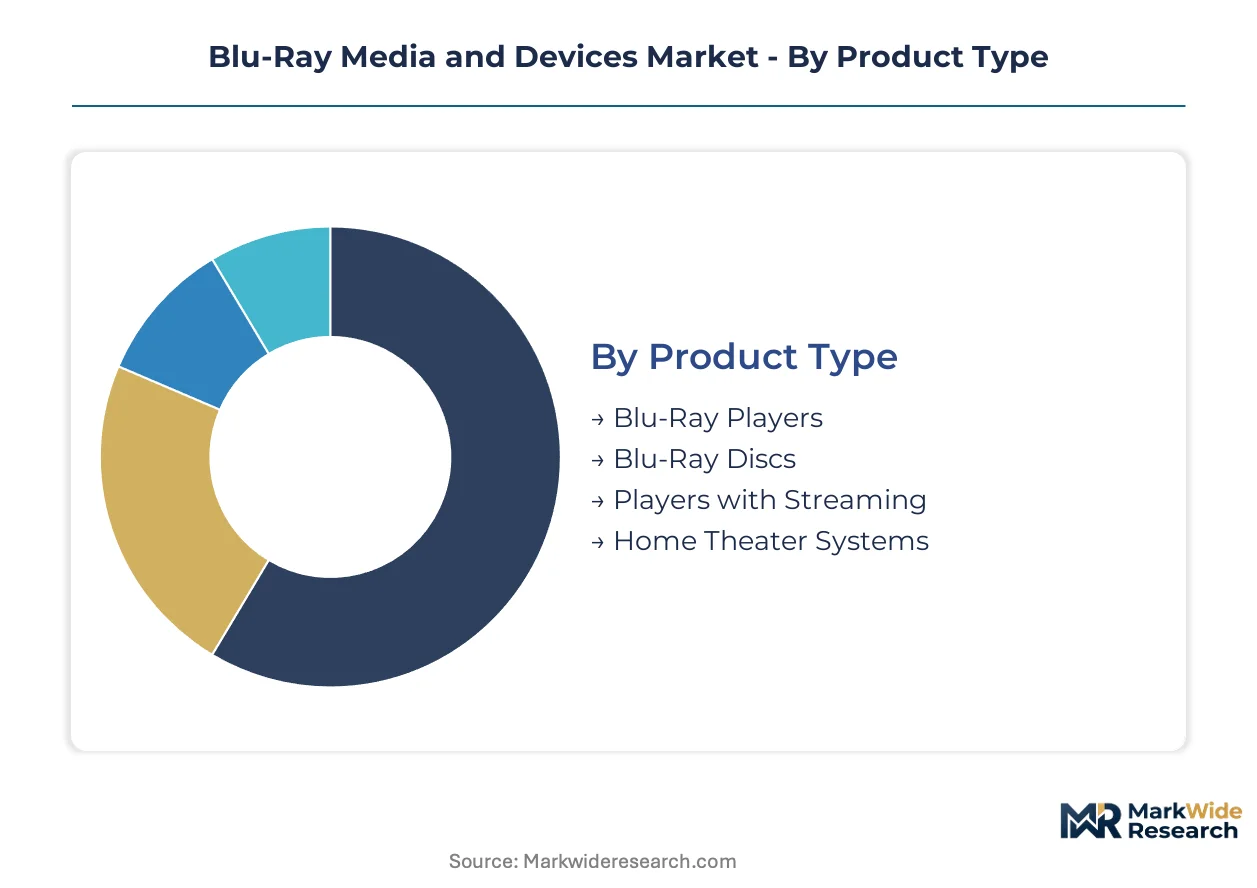
Blu-Ray market segmentation reveals divergent buyer priorities across hardware, media, and integrated systems. Purchase decisions hinge on format longevity, display compatibility, and archival reliability rather than unit cost alone.
Product Type:
Buyers weigh upfront hardware investment against content ecosystem lock-in when selecting physical media equipment.
- Blu-Ray Players:Standalone units process 405nm laser-read optical discs with HDMI 2.0 output for 1080p or 4K scaling. Demand concentrates in Japan and Germany where audiophile communities prioritize lossless audio bitstreaming over smart TV apps.
- Blu-Ray Discs:Polycarbonate substrates with reflective data layers store 25GB to 128GB per disc depending on layer configuration. Japanese collectors drive premium steelbook editions with exclusive bonus content unavailable through streaming redemption codes.
- Players with Streaming:Hybrid devices combine optical drives with Netflix and Amazon Prime Video applications. North American households with inconsistent broadband reliability favor this dual-access redundancy.
- Home Theater Systems:Integrated speaker arrays and amplification paired with disc playback. German and Austrian consumers purchasing complete living room upgrades represent the core addressable base.
Blu-Ray Discs lead on scale; Players with Streaming lead on momentum.
Technology:
Resolution thresholds and color depth specifications determine upgrade cycles among enthusiast buyers.
- Ultra HD Blu-Ray:3840x2160 resolution with HDR10 or Dolby Vision metadata on 66GB dual-layer or 100GB triple-layer discs. Japanese broadcasters adopting this format for master archive migration drive professional-tier procurement.
- Disc-Based Storage:Write-once and rewritable optical media for enterprise cold storage applications. German data centers evaluating GDPR-compliant retention systems favor this technology over magnetic tape degradation risks.
- 3D Blu-Ray:Stereoscopic frame packing for active-shutter or passive polarized displays. Niche home theater installations in Los Angeles and Tokyo sustain residual manufacturing runs.
- Digital Copy:Redemption codes bundled with physical purchases enabling cloud-based access. Studios deploy this hybrid strategy to capture dual-preference households unwilling to commit exclusively to either format.
Ultra HD Blu-Ray leads on scale; Disc-Based Storage leads on momentum.
Application:
Use case durability requirements separate consumer impulse purchases from institutional procurement mandates.
- Home Entertainment:Feature film and television series consumption in residential environments. Japanese consumers retain stronger physical media purchasing habits than any other national market.
- Commercial Use:Broadcast archive, medical imaging, and legal document retention with regulatory durability requirements. METI certification standards in Japan mandate 50-year stability verification for optical media in this segment.
- Gaming:PlayStation and Xbox physical software distribution. Declining retail shelf space in North American big-box chains compresses this channel's viability.
- Educational Content:Documentary and instructional media for classroom deployment. Budget constraints in public school systems favor streaming subscriptions over per-unit disc procurement.
Home Entertainment leads on scale; Commercial Use leads on momentum.
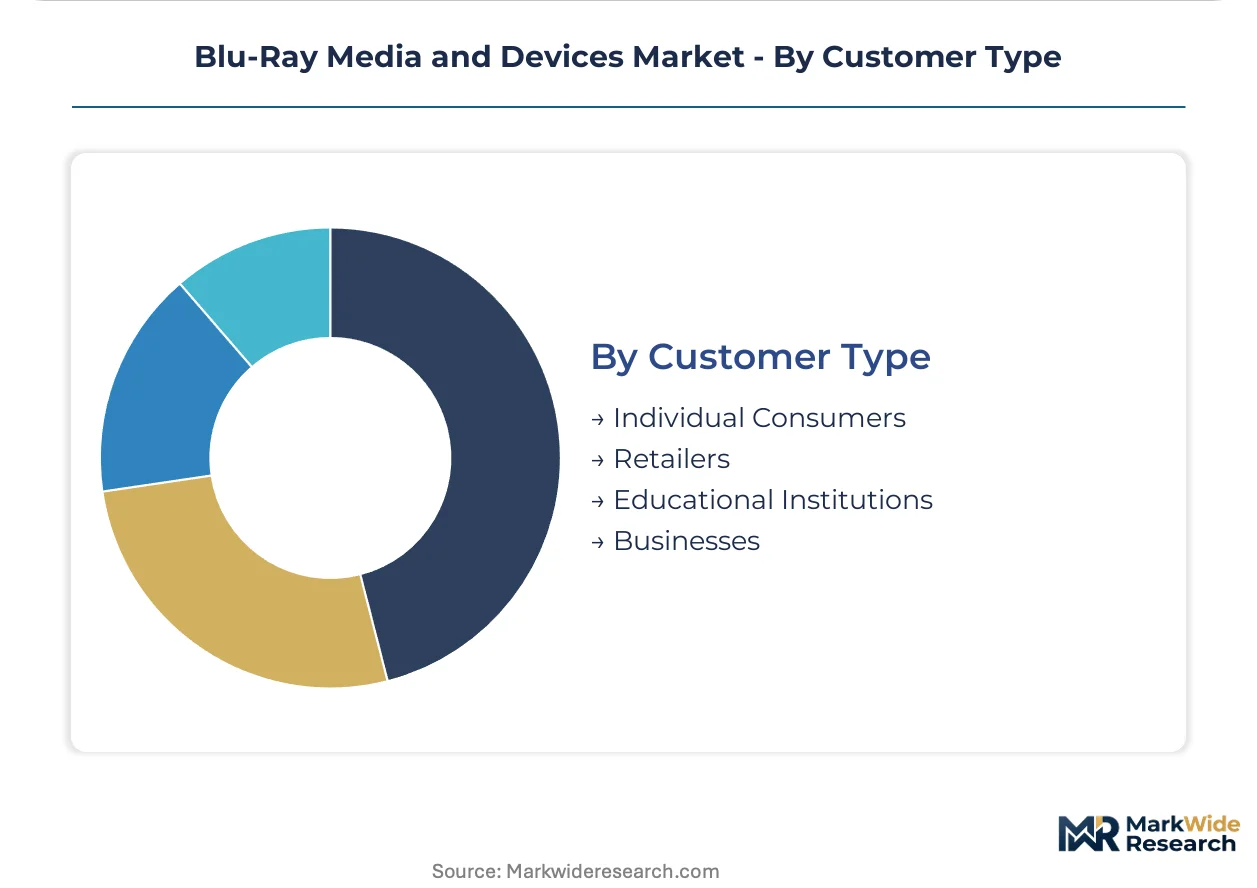
Customer Type:
Procurement authority and volume scale create divergent pricing tolerance across buyer categories.
- Individual Consumers:End-users purchasing single units or small media collections. Collector communities in Osaka and Los Angeles preorder limited editions through boutique e-commerce platforms.
- Businesses:Corporate entities acquiring archival hardware and media for compliance storage. Japanese enterprises subject to METI retention mandates represent the highest-margin account type.
- Retailers:Electronics chains and specialty shops maintaining inventory for walk-in customers. Direct-to-consumer studio storefronts are compressing this tier's margin capture on catalog titles.
- Educational Institutions:Universities and libraries acquiring media for research or lending collections. Acquisition budgets increasingly favor digital licensing over physical ownership.
Individual Consumers leads on scale; Businesses leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan sustains stronger physical media purchasing habits than Germany, yet both markets diverge sharply in regulatory drivers and hardware specialization.
Japan
Collector communities in Tokyo and Osaka drive premium steelbook editions with exclusive bonus content. METI administers JIS standards for optical media longevity testing that manufacturers must satisfy for domestic certification. Domestic manufacturers anchor premium hardware production in the Kanto region, serving both consumer and professional archival segments.
Germany
Audiophile communities prioritize lossless audio bitstreaming over smart TV apps, sustaining demand for standalone players. RoHS substance restrictions shape disc and component material compliance for European market access. Cold storage data centers in Bavaria evaluate optical disc libraries for GDPR-compliant retention systems.
United States
Hybrid devices combining optical drives with streaming applications attract households with inconsistent broadband reliability. FCC equipment authorization requirements govern player electromagnetic compatibility for US market entry. Specialty retailers in Los Angeles build curated inventory systems for out-of-print catalog titles and import editions.
South Korea
Component manufacturing clusters for 405nm blue-violet laser diodes create single-source vulnerability for player assembly lines. MFDS standards influence medical imaging archive specifications where optical media competes with magnetic alternatives. Seoul-based electronics fabricators supply laser modules to downstream device assemblers across Northeast Asia.
United Kingdom
Direct-to-consumer studio storefronts compress traditional wholesale distribution tiers for catalog title sales. CE marking requirements align with broader European conformity assessment procedures. London-based specialty distributors serve collector demand for limited edition imports from Japanese and North American markets.
Blu-Ray Media and Devices Market Competitive Environment
Japanese producers anchor the premium hardware and media tier; South Korean specialists hold component supply positions for laser diodes and optical assemblies. The vendor base concentrates around integrated electronics conglomerates with legacy optical expertise, creating a consolidated structure with limited new entry. Two strategic archetypes dominate: studio-affiliated hardware manufacturers leveraging content libraries for ecosystem loyalty, and pure-play component suppliers serving professional archival markets. Competitive moves center on portfolio diversification into hybrid physical-digital bundles and strategic partnerships with cold storage data center operators.
Within the studio-affiliated tier, Sony Corporation and Panasonic Corporation exemplify integrated strategies spanning content ownership through hardware manufacturing. Samsung Electronics occupies a position bridging consumer electronics scale with selective regional market presence where smart player integration retains relevance. These three anchors represent divergent responses to streaming substitution pressure, with varying emphasis on professional archival certification versus home entertainment volume.
| Leading Market Players |
|---|
| Sony Corporation |
| Panasonic Corporation |
| Samsung Electronics |
| LG Electronics |
| Koninklijke Philips N.V. |
| Pioneer Corporation |
| Toshiba Corporation |
| Sharp Corporation |
| RITEK Corporation |
| Others |
Value Chain & Pricing Dynamics
Ultra HD Blu-Ray mastering migration is compressing per-unit production economics while concentrating premium-tier margins among METI-certified Japanese manufacturers. This dual-layer technology transition simultaneously elevates material specifications for polycarbonate substrates and reflective layers, reshaping cost structures and supplier power across the optical media value chain.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for 405nm laser diode components, intensifying cost competition in player assembly tiers. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified archival discs from consumer-grade media and unbranded import alternatives. Price differentiation hinges on durability certification tier and volume procurement scale, with Japanese broadcasters exhibiting lowest price sensitivity due to regulatory compliance mandates. Cost compression in entry-level players is intensifying because smart TV integration has commoditized basic HDMI output functionality.
Supply Chain Analysis
Single-source vulnerability sits with South Korean laser diode foundries serving 405nm blue-violet component demand across Northeast Asian assembly lines. Manufacturing gravity centers on Japan, South Korea, and Taiwan for optical-grade polycarbonate resin, precision stampers, and injection molding equipment. Raw material dependencies include petrochemical feedstocks for substrate production, rare-earth elements for laser phosphors, and sputtering targets for reflective layer deposition. Tariff exposure on precision optical components creates margin volatility for European and North American device assemblers. Distribution runs through direct-to-consumer studio storefronts and specialty retailers, bypassing traditional wholesale tiers for collector-grade editions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's METI 50-year archival stability mandate operates as a regulatory compounder, transforming compliance certification into a durable pricing moat for domestic manufacturers serving broadcast and enterprise cold storage procurement.
For Market Incumbents: Hedge streaming substitution risk by deepening backward integration into polycarbonate formulation R&D and securing exclusive studio licensing for premium steelbook editions. METI certification investment represents the critical defensive lever against emerging archival tape competitors. Capacity discipline in legacy replication equipment sustains scarcity pricing for out-of-print catalog restorations. For New Entrants and Emerging Players: GDPR in Germany opens a window for GDPR-compliant optical disc library solutions targeting Bavarian data centers evaluating magnetic media degradation risks. Professional archival segments in Japan and Germany present the most penetrable white-space targets given regulatory durability mandates that streaming infrastructure cannot satisfy. A certification-first go-to-market angle emphasizing third-party longevity verification distinguishes entrants from commodity disc suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play optical media component suppliers with stranded capacity in legacy CD-R/DVD-R equipment. Long-term viability over the coming decade hinges on successful pivot toward professional archival certification and hybrid physical-digital bundle integration. The signal to watch is studio commitment to Ultra HD Blu-Ray exclusive windowing for collector editions, indicating sustained physical media R&D prioritization against streaming exclusivity strategies.| Strategic Initiative | Industry Significance |
|---|---|
| METI Certification Investment | Japanese manufacturers securing 50-year archival verification capture premium pricing in broadcast procurement. |
| Hybrid Bundle Development | Studio packaging strategies combining discs with digital redemption codes capture dual-preference households. |
| Laser Diode Supply Agreement | Long-term contracts with Seoul-based foundries mitigate single-source vulnerability in 405nm component supply. |
| Direct-to-Consumer Channel | Boutique e-commerce platforms in Osaka and Los Angeles bypass wholesale margin compression for collector editions. |
| Professional Archival Partnership | Cold storage data center alliances in Germany and Japan anchor enterprise revenue against consumer volume decline. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with optical media plant managers, broadcast archive directors, studio physical media executives, and specialty retailer buyers with secondary validation. SEC filings from Sony and Panasonic, METI certification registries, Japanese customs trade data, and European RoHS compliance databases anchored supply-side assessments. Bottom-up disc production volume estimates and top-down consumer expenditure tracking were triangulated against manufacturer shipment disclosures.
Historical reference periods spanning the streaming platform proliferation era established baseline substitution rates for physical media demand modeling across the projection horizon. Segmentation dimensions included product type, resolution technology tier, application durability requirements, and customer procurement authority. CAGRs were derived from regression analysis against broadband penetration curves and collector community purchasing surveys, with Ultra HD format adoption rates and professional archival procurement cycles serving as key forecast inputs.
Revisions become necessary when streaming exclusivity windows extend beyond theatrical release, when polycarbonate feedstock costs spike due to petrochemical volatility, or when replication equipment parts availability constraints accelerate. Forecasts reflect documented assumptions about regulatory durability standard maintenance and studio commitment to physical premium editions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
AV Surge Protectors Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Broadcasting Equipment Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Global Hybrid Devices Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market