
 Digital Instrument Clusters Market | 2026-2036
Digital Instrument Clusters Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Instrument Clusters Market Analysis
Buyer concentration among tier-one automotive OEMs is hardening as vehicle manufacturers consolidate supplier rosters around full-stack cockpit integrators. Continental AG leverages its display and software bundling to lock in multi-year platform contracts. Robert Bosch GmbH sustains engineering density in Stuttgart through captive semiconductor sourcing for cluster controllers. Visteon Corporation anchors North American share by specializing in reconfigurable digital architectures for electric vehicle programs.
A digital instrument cluster is an electronic display system replacing mechanical gauges, combining thin-film transistor liquid-crystal or organic light-emitting diode panels with real-time vehicle data processing to present speed, battery state, navigation, and advanced driver-assistance alerts to operators. Fully digital product types now dominate new vehicle launches, while hybrid configurations retain residual share in cost-sensitive fleet segments. OLED technology variants command premium positioning for contrast ratio and power efficiency, though TFT-LCD occupies volume production due to mature supply chains and lower unit costs.
NHTSA visibility standards, ECE R121 regulations in Europe, and China's GB standards for dashboard readability collectively dictate minimum luminance, color gamut, and response time thresholds that shape product development roadmaps. OEMs must certify clusters across all three jurisdictions before platform deployment, forcing modular hardware designs that accommodate regional software overlays. Stakeholders should monitor how incoming EU software-type approval requirements and cybersecurity mandates reshape validation timelines and supplier qualification criteria.
Market Dynamics
Automotive OEMs are consolidating cockpit electronics procurement around full-stack integrators capable of delivering hardware-software bundles, compressing supplier rosters and elevating platform contract values for qualified system architects.
Growth Catalysts
- NHTSA Visibility Mandates:US safety regulations for driver information display luminance and response times are compelling OEMs to replace analog clusters with certified digital systems across vehicle lineups.
- OLED Panel Technology:Organic light-emitting diode variants deliver superior contrast ratios and power efficiency that electric vehicle manufacturers prioritize for extended range optimization.
- Bavaria Manufacturing Corridor:Premium automotive production concentration in southern Germany generates concentrated demand for reconfigurable digital architectures with integrated advanced driver-assistance alerts.
Market Restraints
- Semiconductor Supply Concentration:Captive sourcing of cluster controller chips by dominant tier-one suppliers limits second-tier competitors' access to critical components.
- Multi-Jurisdictional Certification Costs:Simultaneous NHTSA, ECE R121, and GB standard compliance forces modular hardware designs that inflate validation budgets.
- TFT-LCD Technology Lock-in:Mature liquid-crystal display supply chains and lower unit costs create switching friction for manufacturers evaluating OLED migration.
Strategic Opportunities
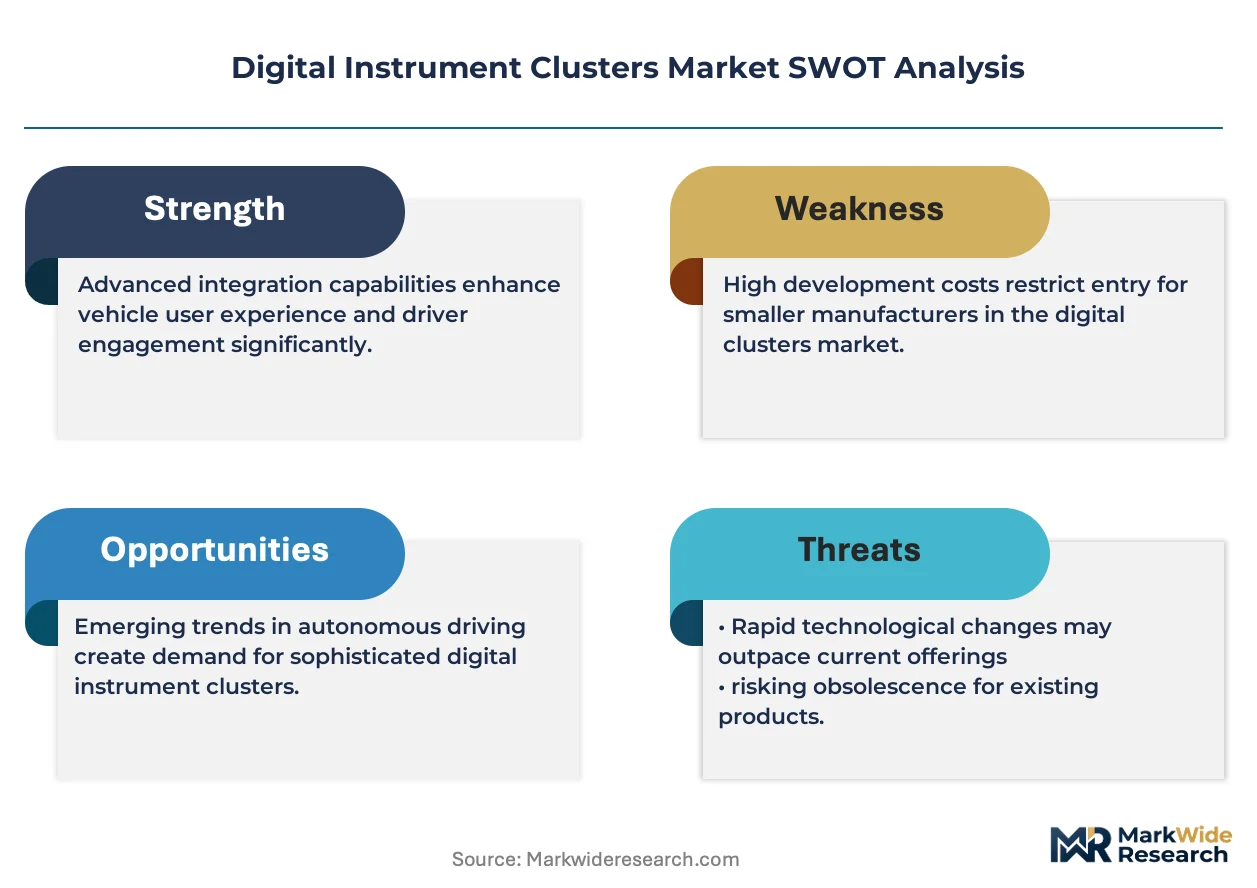
- EU Software-Type Approval Framework:Incoming cybersecurity and software validation requirements create qualification barriers that favor established integrators with existing regulatory relationships.
- Guangdong EV Manufacturing:Electric vehicle production expansion in China's southern manufacturing hub offers white space for cockpit system vendors with localized software overlay capabilities.
- Head-Up Display Convergence:Integration of windshield projection systems with instrument cluster data streams enables new premium feature bundling opportunities.
Industry Challenges
- Functional Safety Engineering Scarcity:ISO 26262-certified software architects remain concentrated at established suppliers, constraining new entrant scale-up velocity.
- Legacy Vehicle Platform Integration:Retrofitting digital clusters into existing electrical architectures requires custom gateway development that extends program timelines.
- Real-Time Operating System Licensing:Proprietary RTOS intellectual property from dominant automotive software vendors creates dependency and royalty cost pressures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Instrument Clusters Market |
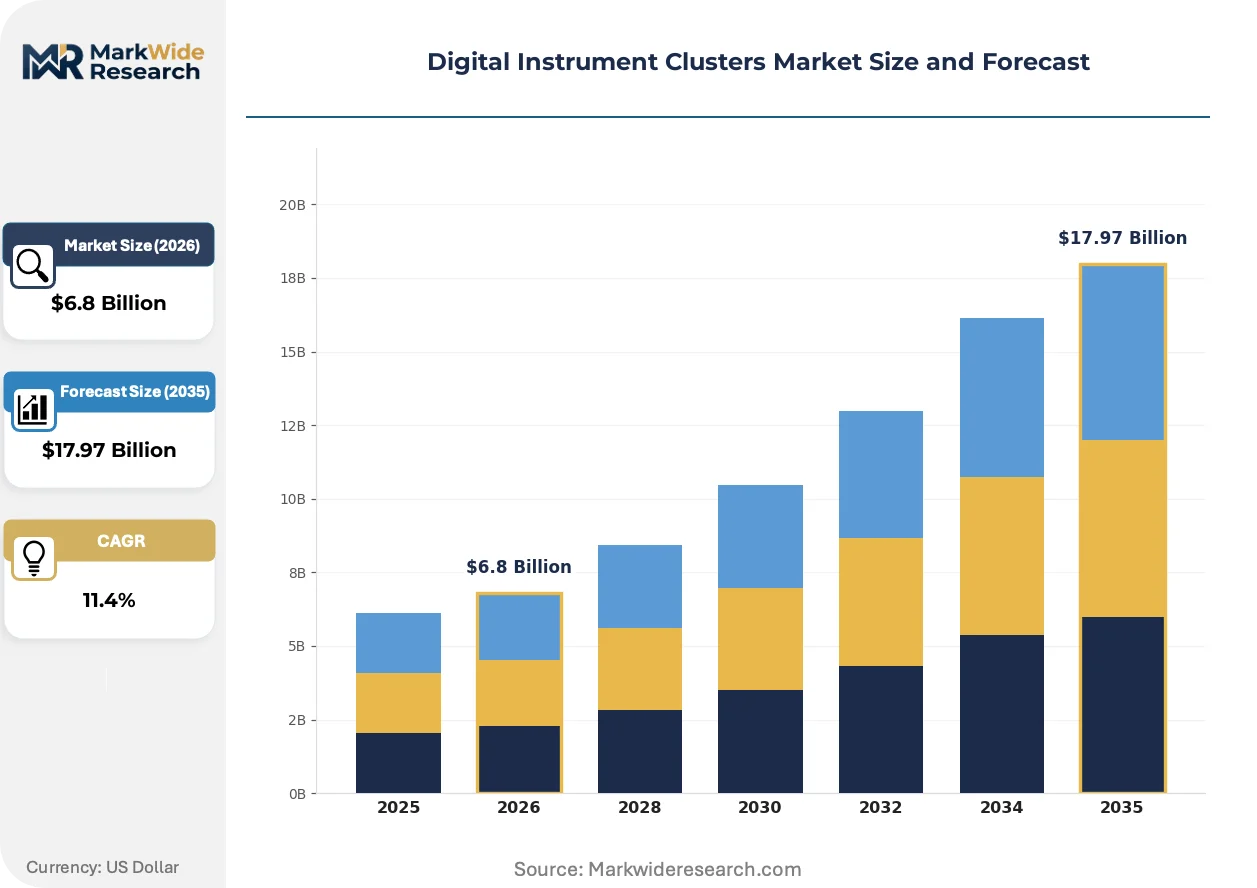
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analogue, Fully Digital, Hybrid, Virtual Technology: LCD, OLED, TFT, LED End User: OEMs, Aftermarket Providers, Fleet Operators, Custom Builders Integration Level: Standalone, Partially Integrated, Fully Integrated, Modular |
| Companies Covered | Continental AG, Visteon Corporation, Robert Bosch GmbH, DENSO Corporation, Yazaki Corporation, Nippon Seiki Co. Ltd., Magneti Marelli S.p.A., Panasonic Corporation, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Instrument Clusters Market Emerging Trajectories
Interface personalization and contextual information layering are redefining how drivers consume vehicle data, shifting competitive differentiation from hardware specifications to software-defined user experience architectures.
MicroLED display technology is integrating directly into curved cockpit surfaces to eliminate bezel boundaries between instrument clusters and center-stack infotainment screens. Premium electric vehicle programs in Germany and Japan are adopting these seamless panel configurations for flagship model differentiation. The technology is integrating previously separate display domains into unified visual fields that reduce driver cognitive load during navigation and advanced driver-assistance system interactions.
ECE R121 regulations in Europe are tightening color gamut and luminance uniformity requirements for dashboard readability under variable lighting conditions. OEMs must now certify cluster visibility performance across dawn, dusk, and direct sunlight scenarios before platform deployment. European premium manufacturers are responding by specifying automotive-grade OLED panels with ambient light sensors that auto-calibrate display output.
Fleet procurement managers are unbundling after-sales software update services from initial hardware contracts, creating recurring revenue streams for cockpit system vendors. Traditional single-transaction supplier relationships are giving way to multi-year service agreements covering over-the-air feature activation. This behavioral shift is most pronounced in North American commercial vehicle segments where total cost of ownership calculations now weight software lifecycle value against upfront hardware expenditure.
Digital Instrument Clusters Market Segmentation
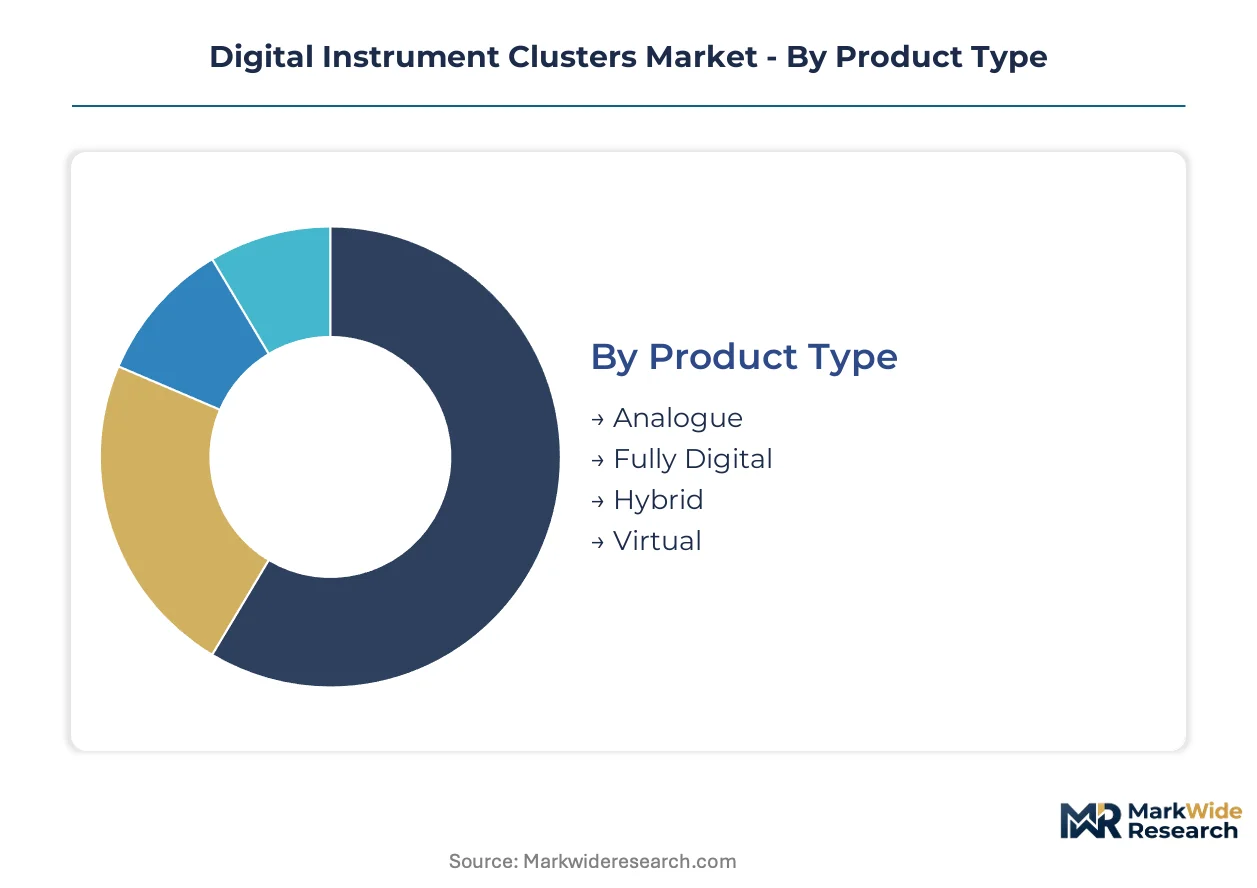
Digital instrument cluster procurement varies sharply by technical specification and supply chain configuration. Capital allocation, certification requirements, and integration complexity create divergent margin profiles across segment boundaries.
Product Type:
Fully digital configurations demand the heaviest upfront engineering investment for software architecture and safety certification.
- Fully Digital:Thin-film transistor liquid-crystal or organic light-emitting diode panels replace all mechanical gauges, requiring real-time vehicle data processing and multi-jurisdictional NHTSA, ECE R121, and GB standard compliance. Electric vehicle OEMs in Germany and Japan concentrate procurement here for extended range optimization and advanced driver-assistance integration.
- Hybrid:Combines analog gauges with digital displays, reducing semiconductor content and certification burden. Fleet operators in cost-sensitive segments favor this architecture where total cost of ownership calculations prioritize hardware durability over feature flexibility.
- Analogue:Traditional mechanical instrumentation retains residual share in emerging market commercial vehicles and legacy platform extensions where electrical architecture retrofit costs prove prohibitive.
- Virtual:Projection-based systems eliminate physical dashboard hardware entirely, with premium German manufacturers piloting windshield-integrated implementations for flagship differentiation.
Fully digital absorbs the bulk of installed capacity; virtual configurations are expanding most quickly.
Technology:
Panel selection determines power consumption, contrast performance, and supply chain vulnerability to semiconductor allocation constraints.
- OLED:Organic light-emitting diode technology delivers superior contrast ratios and power efficiency through self-emissive pixel architecture. Bavaria-based premium manufacturers specify automotive-grade panels with ambient light sensors for ECE R121-compliant auto-calibration.
- TFT:Thin-film transistor liquid-crystal displays dominate volume production through mature supply chains and lower unit costs. Michigan-based electric vehicle programs anchor North American demand for reconfigurable architectures.
- LCD:Legacy liquid-crystal configurations without thin-film transistor backing retain niche presence in cost-optimized fleet retrofits and developing market entry vehicles.
- LED:Light-emitting diode backlighting supports hybrid cluster illumination and indicator functions where full panel replacement remains uneconomical.
TFT commands the largest production footprint; OLED is climbing the fastest.
End User:
Procurement authority concentration shapes contract structure from multi-year platform agreements to transactional aftermarket supply.
- OEMs:Original equipment manufacturers consolidate supplier rosters around full-stack cockpit integrators capable of hardware-software bundling, elevating platform contract values and extending validation timelines.
- Fleet Operators:Commercial vehicle procurement managers unbundle after-sales software update services from initial hardware contracts, creating recurring revenue streams for cockpit system vendors.
- Aftermarket Providers:Independent distributors serve legacy vehicle retrofit demand where custom gateway development extends program timelines but opens margin opportunities unavailable in captive OEM supply.
- Custom Builders:Low-volume specialty manufacturers source modular cluster components for bespoke electrical architectures, prioritizing configurability over economies of scale.
OEMs lock in the majority of forward capacity; fleet operators are gaining share fastest.
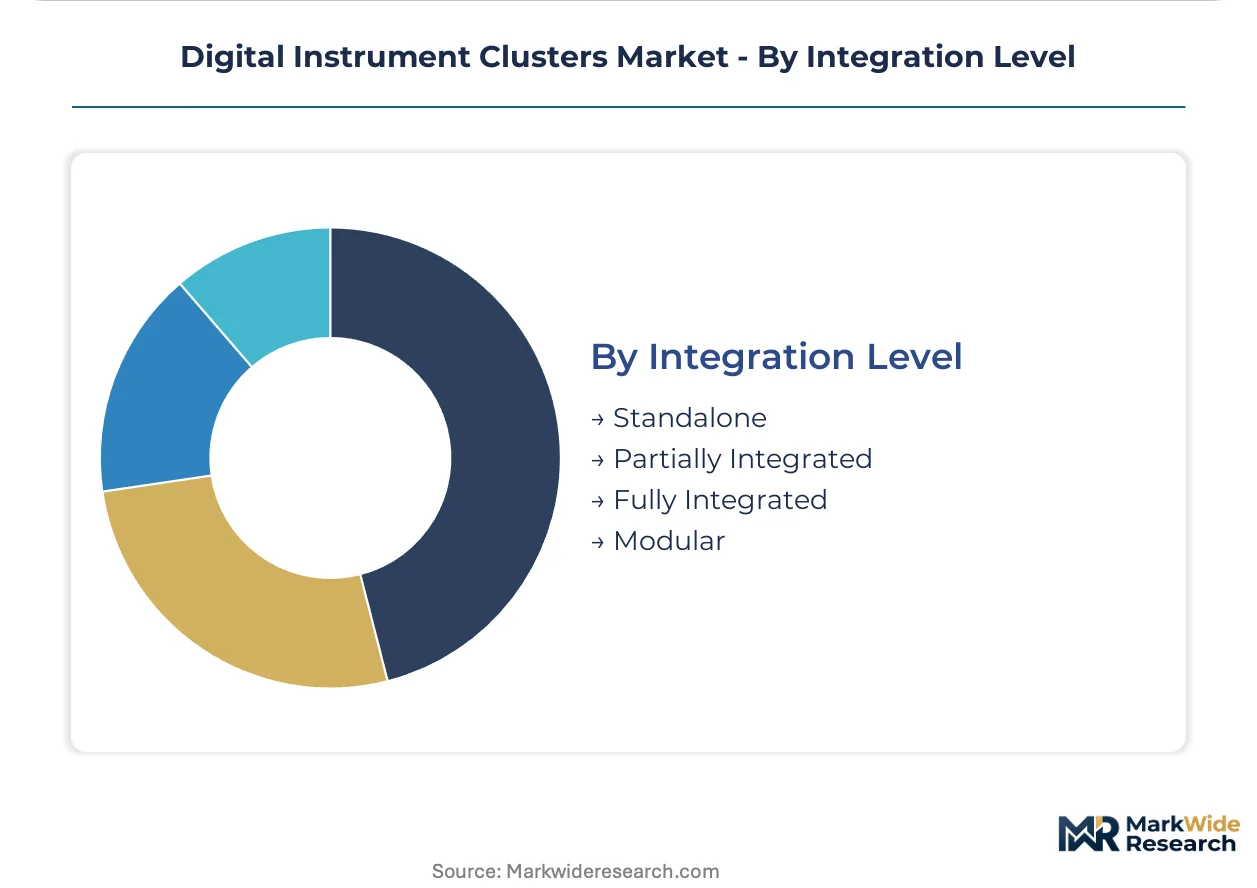
Integration Level:
System architecture selection dictates semiconductor content, software licensing exposure, and functional safety engineering requirements.
- Fully Integrated:Unified cockpit domains merge instrument clusters with center-stack infotainment and head-up displays, eliminating bezel boundaries through microLED curved surfaces. Japanese premium electric vehicle programs lead adoption for cognitive load reduction.
- Modular:Standardized hardware interfaces accommodate regional software overlays for NHTSA, ECE R121, and GB standard compliance without platform redesign, compressing multi-jurisdictional certification timelines.
- Partially Integrated:Shared controller architectures reduce wiring harness complexity while preserving physical separation between safety-critical and convenience functions.
- Standalone:Discrete cluster systems minimize dependency on proprietary real-time operating system licensing and simplify ISO 26262 functional safety scope for new entrant suppliers.
Fully integrated captures the deepest design wins; modular architectures are scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle manufacturers in Germany, Japan, and the United States account for the majority of procurement volume, with premium automotive corridors generating concentrated demand for reconfigurable digital architectures.
United States
NHTSA visibility mandates for driver information display luminance are compelling OEMs across Michigan and California to replace analog clusters with certified digital systems. The agency's response time requirements shape product development roadmaps for Detroit-based manufacturers. Michigan's automotive manufacturing corridor anchors North American demand through electric vehicle program launches from established domestic OEMs.
Germany
Bavaria-based premium manufacturers specify automotive-grade OLED panels with ambient light sensors for ECE R121-compliant auto-calibration. The regulation's tightening color gamut and luminance uniformity requirements dictate visibility performance certification across dawn, dusk, and direct sunlight scenarios. Stuttgart engineering centers sustain captive semiconductor sourcing for cluster controllers that lock in multi-year platform contracts.
Japan
Premium electric vehicle programs in the Kanto and Kansai regions adopt microLED curved surfaces that eliminate bezel boundaries between instrument clusters and center-stack infotainment screens. METI industrial policy supports cockpit electronics integration for cognitive load reduction in advanced driver-assistance interactions. Nagoya-area manufacturing clusters concentrate reconfigurable digital architecture production for export markets.
China
GB standards for dashboard readability dictate minimum luminance thresholds that force modular hardware designs accommodating regional software overlays. Guangdong's southern manufacturing hub generates white space demand for cockpit system vendors with localized software capabilities. Shenzhen and Guangzhou electric vehicle production expansion concentrates procurement authority among domestic OEMs consolidating supplier rosters.
South Korea
Seoul Capital Area display panel producers supply automotive-grade OLED technology to domestic and export OEMs prioritizing power efficiency for extended range optimization. The country's national automotive regulator enforces certification alignment with ECE R121 and NHTSA benchmarks for platform export compatibility. Busan-Ulsan manufacturing corridors integrate cluster controller production with captive semiconductor foundry capacity.
Digital Instrument Clusters Market Vendor Landscape
German producers anchor one tier; Japanese specialists hold differentiated positions in display integration and precision instrumentation. The vendor base concentrates around full-stack cockpit integrators capable of hardware-software bundling, compressing supplier rosters and elevating platform contract values. Three strategic archetypes dominate: diversified automotive electronics conglomerates with captive semiconductor sourcing, display-centric technology vendors with panel manufacturing integration, and software-defined cockpit specialists with reconfigurable architecture expertise. Competitive moves center on multi-year platform contract lock-ins and regional software overlay localization for multi-jurisdictional certification compliance.
Among diversified automotive electronics conglomerates, Continental AG and Robert Bosch GmbH exemplify the engineering-density archetype through Stuttgart-based operations. Visteon Corporation occupies a position within the North American specialist tier, representing reconfigurable digital architecture capabilities for electric vehicle programs. These three entities anchor the competitive structure by demonstrating how geographic proximity to OEM engineering centers and captive supply chain control create qualification barriers for new entrants.
| Leading Market Players |
|---|
| Continental AG |
| Visteon Corporation |
| Robert Bosch GmbH |
| DENSO Corporation |
| Yazaki Corporation |
| Nippon Seiki Co. Ltd. |
| Magneti Marelli S.p.A. |
| Panasonic Corporation |
| NVIDIA Corporation |
| Others |
Supply Flow & Price Mechanics
Tier-one automotive OEM procurement concentration around full-stack cockpit integrators anchors contract-based long-term offtake pricing with multi-year platform lock-ins. This buyer consolidation elevates supplier bargaining power for qualified system architects while compressing margins for second-tier competitors lacking captive semiconductor sourcing.
Pricing Analysis
Volume production of TFT-LCD clusters generates thin margins at scale, while OLED variants capture wider spreads through premium positioning and power efficiency differentiation. Price differentiation rests on certification grade—ECE R121 and NHTSA compliance tiers—and after-sales software bundling rather than hardware alone. Cost compression in hybrid configurations is intensifying because fleet operators prioritize total cost of ownership over feature flexibility. Aftermarket providers exhibit highest price sensitivity due to custom gateway development burdens, whereas German premium OEMs demonstrate lowest sensitivity when specifying automotive-grade OLED with ambient light sensors.
Supply Chain Analysis
Cross-border freight costs for precision display panels from South Korea and Taiwan amplify landed costs for European and North American assembly plants. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, with automotive-grade chip supply drawing from captive foundry arrangements at Robert Bosch GmbH and Continental AG. Single-source vulnerability in cluster controller ASICs creates exposure when tier-one suppliers allocate capacity to flagship OEM programs. Distribution runs through just-in-time sequencing to Bavaria, Michigan, and Guangdong assembly corridors, with modular hardware designs enabling regional software overlay deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-jurisdictional certification requirements under NHTSA, ECE R121, and GB standards erect a cost-of-compliance moat that favors established integrators with existing regulatory relationships and ISO 26262 functional safety infrastructure.
For Market Incumbents: Cement multi-year platform contract extensions by deepening backward integration into automotive-grade semiconductor sourcing and expanding Stuttgart engineering density for faster ECE R121 validation cycles. Lock in OEM loyalty through bundled after-sales software update services that create switching costs. Counter emerging display-centric technology vendors by accelerating microLED curved surface development for flagship differentiation. For New Entrants and Emerging Players: Launch via aftermarket distribution partnerships targeting legacy vehicle retrofit demand where custom gateway development extends timelines but opens margin opportunities unavailable in captive OEM supply. Prioritize Guangdong EV manufacturing corridors for white-space penetration, leveraging localized software overlay capabilities for GB standard compliance. Target fleet operator procurement managers unbundling software services from hardware contracts to establish recurring revenue footholds before attempting tier-one qualification. For Investors and Strategic Acquirers: The window for entry favors software-defined cockpit specialists with reconfigurable architecture expertise and existing ISO 26262 certification infrastructure. Long-term viability hinges on qualification for EU software-type approval frameworks and cybersecurity mandates reshaping validation timelines. Monitor OEM supplier roster consolidation announcements as the primary inflection signal for platform contract availability and competitive displacement opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces NHTSA and ECE R121 re-certification costs across vehicle lineups for Michigan-based OEMs. |
| Battery Supply Agreement | Aligns cluster power efficiency specifications with extended range optimization targets in Bavaria EV programs. |
| Software-Defined Vehicle Investment | Enables over-the-air feature activation revenue streams for North American commercial fleet segments. |
| Geographic Manufacturing Footprint | Localizes Guangdong production to compress GB standard compliance timelines and logistics exposure. |
| Charging Infrastructure Partnership | Integrates instrument cluster data streams with route optimization algorithms for electric vehicle operators. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, aftermarket distribution channel heads, and automotive regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from NHTSA certification databases, ECE R121 regulatory filings, vehicle production registries, and SEC disclosures from cockpit electronics suppliers. Bottom-up segment sizing triangulates against top-down market envelope checks from automotive semiconductor trade flows.
Historical reference periods spanning pre-pandemic baseline through recent platform launch cycles anchor the projection horizon across fully digital, hybrid, and virtual product configurations. Modeled dimensions include display technology tier, integration level architecture, end-user procurement authority, and regional manufacturing cluster concentration. CAGRs derive from segment-level build-up analysis incorporating electric vehicle program launch schedules and content-per-vehicle trajectories for reconfigurable digital architectures.
Semiconductor allocation disruptions, regulatory timeline accelerations, and OEM supplier consolidation announcements are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Broadcasting Equipment Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market