
 Electronic Skin Market | 2026-2036
Electronic Skin Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Skin Market Analysis
Stretchable nano-electronics integration is reconfiguring how electronic skin systems achieve conformal contact with biological surfaces. Abbott leverages polymer science expertise to sustain leadership in glucose-sensing patches. Dexcom, Inc. anchors its position through continuous refinement of minimally invasive sensor architectures. Philips navigates regulatory complexity across multiple jurisdictions to extend its reach in clinical-grade wearable monitors.
Electronic skin refers to thin, flexible substrates embedding conductive polymers, nano-scale sensors, and microfabricated circuits that transduce mechanical, thermal, or biochemical stimuli into processable electrical signals, primarily serving real-time physiological monitoring and human-machine interface applications. Conductive polymer formulations currently dominate material selection due to established biocompatibility profiles and scalable deposition processes, while biohybrid systems represent the fastest-expanding technology segment as researchers integrate living cells with electronic transducers. Healthcare monitoring applications command the largest revenue pool given reimbursement pathways and clinical validation requirements, whereas robotics applications are gaining traction as tactile sensing demands intensify for precision manipulation tasks.
The FDA maintains stringent premarket review pathways for wearable medical devices, compelling developers to generate substantial clinical evidence before commercialization. ISO 10993 biocompatibility standards and IEC 60601 electrical safety requirements further constrain design choices and testing protocols for multi-market product introductions. Stakeholders must monitor how the EU Medical Device Regulation recalibrates conformity assessment burdens for class IIa and higher classifications, as this will reshape market access economics and competitive positioning across jurisdictions.
Market Dynamics
Stretchable nano-electronics integration is compressing development cycles and reconfiguring competitive moats around conformal contact capabilities rather than discrete sensor precision.
Growth Catalysts
- Wearable Health Monitoring:Healthcare providers are integrating electronic skin patches into remote patient monitoring protocols, with reimbursement pathways in the United States accelerating clinical adoption.
- FDA Evolving Framework:The FDA's streamlined premarket review pathways for wearable medical devices are compressing product certification timelines and reducing commercialization barriers.
- Biohybrid Systems:Research institutions are advancing living cell-electronic transducer integration, opening new application vectors in regenerative medicine and closed-loop therapeutic systems.
Market Restraints
- Conductive Polymer Cost Volatility:Specialized polymer feedstocks face supply concentration among a limited supplier base, creating input cost instability for substrate manufacturers.
- ISO 10993 Testing Burden:Biocompatibility validation requirements impose extended timelines and substantial capital allocation for multi-market product introductions.
- Rigid Electronics Substitution:Conventional silicon-based sensors retain cost advantages in non-conformal applications, limiting electronic skin addressable markets.
Strategic Opportunities
- Robotics Tactile Sensing:Precision manipulation demands in industrial automation are creating unmet needs for high-density pressure and shear force mapping.
- EU Medical Device Regulation Recalibration:MDR conformity assessment modifications for class IIa devices are reshaping market access economics and creating first-mover advantages.
- Human-Machine Interface Convergence:Integration of haptic feedback with neural signal acquisition is opening prosthetic and augmented reality application channels.
Industry Challenges
- Microfabrication Talent Scarcity:The intersection of polymer chemistry, nano-scale patterning, and physiological signal processing requires specialized expertise that remains concentrated in limited geographic clusters.
- IEC 60601 Electrical Safety Certification:Multi-jurisdiction compliance timelines extend product development cycles and strain smaller development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Skin Market |
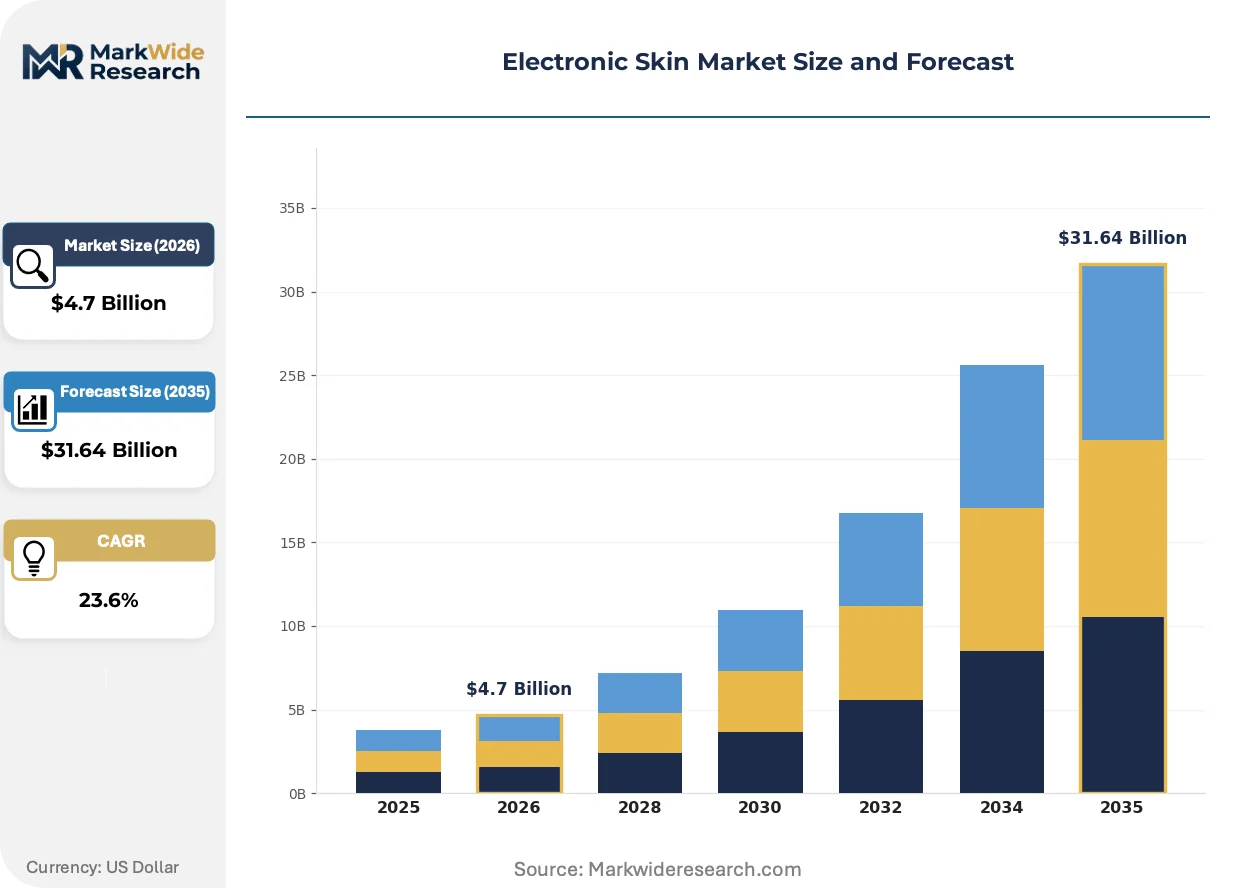
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $31.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Sensors, Wearable Devices, Smart Bandages, Prosthetics Technology: Conductive Polymers, Biohybrid Systems, Nano-electronics, Microfabrication Application: Healthcare Monitoring, Robotics, Cosmetics, Augmented Reality End User: Healthcare Providers, Consumers, Research Institutions, Military |
| Companies Covered | Boston Scientific Corporation, Insulet Corporation, Abbott, iRhythm Technologies, L'Oréal SA, Dexcom, Inc., Koninklijke Philips N.V., 3M Company, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Skin Market Emerging Trajectories
Material science breakthroughs and regulatory pathway refinements are compressing the gap between laboratory validation and commercial deployment across physiological monitoring applications.
Self-healing polymer networks incorporating dynamic covalent bonds are rendering obsolete conventional encapsulation strategies that sacrifice stretchability for device longevity. Medical device manufacturers are adopting these formulations for glucose-monitoring patches and cardiac strain sensors. The shift is rendering obsolete multi-layer barrier films that previously dominated flexible electronics packaging.
REACH substance restrictions on persistent organic pollutants are compelling reformulation of conductive ink chemistries across European manufacturing operations. Industrial consequence includes accelerated migration to silver nanowire and carbon nanotube alternatives that bypass restricted substance lists. German and French medical technology clusters are responding fastest, with several contract manufacturers achieving SVHC-compliant production lines ahead of enforcement deadlines.
Hospital procurement departments are consolidating vendor relationships around full-stack monitoring solutions rather than discrete sensor components. This behavioral shift is compressing margins for pure-play substrate suppliers while rewarding systems integrators with clinical workflow integration capabilities. The United States exhibits the most pronounced consolidation, with integrated delivery networks in Minnesota and Massachusetts driving preference toward single-source accountable care partnerships.
Electronic Skin Market Segmentation
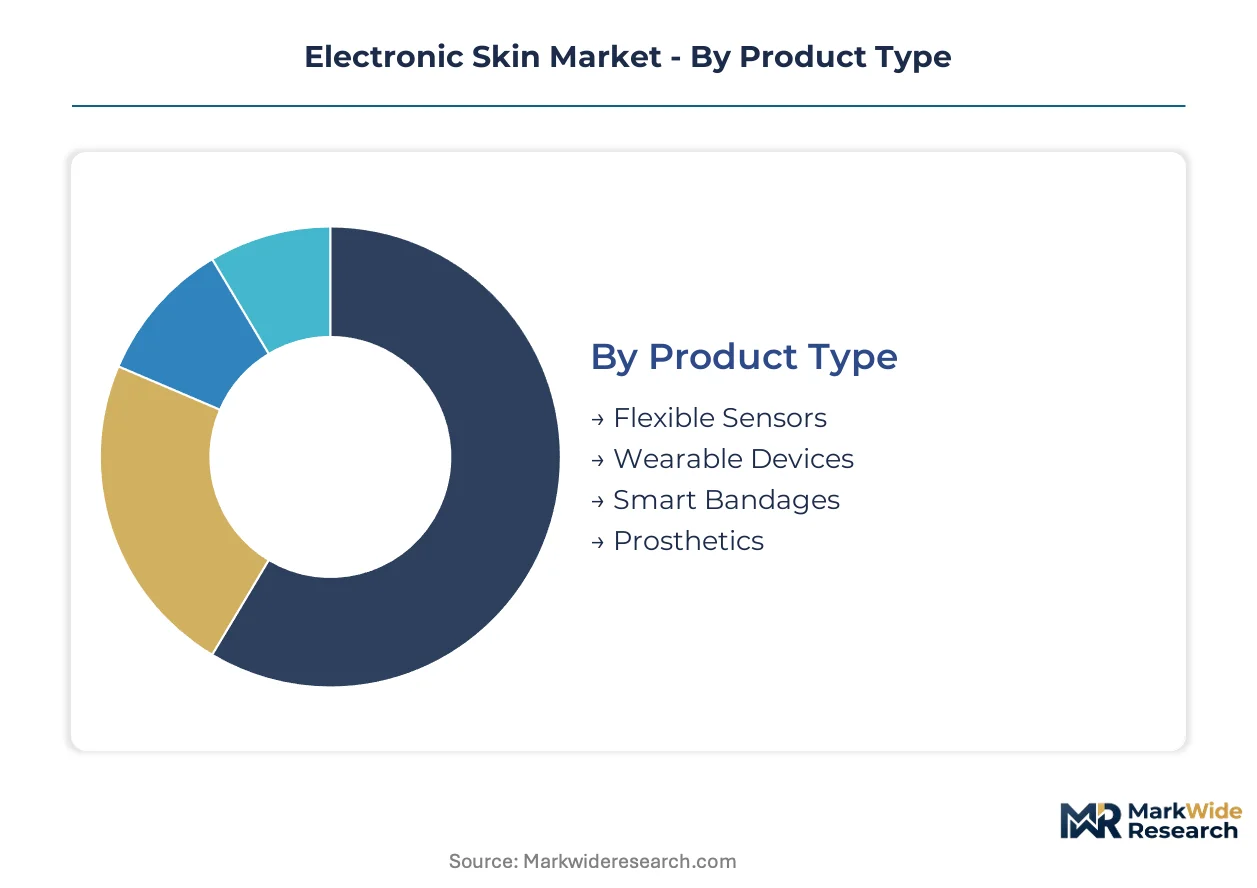
Electronic skin markets fragment across four critical dimensions that determine technical specifications, regulatory pathways, and commercial viability. Product architecture and underlying technology choices lock in manufacturing economics, while application context and end-user procurement patterns shape go-to-market strategies.
Product Type:
Cost tier stratification across product categories reflects manufacturing complexity, certification burden, and volume scale.
- Flexible Sensors:Thin-film substrates embedding conductive traces and transducer elements for strain, pressure, or temperature detection. Demand concentrates in glucose-monitoring patches for diabetic patients in the United States, where CMS reimbursement codes accelerate clinical procurement cycles.
- Wearable Devices:Integrated systems combining sensing layers with wireless communication modules and power management circuits. Healthcare providers in Germany and Japan are consolidating vendor relationships around full-stack cardiac monitoring solutions rather than discrete components.
- Smart Bandages:Wound care platforms integrating pH sensing, temperature mapping, and drug delivery actuation. The UK's NHS innovation procurement programs are piloting these for chronic wound management in integrated care systems.
- Prosthetics:Tactile feedback systems restoring sensory function for amputee patients. Research institutions in Switzerland and the Netherlands are advancing closed-loop neural interfaces for upper-limb prosthetic control.
Wearable Devices holds installed capacity. Flexible Sensors is rotating up the share rankings.
Technology:
Application requirements across physiological monitoring and human-machine interfaces are forcing divergence in material selection and fabrication approaches.
- Conductive Polymers:PEDOT:PSS and polyaniline formulations deposited via inkjet or screen printing for stretchable electrode networks. Established biocompatibility profiles under ISO 10993-5 cytotoxicity testing are accelerating FDA 510(k) submissions from developers in Massachusetts and Minnesota.
- Biohybrid Systems:Living cell populations interfaced with electronic transducers for regenerative medicine applications. Research consortia in South Korea and Singapore are advancing closed-loop therapeutic platforms where cellular metabolism drives signal transduction.
- Nano-electronics:Silver nanowire meshes and carbon nanotube networks achieving percolation conductivity at sub-micron feature scales. REACH substance restrictions on persistent organic pollutants are compelling European manufacturers to migrate from conventional conductive inks.
- Microfabrication:Photolithographic patterning of thin-film metals and dielectrics on polyimide or PDMS substrates. Talent scarcity at the intersection of polymer chemistry and nano-scale patterning is concentrating development in Boston, Stuttgart, and Seoul metropolitan clusters.
Conductive Polymers holds installed capacity. Biohybrid Systems is expanding most quickly as living-electronic interfaces mature.
Application:
Volume concentration and margin structure vary sharply by end-use context, with clinical validation requirements creating divergent competitive moats.
- Healthcare Monitoring:Continuous physiological tracking for cardiac, metabolic, and respiratory parameters. Reimbursement pathways in the United States and Germany are accelerating hospital procurement of remote patient monitoring systems.
- Robotics:Tactile sensing for precision manipulation in industrial automation and surgical robotics. Demand from automotive assembly lines in Japan and Germany is driving high-density pressure mapping requirements.
- Cosmetics:Skin hydration and temperature sensing for personalized beauty regimens. Direct-to-consumer channels in France and South Korea are absorbing disposable patch formats at volume price points.
- Augmented Reality:Haptic feedback interfaces and gesture recognition surfaces. Meta and Apple procurement specifications are compressing development cycles for conformal input devices.
Healthcare Monitoring holds installed capacity. Robotics is climbing the fastest as industrial automation demands intensify.
End User:
Customer type determines procurement methodology, price sensitivity, and regulatory engagement intensity.
- Healthcare Providers:Hospital systems and physician practices purchasing through group purchasing organizations and integrated delivery networks. Procurement consolidation in Minnesota and Massachusetts is favoring single-source accountable care partnerships.
- Consumers:Individual purchasers through retail channels and direct-to-consumer platforms. Wellness-oriented demographics in California and Bavaria are driving subscription models for continuous glucose monitoring.
- Research Institutions:Academic medical centers and national laboratories advancing preclinical validation. NIH and EU Horizon funding streams are supporting biohybrid system development at MIT, ETH Zurich, and KAIST.
- Military:Defense agencies procuring for soldier health monitoring and prosthetic rehabilitation. DARPA programs are accelerating FDA breakthrough device designation pathways for battlefield trauma applications.
Healthcare Providers holds installed capacity. Research Institutions is gaining share fastest as translational funding expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and research consortia concentrate demand across distinct national clusters, with regulatory pathway efficiency and reimbursement infrastructure determining competitive access. Medical technology development gravitates toward regions combining polymer science expertise with streamlined device certification frameworks.
United States
Integrated delivery networks in Minnesota and Massachusetts are consolidating vendor relationships around full-stack monitoring solutions rather than discrete sensor components. The FDA's evolving premarket review pathways for wearable medical devices are compressing certification timelines for glucose-sensing patches. Boston and Minneapolis-St. Paul anchor development clusters where Abbott and Medtronic refine polymer-based sensor architectures.
Germany
Hospital systems are procuring cardiac monitoring solutions through group purchasing organizations that favor single-source accountable care partnerships. REACH substance restrictions on persistent organic pollutants are compelling reformulation of conductive ink chemistries across manufacturing operations. Stuttgart and Munich medical technology clusters are achieving SVHC-compliant production lines ahead of enforcement deadlines.
Japan
Automotive assembly lines are driving demand for high-density pressure mapping in industrial robotics applications. METI standards for medical device electrical safety are shaping design specifications for export-oriented manufacturers. The Kansai region around Osaka concentrates tactile sensing development for precision manipulation systems.
South Korea
Research institutions are advancing closed-loop therapeutic platforms where cellular metabolism drives signal transduction in biohybrid systems. MFDS biocompatibility validation requirements are accelerating parallel FDA submission strategies for multi-market products. Seoul metropolitan clusters concentrate talent at the intersection of polymer chemistry and nano-scale patterning.
Switzerland
Research consortia in Zurich and Geneva are advancing closed-loop neural interfaces for upper-limb prosthetic control. Swissmedic conformity assessment procedures for class IIa devices are recalibrating market access economics for wearable monitors. ETH Zurich anchors translational funding streams supporting living-electronic interface development.
Electronic Skin Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where systems integrators capture margin from substrate suppliers. Medical device conglomerates with established reimbursement relationships dominate procurement channels, while pure-play sensor developers concentrate on conformal contact capabilities. Two strategic archetypes predominate: diversified health technology platforms leveraging polymer science expertise, and focused continuous monitoring specialists refining minimally invasive architectures. Competitive moves center on strategic partnerships with hospital systems and technology licensing agreements that accelerate regulatory pathway navigation.
Within the diversified health technology tier, Abbott and Philips occupy positions that exemplify channel control through clinical workflow integration. Dexcom, Inc. represents the focused monitoring specialist archetype, occupying a position centered on sensor architecture refinement. These three companies anchor the competitive landscape across glucose-sensing patches and cardiac monitoring applications where reimbursement infrastructure determines commercial viability.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Insulet Corporation |
| Abbott |
| iRhythm Technologies |
| L'Oréal SA |
| Dexcom, Inc. |
| Koninklijke Philips N.V. |
| 3M Company |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Undercapacity in conductive polymer feedstock facilities across Germany and Japan is compressing supplier margins while amplifying pricing power for integrated substrate manufacturers serving FDA-cleared glucose-monitoring patches.
Pricing Analysis
Cost-plus contracts indexed to silver nanowire spot markets dominate procurement between substrate manufacturers and medical device OEMs in Massachusetts and Minnesota. Pricing stratifies across clinical-grade, wellness-tier, and research-use certification levels, with ISO 10993-5 cytotoxicity validation commanding substantial premiums. Cost compression in wellness-tier patches is intensifying because direct-to-consumer channels absorb volume at stripped-down feature sets. Hospital procurement committees exhibit lowest price sensitivity, while cosmetics application developers face acute margin pressure from disposable patch economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are emerging as standard supply-chain finance mechanisms among South Korean and Taiwanese nano-material suppliers serving European medical technology clusters. Manufacturing concentration centers on Germany, South Korea, and the United States for conductive polymer deposition equipment. Feedstock supply rests on specialized PEDOT:PSS formulations, silver nanowire meshes, and medical-grade PDMS substrates. Single-source vulnerability pervades photolithographic patterning equipment, where Dutch and Japanese OEMs control critical tool availability. Distribution runs through group purchasing organizations and integrated delivery networks rather than component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic skin markets fragment across application contexts, with hospital procurement consolidation creating defendable niches for workflow-integrated systems integrators while pure-play substrate suppliers face margin compression.
For Market Incumbents: Entrench position through backward integration into conductive polymer formulation and captive production of nano-scale patterning capacity in Stuttgart or Boston metropolitan clusters. Defend against emerging biohybrid specialists by accelerating FDA breakthrough device designations for closed-loop therapeutic platforms. Prioritize certification investment in EU MDR class IIa conformity assessment to preempt compliance-driven market access barriers. For New Entrants and Emerging Players: Establish a beachhead in robotics tactile sensing applications serving Japanese automotive assembly lines, where precision manipulation demands outstrip incumbent capacity. Target research institution procurement channels in Switzerland and the Netherlands, where translational funding for neural interface prosthetics creates vendor-consolidation opportunities. Pursue technology licensing agreements with established medical device OEMs to bypass multi-jurisdiction electrical safety certification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wearable device systems integrators with hospital GPO contracts, rendering these archetypes most resilient across reimbursement cycle volatility. Five-to-ten year viability favors platforms combining polymer science expertise with clinical workflow integration capabilities. Monitor FDA premarket review pathway streamlining announcements as inflection indicators for certification-timeline compression and valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Acceleration | Streamlined 510(k) pathways for glucose-sensing patches compress Abbott and Dexcom commercialization cycles. |
| EU MDR Conformity Investment | Class IIa device certification ahead of enforcement deadlines secures German hospital procurement preference. |
| Hospital System Partnership | Single-source accountable care contracts with Minnesota integrated delivery networks lock in multi-year revenue streams. |
| Backward Integration into Polymers | Captive PEDOT:PSS production insulates Medtronic from feedstock cost volatility and supplier concentration risk. |
| Biohybrid Platform Development | Living cell-electronic transducer integration at ETH Zurich and KAIST opens regenerative medicine reimbursement channels. |
Methodological Framework
The analysis maps conductive polymer formulations, nano-electronics integration, biohybrid systems, and microfabrication segments, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at FDA-cleared device manufacturers. Primary interview findings triangulate against secondary sources including FDA 510(k) filings, EU MDR submission databases, CMS reimbursement code updates, and hospital procurement transaction records. Bottom-up unit economics and top-down market sizing converge through iterative validation.
Assumptions held fixed include current FDA premarket review pathway structures, REACH substance restriction enforcement timelines, and ISO 10993 biocompatibility testing protocols. Variables include EU MDR recalibration pace, conductive polymer feedstock capacity expansion, and robotics tactile sensing adoption curves across automotive and surgical applications. CAGRs derive from segment-level volume projections weighted by reimbursement pathway maturity and certification burden differentials. Modeled inputs incorporate glucose-monitoring patch prescription volumes, cardiac remote patient monitoring system deployments, and industrial robotics pressure sensor density requirements.
Sensitivities concentrate around FDA pathway streamlining announcements, EU MDR enforcement deadline shifts, and silver nanowire supply concentration disruptions. Forecasts reflect documented assumptions regarding reimbursement infrastructure stability and polymer science talent cluster persistence. Macroeconomic contraction affecting hospital capital expenditure, regulatory restriction tightening on persistent organic pollutants, or breakthrough advances in rigid electronics substitution would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Electronic Treadle Market