
 Electronic Weighing Machines Market | 2026-2036
Electronic Weighing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Weighing Machines Market Intelligence
The use of high-strength polymer composites in place of stainless steel for certain scale frames and housings is pivoting product design toward lighter, more corrosion-resistant models. Mettler-Toledo International, Inc. leverages its extensive R&D in sensor technology to maintain a strong position in high-precision laboratory applications. Shimadzu Corporation specializes in analytical and measuring instruments, including precision balances for scientific research. Kern & Sohn GmbH competes through a broad portfolio covering both laboratory and industrial weighing solutions across Europe.
An electronic weighing machine is a device that measures mass by converting the force exerted by an object into a digital signal, typically using a strain gauge load cell. These instruments incorporate microprocessors that enable functions such as taring, piece counting, and data communication, with precision varying from micrograms in analytical balances to kilograms in industrial scales. Precision balances for laboratory analysis constitute a high-margin segment driven by research and regulatory compliance needs. Conversely, floor scales used in manufacturing plants and for inventory management represent a high-volume category where durability and connectivity are primary purchasing criteria.
Compliance with standards like Europe's CE marking for safety and metrology is essential for market access. In the United States, devices intended for commercial transactions are subject to certification based on NIST Handbook 44 guidelines, while scales used in healthcare must meet FDA requirements. Future competitive advantage will hinge on integrating smart features, such as predictive maintenance alerts and seamless ERP system connectivity, into weighing instrumentation.
Market Dynamics
The transformation of electronic weighing machines from isolated measurement tools into connected data sources for enterprise resource planning and manufacturing execution systems is the central force shaping the market. This integration, driven by IoT technology, elevates scales from simple hardware to critical nodes in automated industrial processes.
Growth Catalysts
- Stringent Regulations:Heightened food safety and pharmaceutical traceability rules, such as FSSAI guidelines in India and FDA requirements in the US, mandate precise weight documentation, compelling investment in advanced, compliant weighing systems for quality control.
- Industrial Automation:The expansion of automated logistics and manufacturing facilities, particularly in Germany's automotive and chemical sectors, requires integrated weighing solutions for process control, inventory management, and waste reduction, driving volume demand for robust industrial scales.
- Laboratory Modernization:Growth in biotechnology and life sciences research creates sustained demand for high-precision analytical and microbalances, where accuracy and data integrity are paramount for experimental outcomes and regulatory submissions.
Market Restraints
- High Input Costs:The manufacturing of high-precision strain gauge load cells and sensitive electromagnetic force compensation sensors relies on specialized alloys and manufacturing processes, making them a significant cost component that is vulnerable to material price fluctuations.
- Compliance Fragmentation:Manufacturers face increased costs and longer lead times due to the need to secure different metrological and safety certifications, such as Europe's CE marking and the US NIST Handbook 44, for access to major markets.
- Threat of Substitution:In basic, non-critical applications like bulk material handling or simple portioning, lower-cost mechanical scales or alternative measurement techniques like volumetric filling can present a viable, cheaper alternative for highly price-sensitive customers.
Strategic Opportunities
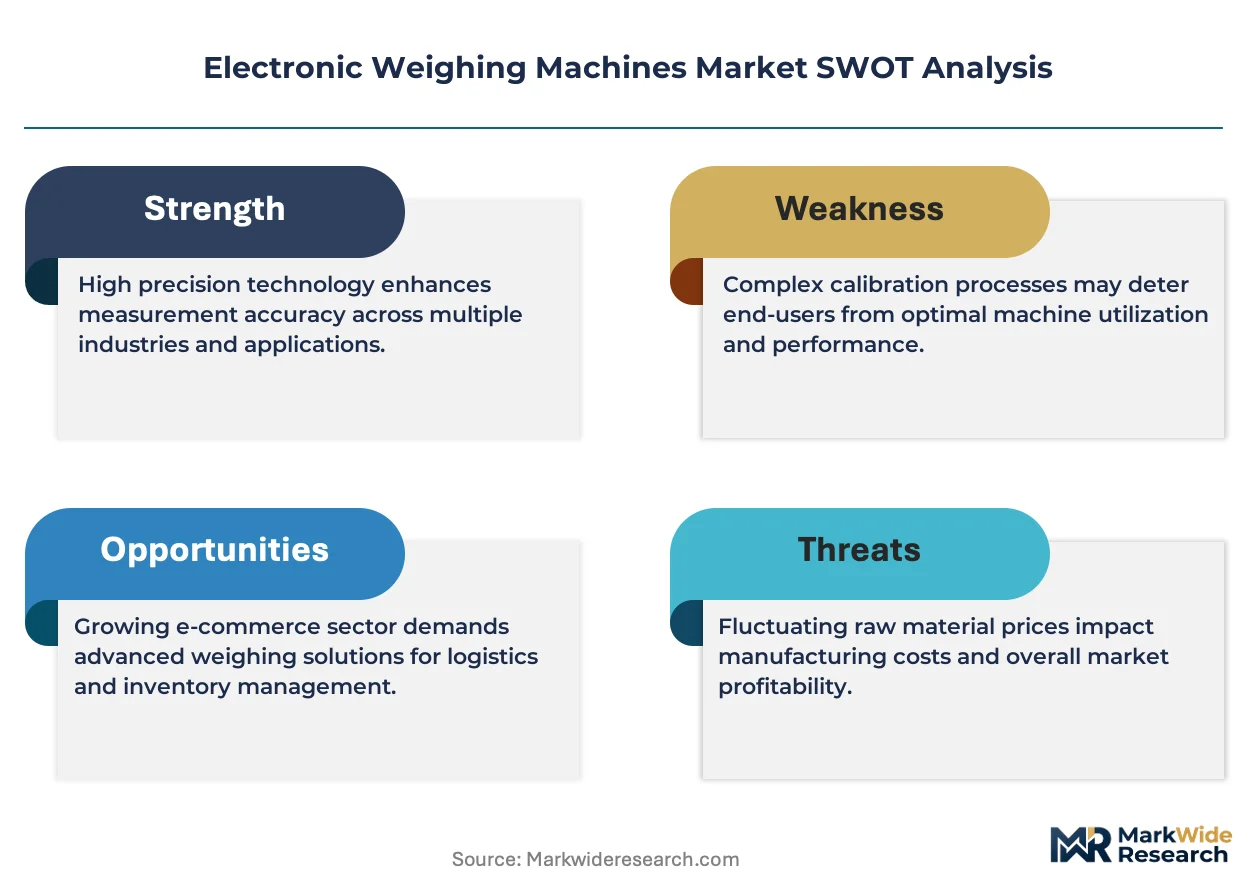
- Predictive Maintenance Services:Integrating AI algorithms with IoT-enabled industrial scales offers the opportunity to provide predictive maintenance alerts based on usage patterns and environmental data, creating a new recurring revenue stream from service contracts.
- Emerging Market Agriculture:Modernizing post-harvest supply chains in Southeast Asian and Latin American economies presents an opportunity for rugged, portable electronic scales for accurate crop weighing, reducing loss and improving farmer-to-market transactions.
- Smart Material Integration:Developing scale housings and platforms from advanced polymer composites embedded with sensors for shock, tilt, or temperature can create more durable, intelligent products that self-diagnose and report on operating conditions.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complexity and cost of integrating modern, network-enabled weighing instruments with older, proprietary Manufacturing Execution Systems (MES) and ERP software prevalent in many industrial facilities.
- Specialized Skills Gap:The market faces a shortage of service technicians who possess a dual competency in traditional metrology for calibration and the IT networking skills required to install, configure, and troubleshoot connected weighing systems.
- Certification Bottlenecks:The lengthy and rigorous testing process required to obtain legal-for-trade certifications from national metrology institutes can create significant delays in bringing new product designs and technologies to market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Weighing Machines Market |
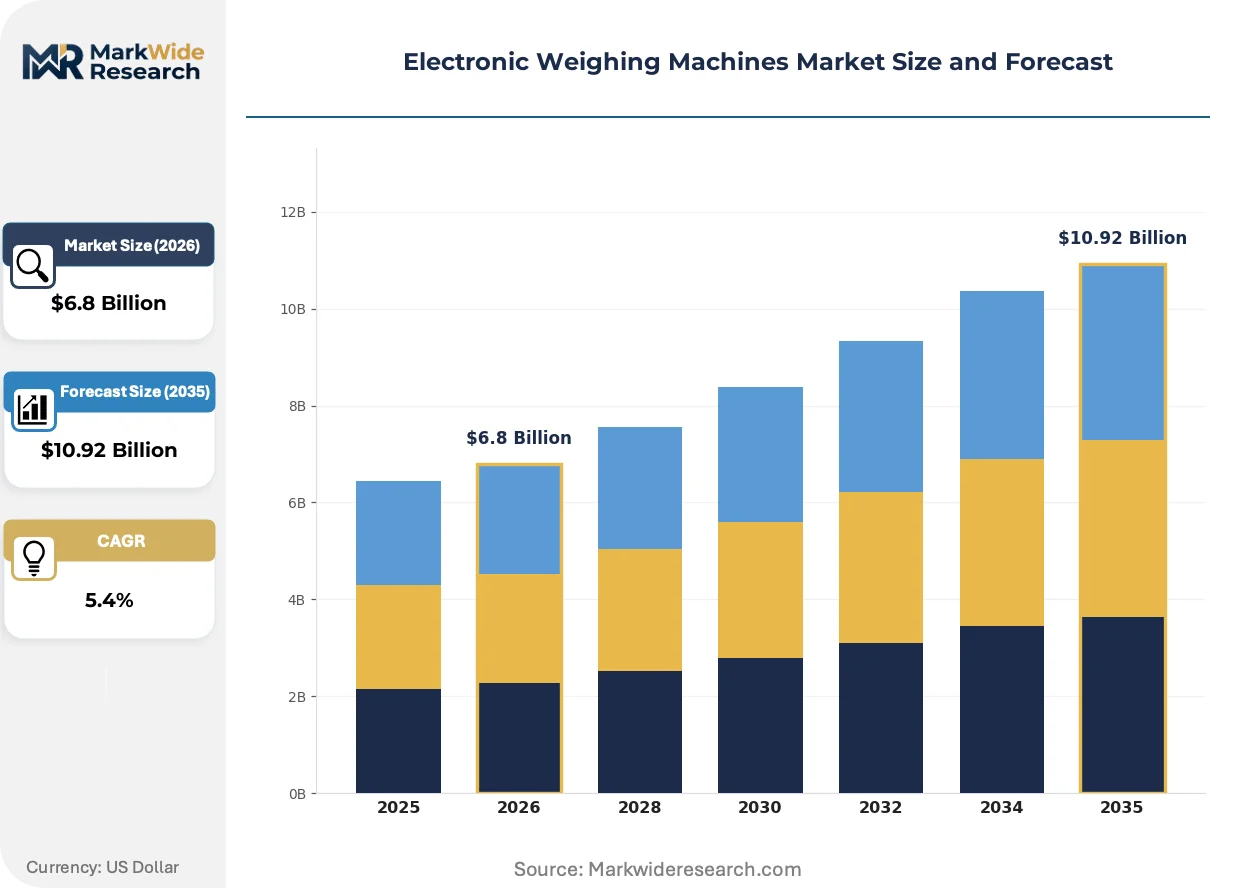
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravimetric Scales, Precision Balances, Floor Scales, Hanging Scales End User: Retailers, Hospitals, Laboratories, Manufacturing Plants Technology: Load Cells, Strain Gauge, Capacitive, Electromagnetic Application: Inventory Management, Quality Control, Shipping, Laboratory Analysis |
| Companies Covered | Mettler-Toledo International, Inc., A&D Company, Limited, Sartorius Group, Shimadzu Corporation, Kern & Sohn GmbH, Fairbanks Scales Inc., Doran Scales, Inc., BONSO Electronics International Inc., Avery Weigh-Tronix, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Weighing Machines Market Strategic Shifts & Innovations
Product development is pivoting from standalone accuracy to system-level data utility. The evolution of electronic weighing machines into intelligent endpoints within a broader digital factory or laboratory ecosystem defines the current innovation cycle, emphasizing connectivity and software-driven functionality over mechanical specifications alone.
Sensor fusion technology combines weight measurement with other critical data points like temperature, humidity, or vibration. Pharmaceutical laboratories and food processing facilities are adopting these multi-sensor systems to ensure measurement integrity in controlled environments. This technology is converging with cloud-based data platforms, enabling a holistic view of process conditions that can impact product quality and regulatory compliance.
Europe's Medical Device Regulation (MDR) imposes stricter requirements on all medical equipment, including scales used for patient weighing and pharmaceutical compounding. The regulation elevates the demands for clinical evaluation, risk management, and post-market surveillance throughout the product lifecycle. The medical scales segment is most affected, forcing manufacturers to overhaul quality management systems and technical documentation to maintain CE marking.
A behavioral shift towards equipment-as-a-service models is gaining traction over traditional capital equipment purchases. Contract research organizations and third-party logistics providers are increasingly leasing high-end analytical balances and industrial scales to convert capital expenses into operational ones. This trend disrupts direct sales channels, favoring vendors who offer bundled calibration, maintenance, and certification services. This is most prominent in North American and European life science clusters.
Electronic Weighing Machines Market Segmentation
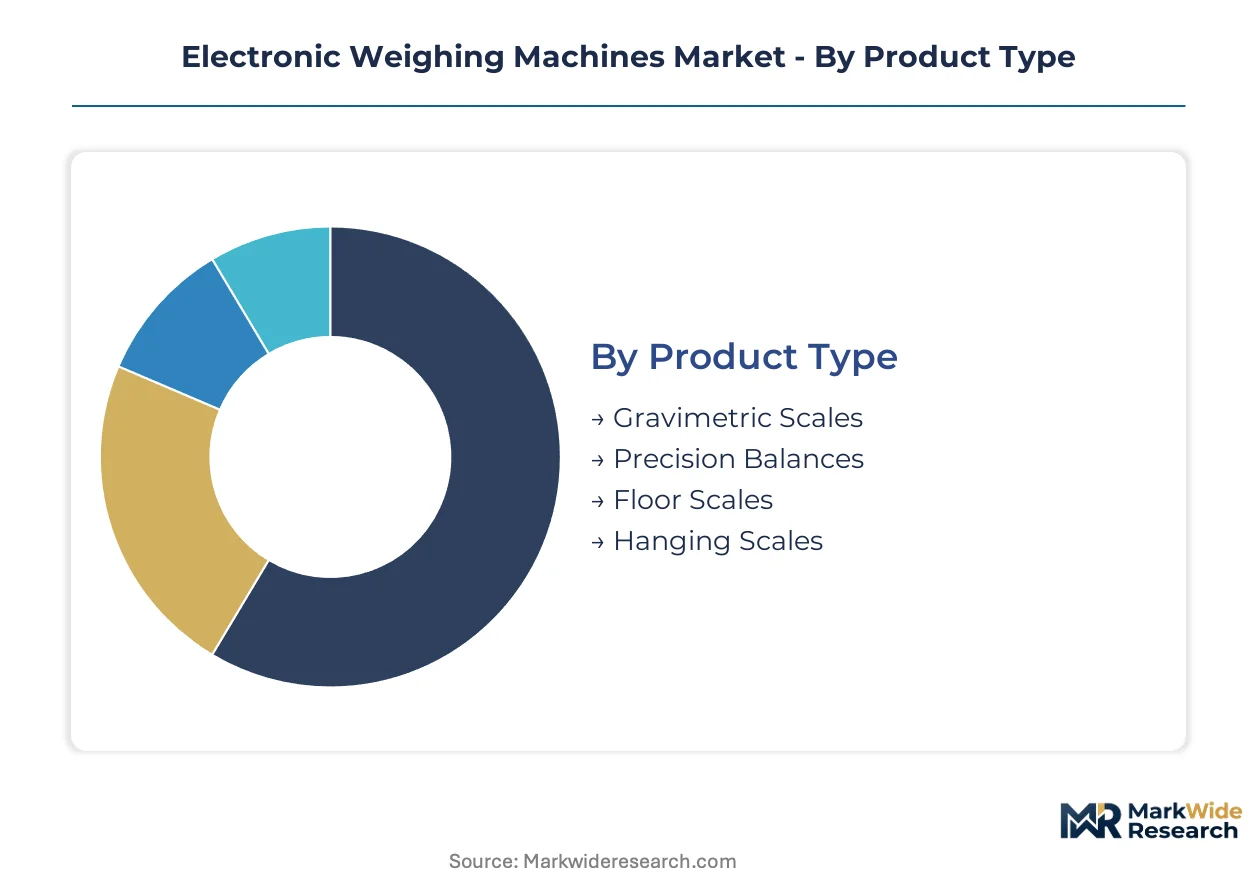
Segmentation within the electronic weighing machines market clarifies diverse product specifications and end-user requirements. This analysis delineates how precision needs, operational environments, and technological advancements define distinct market sub-sectors. Understanding these divisions helps manufacturers tailor product development and market strategies effectively. Each segment reflects unique demand characteristics and competitive dynamics.
Product Type:
The supply of electronic weighing machines often concentrates around specific product types that dictate manufacturing complexity and market reach.
- Precision Balances:Precision balances measure mass with high accuracy, typically in milligrams or micrograms, using electromagnetic force compensation sensors. Demand in pharmaceutical laboratories and biotechnology clusters in India drives sustained investment for research and regulatory compliance.
- Floor Scales:Floor scales are robust, large-capacity devices designed for heavy-duty industrial applications, often integrating directly into automated logistics systems. Manufacturing plants in Germany's automotive sector require these for process control and inventory management.
- Gravimetric Scales:Gravimetric scales determine weight by measuring the force of gravity, commonly used in bulk material handling and packaging processes.
- Hanging Scales:Hanging scales suspend the load from a hook, providing portable and convenient weighing for applications like agricultural produce or small-scale retail.
Floor Scales absorb the bulk of installed capacity; Precision Balances are expanding most quickly.
End User:
End-user segments define distinct volume requirements and application-specific features for electronic weighing machines.
- Laboratories:Laboratories utilize high-precision balances for analytical research, quality control, and formulation development, requiring extreme accuracy and data integrity. Biotechnology and life sciences research in North American clusters generate significant demand for these specialized instruments.
- Manufacturing Plants:Manufacturing plants integrate industrial scales for automated process control, inventory tracking, and waste reduction across various production lines. Germany's advanced manufacturing sector drives demand for robust, networked weighing solutions.
- Retailers:Retailers use point-of-sale scales for precise transaction weighing, often requiring legal-for-trade certification and easy integration with POS systems.
- Hospitals:Hospitals employ medical scales for patient weighing and pharmaceutical compounding, subject to strict regulatory compliance like Europe's MDR and FDA requirements.
Manufacturing Plants represents the largest volume segment; Laboratories show the steepest expansion trajectory.
Technology:
Technological sophistication directly correlates with the margin potential and performance characteristics of electronic weighing machines.
- Strain Gauge:Strain gauge technology employs a load cell with electrical resistors that deform under weight, changing resistance to measure force. This widely adopted technology forms the backbone of industrial scales, offering durability and cost-effectiveness for high-volume applications.
- Electromagnetic:Electromagnetic force compensation (EMFC) sensors use an electromagnet to counteract the weighed mass, providing extremely high precision and stability. Pharmaceutical research and high-end laboratory analysis in Switzerland rely on EMFC for critical measurements.
- Load Cells:Load cells are transducers converting force into an electrical signal, forming the fundamental sensing element in most electronic weighing machines.
- Capacitive:Capacitive technology measures changes in electrical capacitance due to applied force, offering a cost-effective solution for less demanding precision requirements.
Strain Gauge technology accounts for the broadest market penetration; Electromagnetic sensors are gaining share fastest.
Application:
The maturity of various electronic weighing machine applications influences product innovation cycles and market saturation levels.
- Quality Control:Quality control applications demand high accuracy and repeatability to ensure product consistency and regulatory adherence in manufacturing and processing. FSSAI guidelines in India and FDA requirements in the US mandate precise documentation, driving investment in advanced systems.
- Laboratory Analysis:Laboratory analysis requires ultra-high precision balances for research, development, and testing in scientific and medical fields. Growth in biotechnology and life sciences research creates sustained demand for accurate microbalances and analytical instruments.
- Inventory Management:Inventory management leverages scales for accurate stock counting and tracking, integrating with ERP systems to optimize supply chain operations.
- Shipping:Shipping applications use scales for package weight verification and freight cost calculation, ensuring compliance with carrier regulations and logistics efficiency.
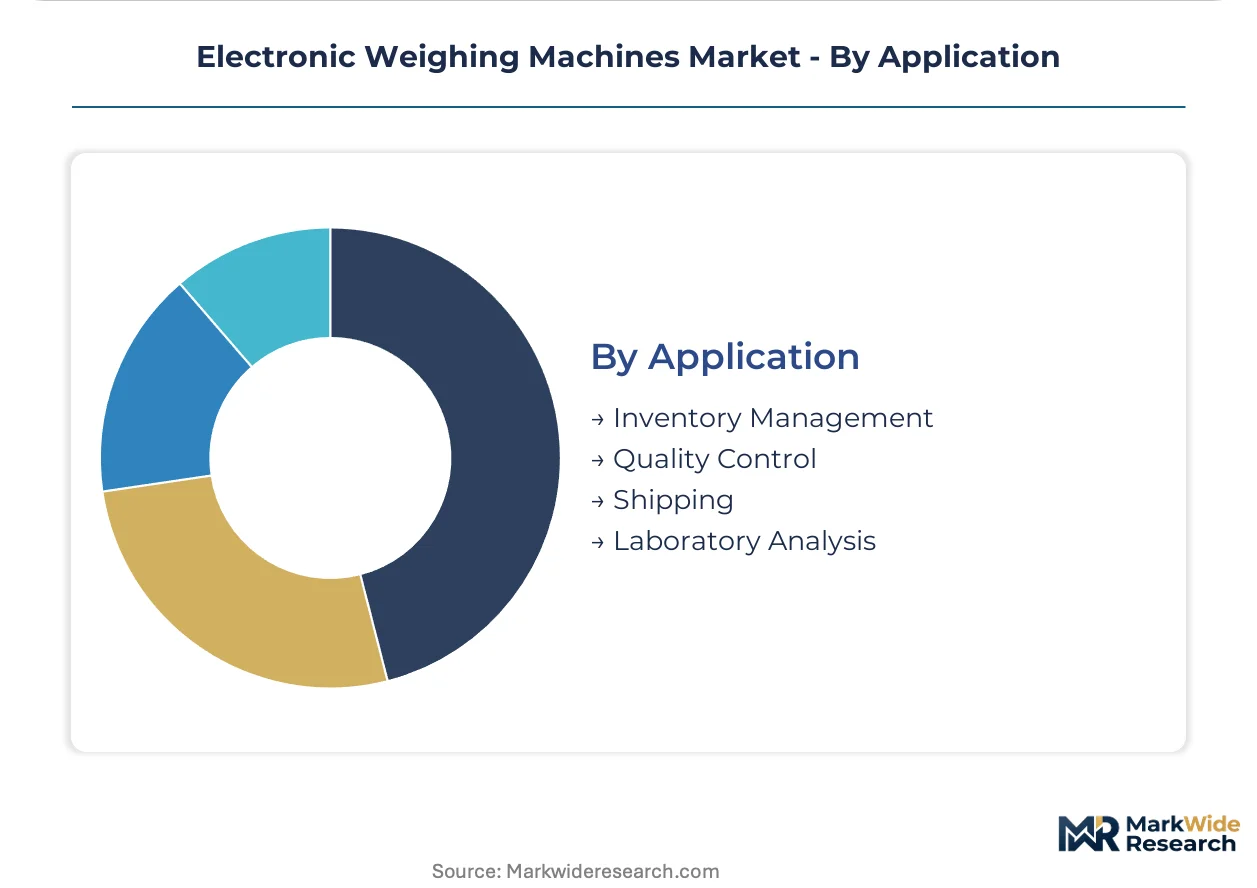
Quality Control represents a mature application segment; Laboratory Analysis is experiencing the most dynamic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electronic weighing machines concentrates significantly in regions with robust pharmaceutical, biotechnology, and advanced manufacturing sectors. These industries require high-precision measurement tools and integrated weighing solutions for quality control and process automation. Stringent regulatory environments in these areas further compel investment in compliant weighing systems.
India
India's pharmaceutical and biotechnology clusters drive substantial demand for high-precision balances, essential for research and quality control. FSSAI guidelines mandate precise weight documentation for food safety and pharmaceutical traceability, influencing procurement decisions. Major pharmaceutical manufacturing hubs in Gujarat and Telangana require advanced laboratory and industrial weighing solutions.
Germany
Germany's advanced manufacturing sector, particularly automotive and chemical industries, requires integrated weighing solutions for process control and inventory management. CE marking for metrology is essential for market access, ensuring device accuracy and safety within the European Union. The industrial heartland of Baden-Württemberg and North Rhine-Westphalia sees significant adoption of robust, networked industrial scales.
United States
The United States' biotechnology and life sciences research sectors generate strong demand for specialized high-precision analytical and microbalances. NIST Handbook 44 guidelines govern commercial transaction devices, while FDA requirements apply to healthcare scales, ensuring accuracy and reliability. North American life science clusters around Boston and San Francisco actively modernize laboratory weighing infrastructure.
Switzerland
Swiss pharmaceutical research and high-end laboratory analysis rely heavily on electromagnetic force compensation (EMFC) sensors for critical, ultra-high precision measurements. Swissmedic regulations impose strict standards on medical and laboratory devices, impacting product design and certification. Biotechnology firms in Basel and Zurich consistently invest in advanced weighing technology for R&D.
Japan
Japan's analytical and measuring instrument sector, including precision balances, supports extensive scientific research and advanced manufacturing. METI oversees industrial standards and quality control, promoting high-accuracy weighing solutions across various applications. Research institutions and technology companies in the Kanto region, including Tokyo, drive innovation in sensor technology and data integration.
Electronic Weighing Machines Market Key Industry Players
Technological innovation dominates the current landscape, with companies focusing on integrating smart features and connectivity into weighing instruments. The market exhibits a tiered structure, with a few global leaders specializing in high-precision solutions and numerous regional players offering industrial and commercial scales. Strategic partnerships for software integration and portfolio diversification into service models are prominent competitive moves.
On the premium-tier vector, Mettler-Toledo International, Inc. leverages extensive R&D in sensor technology to maintain a strong position in high-precision laboratory applications. Shimadzu Corporation, a Japan-based entity, exemplifies specialization in analytical and measuring instruments, including precision balances for scientific research. Kern & Sohn GmbH, a German family-owned company, occupies a position offering a broad portfolio covering both laboratory and industrial weighing solutions across Europe.
| Leading Market Players |
|---|
| Mettler-Toledo International, Inc. |
| A&D Company, Limited |
| Sartorius Group |
| Shimadzu Corporation |
| Kern & Sohn GmbH |
| Fairbanks Scales Inc. |
| Doran Scales, Inc. |
| BONSO Electronics International Inc. |
| Avery Weigh-Tronix, LLC. |
| Others |
Cost & Logistics Intelligence
IoT connectivity and sensor fusion technology are reshaping the electronic weighing machines market, influencing both cost economics and supply chain concentration. This technological evolution drives demand for specialized components, affecting component pricing and manufacturing locations.
Pricing Analysis
The electronic weighing machines market exhibits a clear volume-versus-margin split, with precision balances commanding premium prices and floor scales competing on volume, stratifying pricing across premium, standard, and economy tiers based on accuracy and features. Price differentiation stems from sensor technology complexity and metrological certifications like CE marking. Pricing softness runs through high-volume industrial scales due to the threat of substitution from cheaper alternatives. Pharmaceutical laboratories demonstrate low price sensitivity for high-precision instruments, unlike basic material handling applications.
Supply Chain Analysis
Dual-sourcing requirements are increasingly common for critical components in electronic weighing machines, particularly for specialized alloys and sensors, with the supply of high-precision strain gauge load cells and electromagnetic force compensation sensors drawing from manufacturing hubs in Japan and Switzerland. Key raw material dependencies include specialized alloys and microprocessors. Commodity price volatility for these specialized materials poses a structural risk to manufacturing costs. Distribution runs through a mix of direct sales channels for premium laboratory equipment and regional distributors for industrial and retail scales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic weighing machines market is evolving into a consolidation play, driven by the escalating costs of integrating IoT capabilities and navigating fragmented metrological compliance. This pressure disproportionately affects smaller manufacturers, forcing market rationalization.
For Market Incumbents:Cement leadership by deepening R&D investment in sensor fusion and AI-driven predictive maintenance algorithms. Incumbents must also acquire or partner with software specialists to overcome the integration complexity of legacy MES/ERP systems. Investing in robust certification processes, such as for Europe's MDR, reinforces market access and trust. This strategy defends against new entrants leveraging software-centric solutions and safeguards high-margin laboratory segments.
For New Entrants and Emerging Players:Digital platforms offer a viable entry point for new players targeting niche applications. Focus on underserved segments like rugged, portable scales for emerging market agriculture, or specialized multi-sensor systems for specific pharmaceutical lab environments. The equipment-as-a-service model presents a strong go-to-market angle, particularly for contract research organizations seeking operational expenditure flexibility. Bundling comprehensive calibration and maintenance services creates immediate value.
For Investors and Strategic Acquirers:Exit pathways concentrate in acquiring mid-sized firms with proprietary software for ERP integration or specialized sensor technology. The market offers long-term viability, driven by continuous regulatory compliance and industrial automation trends. Target companies demonstrating robust recurring revenue from service contracts, especially predictive maintenance solutions. The signal to watch is the accelerated adoption rate of equipment-as-a-service models in North American and European life science clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven Predictive Maintenance Services | Creates new recurring revenue streams from IoT-enabled industrial scales and enhances customer loyalty. |
| Acquire Software Integration Specialists | Addresses legacy system integration challenges and enhances seamless ERP system connectivity for manufacturing plants. |
| Expand Equipment-as-a-Service Offerings | Converts capital expenditures to operational costs for contract research organizations, attracting new customer segments. |
| Invest in Advanced Polymer Composite R&D | Pivots product design towards lighter, more corrosion-resistant models for diverse operational environments. |
| Pursue Medical Device Regulation (MDR) Compliance | Ensures market access for medical scales in Europe, meeting strict clinical evaluation and risk management standards. |
Research Approach
Industry association reports, academic journals, and company financial filings formed the secondary backbone for this analysis, providing foundational market data. Primary research involved in-depth interviews with R&D directors in pharmaceutical laboratories, plant managers in Germany's automotive sector, metrology experts, and procurement leads. This approach facilitated bottom-up and top-down triangulation, ensuring data validity and comprehensive market understanding.
A dual analytical lens, combining bottom-up demand estimation with top-down market validation, underpinned the forecast framework. Segmentation dimensions modeled included product type, end user, technology, and application, plus regional regulatory environments. Compound Annual Growth Rates derived from historical data and trend projections. Key industry-specific forecast inputs included IoT integration rates and metrological compliance deadlines.
The model holds under current regulatory stability and projected technology adoption rates; deviation in global supply chain disruptions or unforeseen material price fluctuations would shift the outlook materially. Forecasts reflect assumptions regarding market dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
High Current Springs Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Electronic Treadle Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market