
 Digital Devices Technologies Market | 2026-2036
Digital Devices Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Devices Technologies Market Analysis
Omnichannel retail and direct-to-consumer platforms are reshaping how digital devices reach end users. Samsung leverages vertical integration across display and semiconductor supply chains to control cost structures. Sony differentiates through premium audio-visual engineering and proprietary content ecosystems. LG Electronics competes aggressively in smart home displays and OLED panel supply.
Digital Devices Technologies encompass electronic hardware systems integrating microprocessors, sensors, wireless communication modules, and software interfaces to process, store, and transmit data for consumer and enterprise applications. These systems typically operate on power budgets under 15 watts for wearables and scale to 100+ watts for laptops, with thermal design power dictating form factor constraints. Smartphones anchor the product type landscape as the highest-volume category with mature margin compression, while wearables represent the fastest-expanding segment driven by health sensing capabilities. Artificial Intelligence and IoT technology layers command premium pricing by enabling predictive analytics and ambient connectivity, whereas Virtual Reality remains niche with enterprise training as its primary commercial outlet.
FDA software-as-medical-device regulations and the EU AI Act impose conformity requirements on health-monitoring wearables and algorithm-driven devices, creating compliance costs that favor established manufacturers with dedicated regulatory affairs teams. China's MIIT and SAMR enforce GB standards and network access licenses that shape domestic product roadmaps and limit foreign market penetration without local certification. Stakeholders must weigh certification jurisdiction against addressable market size when prioritizing product development pipelines.
Market Dynamics
FDA software-as-medical-device pathways and the EU AI Act are tightening compliance requirements for connected health devices, forcing manufacturers to restructure product development cycles around multi-jurisdictional certification timelines rather than single-market launches.
Growth Catalysts
- Healthcare Wearable Integration:Chronic disease management programs in the United States are reimbursing remote patient monitoring through CMS billing codes, accelerating hospital procurement of biosensor-enabled wristbands and patches.
- EU AI Act Conformity:Risk-classification frameworks for algorithm-driven diagnostic tools are creating predictable regulatory pathways that reduce market entry uncertainty for AI-enabled imaging peripherals.
- China MIIT Certification Scale:Domestic manufacturing clusters in Shenzhen and Dongguan achieve GB standard compliance at unit economics that undercut import-dependent competitors by 15-20 percent.
Market Restraints
- Semiconductor Supply Concentration:Advanced node fabrication for application processors remains captive to Taiwan Semiconductor Manufacturing and Samsung Foundry, exposing device OEMs to geopolitical disruption risk.
- Lithium-Ion Battery Cost Volatility:Cobalt and nickel price swings tied to Democratic Republic of Congo mining output and Indonesian processing capacity constrain margin predictability for portable electronics.
- Technical Limitation in Thermal Management:Passive cooling solutions hit physical limits at 15-watt TDP thresholds, forcing thicker form factors or active fan systems that degrade waterproofing ratings.
Strategic Opportunities
- India PLI Scheme Manufacturing:Production-linked incentives for electronics assembly are attracting component suppliers to Uttar Pradesh and Tamil Nadu, creating export-competitive capacity outside China.
- Convergence of UWB and BLE:Ultra-wideband ranging combined with Bluetooth Low Energy is digitizing spatial awareness for asset tracking and indoor navigation in industrial facilities.
- Germany BSI Cybersecurity Certification:Federal mandates for IT security labels on connected devices are creating first-mover advantages for OEMs achieving CC EAL4+ ratings ahead of EU-wide harmonization.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time operating system expertise and low-power wireless stack optimization skills command premium compensation that strains mid-tier engineering budgets.
- FDA 510(k) Timeline Compression:Predicate device identification and substantial equivalence documentation for software-as-medical-device submissions now average 18-24 months, delaying revenue recognition.
- Legacy Enterprise System Integration:Industrial IoT deployments face protocol fragmentation between Modbus, OPC-UA, and proprietary SCADA architectures that complicate edge gateway configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Devices Technologies Market |
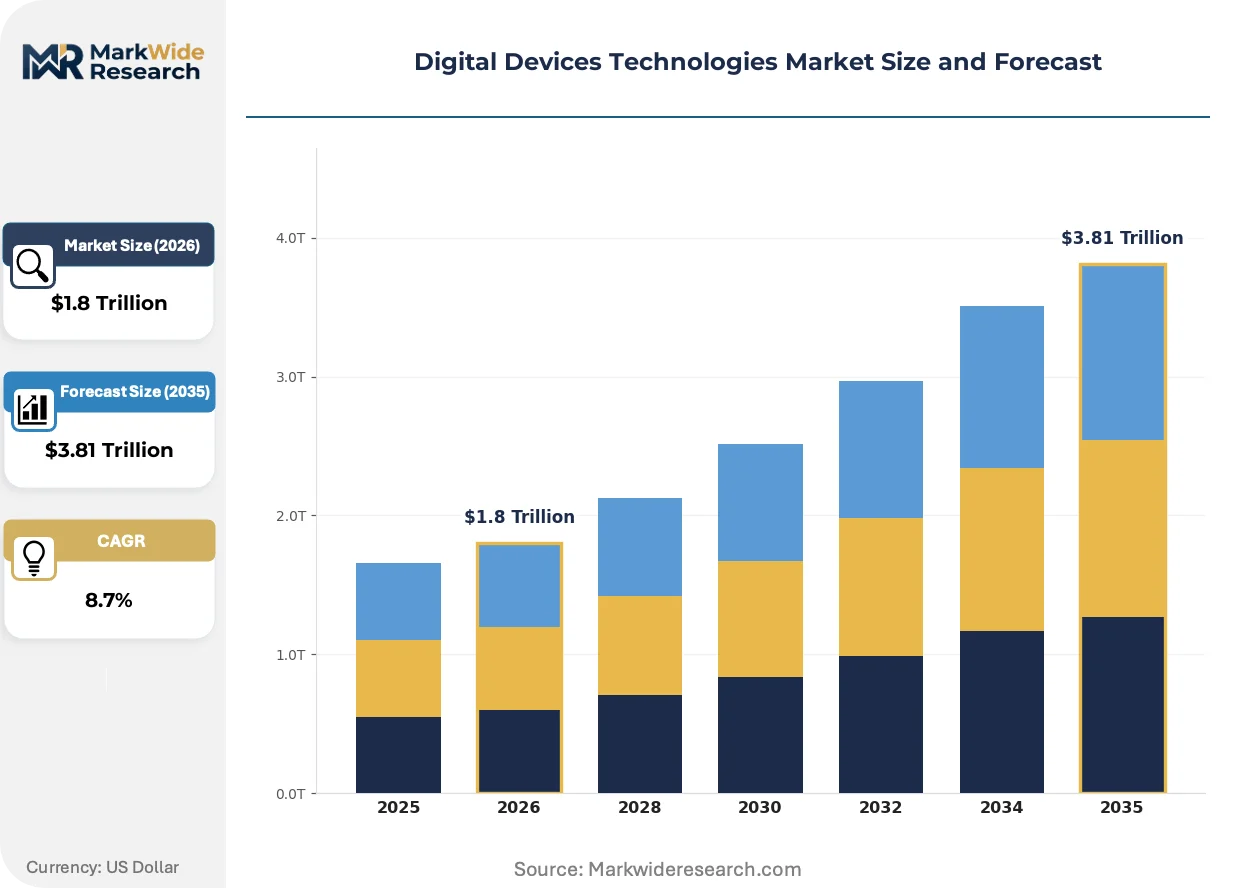
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $3.81 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Wearables, Laptops Technology: IoT, Artificial Intelligence, Augmented Reality, Virtual Reality End User: Consumers, Enterprises, Healthcare Providers, Educational Institutions Application: Gaming, Communication, Healthcare Monitoring, Smart Home |
| Companies Covered | Samsung, Sony, Bose Inc., Cisco Systems, Philips, Hitachi, LG Electronics, Panasonic, Dolby Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Devices Technologies Market Emerging Trajectories
Edge AI inference engines and ambient sensing architectures are redistributing computational load from cloud data centers to device endpoints, compressing latency for real-time health monitoring and industrial predictive maintenance.
Neuromorphic processing chips that mimic biological neural network architectures are digitizing pattern recognition for always-on voice assistants and fall-detection algorithms. Hearing aid manufacturers and smartwatch OEMs are adopting these accelerators to sustain multi-day battery life under continuous sensor fusion workloads. This shift is digitizing the power-performance tradeoff that previously forced feature disablement.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk biometric identification and medical diagnostic devices before CE marking. Manufacturers must maintain technical documentation and quality management systems auditable by notified bodies. Health-monitoring wearables with arrhythmia detection algorithms face the most stringent documentation burdens, pushing some OEMs to remove diagnostic claims from consumer marketing.
Direct-to-consumer subscription models for device-plus-service bundles are displacing traditional retail channel dependence for premium audio and fitness categories. Peloton-style hardware-software integration is migrating to hearing aids and sleep trackers, with recurring revenue offsetting upfront hardware subsidies. This pattern is most visible in the United States, where HSA/FSA eligibility for certain wellness devices accelerates subscriber acquisition economics.
Digital Devices Technologies Market Segmentation
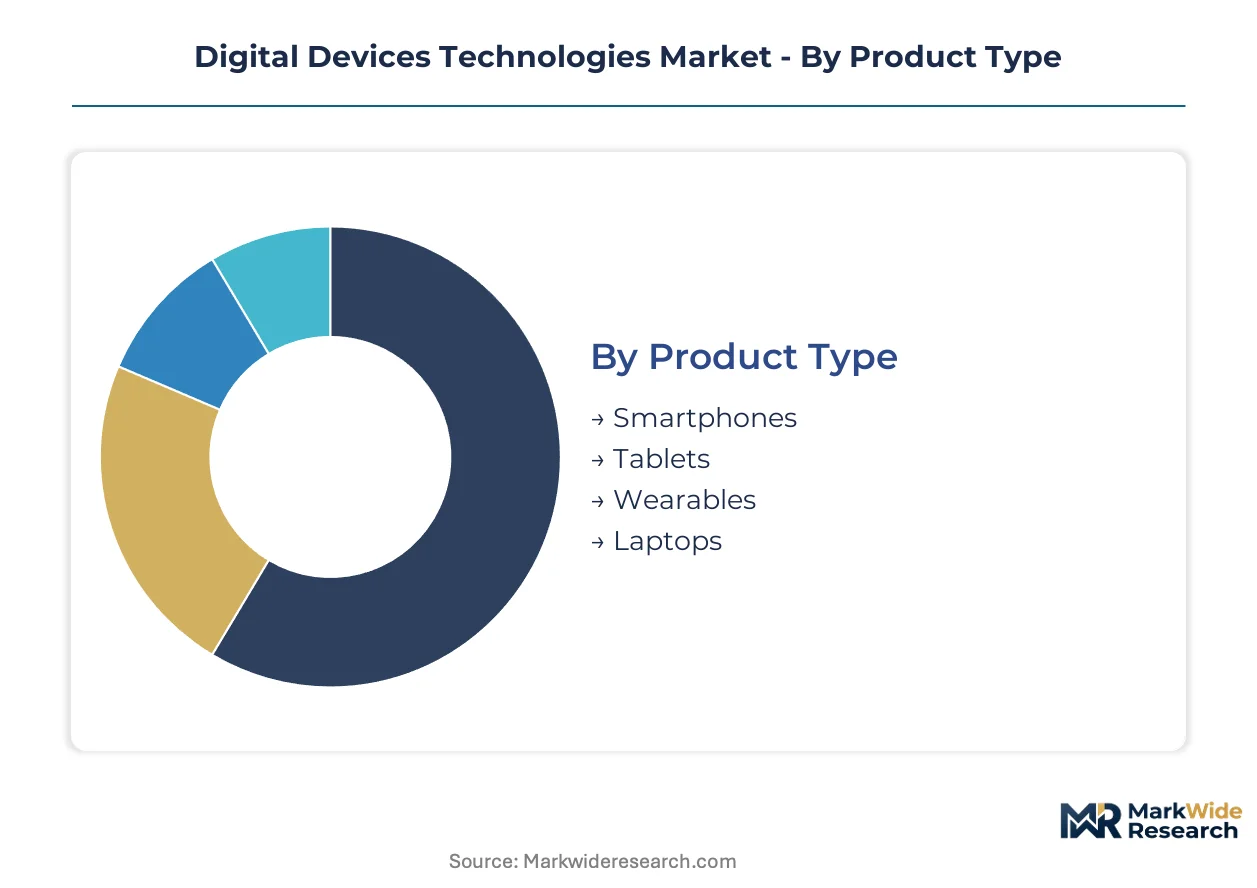
Segmentation reveals how Digital Devices Technologies fragment across competing performance requirements, regulatory exposure, and replacement cycles. Each dimension carries distinct margin profiles and certification burdens that reshape vendor prioritization.
Product Type:
After-sales service intensity varies dramatically across form factors, with repairability mandates in France and warranty regulations in Germany driving divergent support infrastructure investments.
- Smartphones:Mature category with standardized component ecosystems enabling third-party repair networks. Demand concentrates in China and India where MIIT certification and domestic assembly scale compress retail pricing. Replacement cycles extend as performance plateaus and right-to-repair regulations mandate spare parts availability.
- Wearables:Biosensor-integrated wristbands and patches require FDA 510(k) or EU MDR conformity for diagnostic claims. Hospital procurement in the United States accelerates through CMS reimbursement codes for remote patient monitoring. This segment climbs fastest as chronic disease management programs expand.
- Tablets:Education sector procurement in South Korea and Japan sustains volume despite consumer stagnation.
- Laptops:Enterprise refresh cycles in Germany and thermal design constraints at 15-100 watt TDP thresholds segment commercial from consumer configurations.
Smartphones hold the largest share; momentum sits with wearables.
Technology:
Cost tier differentiation separates premium algorithm licensing from commodity connectivity stacks, with royalty structures determining OEM margin capture.
- Artificial Intelligence:Edge inference engines redistribute computational load from cloud to device endpoints. EU AI Act conformity assessments impose documentation burdens on high-risk biometric identification systems. Healthcare monitoring algorithms face the most stringent notified body audit requirements.
- IoT:Ambient sensing architectures enable predictive maintenance in industrial facilities and smart home automation. Protocol fragmentation between Modbus, OPC-UA, and proprietary SCADA architectures complicates edge gateway deployment in German manufacturing plants.
- Augmented Reality:Enterprise training applications in aviation and logistics sustain niche commercial viability despite consumer adoption constraints.
- Virtual Reality:Thermal management limitations at 15-watt TDP thresholds restrict standalone headset form factors to enterprise training deployments.
IoT holds the largest installed base; steepest expansion trajectory belongs to Artificial Intelligence.
End User:
Customer type determines procurement channel structure, with direct-to-consumer subscription models displacing traditional retail dependence in premium categories.
- Healthcare Providers:Hospital systems procure biosensor-enabled devices through group purchasing organizations. FDA software-as-medical-device pathways and EU MDR compliance requirements favor established manufacturers with dedicated regulatory affairs teams. CMS billing code expansion for remote patient monitoring accelerates wristband and patch procurement in the United States.
- Consumers:Direct-to-consumer platforms and subscription bundles for device-plus-service offerings reshape acquisition economics. HSA/FSA eligibility for certain wellness devices in the United States accelerates subscriber acquisition for sleep trackers and hearing aids.
- Enterprises:Industrial IoT deployments in German manufacturing require BSI cybersecurity certification for connected device procurement.
- Educational Institutions:Bulk procurement contracts in South Korea and Japan sustain tablet volume despite consumer market stagnation.
Consumers command the largest volume; Healthcare Providers gain share fastest.
Application:
Application focus dictates sensor fusion requirements and thermal design constraints, with always-on health monitoring imposing the most severe power-performance tradeoffs.
- Healthcare Monitoring:Continuous biosensor fusion for arrhythmia detection and fall detection requires neuromorphic processing chips to sustain multi-day battery life. EU AI Act risk classification and FDA 510(k) timelines averaging 18-24 months delay revenue recognition for diagnostic claim devices.
- Smart Home:Ultra-wideband ranging combined with Bluetooth Low Energy digitizes spatial awareness for asset tracking and indoor navigation. Germany BSI cybersecurity certification mandates create first-mover advantages for OEMs achieving CC EAL4+ ratings.
- Gaming:Thermal management at 100+ watt TDP thresholds forces active cooling systems that degrade waterproofing ratings in premium handheld configurations.
- Communication:Mature category with margin compression as 5G modem integration becomes standard across all price tiers.
Communication holds the largest share; Healthcare Monitoring expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese manufacturing clusters where MIIT certification and domestic scale compress unit economics, while German and US markets absorb premiums for regulatory-compliant health-monitoring devices.
United States
Hospital procurement of biosensor-enabled wearables accelerates through CMS reimbursement codes for remote patient monitoring. FDA software-as-medical-device pathways impose 18-24 month certification timelines that favor established manufacturers with dedicated regulatory affairs teams. Silicon Valley and Boston corridor concentrate edge AI inference engine development for health applications.
China
Domestic brands capture volume through MIIT certification and GB standard compliance achieved at 15-20 percent cost advantages over import-dependent competitors. SAMR network access licenses shape product roadmaps and limit foreign penetration without local certification. Shenzhen and Dongguan manufacturing clusters scale component ecosystems for wearables and smartphones.
Germany
Industrial IoT deployments in manufacturing plants drive demand for BSI cybersecurity-certified connected devices. EU AI Act conformity assessments create first-mover advantages for OEMs achieving CC EAL4+ ratings ahead of harmonization. Bavaria and Baden-Württemberg anchor precision engineering supply chains for automotive-integrated electronics.
Japan
METI standards and PMDA pathways govern diagnostic device market entry for health-monitoring wearables with algorithm-driven features. Enterprise refresh cycles for laptops and tablets sustain commercial volume despite consumer stagnation. Tokyo-Osaka corridor concentrates neuromorphic processing chip development for always-on sensor applications.
India
Production-linked incentive schemes for electronics assembly attract component suppliers to Uttar Pradesh and Tamil Nadu, creating export-competitive capacity. BIS certification requirements shape domestic product specifications for smartphones and wearables. Bangalore and Hyderabad clusters build firmware engineering talent for embedded systems development.
Digital Devices Technologies Market Vendor Landscape
Vertically integrated conglomerates and specialized component suppliers split the market across premium and volume tiers. Samsung and LG Electronics anchor the consolidated display and semiconductor supply chain segment, while audio-visual specialists and networking equipment providers occupy narrower verticals. Strategic archetypes include captive foundry operators, premium brand licensors, and subscription-model hardware-software integrators. Competitive moves center on backward integration into semiconductor supply and geographic diversification of final assembly capacity.
Among diversified electronics conglomerates, Samsung and LG Electronics exemplify the vertically integrated archetype through captive display and semiconductor production. Sony occupies a position as a premium audio-visual engineering specialist with proprietary content ecosystem leverage. Bose Inc. anchors the specialized audio peripheral tier where brand equity sustains pricing power against commodity alternatives.
| Leading Market Players |
|---|
| Samsung |
| Sony |
| Bose Inc. |
| Cisco Systems |
| Philips |
| Hitachi |
| LG Electronics |
| Panasonic |
| Dolby Inc. |
| Others |
Supply Flow & Price Mechanics
Shenzhen and Dongguan manufacturing clusters compress unit economics through MIIT-certified component ecosystems that undercut import-dependent rivals by substantial margins, translating upstream scale into downstream pricing power for domestic brands across wearables and smartphones.
Pricing Analysis
Configured-to-order pricing for enterprise IoT deployments commands substantial premiums over standard consumer SKUs, with three-tier pricing structure across premium, standard, and economy levels separating FDA-cleared diagnostic wearables from wellness trackers and basic fitness bands. Certification grade drives the widest spreads, as EU MDR and FDA 510(k) pathways add compliance costs that OEMs recover through hospital procurement channels. Price erosion runs through entry-level smartphones as MIIT-certified domestic brands exploit manufacturing scale. Healthcare providers show lowest price sensitivity due to CMS reimbursement eligibility, while consumer segments in India and Southeast Asia remain most cost-conscious.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from component distributors help device OEMs manage working capital through 18-24 month FDA certification cycles. Advanced node fabrication draws from Taiwan and South Korea, while lithium-ion cell production concentrates in China and South Korea. Cobalt and nickel feedstock dependency on Democratic Republic of Congo mining and Indonesian processing creates commodity price volatility risk. Distribution runs through direct-to-consumer platforms and hospital group purchasing organizations, with omni-channel retail displacing traditional electronics distributors in premium audio and fitness categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital Devices Technologies markets are shifting toward service-attach revenue models, with subscription bundles for device-plus-software offerings expanding faster than standalone hardware sales as HSA/FSA eligibility and CMS reimbursement codes accelerate recurring revenue economics.
For Market Incumbents: Build regulatory certification moats by expanding dedicated FDA and EU MDR affairs teams ahead of AI Act harmonization. Deepen backward integration into display and semiconductor supply to offset foundry concentration risk from Taiwan Semiconductor Manufacturing and Samsung Foundry. Capture hospital procurement relationships through group purchasing organization contracts before reimbursement codes fully mature. For New Entrants and Emerging Players: Establish a beachhead in industrial IoT edge gateways for German manufacturing plants seeking BSI cybersecurity certification. Target India's PLI scheme manufacturing zones in Uttar Pradesh and Tamil Nadu for export-competitive assembly capacity. Pursue direct-to-consumer subscription positioning for sleep trackers and hearing aids leveraging HSA/FSA eligibility in United States consumer acquisition. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because compliance infrastructure becomes the scarcest asset as FDA software-as-medical-device pathways and EU AI Act conformity assessments extend development timelines. Acquisition targets should concentrate on neuromorphic processing chip specialists and embedded firmware engineering teams with real-time operating system expertise. Watch CMS billing code expansion for remote patient monitoring as the inflection signal for hospital wearable procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Unlocks CMS reimbursement eligibility for diagnostic wearable claims in hospital procurement channels. |
| EU AI Act Conformity Assessment | Secures CE marking pathway for algorithm-driven health monitoring ahead of notified body capacity constraints. |
| MIIT Certification and GB Standard Compliance | Enables domestic China market access with cost advantages from Shenzhen manufacturing cluster scale. |
| Neuromorphic Processing Chip Integration | Extends battery life for always-on biosensor fusion in multi-day wearable deployments. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue offsetting hardware subsidies through HSA/FSA-eligible wellness device bundles. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers at wearable OEMs, regulatory affairs directors navigating FDA 510(k) pathways, and group purchasing organization contract specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, CMS reimbursement code filings, and MIIT certification registries. Bottom-up unit shipment modeling across product types and top-down market sizing through component supply analysis were triangulated for convergence.
Calibration against historical volume trajectories and regulatory approval timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology layer, end-user archetype, and application focus, with thermal design power thresholds and certification jurisdiction cross-cutting multiple dimensions. CAGRs were derived from regression against semiconductor content growth and reimbursement expansion curves, with neuromorphic chip adoption rates and edge AI inference engine deployment serving as technology-specific forecast inputs.
Sensitivities concentrate around FDA timeline compression, EU AI Act notified body capacity constraints, and lithium-ion raw material cost volatility. Forecasts reflect documented assumptions regarding reimbursement code expansion and foundry capacity allocation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
AV Surge Protectors Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Instrument Transformer Market
Electronic Devices & Electrical Systems
Automotive Diode Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Portable Charger Market