
 Europe Low Voltage Switchgear Market | 2026-2036
Europe Low Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Low Voltage Switchgear Market Insights
The capability gap between capital-heavy integrated manufacturers and assembly-focused competitors is bifurcating the competitive landscape. Siemens AG leverages captive semiconductor and software development to dominate digital switchgear architectures. ABB Ltd. anchors its position through deep R&D intensity in smart protection algorithms and predictive maintenance integration. Schneider Electric SE differentiates by controlling distribution channels across French and German industrial corridors.
Europe low voltage switchgear encompasses electrical distribution apparatus rated up to 1,000 volts AC or 1,500 volts DC, comprising molded housings with thermal-magnetic trip units, arc chutes, and electromechanical or solid-state operating mechanisms designed to protect circuits from overload, short circuit, and earth fault conditions in building and industrial power systems. Miniature circuit breakers and residual current devices constitute the mature volume core, while smart switchgear and hybrid switchgear configurations capture expanding margin pools as facility operators prioritize energy monitoring and selective coordination. Panel mounted installations lead in retrofit applications across aging European building stock, though modular formats gain traction in data center and renewable integration projects requiring scalable bus configurations.
CE marking under the EU Low Voltage Directive and IEC 61439 compliance enforced by national metrology institutes shape product design and market access across member states, while the EU Green Deal's building performance standards accelerate replacement cycles in commercial and residential segments. ECHA's REACH restrictions on halogenated flame retardants and persistent organic pollutants are forcing reformulation of insulating materials and enclosure compounds. Stakeholders must monitor the interplay between national grid codes and harmonized product standards as distributed generation penetration reshapes protection coordination requirements.
Market Dynamics
Electrification mandates across European industrial corridors are compressing replacement cycles and forcing wholesale upgrades of legacy protection infrastructure. Facility operators now face simultaneous pressure from the EU Green Deal's building performance standards and the F-Gas Regulation's material restrictions, creating a structural imperative for modernized switchgear architectures.
Growth Catalysts
- EU Green Deal building mandates:Commercial and residential renovation targets in Germany and France are accelerating panel board replacements, pulling forward demand for IEC 61439-compliant assemblies.
- Data center expansion:Hyperscale operators across the Netherlands and Ireland are specifying modular bus configurations with integrated energy monitoring for selective coordination in high-density power architectures.
- Copper-intensive electrification:Industrial facilities in Northern Italy are expanding motor control centers and distribution boards to support automated production lines and EV charging integration.
Market Restraints
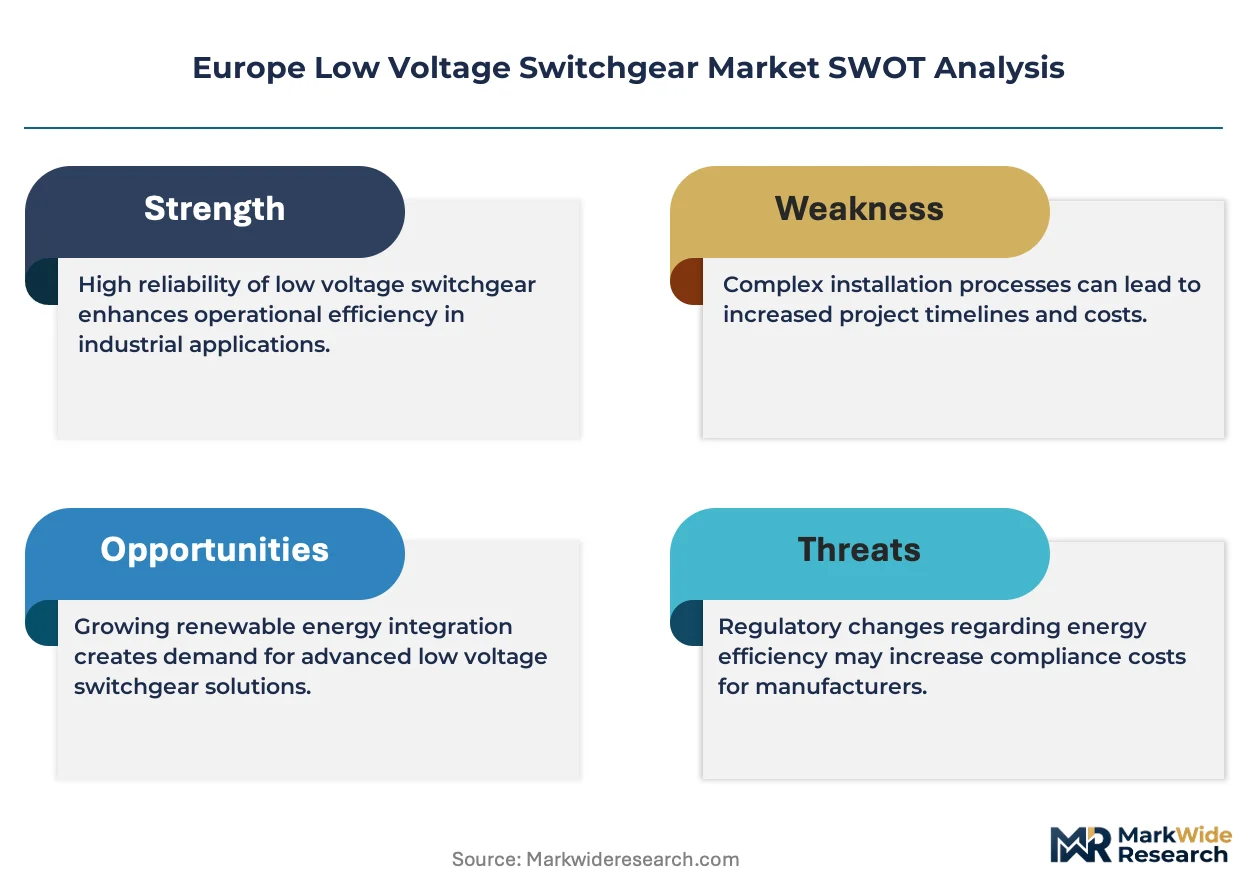
- Silver and copper price volatility:Contact materials and busbar alloys face input cost swings that compress margin predictability for assembly-focused manufacturers without captive metal sourcing.
- Semiconductor supply concentration:Solid-state trip units and smart protection modules depend on wafer fabrication concentrated in East Asian foundries, exposing European OEMs to geopolitical supply interruptions.
- REACH substance restrictions:ECHA's evolving bans on halogenated flame retardants are forcing rapid reformulation of thermoset housings and arc chute materials, extending product recertification timelines.
Strategic Opportunities
- Polish industrial corridor penetration:Manufacturing reshoring and automotive battery plant construction near Katowice and Wrocław are creating demand gaps for local switchgear assembly capacity.
- Smart protection algorithm convergence:Edge computing and IEC 61850 protocol integration enable predictive maintenance overlays that command premium positioning in German chemical processing facilities.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are driving facility managers toward switchgear with embedded carbon footprint tracking and circular material passports.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for digital trip units and communication modules competes with broader industrial automation talent pools, elongating R&D cycles.
- Multi-standard certification complexity:National deviations from harmonized IEC standards in Italy, Spain, and Scandinavia force SKU proliferation and testing redundancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Low Voltage Switchgear Market |
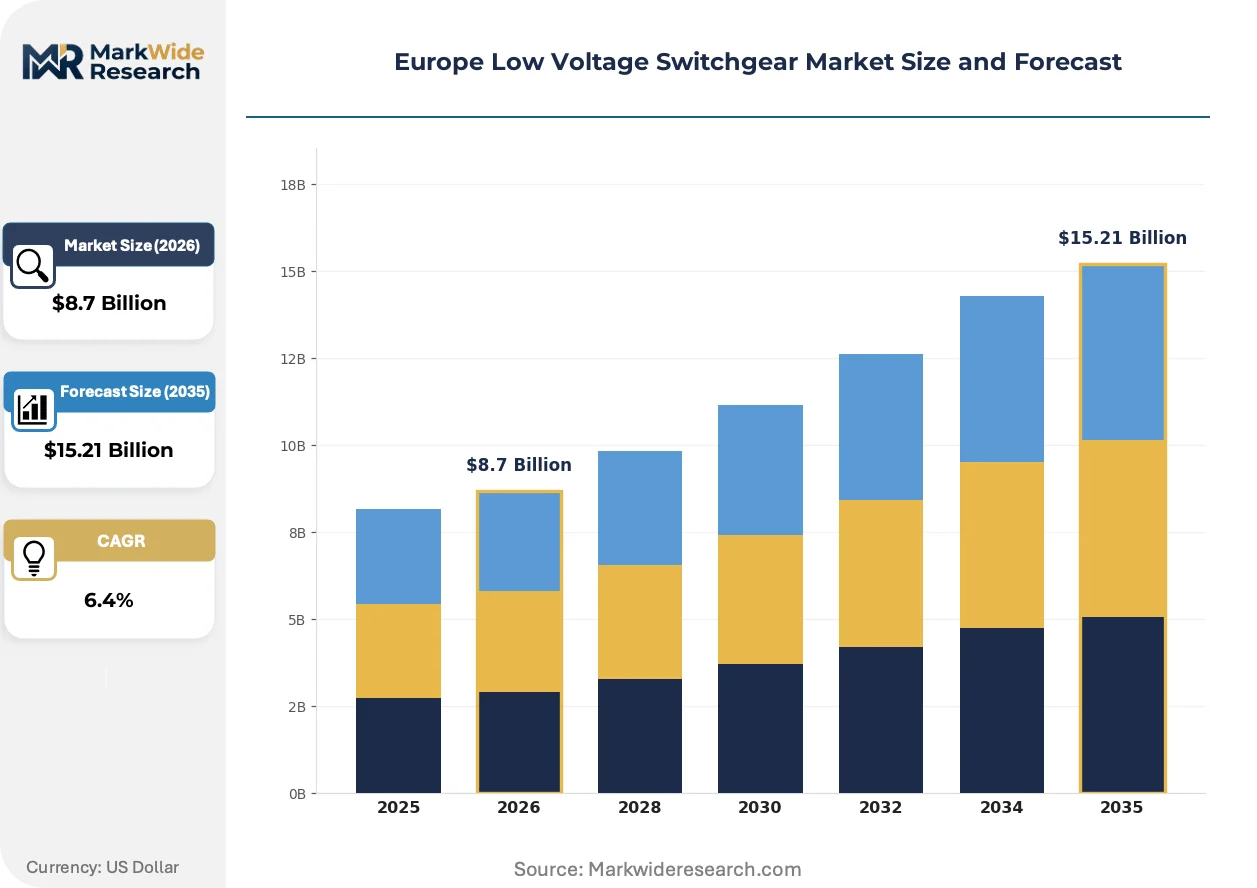
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breakers, Residual Current Devices, Switch Disconnectors, Contactors End User: Commercial, Industrial, Residential, Infrastructure Installation Type: Panel Mounted, Wall Mounted, Free Standing, Modular Technology: Digital Switchgear, Analog Switchgear, Smart Switchgear, Hybrid Switchgear |
| Companies Covered | Eaton Corporation PLC, Rockwell Automation, ABB Ltd., Fuji Electric Co., Ltd., Hitachi Ltd., Siemens AG, Mitsubishi Electric Corporation, HD Hyundai Electric, Schneider Electric SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Low Voltage Switchgear Market Trends and Innovations
Digitalization of protection and control functions is redrawing competitive boundaries between electromechanical specialists and software-capable system integrators. Three developments are compressing traditional product lifecycles and reshaping procurement criteria across European electrical distribution.
Hybrid switchgear configurations combining vacuum interrupters with solid-state controls are fragmenting the historical dominance of pure electromechanical architectures. Data center operators in Frankfurt and Amsterdam clusters are specifying these assemblies for sub-cycle fault isolation and reduced arc flash energy. The technology is compressing margins for conventional molded case circuit breaker suppliers while opening premium positioning for semiconductor-integrated platforms.
REACH restrictions on persistent organic pollutants and halogenated compounds are forcing enclosure material transitions across all voltage classes. Compounders serving the switchgear industry are accelerating bio-based and mineral-filled thermoplastic development to maintain flame ratings without restricted additives. German and French OEMs are most exposed given their reliance on legacy thermoset formulations in industrial-grade panel boards.
Energy-as-a-service contracting is altering capital equipment purchasing patterns among commercial facility operators. Third-party financiers now specify switchgear with embedded metering and remote monitoring capability as loan collateral conditions, displacing traditional specification-driven procurement. This shift is most visible in Spanish and Italian commercial retrofit markets where energy performance guarantees dominate renovation financing structures.
Europe Low Voltage Switchgear Market Segmentation
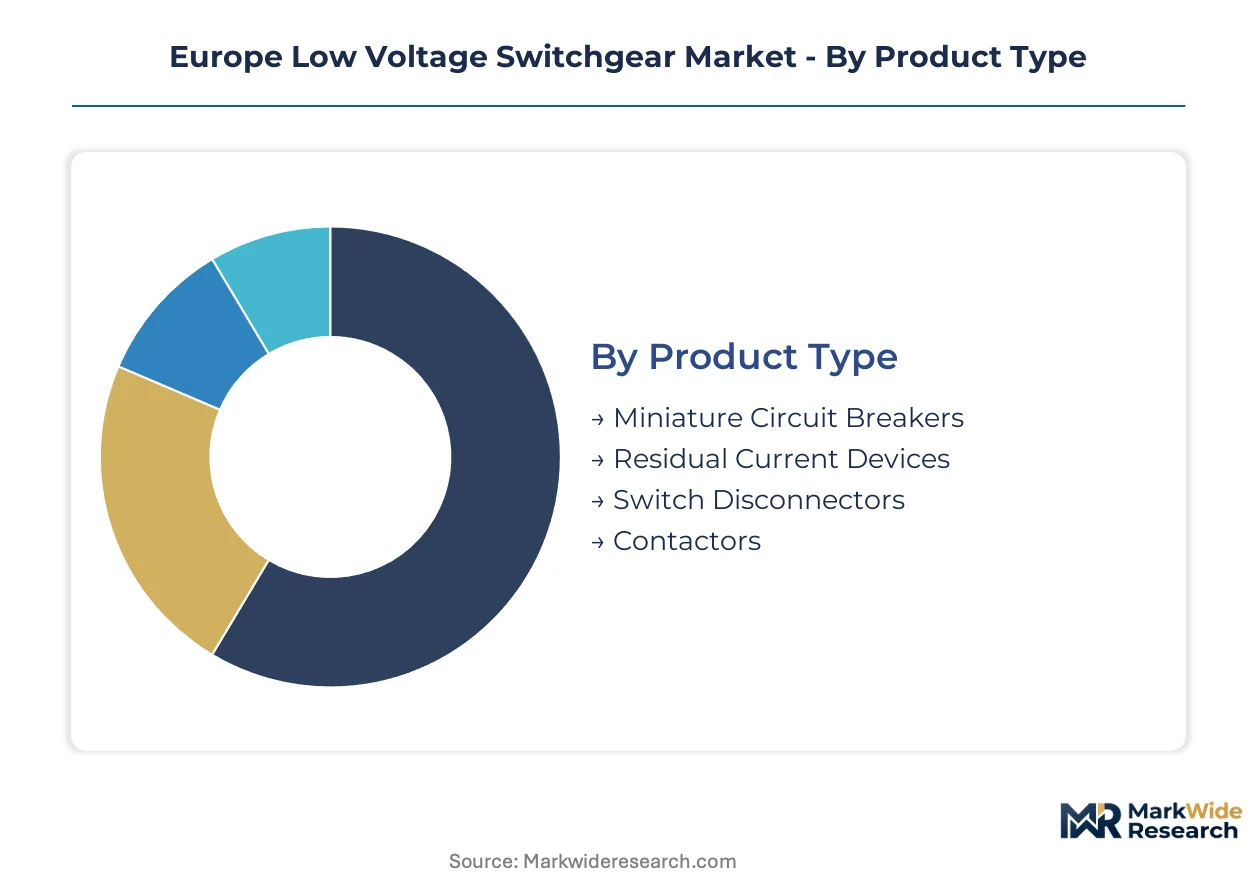
Channel strategy in European low voltage switchgear diverges sharply across product architectures. Electromechanical assemblies flow through electrical wholesalers serving renovation contractors, while digital and smart configurations increasingly route through system integrators and direct OEM relationships with industrial end-users.
Product Type:
Distribution channel intensity varies with product complexity and replacement frequency. Miniature circuit breakers and residual current devices move through high-volume wholesale channels, while switch disconnectors and contactors require more technical specification support.
- Miniature Circuit Breakers:Thermal-magnetic trip units housed in molded casings rated up to 125A dominate residential and light commercial panel boards across Germany and France. IEC 60898 compliance is mandatory for CE marking, with German electrical wholesalers moving the highest volumes through renovation contractor networks.
- Residual Current Devices:Earth leakage protection modules integrating electromechanical or electronic sensing elements command premium positioning in French and Italian markets where TT earthing systems predominate. Mandates for 30mA protection in residential circuits drive replacement cycles in aging Spanish and Portuguese building stock.
- Switch Disconnectors:Load-break isolation devices with visible contact indication serve industrial maintenance safety requirements.
- Contactors:Electromechanical switching devices for motor control and lighting circuits concentrate in Northern Italian automation supply chains.
By volume, Miniature Circuit Breakers leads. By growth pace, Residual Current Devices is ahead.
End User:
Application context determines specification authority and procurement pathway. Industrial buyers emphasize selective coordination and predictive maintenance integration, while residential and commercial segments prioritize cost efficiency and installer familiarity.
- Industrial:Motor control centers and power distribution assemblies in German chemical processing and automotive manufacturing facilities specify IEC 61439-compliant switchboards with integrated energy monitoring. The EU Green Deal's industrial emissions targets accelerate electrification retrofits in Ruhr Valley and Bavarian manufacturing corridors.
- Infrastructure:Data center operators in Amsterdam and Frankfurt clusters demand modular bus configurations with sub-cycle fault isolation for high-density power architectures. F-Gas Regulation compliance and energy performance contracting reshape procurement criteria for critical facility operators.
- Commercial:Office and retail renovation cycles in France and Spain pull standard panel board replacements through electrical contractor channels.
- Residential:Single-family and multi-unit housing construction in Poland and Romania drives volume demand for basic protection devices.
Industrial captures the highest average selling prices. Infrastructure shows the steepest expansion trajectory.
Installation Type:
Physical mounting configuration shapes supply chain logistics and field labor requirements. Fixed installations dominate retrofit applications, while modular formats align with scalable infrastructure buildouts.
- Panel Mounted:Distribution boards and motor control centers assembled in factory-built enclosures constitute the default for European building stock renovation. German and French electrical contractors specify these for residential and light commercial applications where IEC 61439-3 compliance is standard.
- Modular:Scalable busbar systems with plug-in unit compatibility serve data center and renewable integration projects requiring phased capacity expansion. Dutch hyperscale operators and German industrial microgrid developers specify these for flexibility in power architecture evolution.
- Wall Mounted:Surface-installed distribution boards concentrate in residential and small commercial retrofits with space constraints.
- Free Standing:Floor-mounted assemblies for heavy industrial motor control applications concentrate in automotive and metals processing facilities.
Panel Mounted holds volume leadership. Modular is climbing the fastest.
Technology:
Technology tier determines margin structure and competitive set. Electromechanical platforms face commodity pressure, while semiconductor-integrated architectures command premium positioning and require specialized distribution partnerships.
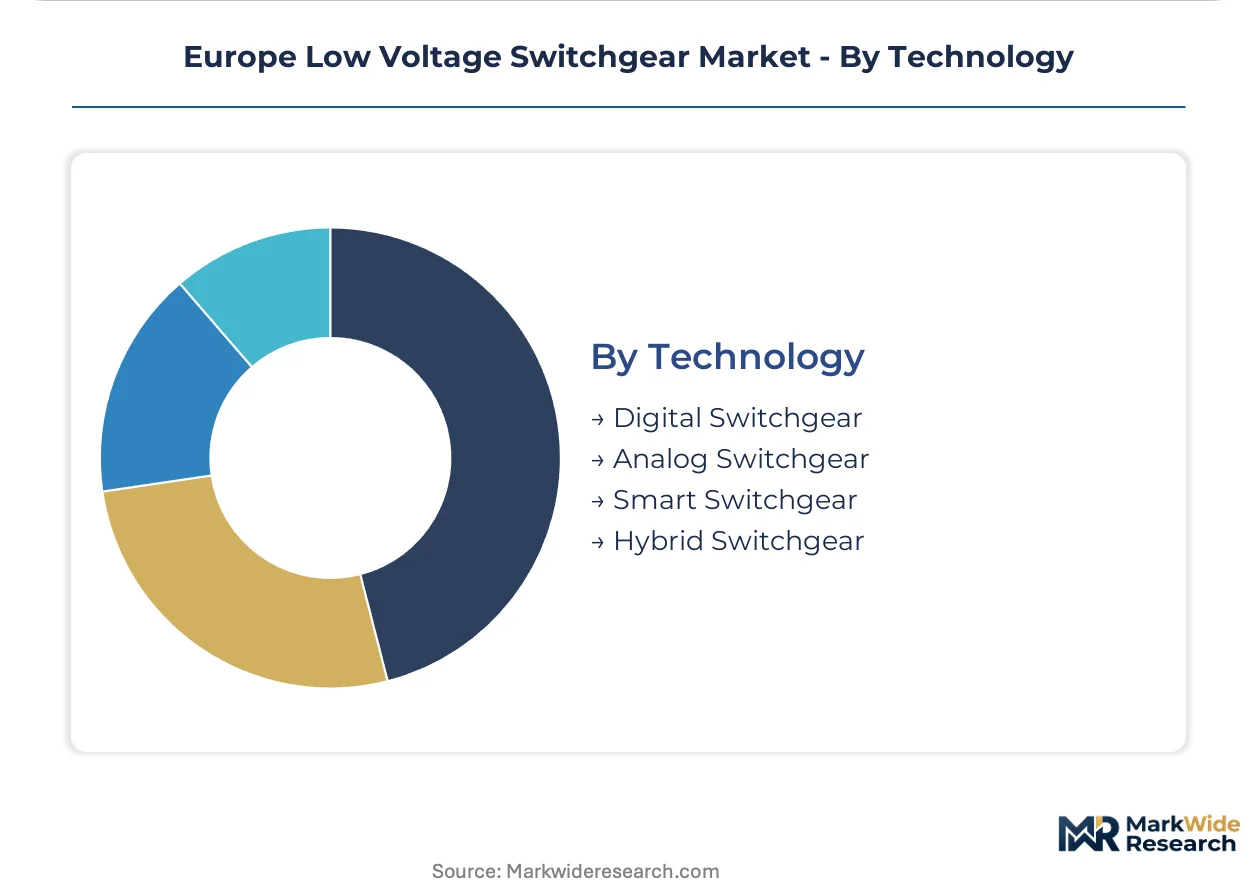
- Smart Switchgear:Protection devices with embedded communication, metering, and edge analytics capability are displacing conventional specifications in German industrial and Dutch data center applications. IEC 61850 protocol integration enables predictive maintenance overlays that justify premium pricing in chemical processing facilities.
- Hybrid Switchgear:Configurations combining vacuum interrupters with solid-state controls deliver sub-cycle fault isolation for arc flash reduction. Frankfurt and Amsterdam data center clusters specify these for selective coordination in high-density architectures, compressing margins for pure electromechanical suppliers.
- Digital Switchgear:Fully electronic protection and control platforms with software-configurable trip characteristics serve advanced industrial automation.
- Analog Switchgear:Conventional electromechanical trip units and thermal-magnetic mechanisms retain cost advantage in price-sensitive residential and commercial segments.
Analog Switchgear dominates current volume. Smart Switchgear is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in Europe's low voltage switchgear market varies sharply by geography. Buyers in Southern and Eastern Europe prioritize cost efficiency in residential retrofits, while German and Dutch industrial operators absorb premiums for digital protection architectures.
Germany
Ruhr Valley chemical processors and Bavarian automotive plants are retrofitting motor control centers with IEC 61850-compliant switchgear. The EU Green Deal's building performance standards mandate panel board replacements in commercial structures. Frankfurt data center clusters specify hybrid switchgear configurations for sub-cycle fault isolation in high-density power architectures.
France
TT earthing system dominance drives residual current device demand across residential and commercial renovation cycles. The F-Gas Regulation tightens material specifications for electrical distribution equipment in industrial facilities. Île-de-France commercial property managers prioritize switchgear with embedded energy monitoring to meet CSRD disclosure requirements.
Italy
Northern Italian automation corridors are expanding motor control centers to support battery plant construction and EV charging integration. ECHA's REACH restrictions on halogenated flame retardants force rapid reformulation of thermoset housings. Lombardy and Piedmont manufacturing clusters specify IEC 61439-compliant assemblies for selective coordination in automated production lines.
Netherlands
Amsterdam hyperscale data centers demand modular bus configurations with integrated energy monitoring for phased capacity expansion. The EU Green Deal accelerates replacement cycles in aging commercial building stock. Eindhoven industrial microgrid developers specify scalable switchgear platforms for renewable integration projects requiring flexible power architecture evolution.
Poland
Manufacturing reshoring and automotive battery plant construction near Katowice and Wrocław create demand gaps for local switchgear assembly capacity. CE marking under the EU Low Voltage Directive shapes product design compliance. Silesian industrial corridors prioritize cost-efficient panel mounted installations for facility electrification retrofits.
Europe Low Voltage Switchgear Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European low voltage switchgear market. The competitive structure consolidates around integrated manufacturers with captive semiconductor development and assembly-focused competitors serving price-sensitive segments. Three archetypes dominate: vertically integrated industrial conglomerates, specialist protection device manufacturers, and regional assembly operations. M&A activity concentrates on digital capability acquisition, while capacity expansion targets Polish and Romanian industrial corridors.
Among European-headquartered industrial conglomerates, Siemens AG and ABB Ltd. occupy positions exemplifying technology-forward archetypes, while Schneider Electric SE anchors the integrated distribution channel model. These three represent the dominant competitive anchors in digital switchgear architectures, smart protection algorithms, and French-German industrial corridor penetration respectively.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| Rockwell Automation |
| ABB Ltd. |
| Fuji Electric Co., Ltd. |
| Hitachi Ltd. |
| Siemens AG |
| Mitsubishi Electric Corporation |
| HD Hyundai Electric |
| Schneider Electric SE |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with East Asian foundries lock in semiconductor supply access while fixing cost visibility for smart protection module production. German and Dutch OEMs leverage these structures to hedge against wafer fabrication volatility, though contract minimums strain working capital for assembly-focused competitors serving Polish and Romanian price-sensitive segments.
Pricing Analysis
After-market service contracts and predictive maintenance subscriptions drive lifetime value capture across digital switchgear portfolios. Three-tier pricing structure across premium, standard, and economy levels segments buyers by IEC 61850 compliance depth and embedded analytics capability. Cost compression in economy-tier electromechanical devices intensifies because copper and silver contact material volatility squeezes margin predictability for non-integrated manufacturers. Residential contractors in Eastern Europe exhibit highest price sensitivity, while Frankfurt data center operators absorb premiums for sub-cycle fault isolation.
Supply Chain Analysis
Strategic stockpiling of copper busbar alloys and silver contact materials dominates inventory strategy among German integrated manufacturers, while just-in-time procurement prevails in assembly-focused Polish operations. Wafer fabrication concentrates in Taiwan, South Korea, and China, with thermoset compounders clustered in Germany and France. Semiconductor supply rests on East Asian foundry concentration, exposing European OEMs to geopolitical interruption risks. Distribution runs through electrical wholesalers serving renovation contractors for volume products, while direct OEM relationships handle smart switchgear configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale data center operators and automotive battery plant developers, compressing supplier margins and demanding embedded service capabilities that fragment traditional equipment-only vendors.
For Market Incumbents: Compound firmware development capabilities for IEC 61850 protocol integration to defend against software-capable system integrators encroaching on German chemical processing accounts. Deepen backward integration into captive semiconductor sourcing to offset East Asian foundry concentration risks. Channel control across French and German industrial corridors remains essential as procurement authority shifts toward facility operators with energy-as-a-service financing. For New Entrants and Emerging Players: Predictive maintenance algorithm gaps in mid-sized Italian manufacturing facilities offer white-space entry where Siemens and ABB prioritize large-account deployments. Polish automotive battery plant construction near Katowice presents the most penetrable geography, with local assembly capacity shortages creating demand windows for regional entrants. Target system integrator partnerships rather than wholesale channel competition to bypass incumbent distribution lock-in. For Investors and Strategic Acquirers: Specialist protection device manufacturers with REACH-compliant thermoplastic formulations represent acquisition targets as ECHA restrictions force rapid material transitions. Long-term viability hinges on digital capability depth rather than electromechanical scale across the analysis window. Watch for IEC 61850 certification velocity among mid-tier players as inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive wafer supply secures smart protection module production against East Asian foundry concentration. |
| REACH-Compliant Material Reformulation | Bio-based thermoplastic development maintains flame ratings without ECHA-restricted halogenated additives. |
| Smart Protection Algorithm Acquisition | Edge analytics capability commands premium positioning in German chemical processing selective coordination. |
| Polish Assembly Capacity Expansion | Local production footprint captures automotive battery plant demand near Katowice and Wrocław corridors. |
| Energy-as-a-Service Partnership Structure | Third-party financier relationships embed switchgear specifications as loan collateral conditions in Spanish retrofits. |
Research Methodology
The analysis maps electromechanical, hybrid, and fully digital switchgear architectures, each validated through electrical contractor interviews, facility maintenance director consultations, and OEM product manager assessments. Primary fieldwork with German wholesalers, French system integrators, and Polish industrial procurement teams combined with secondary validation from IEC standard documentation, ECHA regulatory filings, and national grid code variations. Customs data on copper and silver trade flows, SEC filings from listed electrical equipment manufacturers, and EU Green Deal implementation timelines anchored bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology tier, end-use application, installation configuration, and regional regulatory cluster dimensions. CAGRs derived from segment-level demand buildups incorporating electrification retrofit cycles, data center capacity expansion, and REACH compliance deadlines. Copper price trajectory assumptions and semiconductor supply elasticity shaped forecast sensitivity bounds.
Forecasts assume regulatory continuity in EU Green Deal building mandates and F-Gas Regulation enforcement; material policy shifts would require re-modeling. Commodity price volatility, REACH substance restriction evolution, and East Asian foundry supply interruption represent specific risk factors. Revision becomes warranted when semiconductor lead time volatility or copper futures spread crosses thresholds that alter OEM sourcing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Asia Pacific Transfer Switches Market
Switches
South Korea Reed Sensors Switches Market
Switches
Global Smart Switch Panel Market
Switches
DC Switchgear Market
Switches
Vibration Level Switch Market
Switches
Miniature-Circuit Breaker Market
Switches
Dual Power Transfer Switches Market
Switches
Static Transfer Switches Market
Switches
Mexico Rocker Switch Market
Switches
Global High Voltage Switchgear Market
Switches
Hazardous Location Limit Switches Market
Switches
Reed Switches Sensors Market
Switches
North America Low Voltage Switchgear Market
Switches
In-Wall Smart Switch Market
Switches
Smart Pole-Mounted Switch Market
Switches
Global Light Control Switches Market