
 Electronic Load Market | 2026-2036
Electronic Load Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Load Market Intelligence
Silicon carbide is pivoting into power semiconductor test benches, displacing silicon-based validation setups that require less aggressive thermal cycling. Keysight Technologies leverages its programmable DC load portfolio to anchor premium positioning in automotive battery cycling applications. Chroma ATE dominates Taiwan's test equipment supply chain with vertically integrated manufacturing of high-current electronic loads. Rohde & Schwarz competes through precision RF-integrated load systems that extend into aerospace power subsystem validation.
An electronic load is an instrument that sinks current and dissipates power to test sources such as power supplies, batteries, and solar arrays, with DC loads typically handling 0-1000V and 0-1000A ranges while programmable units offer transient response times below 10 microseconds. The device serves primarily to characterize power conversion efficiency, battery discharge curves, and regenerative energy recovery under controlled conditions. DC loads lead product type revenue due to concentrated demand from lithium-ion battery formation and electric drivetrain testing, while programmable technology captures the fastest expansion as automated test sequences replace manual bench setups in high-volume manufacturing lines. Application segmentation shows power electronics testing as the mature margin pool, whereas renewable energy systems testing represents the emerging growth corridor as inverter validation requirements intensify.
FCC equipment authorization rules shape US market access for programmable loads with embedded wireless monitoring capabilities, while REACH and RoHS compliance in Europe constrains material selection for load resistor elements and heat sink alloys. China's GB standards and MIIT certification requirements for grid-tied energy equipment create a distinct regulatory threshold for imported test equipment. India's BIS compulsory registration scheme for electronic products adds a compliance layer that manufacturers must navigate for direct market participation. Stakeholders should monitor how evolving carbon border adjustment mechanisms and regional content requirements for clean energy supply chains reshape procurement criteria for test and validation equipment across major manufacturing hubs.
Market Dynamics
Silicon carbide power semiconductors are forcing a wholesale rebuild of thermal cycling protocols, rendering legacy validation equipment inadequate for next-generation inverter and battery pack testing.
Growth Catalysts
- EU Green Deal efficiency mandates:Tighter energy conversion standards under the framework are compelling power electronics manufacturers to adopt programmable loads for precise efficiency validation across EV drivetrains and grid-tied inverters.
- Lithium-ion battery formation:Gigafactory expansion in China and South Korea is driving concentrated demand for high-current DC loads capable of simulating aggressive charge-discharge profiles during cell conditioning.
- SiC device qualification:Wide-bandgap semiconductor manufacturers require electronic loads with faster transient response to capture switching losses under elevated temperature ramps.
Market Restraints
- Heat sink alloy costs:REACH and RoHS constraints on copper-tungsten and aluminum alloys used in high-dissipation load resistors are elevating raw material input costs for European manufacturers.
- Precision resistor supply concentration:Manganin and Evanohm foil resistor production concentrates among a handful of Japanese and German specialty metal suppliers, creating single-source vulnerability.
- Regulatory fragmentation:Divergent certification requirements between China's MIIT grid-tied equipment standards, India's BIS compulsory registration, and FCC equipment authorization rules inflate compliance overhead for multi-region product lines.
Strategic Opportunities
- Regenerative load architecture:Energy recovery capabilities that return power to the grid rather than dissipating as heat are capturing interest from battery cycling facilities facing rising electricity costs and carbon accounting pressures.
- Aerospace power subsystem validation:Satellite and electric aircraft programs are creating demand for RF-integrated load systems that combine power sinking with electromagnetic interference characterization.
- Automated test sequence penetration:High-volume semiconductor and battery manufacturing lines in Taiwan and South Korea are replacing manual bench setups with programmable loads supporting Python and LabVIEW script integration.
Industry Challenges
- Thermal management engineering talent:The intersection of power electronics, materials science, and control systems expertise required for next-generation load design exceeds available specialized workforce pools in multiple manufacturing hubs.
- Legacy ATE integration friction:Semiconductor test floors running decades-old handler and prober infrastructure face protocol incompatibility when retrofitting modern electronic loads with Ethernet-based command interfaces.
- Extended certification timelines:Safety agency approvals for high-voltage DC loads exceeding 1000V are stretching validation schedules as UL and TÜV Rheinland apply evolving arc-fault protection standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Load Market |
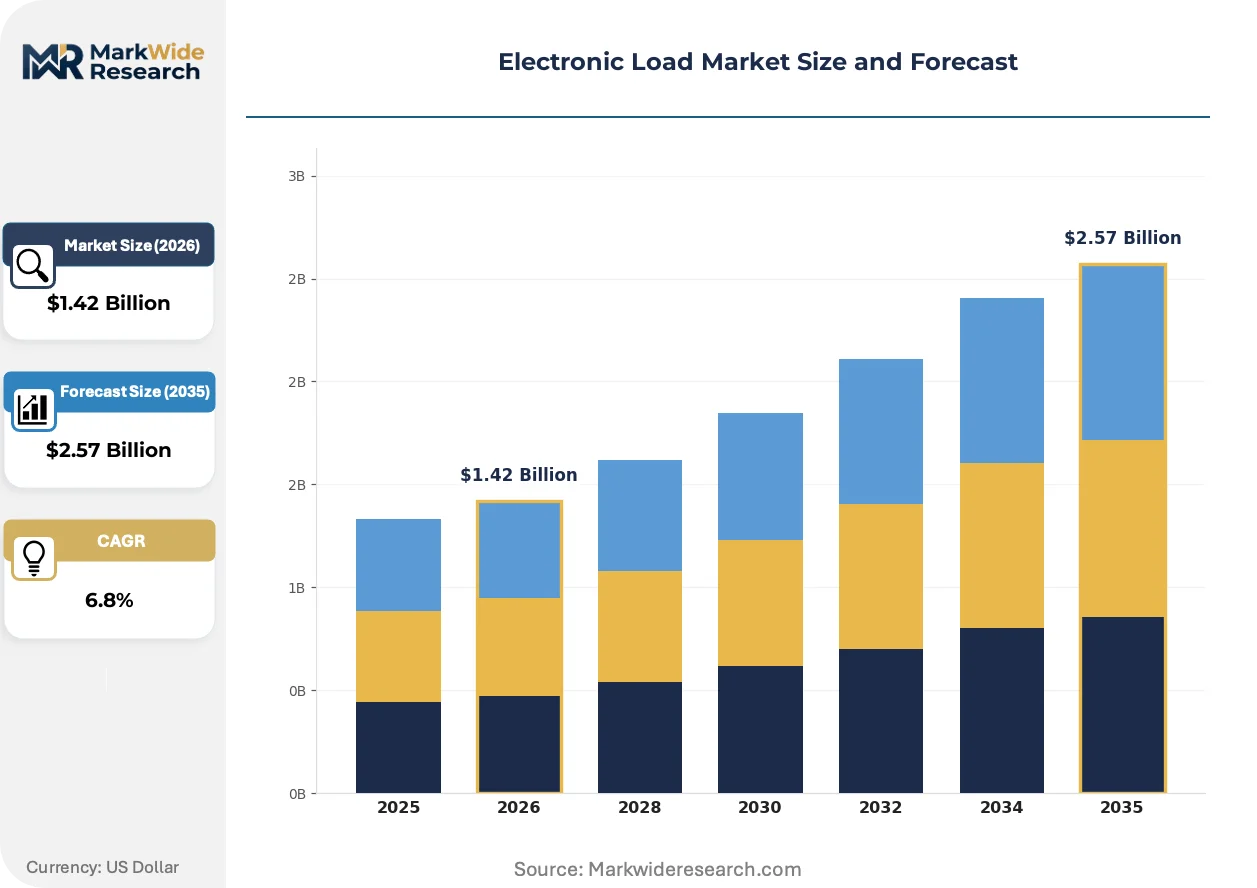
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Load, DC Load, Electronic Load Modules, Resistors End User: Manufacturers, Research Institutions, Testing Labs, Educational Institutions Technology: Programmable, Automated, Manual, Hybrid Application: Power Electronics Testing, Battery Testing, Renewable Energy Systems, Automotive Testing |
| Companies Covered | Keysight Technologies, Chroma ATE, Rohde & Schwarz, Ametek, ITECH Electronic, National Instruments, B&K Precision, Tektronix, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Load Market Strategic Shifts & Innovations
Test equipment architecture is pivoting from passive dissipation toward intelligent energy management, with software-defined control layers and regenerative topologies redefining performance benchmarks across battery and power semiconductor validation.
Wide-bandgap semiconductor test benches are integrating silicon carbide power stages to replicate the thermal and electrical stress conditions that SiC MOSFETs and diodes encounter in deployed EV inverters. Automotive tier-one suppliers and semiconductor foundries are adopting these platforms at accelerated cadences to compress qualification cycles. This integration is compressing the validation timeline for 800V drivetrain components from months to weeks.
REACH substance restrictions and RoHS material bans are forcing redesigns of load resistor elements and heat sink assemblies across European manufacturing. The industrial consequence is a migration toward compliant copper-aluminum composites and advanced ceramic substrates that maintain thermal conductivity without restricted alloying agents. High-precision DC load portfolios targeting automotive and aerospace applications are most affected, with manufacturers accelerating alternative material qualification programs.
Capital equipment purchasing committees are consolidating vendor relationships and demanding multi-year service agreements with guaranteed uptime commitments rather than transactional hardware procurement. Distributor and manufacturer-direct channels are being disrupted by systems integrators offering bundled test cell design, installation, and calibration services. This pattern is most visible in Germany's automotive supply base, where battery and inverter test line contracts increasingly specify full lifecycle support over discrete equipment sales.
Electronic Load Market Segmentation
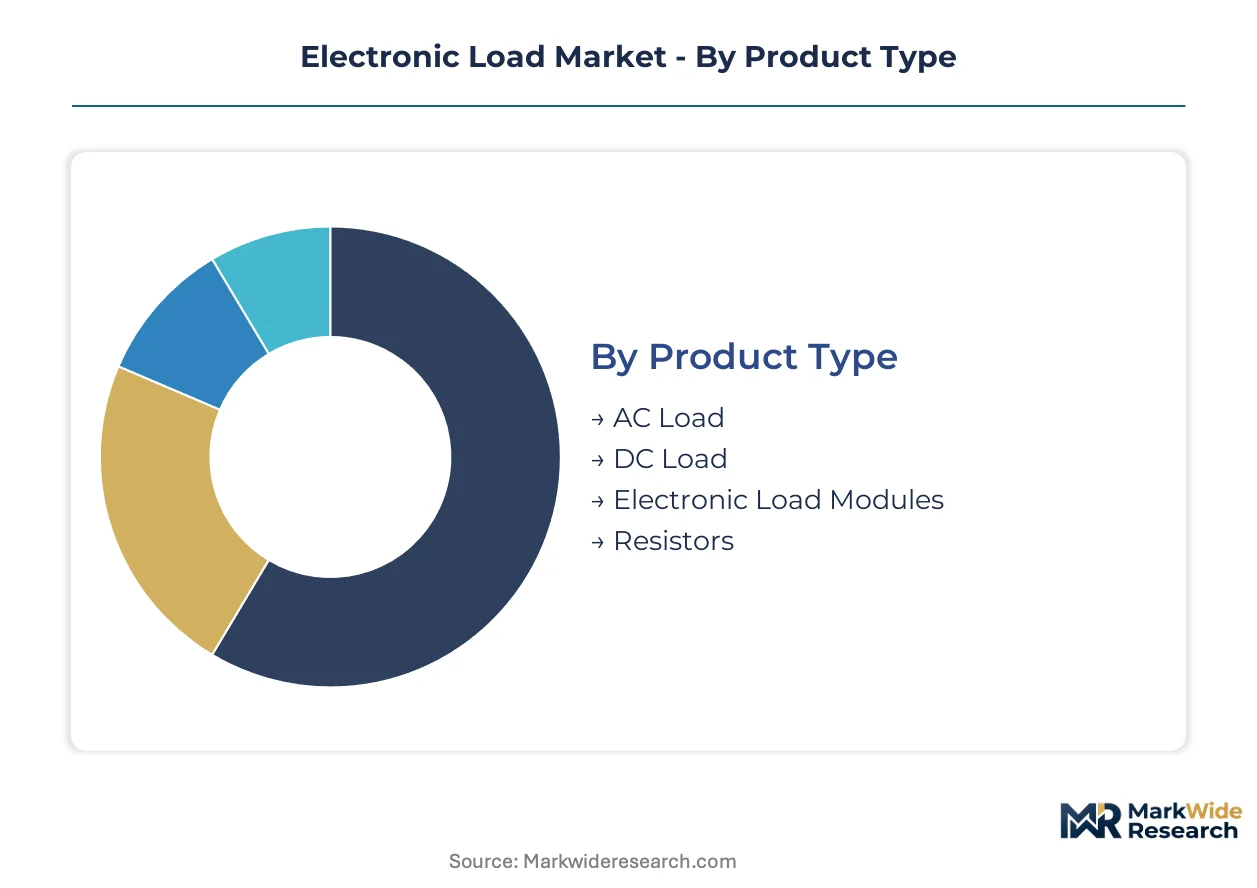
Electronic load architecture fragments across power handling topologies, control interfaces, and end-use validation requirements. Each segmentation axis reveals distinct margin structures and procurement patterns that shape vendor positioning strategies.
Product Type:
Volume deployment clusters in standardized DC platforms, while premium capture concentrates in modular and programmable configurations.
- AC Load:Handles alternating current sinking for inverter and grid-tied equipment validation. Demand concentrates in Germany and South Korea as solar inverter manufacturers expand test capacity under EU Green Deal efficiency mandates.
- DC Load:Dominates revenue through 0-1000V and 0-1000A ranges serving lithium-ion battery formation and electric drivetrain testing. China's gigafactory buildout drives concentrated procurement of high-current units capable of aggressive charge-discharge cycling.
- Electronic Load Modules:Compact units designed for rack-mounted ATE integration. Automotive tier-one suppliers in Germany favor these for flexible test line reconfiguration.
- Resistors:Passive dissipation elements for basic power sinking. REACH and RoHS constraints on copper-tungsten alloys elevate material costs for European manufacturers.
Mature deployment sits with DC Load. Newer deployment is concentrated in Electronic Load Modules.
End User:
Procurement authority divides between high-volume manufacturing floors and qualification-focused validation centers.
- Manufacturers:Semiconductor foundries and battery cell producers operate automated test lines requiring programmable loads with Python and LabVIEW script integration. Taiwan and South Korea represent the densest installed base.
- Research Institutions:Universities and national laboratories pursue wide-bandgap semiconductor characterization. SiC device qualification protocols demand transient response times below 10 microseconds.
- Testing Labs:Third-party validation services for automotive and aerospace power subsystems. RF-integrated load systems extend into electromagnetic interference characterization for satellite programs.
- Educational Institutions:Training equipment for power electronics curricula. Budget constraints favor manual bench setups over programmable alternatives.
Volume procurement dominates Manufacturing. Premium specification capture clusters in Testing Labs.
Technology:
Control sophistication separates legacy bench equipment from automated manufacturing integration.
- Programmable:Software-defined control layers enable automated test sequences and data logging. Expanding most quickly as high-volume lines replace manual setups.
- Automated:Handler and prober integration for semiconductor test floors. Protocol incompatibility with decades-old ATE infrastructure creates retrofit friction.
- Manual:Front-panel operation for benchtop troubleshooting. Educational and small-scale repair applications sustain residual demand.
- Hybrid:Combines manual override with programmable automation. Appeals to R&D environments requiring flexibility across development phases.
Established deployment persists in Manual. Technology migration accelerates toward Programmable.
Application:
Margin pool concentration diverges between mature power electronics validation and emerging renewable energy test requirements.
- Power Electronics Testing:Mature segment covering converter and supply validation. Efficiency characterization under steady-state and transient conditions drives baseline demand.
- Battery Testing:Cell formation, cycle life validation, and safety abuse testing for lithium-ion and solid-state chemistries. China's MIIT certification requirements for grid-tied energy equipment shape equipment specifications.
- Renewable Energy Systems:Inverter and energy storage system validation under variable source conditions. India's BIS compulsory registration scheme adds compliance overhead for imported test equipment.
- Automotive Testing:800V drivetrain component qualification and battery pack cycling. Germany's automotive supply base increasingly specifies full lifecycle service agreements over discrete hardware procurement.
Revenue concentration remains with Power Electronics Testing. Steepest expansion trajectory appears in Renewable Energy Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electronic loads concentrates in three manufacturing corridors: China's battery formation clusters, South Korea's semiconductor test floors, and Germany's automotive electrification supply chain. These geographies anchor procurement volume for high-current DC units and programmable validation systems.
China
Gigafactory buildouts in Shenzhen and Ningde drive concentrated procurement of high-current DC loads for lithium-ion cell formation. MIIT certification requirements for grid-tied energy equipment shape equipment specifications for imported test systems. The Yangtze River Delta hosts dense concentrations of power semiconductor foundries deploying SiC validation benches.
South Korea
Samsung SDI and LG Energy Solution expansion in Gyeonggi Province sustains demand for automated battery cycling equipment. MFDS-equivalent industrial standards for clean energy equipment create compliance thresholds for foreign suppliers. Seoul Capital Area semiconductor test floors represent the densest installed base of programmable loads with Python integration.
Germany
EU Green Deal efficiency mandates compel power electronics manufacturers to adopt programmable loads for EV drivetrain validation. REACH and RoHS constraints on heat sink alloys elevate material costs for domestic manufacturers. Bavaria's automotive supply base increasingly specifies full lifecycle service agreements over discrete hardware procurement.
United States
FCC equipment authorization rules shape market access for programmable loads with embedded wireless monitoring capabilities. NHTSA electrification timelines accelerate battery pack validation requirements for domestic EV programs. Michigan and California host concentrated test lab capacity for automotive power subsystem qualification.
India
BIS compulsory registration for electronic products adds compliance overhead for imported test equipment. PLI scheme incentives for battery cell manufacturing are driving initial demand for formation-grade DC loads. Tamil Nadu and Gujarat emerging as early clusters for gigafactory construction and associated test infrastructure.
Electronic Load Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium programmable systems consolidating around instrumentation incumbents and standard DC loads fragmenting across regional fabricators. The vendor base organizes into three strategic archetypes: vertically integrated test equipment conglomerates, precision electronics specialists, and regional automation integrators. Dominant competitive moves include strategic partnerships for software ecosystem integration and geographic expansion through local calibration service networks.
Within the precision instrumentation tier, Keysight Technologies and Rohde & Schwarz exemplify archetypes anchored in RF and power measurement heritage. Chroma ATE occupies a position representing Taiwan-based vertical integration into automated test equipment. These three entities sit within distinct competitive vectors: RF-integrated load systems, high-volume manufacturing automation, and software-defined control platforms.
| Leading Market Players |
|---|
| Keysight Technologies |
| Chroma ATE |
| Rohde & Schwarz |
| Ametek |
| ITECH Electronic |
| National Instruments |
| B&K Precision |
| Tektronix |
| Teledyne Technologies |
| Others |
Cost & Logistics Intelligence
Thermal management engineering talent concentration in Taiwan and South Korea generates substantial labor-cost differentials that widen pricing spreads between premium programmable loads and standard DC units. European manufacturers absorb elevated heat sink alloy costs under REACH and RoHS constraints, compressing margins on mid-tier offerings while Asian fabricators exploit integrated supply chains to defend economy pricing.
Pricing Analysis
Volume capture clusters in standardized DC loads where economy-tier suppliers compete on unit economics, while margin extraction concentrates in programmable systems bundled with multi-year service agreements. Price differentiation hinges on certification grade—UL and TÜV Rheinland arc-fault approvals command substantial premiums—and after-sales calibration networks. Pricing pressure stems from regenerative load architectures that reduce lifetime energy costs for battery cycling facilities. Semiconductor foundries exhibit lowest price sensitivity due to uptime guarantees, whereas educational institutions face severe budget constraints.
Supply Chain Analysis
Precision resistor supply rests on Japanese and German specialty metal producers—Manganin and Evanohm foil manufacturing concentrates among a handful of suppliers—creating single-source vulnerability for high-precision DC load producers. Raw material dependencies include copper-aluminum composites, advanced ceramic substrates, and silicon carbide power stages. Distribution runs through systems integrators offering bundled test cell design in Germany's automotive supply base, with manufacturer-direct channels retaining share in Taiwan's semiconductor test floors. Tariff exposure on Chinese-sourced heat sink alloys elevates input costs for European assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around programmable load specialists capable of absorbing certification complexity and service infrastructure investments. REACH substance restrictions and extended UL validation timelines for high-voltage units are forcing sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Deepen backward integration into precision resistor sourcing to mitigate Japanese supplier concentration risk. Anchor premium positioning through captive calibration service networks in Germany and South Korea, defending against emerging Taiwanese automation integrators with aggressive service bundling. For New Entrants and Emerging Players: Launch via systems integrator partnerships targeting India's PLI-subsidized battery formation facilities, where BIS compliance overhead deters direct foreign entry. Penetrate the educational equipment segment through hybrid manual-programmable units priced below Keysight and Chroma ATE bench offerings. For Investors and Strategic Acquirers: Re-rating potential sits with precision electronics specialists possessing MIIT certification infrastructure and established China service presence, given accelerating domestic gigafactory buildouts. Long-term viability favors targets with software-defined control platforms and Python integration capabilities. Monitor regenerative load adoption rates in European battery cycling facilities as inflection signal for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Load Architecture Development | Energy recovery capabilities address carbon accounting pressures at LG Energy Solution cycling facilities. |
| MIIT Certification Infrastructure Investment | Grid-tied equipment approval unlocks direct procurement from CATL and BYD gigafactory projects. |
| Python and LabVIEW Integration Partnership | Script compatibility secures placement on Samsung SDI automated test floors in Gyeonggi Province. |
| Calibration Service Network Expansion | Guaranteed uptime commitments satisfy Bavarian automotive tier-one supplier procurement committees. |
| Copper-Aluminum Composite Resistor Qualification | REACH-compliant materials substitution defends European manufacturing cost position against Asian imports. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with semiconductor test floor managers, battery formation engineers, power electronics procurement leads, and thermal management R&D directors. Primary fieldwork validated shipment volumes and pricing tiers across Taiwan, South Korea, Germany, and China. Secondary sources included MIIT equipment certification databases, ECHA REACH substance restriction updates, UL safety approval registries, and SEC filings from listed test equipment manufacturers. Bottom-up unit economics and top-down sectoral demand estimates were reconciled through iterative triangulation.
Data-stream reconciliation across product type, end user, technology, and application segmentation generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth rate distributions weighted by revenue contribution. Modeled dimensions included power handling topology, control interface sophistication, and regional regulatory cluster. Industry-specific forecast inputs incorporated SiC device qualification protocol adoption curves and gigafactory construction pipelines.
Regulatory timeline shifts, commodity alloy price volatility, and workforce availability constraints are the dominant revision risks. Forecasts reflect assumptions regarding certification standard stability and clean energy supply chain localization policies. A small set of named triggers—EU carbon border adjustment implementation, Chinese dual carbon goal acceleration, and Indian PLI scheme expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Broadcasting Equipment Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
AV Surge Protectors Market
Electronic Devices & Electrical Systems
Automotive Diode Market
Electronic Devices & Electrical Systems
Global Hybrid Devices Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
Digital Instrument Transformer Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market