
 Global Automotive Electronic Devices Market | 2026-2036
Global Automotive Electronic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Electronic Devices Market Intelligence
Automotive embedded software engineering talent scarcity is unwinding production timelines for next-generation vehicle platforms. Tesla leverages its in-house chip design capability to sustain vertical integration advantages in autonomous compute. BMW anchors its premium positioning through specialized control unit architectures for chassis dynamics. Toyota competes on manufacturing scale across sensor fusion modules for hybrid powertrains.
Automotive electronic devices encompass semiconductor-based components, electromechanical assemblies, and embedded control systems operating across temperature ranges from minus forty to one hundred fifty degrees Celsius, designed to manage power conversion, signal processing, and real-time vehicle communication. Their primary purpose is enabling safe propulsion, occupant protection, and connected mobility in mass-produced transportation equipment. Power electronics for electrified drivetrains now captures the deepest margin pools as OEMs internalize inverter and DC-DC converter sourcing. MEMS-based sensor clusters represent the fastest-expanding technology segment, displacing legacy analog architectures in pressure and inertial measurement roles. Infotainment systems remain mature in hardware terms, though software-defined cockpit platforms are renewing upgrade cycles.
FDA-level functional safety expectations embedded within ISO 26262 are reshaping supplier qualification timelines for advanced driver assistance controllers. EU F-Gas Regulation and REACH chemical restrictions are forcing material substitutions in PCB substrates and thermal interface compounds. China's GB standards for connected vehicle data security add parallel compliance layers for modules entering that market. Stakeholders must decide whether to pursue multi-domain certification simultaneously or sequence regulatory approvals by target market entry priority.
Market Dynamics
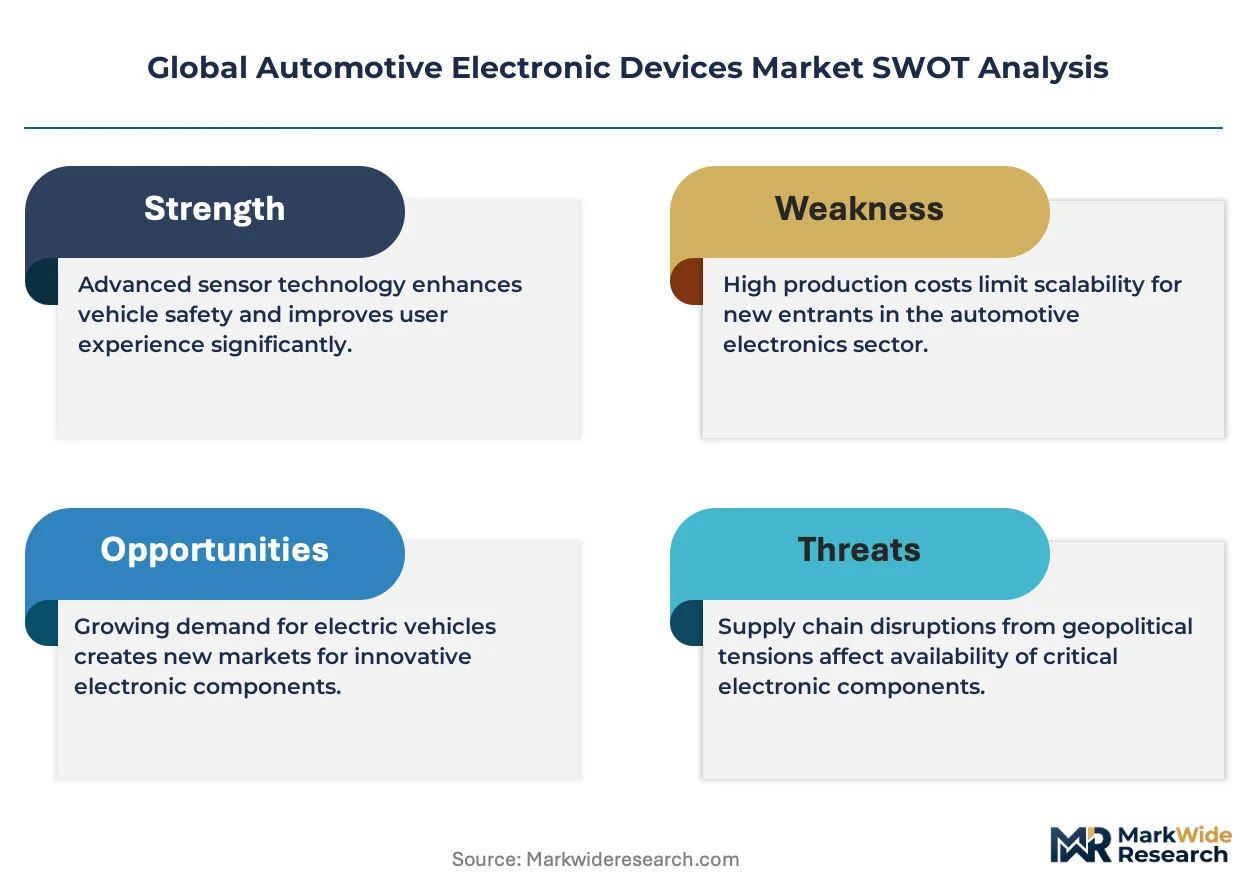
Electric vehicle powertrain electrification is compressing supplier margins while expanding semiconductor content per vehicle, forcing tier-one electronics manufacturers to recalibrate capacity allocation between legacy internal combustion platforms and high-voltage architectures.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential refrigerants in thermal management systems are accelerating demand for redesigned sensor arrays and control modules compatible with new coolant chemistries.
- Silicon carbide power semiconductors:Traction inverter applications are pulling substrate capacity expansion as OEMs pursue efficiency gains in 800-volt architectures.
- China's GB standards for connected vehicle data security:Mandatory encryption and localization requirements are stimulating domestic module production and creating compliance-driven refresh cycles for foreign suppliers.
Market Restraints
- Neodymium and dysprosium price volatility:Rare earth magnet dependence in electric motor position sensors exposes cost structures to Chinese export quota fluctuations.
- Advanced packaging substrate concentration:ABF substrate supply from Taiwan and Japan creates single-source vulnerability for high-density ECU interconnects.
- ISO 26262 ASIL-D certification timelines:Functional safety validation for autonomous driving compute platforms extends development cycles by 18-24 months versus conventional ADAS.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced automotive electronics are attracting module assembly investments to serve domestic and export markets.
- Vehicle-to-everything communication modules:C-V2X chipset integration creates new content opportunities in roadside infrastructure and fleet telematics.
- Software-defined vehicle architectures:Centralized zonal ECU designs enable over-the-air feature monetization and recurring revenue models for cockpit and powertrain functions.
Industry Challenges
- Embedded systems cybersecurity engineering:Shortage of professionals qualified in both automotive functional safety and threat modeling is delaying secure boot implementation for connected modules.
- Legacy 12-volt system integration:Maintaining signal integrity across mixed-voltage architectures during platform transitions consumes validation resources and extends fault-tree analysis timelines.
- Conflict minerals traceability:Smelter and refiner audit requirements for tantalum and tin are complicating multi-tier supplier qualification in Central African sourcing corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Electronic Devices Market |
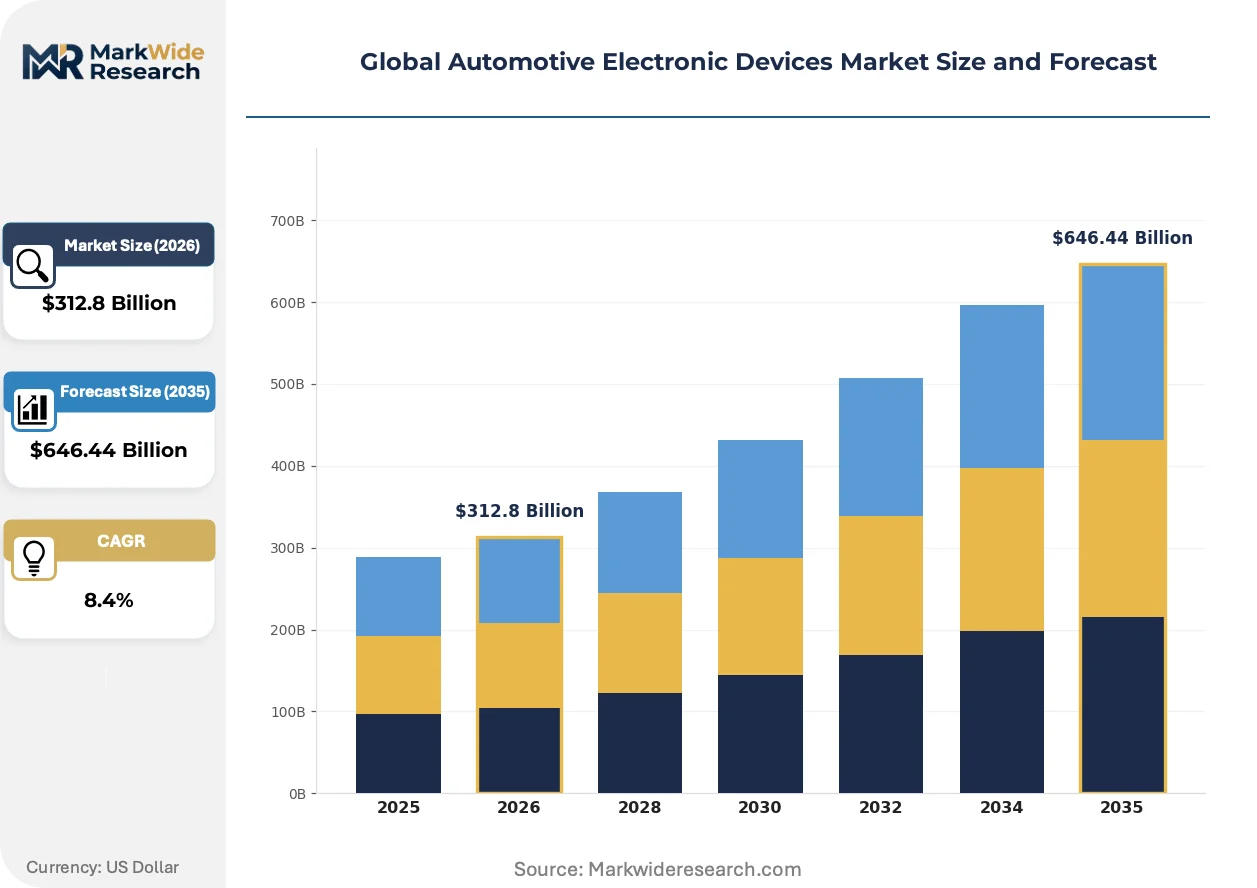
| Market Size in 2026 | $312.8 Billion |
| Market Size in 2035 | $646.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Control Units, Actuators, Infotainment Systems, Power Electronics, Connectivity Modules Technology: Analog, Digital, MEMS, Wireless, Bluetooth, CAN Bus Application: Advanced Driver Assistance, Navigation Systems, Telematics, Engine Management, Body Electronics, Lighting Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Fleet Operators, Repair Shops |
| Companies Covered | General Motors, BMW, Tesla, Mercedes-Benz, Volkswagen, Toyota, Hyundai, Honda, BYD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Electronic Devices Market Strategic Shifts & Innovations
Automotive electronics development is pivoting from discrete component optimization toward system-level architecture decisions that determine software upgradeability and functional safety margins across vehicle lifecycles.
Domain controller consolidation is fragmenting the traditional distributed ECU landscape. Zonal architectures aggregate sensor inputs and actuator outputs into regional compute nodes, reducing wiring harness complexity. Tier-one suppliers are repositioning from box-build manufacturing toward software integration services as OEMs internalize hardware specification.
REACH chemical restrictions and EU F-Gas Regulation are forcing material substitutions in PCB substrates and thermal interface compounds. Suppliers must qualify alternative chemistries without compromising thermal cycling reliability. German and French automotive clusters are investing in localized substrate production to reduce dependence on Asian supply chains.
Fleet operators and mobility service providers are compressing procurement cycles for electronic subsystems. Traditional model-year refresh patterns are giving way to continuous hardware upgradeability demands. This shift is most visible in North American commercial vehicle segments where uptime guarantees drive predictive maintenance module deployment.
Global Automotive Electronic Devices Market Segmentation
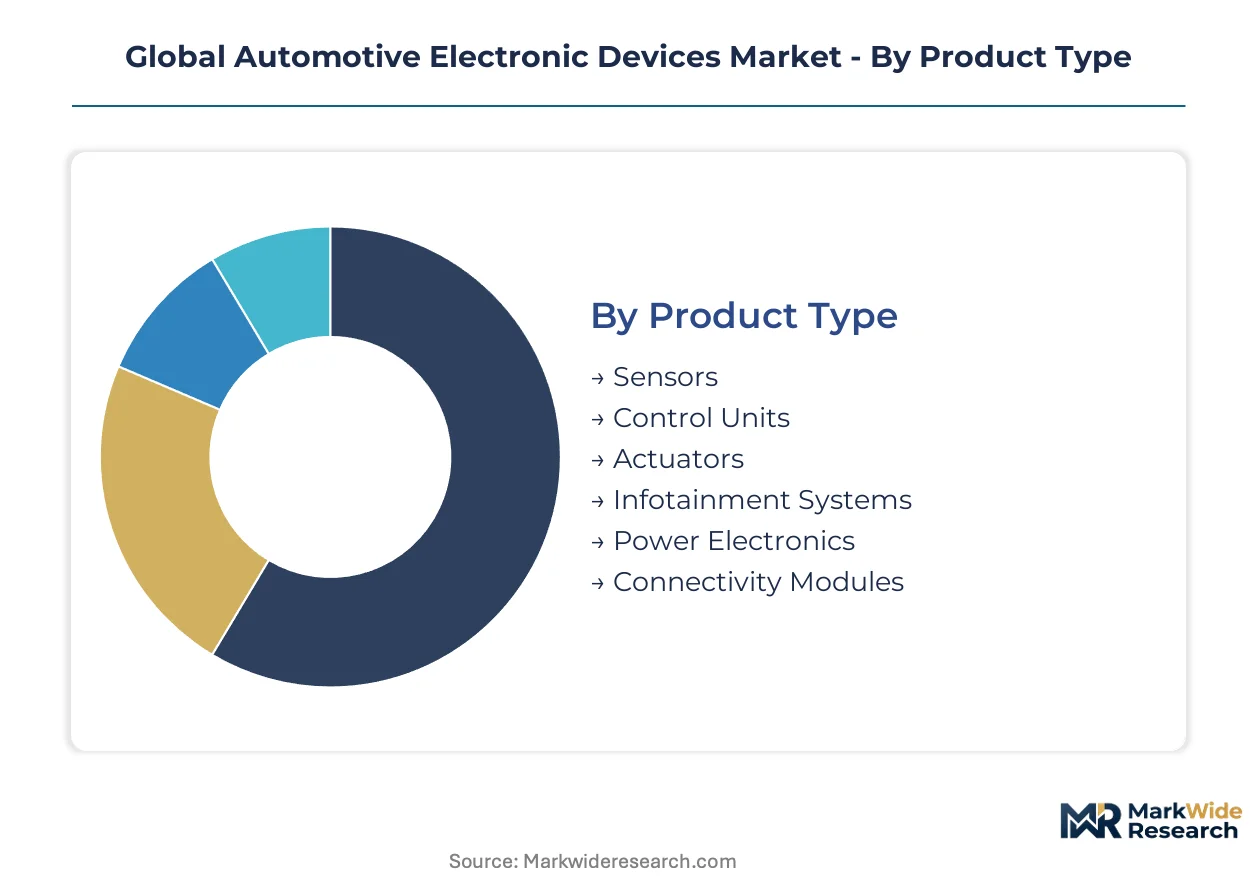
Automotive electronic devices fragment across multiple orthogonal dimensions, each carrying distinct margin profiles and supplier qualification barriers. Segmentation clarity enables stakeholders to align R&D budgets with electrification and software-defined vehicle trajectories.
Product Type:
Power electronics and MEMS-based sensors face the most acute substitution pressure as silicon carbide and solid-state architectures displace legacy silicon and electromechanical alternatives.
- Sensors:MEMS-based pressure, inertial, and environmental sensing modules operate across minus forty to one hundred fifty degrees Celsius. German chassis control suppliers and Chinese battery management system integrators drive procurement concentration for high-reliability variants.
- Power Electronics:Traction inverters, DC-DC converters, and onboard chargers manage high-voltage power conversion in 400-volt and 800-volt architectures. Silicon carbide substrate adoption concentrates demand among Japanese and Korean semiconductor fabricators serving European OEM electrification programs.
- Control Units:Domain controllers and zonal ECUs aggregate distributed computing functions.
- Actuators:Electromechanical and electrohydraulic units execute chassis, powertrain, and thermal management commands.
- Infotainment Systems:Cockpit display and audio hardware faces software-defined upgrade cycles.
- Connectivity Modules:C-V2X and cellular telematics units enable vehicle-to-infrastructure communication.
Control Units anchors the volume base while Power Electronics gains share at the steepest rate.
Technology:
Cost tier stratification separates premium-priced MEMS and wireless architectures from commodity analog implementations in mature vehicle platforms.
- MEMS:Micro-electromechanical systems enable miniaturized pressure, acceleration, and gyroscopic measurement with semiconductor manufacturing economics. Japanese and German sensor specialists dominate substrate fabrication for safety-critical applications.
- Digital:Microcontroller and processor-based signal processing architectures enable software-defined functionality. US and Taiwanese semiconductor houses supply automotive-grade compute for autonomous driving platforms.
- Analog:Continuous signal processing circuits persist in cost-optimized body electronics and legacy powertrain controls.
- Wireless:RF-based communication protocols support keyless entry and tire pressure monitoring.
- Bluetooth:Short-range connectivity enables smartphone integration and diagnostic interfaces.
- CAN Bus:Controller area network protocols maintain dominance in powertrain and chassis communication backbones.
Analog technologies retain the largest installed base while MEMS expands most quickly into safety and electrification applications.
Application:
Volume concentration clusters around electrification-critical functions versus mature segments where hardware refresh cycles have elongated.
- Advanced Driver Assistance:Camera, radar, and lidar fusion systems execute automated emergency braking and lane-keeping functions. German and Chinese regulatory mandates for automatic emergency braking concentrate procurement among tier-one sensor integrators.
- Engine Management:Powertrain control modules optimize combustion and emissions in hybrid architectures. Japanese and Korean OEMs sustain demand for sophisticated engine controllers in markets with prolonged internal combustion transitions.
- Telematics:Cellular-connected modules enable remote diagnostics and over-the-air updates.
- Navigation Systems:GNSS positioning hardware integrates with cloud-based routing services.
- Body Electronics:Door, seat, and climate control modules face cost-down pressure from centralized zonal architectures.
- Lighting Systems:LED and matrix beam controllers enable adaptive headlamp functionality.
Body Electronics represents the most mature volume base while Advanced Driver Assistance climbs the fastest on regulatory mandate expansion.
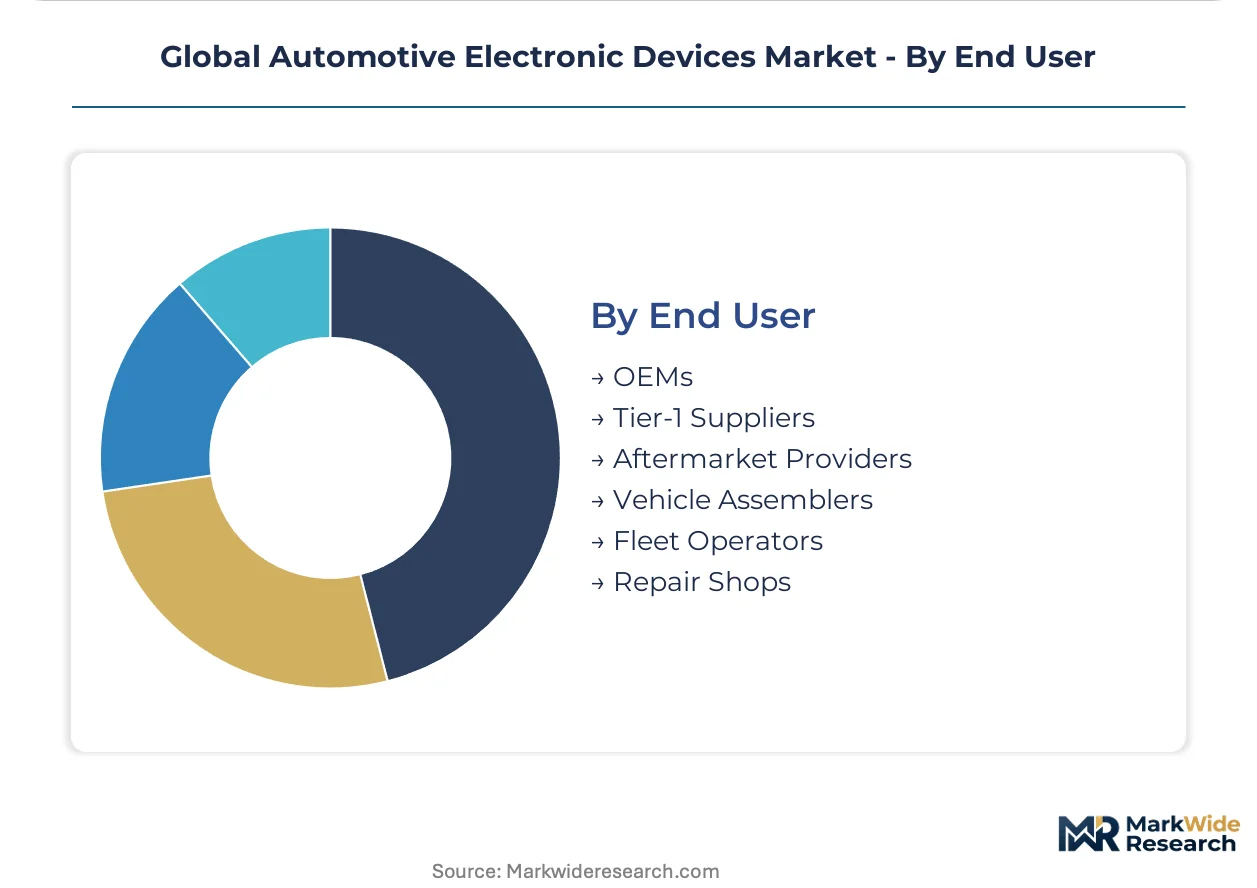
End User:
Customer type determines procurement pattern differentiation between captive internal sourcing and merchant market supply relationships.
- OEMs:Volkswagen, Toyota, and BYD internalize specification authority for domain controllers and power electronics, driving direct semiconductor procurement relationships. Vertical integration into chip design accelerates among premium German and US electric vehicle manufacturers.
- Tier-1 Suppliers:Bosch, Continental, and Denso aggregate component sourcing into subsystem assemblies for OEM customers. Margin compression in high-voltage electrification components forces portfolio restructuring toward software and integration services.
- Aftermarket Providers:Independent distributors serve repair and upgrade demand outside warranty channels.
- Vehicle Assemblers:Contract manufacturers focus on integration rather than component specification.
- Fleet Operators:Commercial vehicle and mobility service buyers compress procurement cycles for predictive maintenance modules.
- Repair Shops:Independent service channels source replacement control units and sensors.
Tier-1 Suppliers capture the dominant procurement volume while Fleet Operators generate the steepest demand expansion through uptime-guarantee service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys automotive electronics predominantly for battery management and powertrain control in mass-market electric vehicles, whereas Germany concentrates resources on chassis dynamics and autonomous compute for premium architectures, and the United States splits demand between Silicon Valley-designed autonomous platforms and Detroit-scale electrification programs.
China
BYD and CATL procurement networks drive silicon carbide demand for 800-volt traction inverters across Ningbo and Shenzhen manufacturing corridors. MIIT's GB standards for connected vehicle data security mandate encryption modules with localized data storage. Yangtze River Delta clusters in Shanghai and Suzhou concentrate domestic module assembly capacity for export markets.
Germany
BMW and Mercedes-Benz specification authority pulls high-density ECU substrate demand toward Bavarian and Baden-Württemberg engineering centers. EU F-Gas Regulation accelerates sensor redesign for low-global-warming-potential refrigerant compatibility. Stuttgart and Munich anchor specialized control unit development for chassis dynamics and autonomous driving compute.
United States
Tesla's in-house chip design and vertical integration model disrupts traditional tier-one procurement patterns in California and Texas. NHTSA advanced driver assistance mandates concentrate camera and radar fusion sourcing among domestic sensor integrators. Detroit automakers sustain demand for hybrid powertrain controllers while Silicon Valley clusters focus on zonal ECU architecture.
Japan
Toyota and Honda manufacturing scale drives sensor fusion module procurement for hybrid architectures across Aichi and Tochigi prefectures. METI carbon neutrality roadmaps accelerate silicon carbide adoption in traction inverter applications. Nagoya and Tokyo-Yokohama corridors concentrate MEMS fabrication for safety-critical pressure and inertial measurement.
South Korea
Hyundai and Kia electrification programs pull power semiconductor demand toward domestic fabricators serving 400-volt and 800-volt platforms. MFDS automotive cybersecurity guidelines add compliance layers for connected module exports. Seoul Capital Area and Busan-Ulsan clusters concentrate battery management system integration and onboard charger manufacturing.
Global Automotive Electronic Devices Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with OEMs internalizing specification authority for domain controllers and power electronics while tier-one suppliers reposition toward software integration services. The structure fragments across captive in-house design arms, merchant semiconductor fabricators, and subsystem assemblers. Dominant archetypes include silicon carbide substrate specialists, zonal ECU integrators, and MEMS sensor fabricators. Competitive moves concentrate on backward integration into chip design and strategic partnerships for 800-volt architecture qualification.
Among integrated OEMs with captive electronics capability, Tesla and BYD exemplify the vertical-control archetype, while BMW represents premium-tier specialization through chassis-focused control architectures. German and Chinese manufacturers anchor opposite ends of the integration spectrum, with Stuttgart-based Mercedes-Benz occupying a position between captive silicon design and merchant semiconductor sourcing.
| Leading Market Players |
|---|
| General Motors |
| BMW |
| Tesla |
| Mercedes-Benz |
| Volkswagen |
| Toyota |
| Hyundai |
| Honda |
| BYD |
| Others |
Cost & Logistics Intelligence
800-volt silicon carbide substrate capacity utilization at Japanese and Korean foundries concentrates pricing power among semiconductor fabricators serving European electrification programs. This scale asymmetry creates divergent price floors between legacy silicon power modules and next-generation traction inverters, while OEMs internalize inverter sourcing to escape margin capture by merchant suppliers.
Pricing Analysis
Long-term offtake contracts dominate silicon carbide substrate procurement, locking in volume commitments from German and US OEMs as they scale 800-volt platforms. Three-tier pricing structure across premium ASIL-D certified, standard automotive-grade, and economy industrial-tier modules separates ISO 26262 validation levels. Cost compression in high-voltage power electronics intensifies as Chinese battery management system integrators enter European supply chains. Fleet operators exhibit the lowest price sensitivity due to uptime-guarantee service models, while aftermarket repair channels face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of ABF substrates and rare earth magnets has replaced just-in-time preferences as Tier 1 suppliers buffer against Taiwan-Japan concentration risk. Taiwan, Japan, and South Korea anchor high-density ECU interconnect fabrication, drawing from neodymium-dysprosium magnet supply exposed to Chinese export quota volatility. Single-source vulnerability in advanced packaging substrates creates structural risk for autonomous driving compute platforms. Distribution runs through captive OEM procurement offices and Tier 1 subsystem assemblers with direct semiconductor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Over-the-air software update subscriptions and predictive maintenance module services are expanding faster than hardware refresh cycles, converting one-time component sales into recurring revenue streams across commercial vehicle and mobility service segments.
For Market Incumbents: Shield domain controller margins by accelerating backward integration into chip design capability, matching Tesla's vertical-control archetype in autonomous compute. Prioritize ISO 26262 ASIL-D certification investment to create qualification barriers against emerging Chinese sensor fusion suppliers. Capacity addition in Indian module assembly corridors under PLI incentives defends cost position against Southeast Asian entrants.
For New Entrants and Emerging Players: Certification fast-track partnerships with German TÜV or US NHTSA testing laboratories compress validation timelines for ADAS controller market entry. White-space concentration sits in C-V2X roadside infrastructure modules for smart city deployments in India and Southeast Asia, where domestic production mandates create procurement preference. Fleet telematics integration services offer the most penetrable go-to-market angle, bypassing entrenched Tier 1 OEM relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among zonal ECU software platform providers with over-the-air monetization infrastructure already deployed. Long-term viability across the analysis window favors acquisition targets with captive semiconductor sourcing relationships and multi-domain certification spanning EU F-Gas, China GB standards, and US NHTSA mandates. Watch silicon carbide substrate utilization rates at Japanese foundries as the inflection signal for power electronics margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Centralized zonal architectures enable Tesla-style over-the-air feature monetization for cockpit functions. |
| Battery Supply Agreement | Direct silicon carbide procurement from Korean fabricators secures 800-volt inverter capacity for European OEM programs. |
| Platform Standardization | Domain controller consolidation reduces wiring harness complexity across BMW and Mercedes-Benz vehicle lines. |
| Geographic Manufacturing Footprint | Indian PLI scheme incentives attract module assembly investments serving domestic and Middle East export markets. |
| Charging Infrastructure Partnership | C-V2X chipset integration creates content opportunities in roadside units for China's connected vehicle deployment. |
Research Approach
Initial hypotheses were tested against primary input from Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and semiconductor fabrication executives and refined through secondary validation. Trade data from customs authorities, IHS Markit vehicle production databases, SEC filings from automotive electronics suppliers, and MIIT GB standard disclosure records anchored supply-side quantification. Bottom-up component content per vehicle estimates triangulated against top-down market value reconstructions.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Silicon carbide adoption curves in 800-volt platforms and zonal ECU penetration rates served as industry-specific forecast inputs.
Underlying assumptions cover electrification program timelines, regulatory mandate enforcement intensity, and semiconductor capacity expansion schedules, with deviation risk concentrated in Chinese export quota volatility and EU F-Gas implementation pace. Revision becomes warranted when silicon carbide substrate utilization crosses 85 percent or when autonomous driving safety certification timelines compress beyond modeled ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Digital Instrument Transformer Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
AV Surge Protectors Market