
 Global Hybrid Devices Market | 2026-2036
Global Hybrid Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid Devices Market Intelligence
A divergence in processing power and display technology is realigning the market, separating premium devices from mass-market alternatives. Microsoft Corporation positions its Surface line at the premium end with high-resolution touchscreens. Lenovo Group competes across multiple price points with its Yoga series, targeting both professional and student segments. Samsung Electronics leverages its display manufacturing prowess to differentiate its tablet and convertible offerings.
Hybrid devices are portable computing machines that combine the functionality of a laptop and a tablet, often featuring detachable or 360-degree hinge keyboards. These products are characterized by touchscreen interfaces, stylus compatibility, and operating systems optimized for both touch and keyboard input. Within product types, laptops with convertible features maintain a dominant share, while detachable tablets show strong growth. The Professionals end-user segment commands the highest value, driven by enterprise fleet purchases through direct sales and specialized electronics stores.
Manufacturers must navigate a complex web of electronics regulations, including FCC Part 15 rules in the United States for radio-frequency interference and CE marking requirements in Europe. In China, all electronic products must comply with GB standards for safety and quality, which impacts component sourcing and final assembly. Future competitive advantage will depend on successfully integrating next-generation wireless technologies while managing rising component costs and supply chain volatility.
Market Dynamics
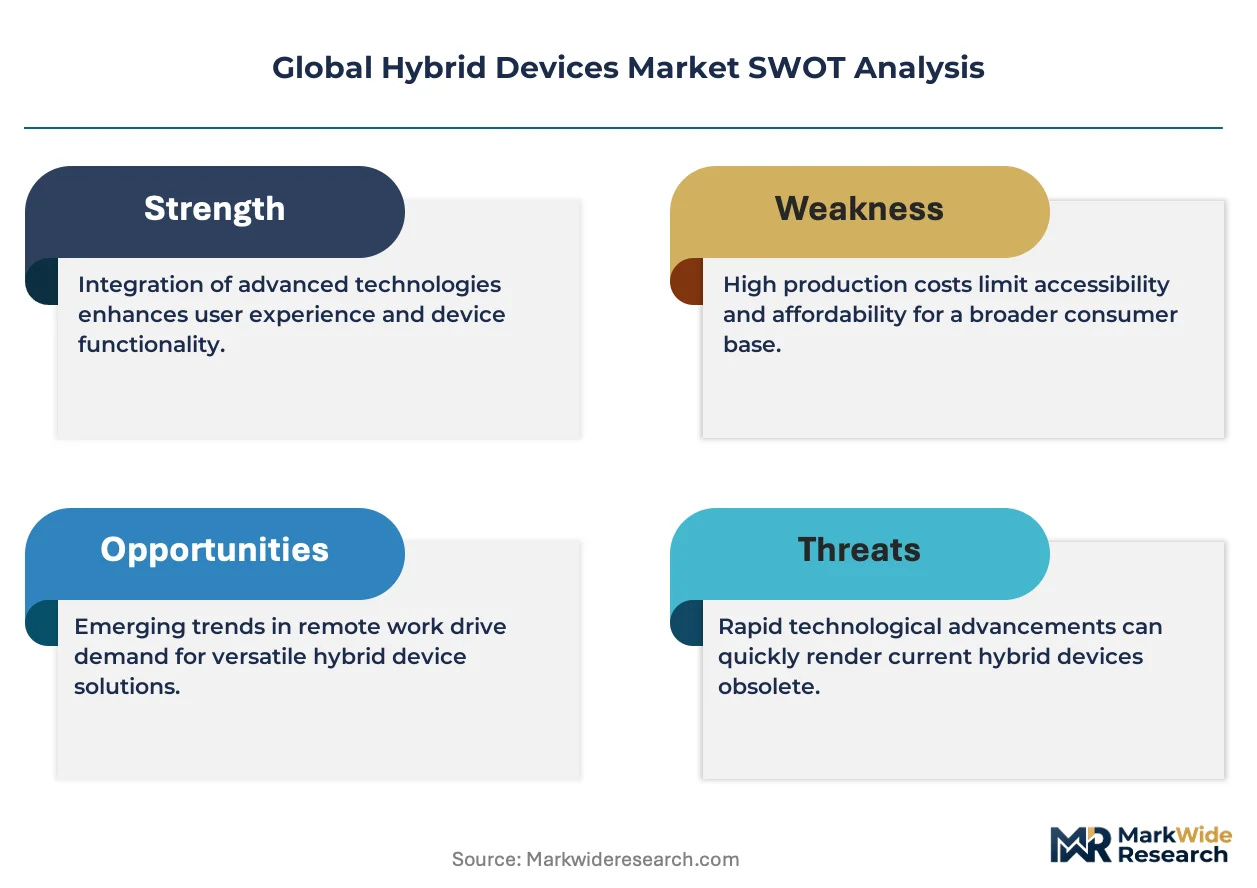
The central tension shaping the hybrid device market is the divergence between enterprise-grade security and performance requirements and the mass-market demand for affordability, creating distinct premium and value-oriented product tiers across the competitive landscape.
Growth Catalysts
- Hybrid Work Models:The widespread adoption of flexible work arrangements by Professionals necessitates versatile computing devices that function seamlessly in both remote and office settings, directly stimulating enterprise fleet purchases.
- Regulatory Compliance:Mandates like the GDPR in Europe are compelling corporations to invest in devices with advanced biometric security, making compliant hybrid models an appealing choice for enterprise refresh cycles.
- Display Technology Advancement:Continuous innovation in high-resolution, power-efficient touchscreen and OLED technologies enhances the user experience, driving upgrades and differentiating premium products in mature markets like Germany and the United States.
Market Restraints
- Component Cost Volatility:Fluctuations in the price of key components, such as processors, memory, and high-resolution display panels, create margin pressure for manufacturers and can lead to price increases for consumers.
- Supply Chain Complexity:The global and intricate nature of the electronics supply chain exposes the market to disruption risks, from component shortages to logistical bottlenecks, impacting product availability.
- Regulatory Fragmentation:Manufacturers must navigate a patchwork of national and regional electronics regulations, including FCC Part 15 in the US, CE marking in Europe, and GB standards in China, which increases compliance costs.
Strategic Opportunities
- Next-Generation Connectivity:Integrating 5G and Wi-Fi 6E technologies into hybrid devices presents a significant opportunity to offer superior connectivity for mobile professionals and create a new feature-based upgrade cycle.
- Educational Segment Expansion:There is a substantial opportunity to develop and market durable, cost-effective hybrid devices tailored for the student segment, an area where penetration is not yet saturated.
- Direct Enterprise Channels:Building out direct sales and service channels for large enterprise customers allows for customized device configurations, fleet management software integration, and stronger long-term client relationships.
Industry Challenges
- Software Optimization:Ensuring that operating systems and applications are fully optimized for seamless switching between touch, stylus, and keyboard inputs remains a persistent software engineering challenge across different hardware platforms.
- Intellectual Property Licensing:The market is characterized by a dense web of patents related to hinge mechanisms, detachable keyboards, and stylus technologies, creating complex and costly licensing negotiations for new entrants.
- Battery Life Limitations:Balancing the demand for powerful processors and bright, high-resolution screens with user expectations for all-day battery life is a difficult engineering trade-off that challenges all manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid Devices Market |
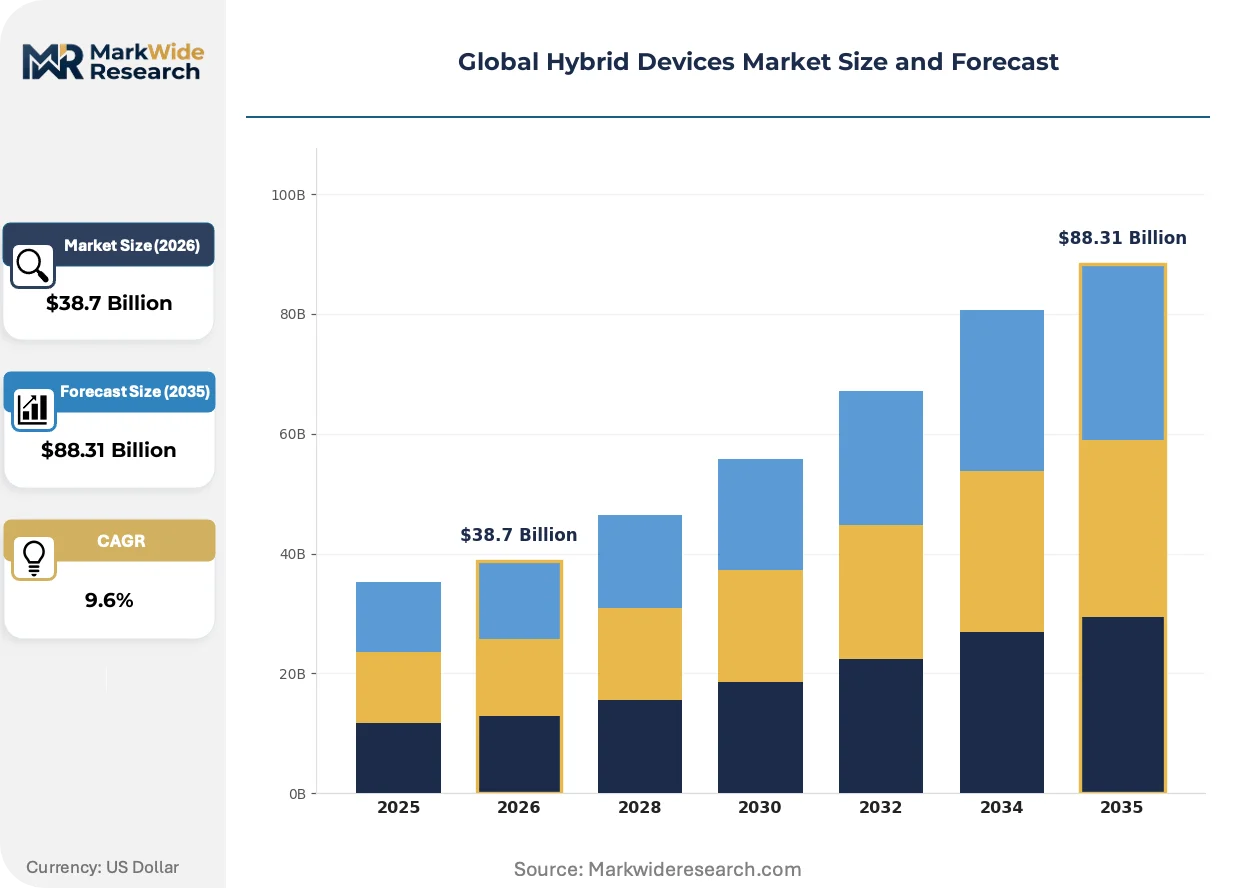
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $88.31 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Laptops, Wearables End User: Students, Professionals, Healthcare Providers, Retailers Technology: Touchscreen, Biometric, Wireless, IoT Distribution Channel: Online Retailers, Electronics Stores, Wholesale, Direct Sales |
| Companies Covered | Dell Technologies Inc., Samsung Electronics, Microsoft Corporation, HP Development Company, Acer Inc., Lenovo Group, Hewlett-Packard Development Company, Fujitsu Limited, ASUSTeK Computer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid Devices Market Strategic Shifts & Innovations
Hardware differentiation is creating a clear stratification between premium devices tailored for corporate users and mass-market alternatives. This split influences everything from component sourcing to channel strategy, with security and display technology acting as key separating factors.
Advanced biometric security, including integrated fingerprint readers and infrared cameras for facial recognition, provides a secure and convenient authentication method. The corporate sector is adopting these features at a swift pace to enhance data protection and meet compliance standards like GDPR. This technology is expanding into mid-range devices as a standard feature, compelling premium brands to innovate further on security integration.
China's GB standards for safety and quality exert significant influence over the global electronics supply chain. These national standards dictate requirements for components and final assembly for all products sold within the country, impacting sourcing decisions for manufacturers worldwide. As a result, global device makers and their component suppliers must align their production and quality assurance processes with these specific Chinese regulations to access the market.
A notable shift in purchasing behavior involves large enterprises moving away from ad-hoc, individual device acquisitions. Instead, they are consolidating procurement through structured fleet purchasing programs that often bypass traditional retail channels entirely. This trend, most visible in the United States and Germany, favors direct sales agreements with manufacturers or partnerships with specialized B2B electronics distributors.
Global Hybrid Devices Market Segmentation
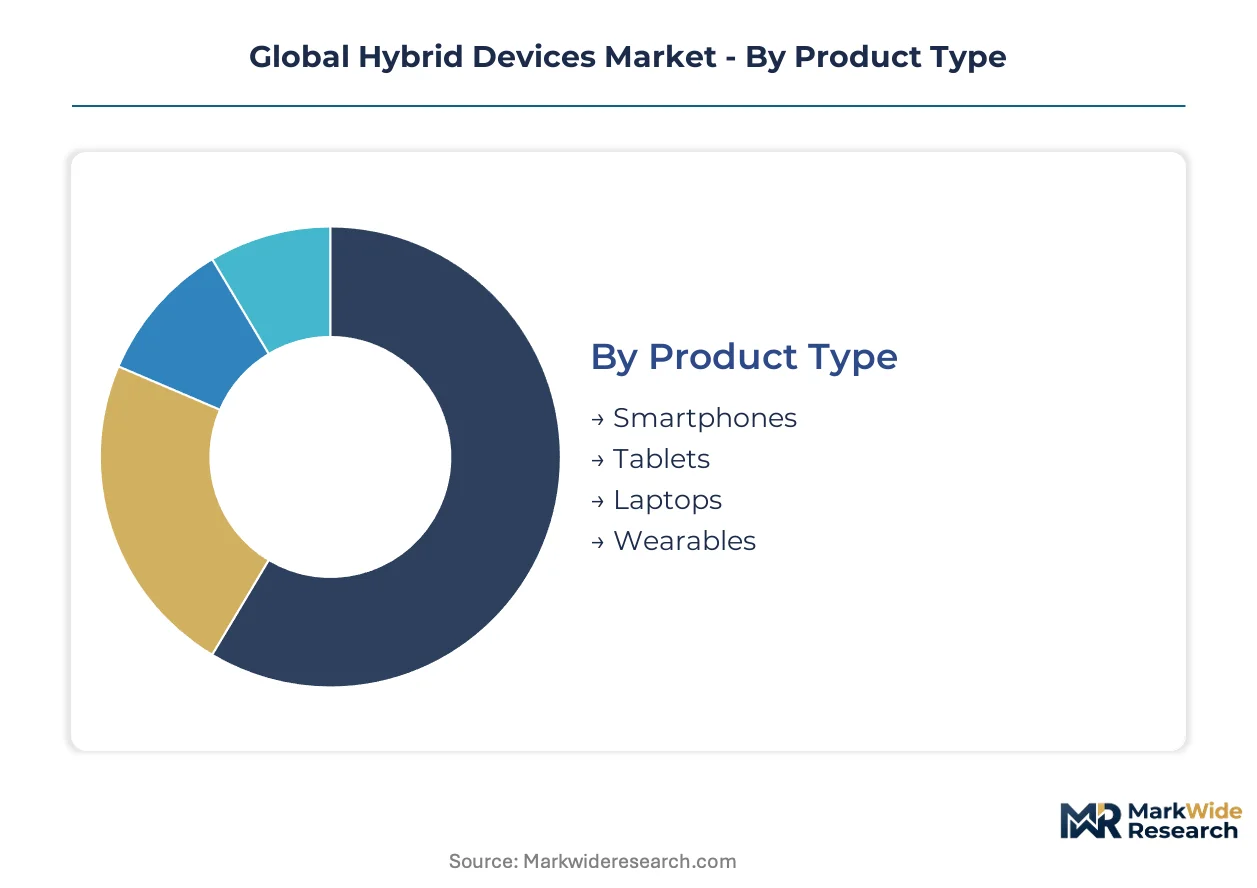
The segmentation analysis for the global hybrid devices market reveals distinct patterns in product evolution, user needs, technological integration, and procurement strategies. Understanding these divisions helps manufacturers align product development and market outreach with specific demand drivers across the competitive landscape.
Product Type:
The product type segmentation highlights how different form factors integrate computing power and portability for diverse user needs.
- Smartphones:These mobile computing devices offer versatile functionality, blending communication, productivity, and entertainment capabilities for a broad consumer base.
- Tablets:Characterized by a touchscreen interface and stylus compatibility, tablets prioritize portability and touch-first interaction. Strong growth is observed in both professional and student segments, enhanced by continuous innovation in high-resolution OLED display technologies.
- Laptops:These devices integrate a full keyboard with a screen that can detach or rotate 360 degrees, offering a complete computing experience. Demand concentrates heavily among Professionals in Germany and the United States, driven by the necessity for robust performance in hybrid work environments.
- Wearables:Encompassing smartwatches and fitness trackers, these devices provide convenient, on-the-go access to notifications and health monitoring, often integrating with other hybrid devices.
Volume placements concentrate in Laptops; the faster expansion belongs to Tablets.
End User:
This end-user segmentation reveals distinct purchasing behaviors and device requirements across various customer types.
- Students:Encompassing K-12 and higher education, this segment seeks durable, cost-effective, and adaptable devices for learning and digital content creation. The opportunity here lies in developing tailored products that balance affordability with necessary computing power.
- Professionals:This segment comprises corporate and individual users requiring high-performance, secure, and versatile devices for demanding work tasks. Enterprise fleet purchases, particularly in mature markets, are driven by hybrid work models and stringent regulatory compliance like GDPR.
- Healthcare Providers:These users require reliable and secure hybrid devices for patient data management, telemedicine, and mobile clinical applications within medical environments.
- Retailers:Retail professionals utilize hybrid devices for inventory management, point-of-sale operations, and customer engagement, often needing robust and portable solutions.
Value generation is highest among Professionals, while Students presents significant growth potential.
Technology:
The technology segmentation categorizes the core innovations applied to enhance hybrid device functionality and user interaction.
- Touchscreen:Fundamental to hybrid devices, touchscreen technology enables intuitive direct interaction with the operating system, supporting both finger and stylus input.
- Biometric:This technology includes integrated fingerprint readers and infrared cameras for facial recognition, providing enhanced device security and user authentication. Corporate adoption is swift, especially in GDPR-compliant regions, to protect sensitive data and streamline access.
- Wireless:Encompassing technologies like Wi-Fi 6E and 5G, wireless connectivity provides seamless, high-speed network access for mobile users. Integration of these next-generation technologies creates a new upgrade cycle for professionals requiring constant, reliable communication.
- IoT:Integration of Internet of Things capabilities allows hybrid devices to connect and interact with a broader ecosystem of smart devices and sensors, expanding their utility.
Differentiation in the premium segment relies heavily on Biometric features, with Wireless becoming a foundational expectation.
Distribution Channel:
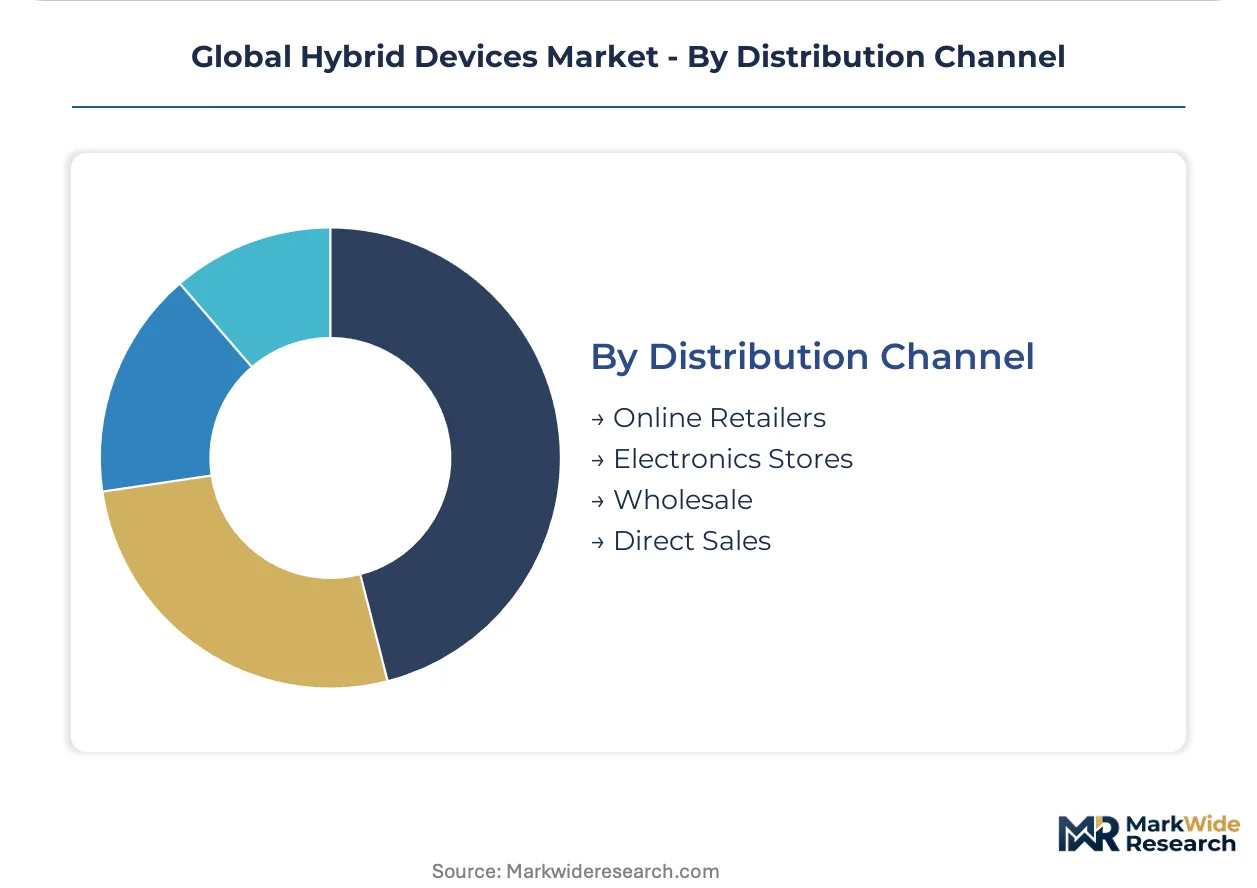
The distribution channel segmentation outlines how supply concentration and customer engagement models influence market reach and sales efficiency.
- Online Retailers:E-commerce platforms provide a wide selection of hybrid devices, competitive pricing, and convenience for consumers globally, driving significant market volume.
- Electronics Stores:Traditional brick-and-mortar retailers offer consumers immediate access to hybrid devices, allowing for hands-on experience and expert advice. This channel caters to individual buyers and small businesses seeking readily available solutions.
- Wholesale:This channel involves bulk sales to resellers, integrators, and smaller businesses, often providing cost efficiencies for larger volume procurements.
- Direct Sales:This channel involves manufacturers selling directly to large enterprise customers, facilitating customized configurations, fleet management, and long-term client relationships. Large corporations in the United States and Germany increasingly favor this procurement model.
Enterprise procurement increasingly favors Direct Sales, whereas individual consumer sales remain strong in Electronics Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Silicon Valley region in the United States drives significant innovation in hybrid device architecture. This technological hub fosters both software optimization and hardware integration for new form factors. Companies in this area develop advanced components for global distribution.
United States
Professionals in major US cities like New York and Chicago demand high-performance hybrid devices for hybrid work models. Enterprise fleet purchases are influenced by data protection mandates under HIPAA compliance. The Seattle tech corridor sees continuous development of operating systems optimized for touch and keyboard input.
Germany
German enterprises require secure and powerful hybrid devices to meet stringent GDPR regulations for data privacy. The demand for versatile computing is strong among professionals across Frankfurt and Munich. Advanced engineering centers in Bavaria focus on integrating biometric security features into premium models.
China
Chinese consumers and businesses increasingly adopt hybrid devices, driven by a preference for versatile mobile computing solutions. All electronic products sold in China must comply with GB standards for safety and quality. Manufacturing hubs in the Pearl River Delta region produce a vast array of hybrid components and finished devices.
South Korea
Seoul-based technology firms propel advancements in display technology, enhancing hybrid device user experience. The country's national electronics regulations influence component sourcing for global manufacturers. Busan's industrial clusters contribute to the supply chain for high-resolution OLED panels used in premium tablets.
Japan
Japanese professionals seek highly reliable hybrid devices for diverse work environments, including advanced mobile connectivity. METI guidelines encourage domestic innovation in consumer electronics and computing. Tokyo's dense urban centers foster demand for compact, feature-rich convertible laptops.
Global Hybrid Devices Market Key Industry Players
Premium-margin players sit above commodity-margin players across product differentiation and brand equity within the hybrid devices market. The market exhibits a tiered structure, with established technology giants dominating the high-end segment. This structure supports archetypes ranging from innovation-driven premium brands to volume-focused mass-market producers. Companies pursue strategic partnerships for component sourcing and portfolio diversification to capture varied customer segments, alongside continuous R&D investment.
On the premium-tier vector, Microsoft Corporation exemplifies a strategy focused on high-resolution touchscreens and advanced software integration for its Surface line. Samsung Electronics, a global conglomerate, leverages its display manufacturing prowess to differentiate its tablet and convertible offerings across diverse markets. Lenovo Group, a multinational technology company, occupies a position across multiple price points with its diverse Yoga series, targeting both professional and student segments globally. These companies anchor different segments of the market, reflecting varied approaches to product development and market penetration.
| Leading Market Players |
|---|
| Dell Technologies Inc. |
| Samsung Electronics |
| Microsoft Corporation |
| HP Development Company |
| Acer Inc. |
| Lenovo Group |
| Hewlett-Packard Development Company |
| Fujitsu Limited |
| ASUSTeK Computer Inc. |
| Others |
Cost & Logistics Intelligence
High-resolution display panels, sourced from specialized manufacturers in East Asia, drive significant cost into premium hybrid devices, directly influencing their downstream pricing tiers for corporate buyers.
Pricing Analysis
Performance and feature set anchor value-based pricing within the global hybrid devices market. The pricing model exhibits premium-mid-economy differentiation across product types. Advanced biometric security features and cutting-edge display technology serve as key price differentiation drivers. Pricing pressure stems from component cost volatility, particularly for high-end processors. The Student segment demonstrates the highest price sensitivity, contrasting with Professionals who prioritize device capability over cost.
Supply Chain Analysis
Processor and memory chip supply relies heavily on manufacturing hubs in China and South Korea. Key raw material dependencies include rare earth elements for displays and specialized semiconductor components. Logistical bottlenecks, particularly for cross-border shipments of sensitive electronics, represent a structural supply chain risk. Distribution runs through a dual model, with direct enterprise channels dominating large fleet purchases and electronics stores serving individual consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global hybrid devices market is in a technology-transition phase, with next-generation wireless connectivity like Wi-Fi 6E actively replacing older standards for mobile professionals.
For Market Incumbents: Anchor market leadership by deepening software optimization for seamless multi-modal input across diverse operating systems. Secure long-term component supply agreements to mitigate future component cost volatility. Invest heavily in R&D for next-generation connectivity and advanced biometric security features, countering threats from emerging specialized device manufacturers.
For New Entrants and Emerging Players: Launch into the underpenetrated educational segment via direct sales to institutions. Develop durable, cost-effective hybrid devices tailored specifically for student needs, balancing affordability with necessary computing power. Focus on specific regional markets like emerging economies where penetration is not yet saturated, offering localized support and services.
For Investors and Strategic Acquirers: Accelerated enterprise refresh cycles in Germany and the United States are the leading indicator for sustained market growth. The market demonstrates long-term viability due to the persistent demand for versatile computing in hybrid work environments. Target vertically integrated component suppliers or specialized software firms with strong IP in security or display optimization. Watch for the widespread integration of advanced AI accelerators as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Software Optimization | Enhances user experience across form factors, crucial for professional adoption. |
| Secure Component Supply Agreements | Mitigates margin pressure and ensures consistent product availability for manufacturers. |
| Expand Direct Enterprise Channels | Builds stronger client relationships and facilitates customized fleet management solutions. |
| Invest in Next-Gen Connectivity R&D | Drives new upgrade cycles for mobile professionals requiring superior network access. |
| Develop Cost-Effective Student Devices | Captures significant growth potential in the underpenetrated educational segment. |
Research Approach
Corporate financial filings, industry association reports, and government technology statistics formed the secondary backbone for initial market sizing. This was triangulated with primary interviews conducted with device manufacturers' product managers, enterprise IT procurement leads, electronics retailers, and education technology specialists. Bottom-up analysis was then validated through top-down market sizing approaches.
Bottom-up analysis, validated by top-down market sizing, guided the quantitative modeling over the projection horizon. The framework segmented the market by product type, end-user segment, technology integration, and regional adoption patterns. Compound annual growth rates were derived from regression analysis of historical data. Hybrid work model prevalence and regulatory compliance mandates served as key forecast inputs.
Component cost volatility, supply chain disruptions, and evolving regulatory frameworks are the dominant revision risks to market forecasts. These forecasts reflect assumptions regarding technological advancements and market adoption rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Digital Video Recorder Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
AV Surge Protectors Market
Electronic Devices & Electrical Systems
Digital Devices Technologies Market
Electronic Devices & Electrical Systems
Electronic Load Market
Electronic Devices & Electrical Systems
High Voltage Amplifiers Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Digital Synthesizers Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Broadcasting Equipment Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Automotive Diode Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market