
 Insurance Brokerage Market | 2026-2036
Insurance Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance Brokerage Market Intelligence
Corporate buyer concentration is hardening as mid-market enterprises consolidate insurance procurement under single brokers rather than fragmented local agents. Marsh McLennan leverages its captive reinsurance capabilities to anchor multinational accounts with complex cross-border risk profiles. Aon plc competes through data-analytics platforms that quantify climate exposure for commercial property portfolios. Arthur J. Gallagher & Co. specializes in niche construction and energy sector placements where technical underwriting expertise commands premium placement fees.
Insurance brokerage denotes the intermediation of risk transfer contracts between policyholders and underwriters, encompassing advisory, placement, claims advocacy, and ongoing policy administration services. Brokers earn commission or fee-based revenue by matching client risk profiles with appropriate carrier capacity across life, health, property, and liability lines. The service type dimension shows property and liability insurance generating the deepest margin pools due to commercial renewal complexity and commission rate durability. Distribution channel structure reveals online platforms capturing the fastest expansion as direct-to-consumer term life and small commercial policies bypass traditional agent networks. End user segmentation indicates corporations commanding the largest account values while government agencies represent an underdeveloped procurement channel with lengthening sales cycles.
State insurance departments in the United States enforce producer licensing and fiduciary duty standards that elevate compliance costs for independent brokerages. The National Association of Insurance Commissioners coordinates model laws affecting broker compensation disclosure and data privacy obligations across jurisdictions. Stakeholders must monitor regulatory divergence between state-level consumer protection frameworks and federal proposals for uniform fiduciary standards applicable to retirement-related insurance recommendations.
Market Dynamics
Digital distribution mandates from state insurance regulators are compressing traditional agent commissions while accelerating platform-based intermediation across commercial and personal lines.
Growth Catalysts
- Small business bundled policy adoption:Mid-market enterprises in the United States, the United Kingdom, and Germany are consolidating fragmented insurance procurement under single broker relationships, driving account value concentration.
- Climate risk quantification technology:Data-analytics platforms that model commercial property exposure to extreme weather events are enabling brokers to command premium advisory fees for complex risk placements.
- Captive reinsurance structuring:Multinational corporations with cross-border operations are demanding integrated risk transfer solutions that combine direct placement with captive reinsurance capacity.
Market Restraints
- Commission compression from direct digital distribution:State-level mandates for online policy comparison and purchase are eroding traditional percentage-based compensation structures for standard commercial lines.
- Regulatory fragmentation across jurisdictions:Divergent fiduciary duty standards between the National Association of Insurance Commissioners model laws and federal retirement-related proposals are elevating compliance architecture costs.
- Technical underwriting capacity scarcity:Niche construction and energy sector placements require specialized expertise that concentrates among limited broker teams, constraining scalable growth in high-margin segments.
Strategic Opportunities
- Government agency procurement channel development:Public sector risk management budgets remain underpenetrated relative to corporate accounts, offering lengthening but high-value contract opportunities.
- Cyber liability policy bundling:Small and mid-sized enterprises are seeking integrated cyber coverage alongside traditional property and liability protection, creating cross-sell potential.
- API-enabled embedded insurance distribution:Partnerships with fintech platforms and commercial service marketplaces are opening direct integration channels that bypass traditional agent recruitment.
Industry Challenges
- Legacy system integration complexity:Established brokerages face friction connecting proprietary placement platforms with carrier policy administration systems and emerging insurtech data standards.
- Producer licensing and continuing education requirements:State insurance departments mandate jurisdiction-specific credentials that create operational drag for multi-state independent brokerages expanding geographically.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance Brokerage Market |
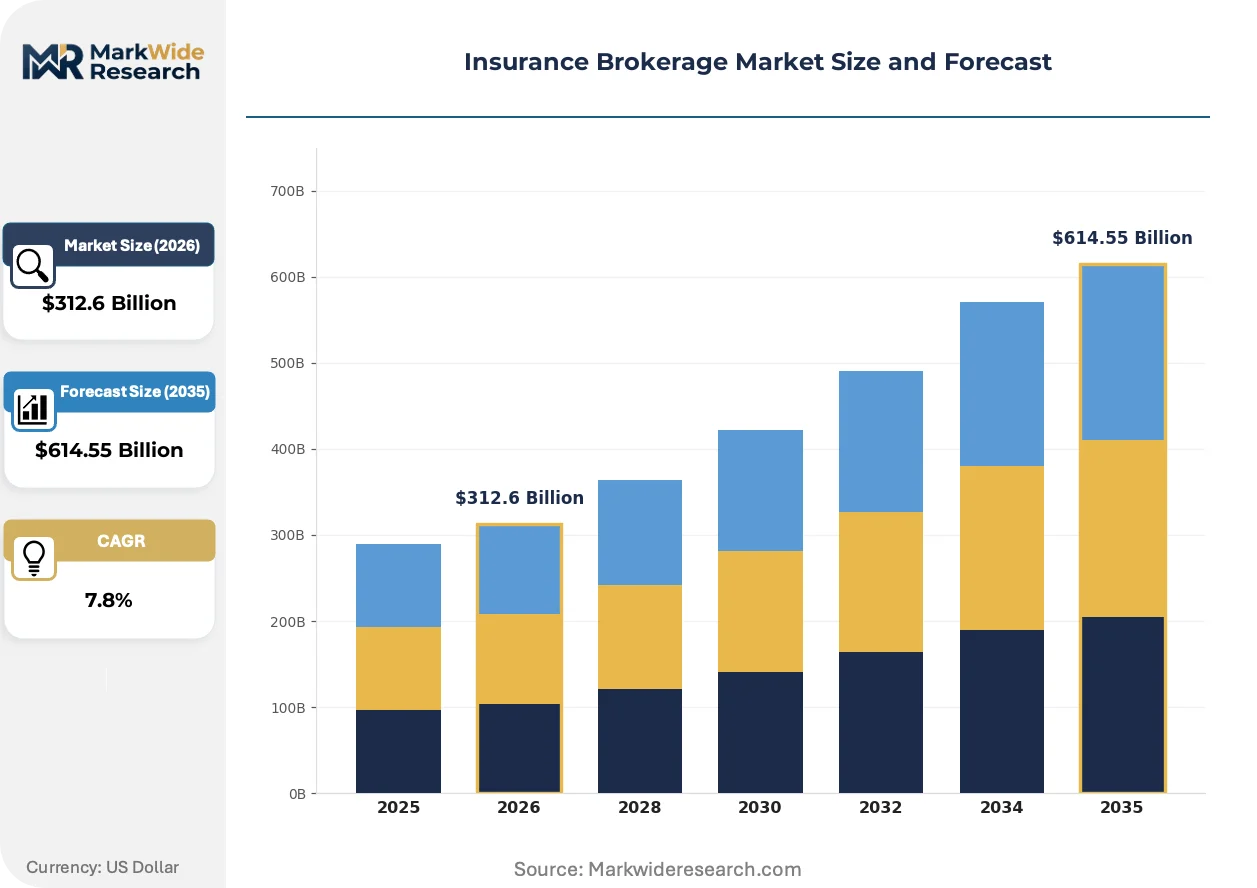
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $614.55 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Life Insurance, Health Insurance, Property Insurance, Liability Insurance Distribution Channel: Brokers, Direct Sales, Online Platforms, Agent Networks End User: Individuals, Small Businesses, Corporations, Government Agencies Policy Type: Mainstream, Niche, Customizable, Multi-Policy |
| Companies Covered | WTW, Hub International Ltd., Marsh McLennan, Acrisure LLC, Brown & Brown Inc., Aon plc, Alliant Insurance Services Inc., Lockton Inc., Arthur J. Gallagher & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance Brokerage Market Strategic Shifts & Innovations
Technology platforms are restructuring how risk transfer contracts are originated, priced, and serviced, compressing traditional intermediation layers while elevating data-driven advisory roles.
Artificial intelligence-powered risk scoring engines are consolidating underwriting decision support functions that previously required manual actuarial review. Mid-market commercial brokers in the United States and Germany are deploying these tools to accelerate quote turnaround from days to hours. The technology is consolidating placement workflows around platforms that embed carrier appetite matching with client risk profiling.
The European Union's Digital Operational Resilience Act is imposing stringent third-party risk management requirements on financial services intermediaries, including insurance brokers handling sensitive client data. Compliance investments are redirecting technology budgets toward cybersecurity infrastructure and vendor due diligence frameworks. Brokers with cross-border European operations are consolidating data governance functions to meet unified supervisory expectations.
Corporate risk managers are unbundling traditional broker relationships to separate advisory, placement, and claims advocacy functions across specialized providers. Large enterprises in the United States are segmenting procurement between strategic risk consultants and transactional placement platforms. This pattern is most visible in Fortune 500 manufacturing and energy verticals where risk complexity justifies multi-vendor structures.
Insurance Brokerage Market Segmentation
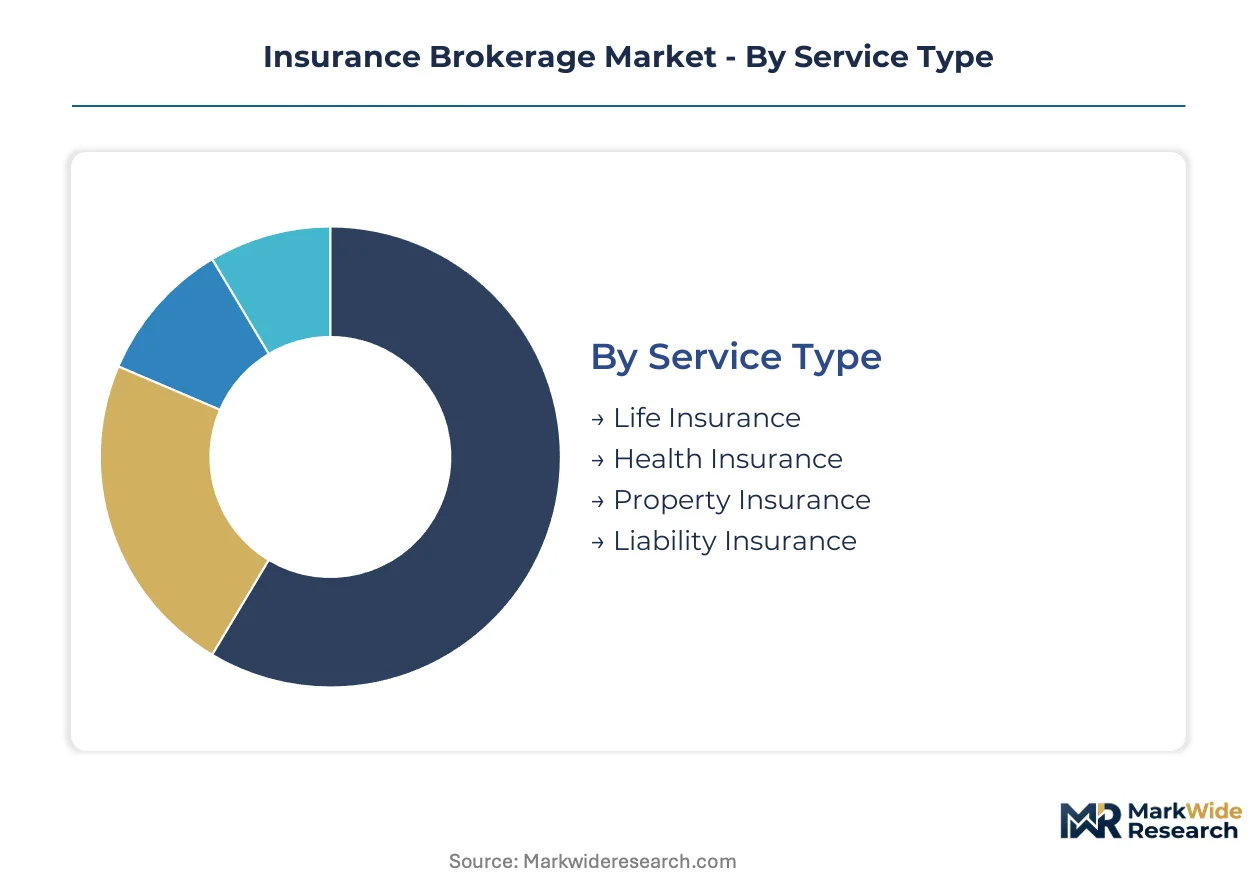
Insurance brokerage segmentation reveals how capital deployment, regulatory exposure, and client complexity vary across service lines and distribution modes. Brokers allocate resources differently across segments based on commission durability, placement friction, and compliance overhead.
Service Type:
Capital intensity peaks in segments requiring specialized underwriting infrastructure and ongoing policy administration systems.
- Life Insurance:Long-duration liabilities demand actuarial reserving systems and mortality table licensing. Demand concentrates among mass-affluent households in Germany and the United States seeking estate planning vehicles, constrained by persistently low interest rate compression on guaranteed products.
- Property Insurance:Catastrophe modeling platforms and reinsurance treaty access require substantial data infrastructure investment. Commercial property placements in coastal United States counties and London market syndicates command premium advisory fees as climate exposure hardens pricing.
- Health Insurance:Employer-sponsored group benefits administration scales through technology platforms rather than human capital.
- Liability Insurance:D&O and professional liability placements rely on legal expertise networks concentrated in New York and London.
Most installed capacity flows through Property Insurance. Expansion is steepest in Liability Insurance as litigation frequency climbs.
Distribution Channel:
Margin profiles diverge sharply based on customer acquisition costs and technology platform amortization schedules.
- Online Platforms:Direct-to-consumer term life and small commercial portals operate on thin spreads but scale through algorithmic underwriting. United Kingdom and German regulators mandate price transparency tools that accelerate platform adoption among digitally native small businesses.
- Brokers:Full-service advisory relationships sustain percentage-based compensation for complex commercial placements. Mid-market enterprises in the United States consolidate procurement under single broker mandates, elevating account values.
- Direct Sales:Captive agent forces require fixed cost absorption through exclusive carrier arrangements.
- Agent Networks:Independent producer access demands multi-state licensing compliance architecture.
Transaction volume concentrates in Online Platforms. Revenue per placement climbs fastest in Broker relationships.
End User:
Risk sophistication and procurement authority determine advisory fee potential across client categories.
- Corporations:Fortune 500 risk managers unbundle advisory, placement, and claims functions across specialized providers. United States manufacturing and energy verticals drive demand for captive reinsurance structuring and cross-border capacity placement.
- Small Businesses:Bundled commercial package policies streamline procurement for owner-operators with limited risk management staff. Adoption accelerates across United Kingdom and German mid-market enterprises consolidating fragmented coverage.
- Individuals:Mass-market term life and personal lines distribute through lowest-cost channels.
- Government Agencies:Public sector procurement cycles extend 18-36 months but yield sticky multi-year contracts.
Commission dollars concentrate in Corporations. New account formation runs strongest in Small Businesses.
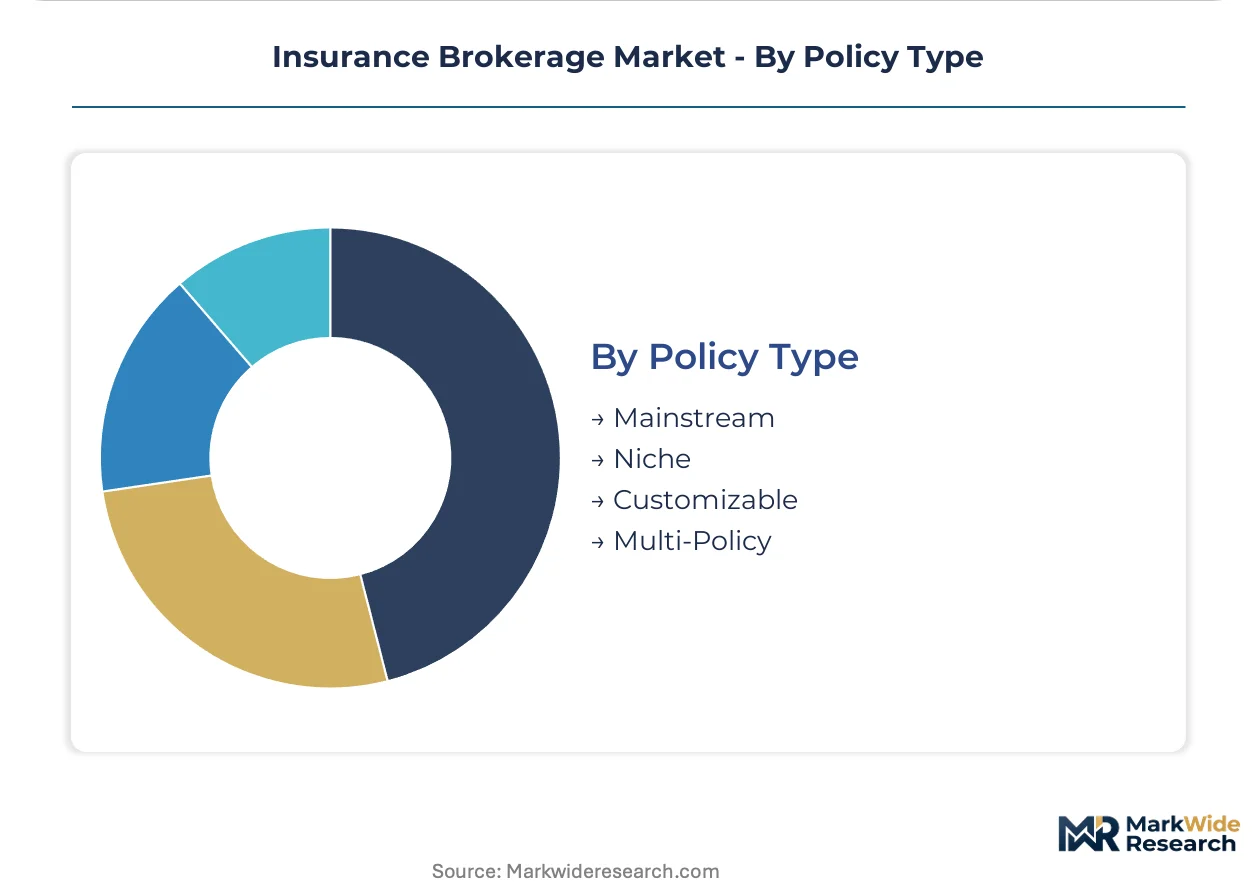
Policy Type:
Underwriting complexity and placement friction separate premium-priced specialty contracts from commoditized mainstream coverage.
- Niche:Construction surety, energy catastrophe, and cyber liability placements require technical expertise that concentrates among limited broker teams. London market and Bermuda capacity access commands placement fees exceeding standard commercial lines multiples.
- Multi-Policy:Integrated property, liability, and cyber coverage bundles reduce procurement friction for mid-market enterprises. United States and German small businesses drive adoption as risk managers seek coverage simplification.
- Mainstream:Standard commercial auto and general liability contracts compete on price through direct channels.
- Customizable:Modular coverage design adds administrative overhead without proportional fee recovery.
Advisory effort concentrates in Niche placements. Policy count expansion leads in Multi-Policy bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger brokerage commission pools than Germany, yet both markets face identical pressure from state-level digital distribution mandates that compress traditional agent compensation structures.
United States
Mid-market enterprises in manufacturing and energy verticals consolidate fragmented insurance procurement under single broker mandates, elevating account values per placement. State insurance departments enforce producer licensing and fiduciary duty standards through the National Association of Insurance Commissioners model laws. Chicago and Houston anchor commercial property and energy sector brokerage clusters where technical underwriting expertise commands premium placement fees.
Germany
Mass-affluent households seek estate planning vehicles through life insurance brokers constrained by persistently low interest rate compression on guaranteed products. BaFin implements stringent conduct-of-business rules affecting broker compensation disclosure and client suitability assessments. Munich and Frankfurt concentrate D&O and professional liability placement expertise alongside captive reinsurance structuring for multinational corporations.
United Kingdom
Small commercial policy portals scale through algorithmic underwriting as regulators mandate price transparency tools accelerating platform adoption among digitally native businesses. The Prudential Regulation Authority and Financial Conduct Authority coordinate solvency and conduct standards for intermediaries. London market syndicates in the City command placement fees exceeding standard commercial lines multiples for construction surety and cyber liability risks.
Canada
Mid-market enterprises adopt bundled commercial package policies streamlining procurement for owner-operators with limited risk management staff. Provincial insurance regulators maintain jurisdiction-specific licensing requirements creating operational drag for multi-state independent brokerages expanding geographically. Toronto anchors the largest concentration of commercial property and liability brokerage capacity serving cross-border United States accounts.
France
Corporate risk managers unbundle traditional broker relationships to separate advisory, placement, and claims advocacy functions across specialized providers. Autorité de Contrôle Prudentiel et de Résolution enforces third-party risk management requirements on financial services intermediaries under EU-wide operational resilience frameworks. Paris concentrates strategic risk consulting capabilities serving Fortune 500 manufacturing verticals with complex cross-border risk profiles.
Insurance Brokerage Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure favors scale-driven players with captive reinsurance capabilities and data-analytics platforms, while fragmentation persists in niche construction and energy placements requiring technical underwriting expertise. Three archetypes dominate: multinational advisory platforms with cross-border capacity, regional bundled-policy specialists serving mid-market enterprises, and boutique technical underwriters commanding premium placement fees. M&A activity concentrates advisory functions under expanding broker networks, while strategic partnerships embed insurance distribution into fintech and commercial service marketplaces.
Within the multinational advisory tier, Marsh McLennan and Aon plc exemplify scale-driven platforms leveraging data-analytics capabilities to quantify climate exposure and structure integrated risk transfer solutions. Arthur J. Gallagher & Co. occupies a specialized position representing the boutique technical underwriting archetype where niche sector expertise commands premium fees.
| Leading Market Players |
|---|
| WTW |
| Hub International Ltd. |
| Marsh McLennan |
| Acrisure LLC |
| Brown & Brown Inc. |
| Aon plc |
| Alliant Insurance Services Inc. |
| Lockton Inc. |
| Arthur J. Gallagher & Co. |
| Others |
Cost & Logistics Intelligence
Actuarial talent concentration in London and New York drives labor-cost differentials that widen pricing spreads between premium advisory tiers and commoditized placement services. Technical underwriting expertise commands compensation multiples that standard commercial lines cannot absorb, forcing tiered service architectures.
Pricing Analysis
Capacity additions in Germany and the United Kingdom are reshaping price floors for algorithmic small commercial platforms. The dominant pricing structure runs on percentage-based commissions for complex placements alongside flat-fee advisory for risk consulting engagements. Price differentiation hinges on technical specialization depth and captive reinsurance structuring capability. Pricing pressure stems from state-level digital distribution mandates compressing standard line commissions. Small businesses exhibit highest price sensitivity while Fortune 500 risk managers prioritize expertise over cost.
Supply Chain Analysis
Regional distribution centers in Chicago, London, and Frankfurt anchor hub-and-spoke placement networks connecting carrier capacity to client risk profiles. The supply chain draws from proprietary data platforms, licensed producer networks, and reinsurance treaty relationships. Raw material dependencies center on actuarial talent pools, catastrophe modeling licenses, and regulatory compliance infrastructure. Single-source vulnerability concentrates in niche construction and energy underwriting teams with irreplaceable technical expertise. Distribution runs through multi-layered structures: direct platform access for standardized coverage, broker intermediation for mid-market complexity, and specialized advisory for multinational accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insurance brokerage operates as a geographic-arbitrage play where regulatory divergence between United States state-level fiduciary standards and European Union operational resilience frameworks creates compliance cost differentials favoring scale platforms.
For Market Incumbents: Cement captive reinsurance capabilities and data-analytics platforms as defensive moats against insurtech disintermediation. Invest in climate risk quantification technology to preserve premium advisory fees. Expand producer licensing compliance architecture across multi-state footprints to neutralize regulatory fragmentation drag. For New Entrants and Emerging Players: Begin with cyber liability policy bundling for United States mid-market enterprises where incumbent coverage gaps persist. Target government agency procurement channels where sales cycle length deters established competitors. Pursue API-enabled embedded distribution partnerships with fintech platforms to bypass traditional agent recruitment costs. For Investors and Strategic Acquirers: Diversified financial services conglomerates are the most active acquirer in this space, consolidating advisory functions under expanding broker networks. Long-term viability favors platforms combining scale-driven data capabilities with niche technical underwriting expertise. Watch for inflection signals in state-level digital distribution mandate adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Reinsurance Structuring | Marsh McLennan leverages captive capabilities to anchor multinational accounts with cross-border risk profiles. |
| Climate Risk Analytics Platform | Aon plc deploys data-analytics tools to quantify commercial property exposure and command premium advisory fees. |
| Niche Sector Specialization | Arthur J. Gallagher & Co. concentrates construction and energy expertise where technical underwriting commands placement multiples. |
| API-Enabled Embedded Distribution | Partnerships with fintech platforms open direct integration channels bypassing traditional agent networks. |
| Government Procurement Channel Development | Public sector risk management budgets offer high-value contract opportunities despite lengthening sales cycles. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged insurance brokerage executives, carrier underwriting officers, corporate risk managers, state insurance regulators, and insurtech platform engineers. Secondary validation drew from National Association of Insurance Commissioners model law databases, state insurance department filings, Securities and Exchange Commission broker disclosure documents, and European insurance supervisory authority reports. Bottom-up account value estimates triangulated against top-down commission pool assessments.
Comparable historical periods anchored the forecast window against baseline market structures. The analytical framework modeled segmentation across service type, distribution channel, end user category, and policy complexity tier. CAGRs derived from trajectory analysis of account value concentration and digital platform penetration rates. Industry-specific forecast inputs incorporated state-level regulatory mandate adoption curves and corporate risk management budget expansion patterns.
Several conditions sit outside the modeled scope, including macroeconomic recession impacts on commercial insurance demand and federal fiduciary standard preemption of state insurance regulations. Forecasts reflect documented assumptions about regulatory divergence persistence and technology platform adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Saudi Arabia Travel Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Green Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Earthquake Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Takaful Insurance Market
Insurance
Aviation Insurance Market
Insurance
India Health Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Agriculture Insurance Market
Insurance
Travel Insurance Market
Insurance
UAE Property and Casualty Insurance Market