
 Green Insurance Market | 2026-2036
Green Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Green Insurance Market Insights
Europe is fragmenting as national regulators impose divergent climate stress-test requirements on carriers. Munich Re dominates catastrophe modeling for offshore wind portfolios across the North Sea. AXA differentiates through parametric coverage for flood-prone commercial assets in France and Belgium. Zurich Insurance Group extends its agricultural climate-risk franchise into Latin American markets.
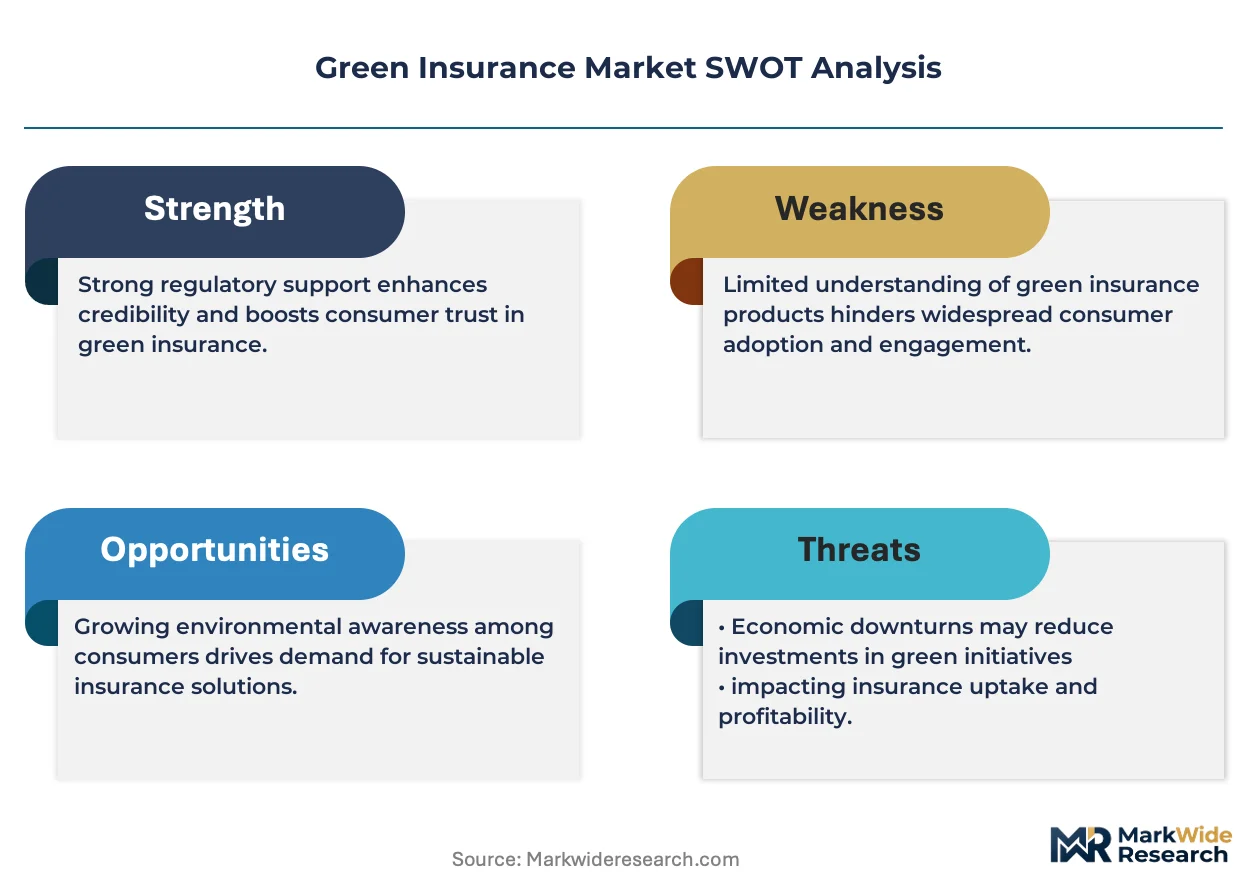
Green insurance encompasses policies that embed environmental criteria into underwriting, pricing, and claims settlement, typically requiring ISO 14001 certification or carbon footprint verification as a condition of preferential rates. Its primary commercial purpose is to align risk transfer with transition finance, enabling capital flows into low-carbon assets while protecting lenders against physical and regulatory climate losses. Renewable energy insurance leads product-type margins due to long-duration project finance structures and complex supply-chain exposures. Eco auto coverage registers the fastest application growth as fleet electrification accelerates and OEMs bundle insurance at point of sale. Brokers control the dominant distribution channel for commercial lines, though online platforms gain share in standardized personal products.
The EU Green Deal and CSRD compel carriers to disclose portfolio climate alignment, reshaping product eligibility and capital allocation across European markets. EIOPA stress-testing guidelines and national implementations of the EU AI Act govern algorithmic underwriting in climate-risk scoring, constraining model deployment speed. The US SEC climate disclosure rules and state-level mandates from California's insurance regulator create parallel compliance architectures. Stakeholders must monitor whether physical-risk model convergence or regulatory fragmentation determines competitive advantage in climate-linked coverage.
Market Dynamics
Project finance requirements for renewable energy assets are tightening coverage terms and accelerating parametric product adoption across commercial portfolios. Capital providers now mandate climate-aligned insurance as a condition of debt covenants, compressing traditional indemnity structures.
Growth Catalysts
- EU Green Deal disclosure mandates:Carriers must report portfolio climate alignment, forcing product redesign to capture transition finance flows into low-carbon assets.
- Offshore wind expansion:North Sea project pipelines require specialized catastrophe coverage for complex supply-chain and construction-phase exposures.
- Fleet electrification acceleration:OEMs bundle eco auto coverage at point of sale, embedding insurance into vehicle procurement decisions.
Market Restraints
- Physical risk model divergence:Munich Re's proprietary North Sea wind models differ from AXA's flood algorithms, creating pricing opacity for multi-jurisdiction portfolios.
- Capital charge volatility:EIOPA stress-test variations across Germany, France, and Belgium fragment reserving requirements and slow product rollout.
- Carbon verification bottlenecks:ISO 14001 certification delays limit preferential rate eligibility for mid-market commercial policyholders.
Strategic Opportunities
- Latin American agricultural expansion:Zurich Insurance Group's climate-risk franchise can replicate French parametric structures for drought-exposed Brazilian soy operations.
- CSRD-aligned coverage bundling:European corporates facing disclosure mandates seek integrated policies linking property, liability, and transition risk in single contracts.
- Online platform disintermediation:Standardized personal green products bypass broker networks, capturing price-sensitive household segments in Germany and China.
Industry Challenges
- Climate actuarial talent scarcity:Shortages in catastrophe modelers with renewable energy specialization constrain underwriting capacity expansion.
- Legacy system integration friction:Algorithmic climate-risk scoring requires API connectivity with decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Insurance Market |
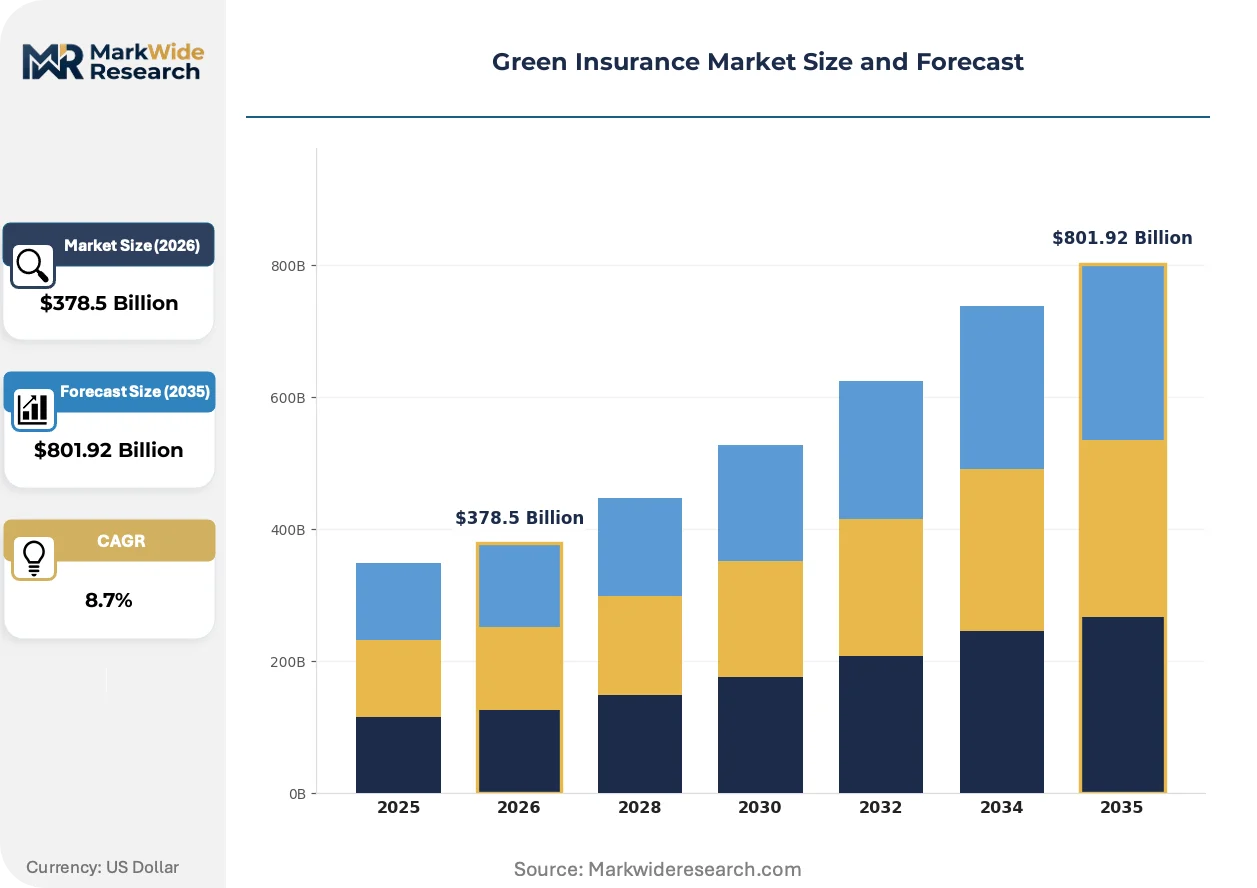
| Market Size in 2026 | $378.5 Billion |
| Market Size in 2035 | $801.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Home Insurance, Eco Auto Coverage, Renewable Energy Insurance, Sustainable Property Insurance Application: Natural Disaster Protection, Climate Change Mitigation, Energy Efficiency Incentives, Carbon Offset Programs End User: Property Owners, Renewable Energy Firms, Environmental NGOs, Sustainable Developers Distribution Channel: Direct Sales, Brokers, Online Platforms, Bancassurance |
| Companies Covered | Zurich Insurance Group, Ping An Insurance, Allianz, Arch Capital Group, Liberty Mutual, AXA, Chubb Limited, Munich Re, AIG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Insurance Market Trends and Innovations
Parametric triggers are displacing traditional loss-adjustment protocols across climate-exposed commercial lines. This shift compresses claims settlement cycles and transfers basis risk to policyholders in exchange for liquidity speed.
Blockchain-enabled smart contracts are hybridizing with satellite-based index triggers for agricultural and flood coverage. French and Belgian commercial buyers are piloting these instruments for 2025 renewals. The technology is hybridizing claims processing from months to days, eliminating adjuster deployment costs.
EIOPA's algorithmic underwriting guidelines under the EU AI Act impose explainability requirements on climate-risk scoring models. Carriers must document feature importance for premium differentiation decisions. German and French personal lines are most affected, with several carriers pausing automated quoting pending compliance verification.
Corporate risk managers now bundle green insurance procurement with ESG-linked credit facilities. This pattern concentrates buying power among sustainability-linked loan borrowers in the United States and China. Banks increasingly require coverage placement as a drawdown condition, elevating insurance from cost center to capital access enabler.
Green Insurance Market Segmentation
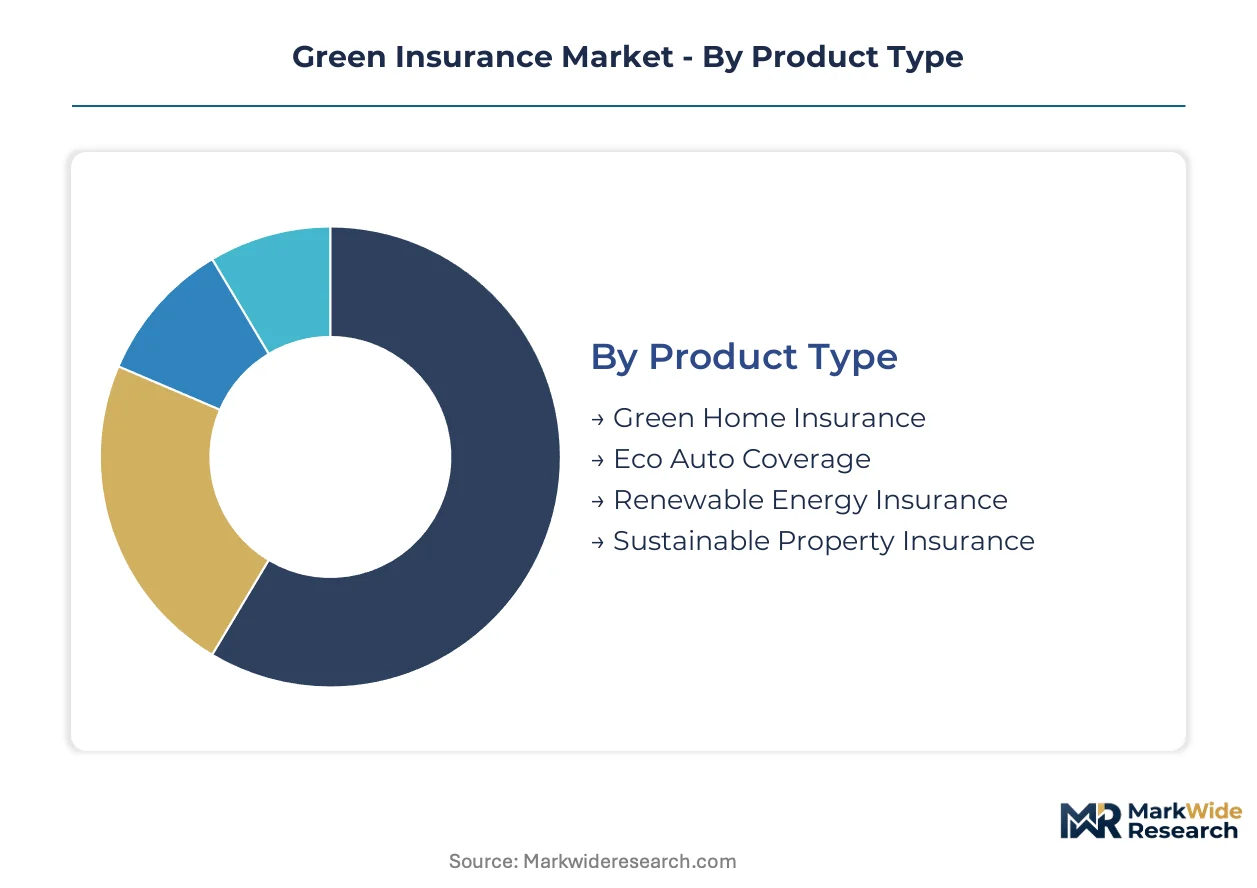
Green insurance segmentation reveals how environmental criteria reshape underwriting architecture across product lines. Distinct risk profiles, regulatory triggers, and buyer procurement patterns create heterogeneous margin structures that carriers must navigate.
Product Type:
After-sales service intensity varies sharply across green insurance products, with renewable energy portfolios demanding continuous catastrophe model recalibration and construction-phase monitoring that home or auto lines rarely require.
- Green Home Insurance:Policies tie premium discounts to ISO 14001 certification or energy efficiency ratings, with claims settlement incorporating carbon footprint verification for rebuilding materials. Demand concentrates in Germany and California where building codes mandate disclosure.
- Renewable Energy Insurance:Specialized coverage addresses long-duration project finance structures, offshore wind construction phases, and complex supply-chain exposures across North Sea portfolios. Capital providers now mandate this coverage as a debt covenant condition.
- Eco Auto Coverage:OEM bundling at point of sale accelerates penetration as fleet electrification advances.
- Sustainable Property Insurance:Commercial assets in flood-prone French and Belgian markets drive parametric product adoption.
By volume, sustainable property insurance leads. By growth pace, eco auto coverage is expanding most quickly.
Application:
Cost tier differentiation separates applications by claims settlement complexity and data infrastructure requirements, with natural disaster protection commanding premium pricing against standardized carbon offset offerings.
- Natural Disaster Protection:Parametric triggers displace traditional loss-adjustment protocols, compressing settlement cycles from months to days. Satellite-based index triggers now dominate French and Belgian commercial renewals.
- Climate Change Mitigation:Coverage aligns with transition finance flows, protecting lenders against physical and regulatory climate losses in renewable energy project finance.
- Energy Efficiency Incentives:Preferential rates require verified carbon footprint reduction, creating bottlenecks for mid-market commercial policyholders.
- Carbon Offset Programs:Blockchain-enabled smart contracts automate verification, reducing adjuster deployment costs.
Mitigation applications capture the deepest premium pools. Offset programs are gaining share fastest among corporate ESG-linked credit facilities.
End User:
Customer type determines procurement channel and policy bundling complexity, with renewable energy firms negotiating integrated coverage through broker networks while property owners migrate toward online platforms.
- Renewable Energy Firms:Project finance requirements tighten coverage terms, accelerating parametric adoption and compressing traditional indemnity structures. North Sea offshore wind pipelines require specialized catastrophe modeling.
- Property Owners:Price-sensitive households in Germany and China shift toward online platform distribution for standardized personal products.
- Environmental NGOs:Specialized liability coverage addresses advocacy-related litigation risks.
- Sustainable Developers:CSRD-aligned disclosure mandates drive integrated policy procurement linking property, liability, and transition risk.
Renewable energy firms generate the highest premium per account. Sustainable developers are climbing the fastest as CSRD implementation accelerates.
Distribution Channel:
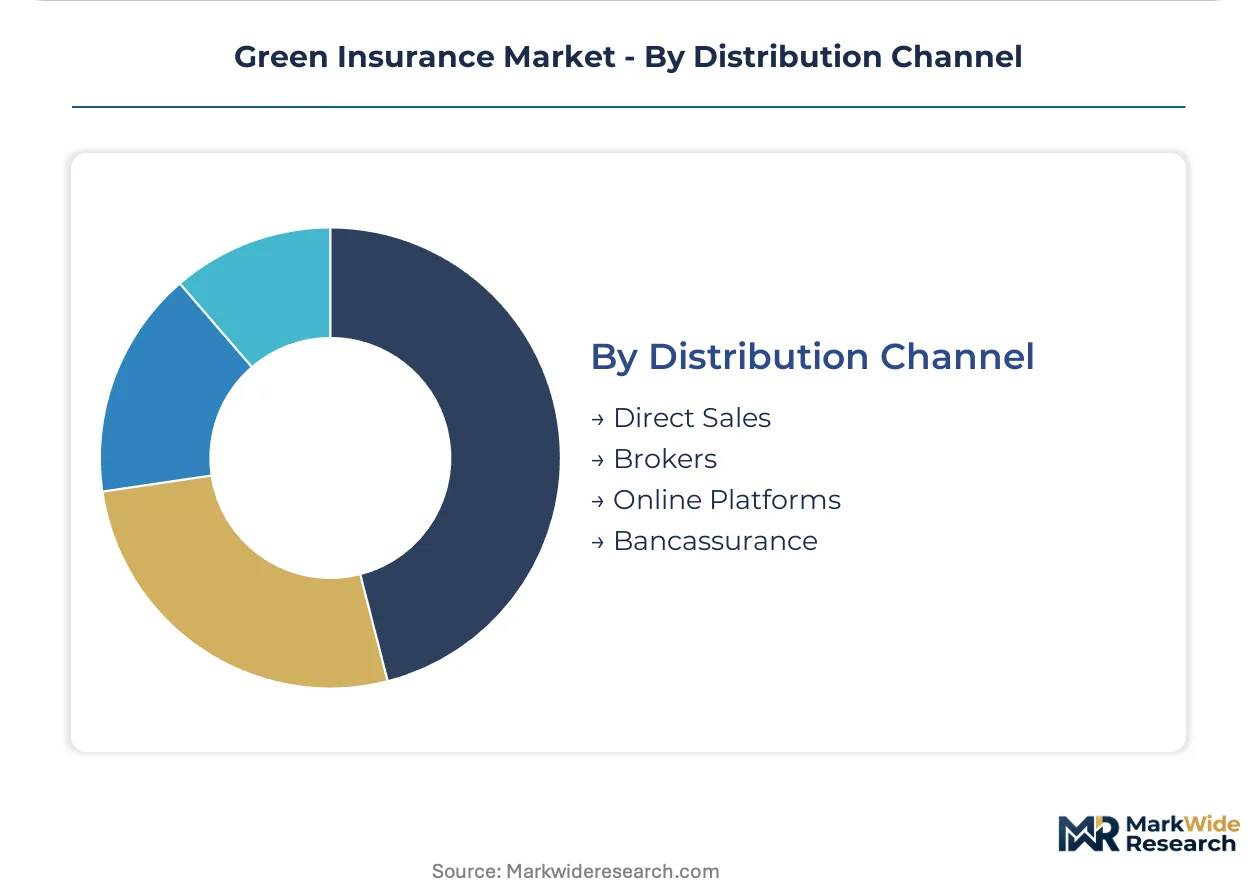
Margin concentration favors broker-controlled commercial lines against disintermediated personal products, with online platforms capturing standardizable risk segments at lower acquisition cost.
- Brokers:Dominate commercial lines through relationship-based placement of complex renewable energy and sustainable property coverage. ESG-linked credit facilities concentrate buying power among sustainability-linked loan borrowers.
- Online Platforms:Gain share in standardized personal green products across Germany and China, bypassing traditional networks.
- Direct Sales:Carrier-owned channels target large renewable energy firms with bespoke coverage structures.
- Bancassurance:Banks increasingly require coverage placement as a drawdown condition, elevating insurance from cost center to capital access enabler.
Brokers lead by premium volume. Online platforms show the steepest expansion trajectory as personal product standardization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier capital concentrates in jurisdictions with stringent climate disclosure regimes. The United States, Germany, and China host the dominant underwriting capacity for green insurance products.
United States
California's insurance regulator mandates climate risk disclosure for carriers operating in wildfire-exposed zones. The SEC climate disclosure rules create parallel compliance architectures for nationally active underwriters. New York and Texas host the largest broker networks placing renewable energy coverage for utility-scale solar and wind portfolios.
Germany
EIOPA stress-testing guidelines and the national implementation of the EU AI Act govern algorithmic underwriting for climate-risk scoring. Munich Re anchors catastrophe modeling capacity for offshore wind portfolios across the North Sea. Frankfurt and Munich cluster the highest concentration of climate actuarial talent in continental Europe.
France
AXA differentiates through parametric coverage for flood-prone commercial assets in Paris and Lille metropolitan areas. The EU Green Deal and CSRD compel carriers to disclose portfolio climate alignment, reshaping product eligibility. Lyon and Marseille drive demand for agricultural climate-risk products as drought exposure intensifies.
China
Ping An Insurance scales eco auto coverage through OEM bundling partnerships as fleet electrification accelerates. National dual carbon goals embed insurance requirements into renewable energy project finance structures. Shanghai and Shenzhen concentrate the largest broker-controlled placements for sustainable property coverage.
United Kingdom
Lloyd's of London syndicates specialize in construction-phase coverage for offshore wind projects in the North Sea. The UK's implementation of CSRD-aligned disclosure rules affects London-based carriers with European exposures. The City of London remains the dominant placement hub for complex renewable energy and sustainable property risks.
Green Insurance Market Competitive Landscape
Global reinsurers and diversified national carriers split the market between specialized catastrophe modeling and broad personal lines distribution. The structure consolidates around scale advantages in data acquisition and regulatory compliance capacity. Three archetypes dominate: reinsurance specialists with proprietary climate models, diversified carriers with bancassurance distribution networks, and broker-dependent commercial lines underwriters. Competitive moves concentrate on parametric product development and geographic expansion into climate-exposed emerging markets.
Among European reinsurance specialists, Munich Re and Zurich Insurance Group exemplify the catastrophe-modeling archetype, anchoring technical capacity for complex renewable energy risks. AXA represents the diversified carrier model with integrated bancassurance and direct distribution channels across continental markets. These three entities occupy positions that define the competitive frontier for climate-linked coverage design and capital deployment.
| Leading Market Players |
|---|
| Zurich Insurance Group |
| Ping An Insurance |
| Allianz |
| Arch Capital Group |
| Liberty Mutual |
| AXA |
| Chubb Limited |
| Munich Re |
| AIG |
| Others |
Pricing and Supply Chain Analysis
Munich and Frankfurt anchor the highest concentration of climate actuarial talent and catastrophe modeling capacity in continental Europe, concentrating underwriting expertise that translates directly into pricing power for complex renewable energy portfolios. This geographic clustering of technical capability creates tiered premium structures where carriers with proprietary North Sea wind models command substantial rate advantages over competitors reliant on third-party data.
Pricing Analysis
EIOPA stress-testing guidelines dictate the pricing tier structure across German and French commercial lines, forcing carriers to embed capital charge volatility into premium calculations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified risks from verified carbon footprint reductions and uncertified baseline coverage. Cost compression in mid-market commercial tiers is intensifying because carbon verification bottlenecks delay preferential rate eligibility. Renewable energy firms show the least price sensitivity given debt covenant mandates, while price-sensitive households in Germany and China drive online platform migration for standardized personal products.
Supply Chain Analysis
Specialized catastrophe modelers and climate-risk data providers hold concentrated capacity across Germany, the United Kingdom, and the United States. Proprietary flood algorithms from AXA and Munich Re's North Sea wind models feed from meteorological data streams, satellite imagery providers, and construction-phase monitoring systems. Single-source vulnerability runs through dominant broker networks controlling complex commercial placements. Distribution runs through relationship-based broker channels for renewable energy coverage, while online platforms disintermediate standardized personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green insurance sits in early-cycle expansion as fleet electrification and CSRD-aligned disclosure mandates embed coverage into capital access decisions. OEM bundling at point of sale and ESG-linked credit facility requirements are accelerating penetration beyond traditional procurement patterns.
For Market Incumbents: Pre-empt parametric product commoditization by investing in proprietary satellite-based index triggers and blockchain-enabled smart contract infrastructure. AXA's flood algorithms and Munich Re's wind models demonstrate how technical differentiation defends margin position against algorithmic underwriting standardization. Backward integration into climate data acquisition—direct meteorological sensor networks and construction-phase IoT monitoring—creates sustainable pricing power. For New Entrants and Emerging Players: Pursue Latin American agricultural climate-risk expansion where Zurich Insurance Group's franchise replication remains incomplete. Brazilian soy operations and drought-exposed Argentine grain belts offer the most penetrable white space for parametric structures proven in French markets. A bancassurance partnership model with agricultural lenders provides the cleanest go-to-market angle, embedding coverage as a drawdown condition similar to European sustainability-linked loan structures. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because climate disclosure mandates are hardening into capital access gatekeepers across the EU, US, and China. Acquisition targets should concentrate on mid-tier carriers with established broker relationships in renewable energy project finance but underinvested parametric product capabilities. Watch EIOPA stress-test harmonization progress as the inflection signal—convergence would compress capital charge volatility and accelerate product rollout velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Blockchain-smart contract hybridization with satellite triggers compresses settlement cycles for French and Belgian commercial renewals. |
| Climate Actuarial Talent Acquisition | Munich and Frankfurt clusters face shortages in catastrophe modelers with renewable energy specialization. |
| Bancassurance Network Expansion | Banks increasingly mandate coverage placement as drawdown condition for ESG-linked credit facilities. |
| Online Platform Disintermediation | Standardized personal green products bypass broker networks in price-sensitive German and Chinese household segments. |
| CSRD-Aligned Coverage Bundling | European corporates seek integrated policies linking property, liability, and transition risk in single contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association disclosures, and project finance documentation. Underwriting executives at major reinsurers, broker network heads placing renewable energy coverage, climate actuarial specialists, and ESG-linked credit facility originators provided structured input. EIOPA guidelines, SEC climate disclosure rules, EU Green Deal implementation documents, and national insurance regulator mandates supplied secondary validation. Bottom-up policy count estimates and top-down premium pool calculations were cross-referenced for triangulation.
Forecast inputs include algorithmic underwriting adoption curves, parametric product penetration rates by geography, and fleet electrification timelines affecting eco auto bundling. Segmentation dimensions span product type, application, end user, and distribution channel, with regulatory framework clusters modeled separately across German, French, US, and Chinese jurisdictions. CAGRs were derived from policy volume trajectories and average premium per account trends. Offshore wind construction phase exposure and carbon verification bottleneck resolution timelines served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting project finance structures or commodity price volatility impacting renewable energy buildout would shift the trajectory. Forecasts reflect assumptions around regulatory implementation timelines and physical risk model convergence. Quarterly review of EIOPA stress-test harmonization progress, CSRD disclosure mandate enforcement intensity, and parametric product loss experience is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
India Liability Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
Credit Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
Jewelry Insurance Market
Insurance
Germany Car Insurance Market
Insurance
India Travel Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Group Health Insurance Market
Insurance
Djibouti Insurance Market
Insurance
Europe Car Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
Europe Extended Warranty Market