
 United States Insurance Brokerage Market | 2026-2036
United States Insurance Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
United States Insurance Brokerage Market Insights
The Series 6 and Series 7 FINRA qualification cycle is bifurcating the United States insurance brokerage landscape between licensed securities brokers and pure property-casualty intermediaries. Marsh & McLennan Companies leverages its captive reinsurance brokerage capabilities to sustain premium flow through Bermuda and London market interfaces. Aon anchors its competitive posture through data-analytics platforms that quantify enterprise risk for Fortune 500 placement teams.
United States insurance brokerage denotes the intermediated distribution of risk transfer contracts, wherein licensed brokers solicit, negotiate, and bind coverage on behalf of policyholders without assuming underwriting risk, typically earning commission rates scaled to premium volume and policy complexity. The commercial lines segment dominates broker revenue pools due to the contractual sophistication and renewal stickiness inherent in multi-line corporate programs, while specialty lines—encompassing cyber, directors and officers, and environmental impairment—attract placement fees at premium multiples to standard commercial business. Health insurance brokerage through employer-sponsored group benefits sustains recurring commission structures distinct from the transactional nature of personal lines auto and homeowners placement.
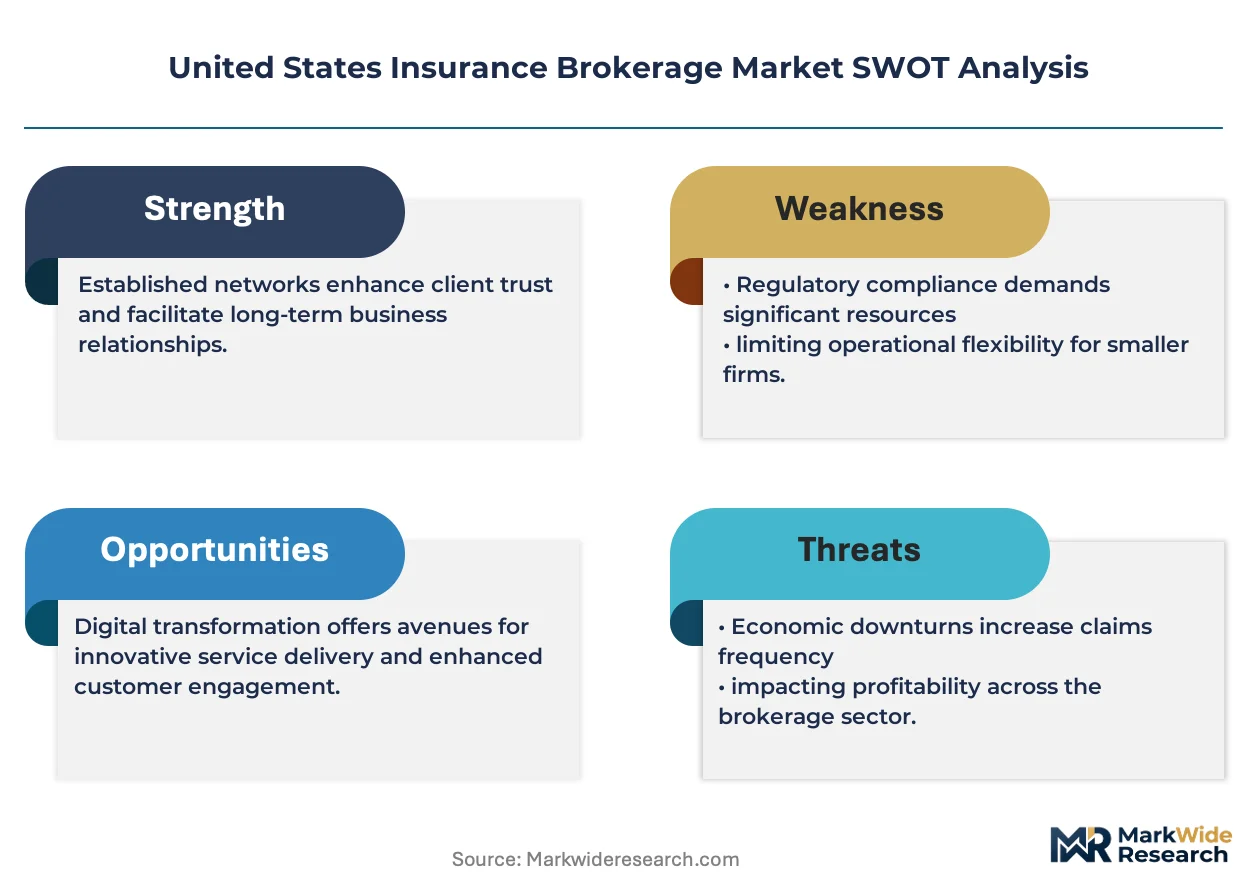
State insurance commissioners in New York, California, and Texas enforce divergent surplus lines eligibility standards that fragment broker licensing requirements and E&S market access protocols across jurisdictions. The National Association of Registered Investment Advisers and FINRA maintain overlapping oversight of broker-dealer hybrids that package investment advisory with insurance placement, creating compliance cost differentials between dually registered and pure brokerage operations. Stakeholders must monitor state legislative momentum toward non-admitted market modernization and the evolving fiduciary standard debate as these forces recalibrate capital requirements and competitive positioning across the intermediary tier.
Market Dynamics
State surplus lines reforms in Texas, Florida, and California are fragmenting broker licensing requirements while accelerating E&S market access for mid-market manufacturers facing elevated product liability exposures. This regulatory divergence is compressing traditional admitted carrier dominance and reshaping intermediary competitive positioning.
Growth Catalysts
- Commercial Cyber Coverage Gaps:Traditional admitted carriers maintain limited appetite for enterprise cyber risk, pushing Fortune 500 risk managers toward specialty brokers with Bermuda and London market interfaces.
- Texas Senate Bill 1075:Streamlined surplus lines eligibility standards reduce broker compliance burdens and expand non-admitted capacity for environmental impairment policies in the Permian Basin.
- Mid-Market Manufacturing Consolidation:Merged entities require multi-line corporate programs with contractual sophistication that only full-service independent brokers can structure and bind.
Market Restraints
- FINRA Qualification Costs:The bifurcated Series 6 and Series 7 examination cycle imposes compliance cost differentials that disadvantage dually registered broker-dealer hybrids against pure property-casualty operations.
- California Surplus Lines Tax Arbitrage:Divergent state tax treatment of non-admitted premiums creates pricing friction that steers placement volume toward lower-tax jurisdictions.
- Legacy Agency Management Systems:Proprietary technology stacks at incumbent regional brokers resist API integration with modern data-analytics platforms, constraining real-time risk quantification capabilities.
Strategic Opportunities
- Environmental Liability White Space:EPA enforcement acceleration under the Comprehensive Environmental Response, Compensation, and Liability Act creates demand for pollution legal liability coverage that admitted markets rarely underwrite.
- Embedded Insurance APIs:Commercial auto fleets and construction equipment lessors are integrating usage-based coverage at point-of-sale, bypassing traditional annual renewal cycles.
- Florida Hurricane Catastrophe Bonds:Post-Ian reconstruction capital requirements are opening placement channels for insurance-linked securities that bypass traditional reinsurance intermediation.
Industry Challenges
- Actuarial Talent Scarcity:Specialty cyber and climate risk modeling demands quantitative skill sets that traditional broker compensation structures fail to attract from competing fintech and consulting sectors.
- Carrier-Broker Data Asymmetry:Real-time IoT telemetry from insured manufacturing assets threatens to disintermediate risk assessment value that brokers traditionally provide to underwriters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Insurance Brokerage Market |
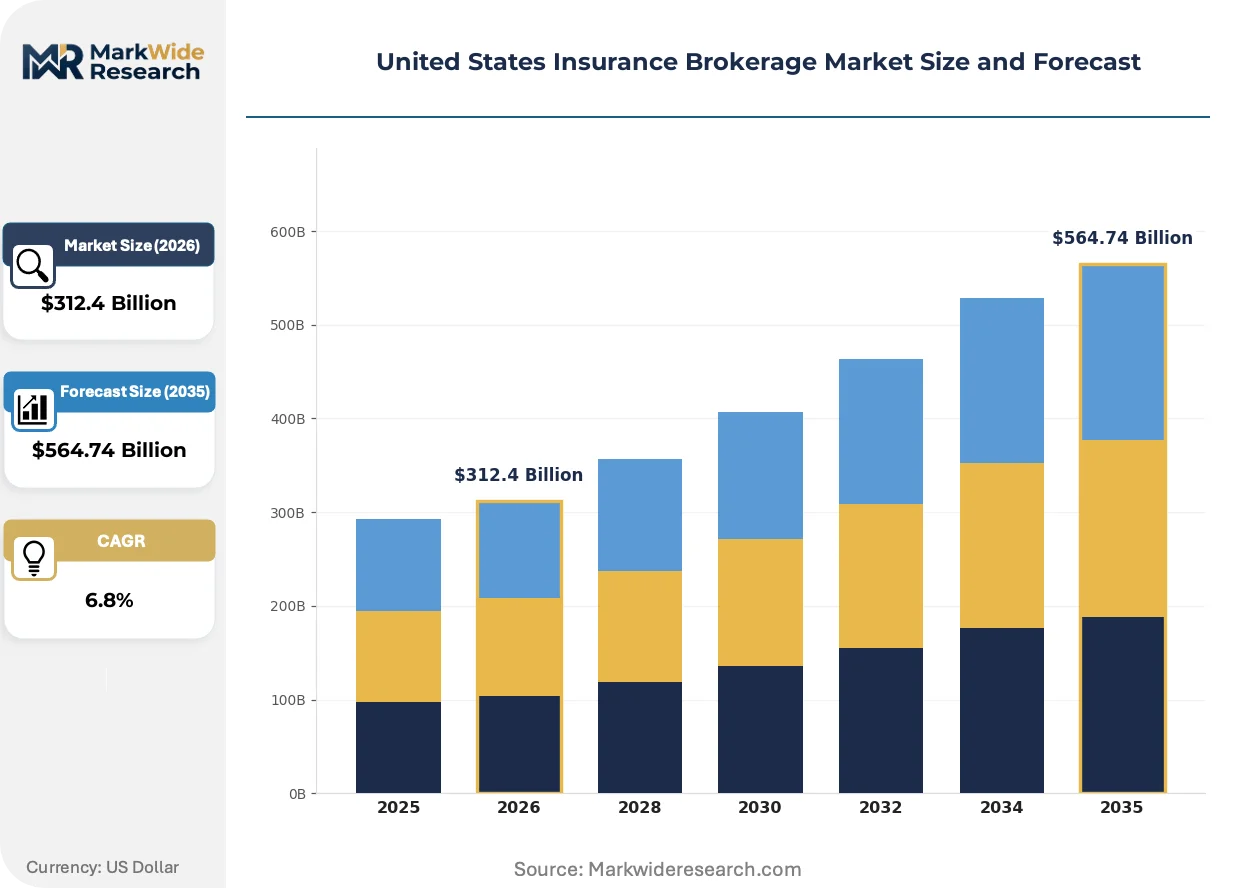
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Life Insurance, Property Insurance, Casualty Insurance, Health Insurance Distribution Channel: Direct Sales, Online Platforms, Agents, Brokers Client Type: Individuals, Small Businesses, Corporates, Non-Profits Insurance Type: Personal Lines, Commercial Lines, Specialty Lines, Reinsurance |
| Companies Covered | Marsh & McLennan Companies, Aon, Arthur J. Gallagher & Co., Willis Towers Watson, Alliant Insurance Services, Hub International, Brown & Brown, Acrisure, Lockton Companies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Insurance Brokerage Market Trends and Innovations
Digital distribution infrastructure is compressing traditional commission structures while elevating data-analytics capabilities as the primary competitive differentiator among intermediaries serving complex commercial risks.
Algorithmic placement engines are fragmenting the small commercial market by automating coverage matching against carrier appetite matrices. Regional independent agencies in Ohio and Illinois are deploying these tools to bind standard BOP policies without human underwriter involvement. The structural consequence is margin compression on transactional business that subsidizes specialty lines expertise.
California's Senate Bill 531 mandates enhanced fiduciary disclosure requirements for broker-dealer hybrids packaging investment advisory with insurance placement. The industrial consequence is accelerated compliance spend among dually registered firms. Mid-market employee benefits brokers in Los Angeles and San Francisco are responding by segregating securities and insurance operations into distinct legal entities.
Employer-sponsored group benefits procurement is compressing renewal cycles from annual to semi-annual review as HR technology platforms enable real-time benchmarking. Benefits consultants in Texas and New York are replacing commission-based placement with fee-for-service advisory models. This shift is most visible among technology sector employers with distributed workforces requiring multi-state compliance navigation.
United States Insurance Brokerage Market Segmentation
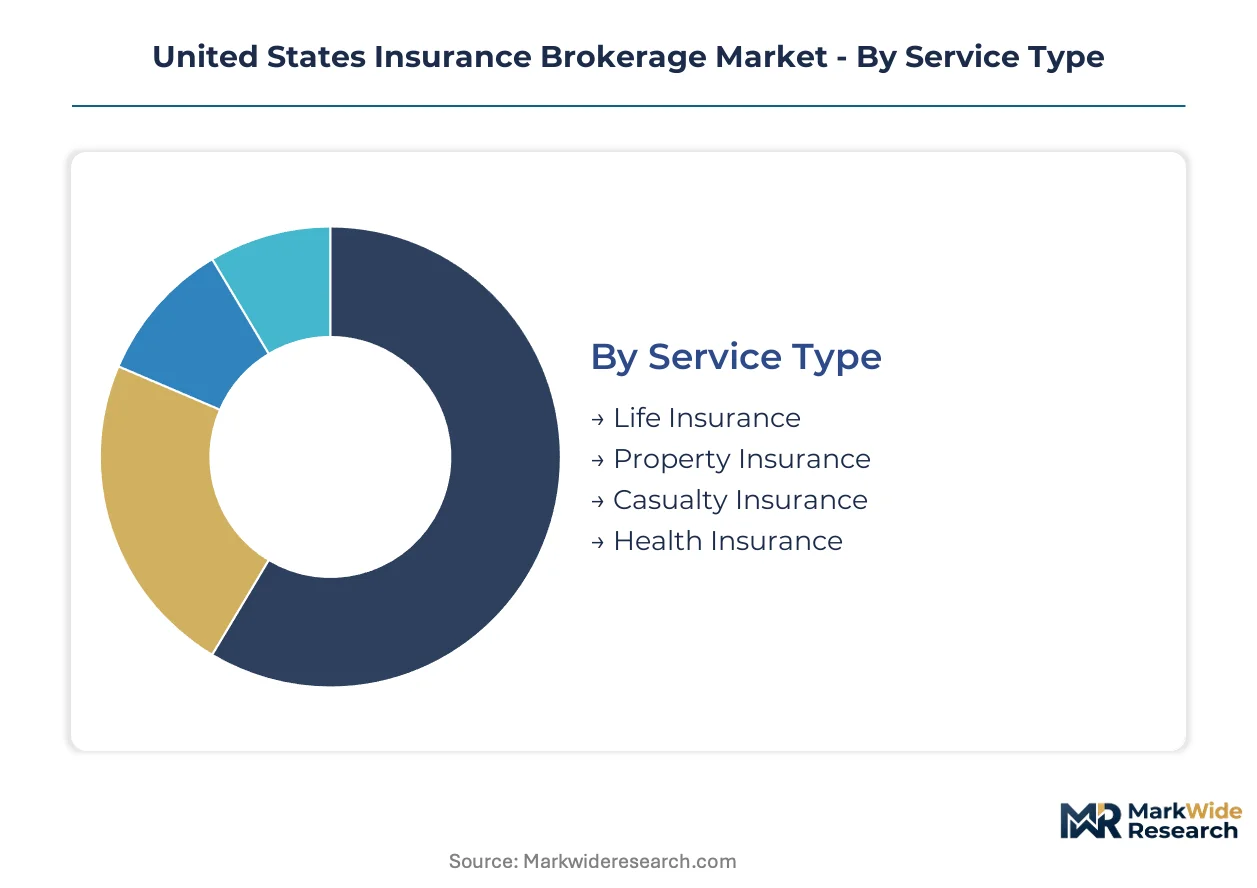
Broker revenue concentration varies sharply across service lines and client tiers, with regulatory treatment of commissions and fiduciary duties creating divergent profitability profiles. State-level surplus lines reforms and FINRA qualification requirements further fragment competitive positioning within each segment category.
Service Type:
State insurance commissioners enforce divergent capital reserve requirements and commission disclosure rules that reshape competitive economics across life, property, casualty, and health brokerage.
- Life Insurance:Permanent and term products generate recurring renewal commissions that sustain agency cash flow across multi-year policy horizons. Demand concentrates among high-net-worth households in Florida and Texas seeking estate liquidity solutions, though FINRA Series 6/7 bifurcation is compressing broker-dealer hybrid margins.
- Property Insurance:Catastrophe-exposed commercial and residential placement requires surplus lines access that only licensed intermediaries in reform states can efficiently navigate. Post-hurricane reconstruction in Florida and wildfire-prone California counties is accelerating E&S market penetration for capacity-constrained risks.
- Casualty Insurance:General liability and workers compensation programs dominate mid-market manufacturing placement. Texas Senate Bill 1075 streamlined eligibility standards reduce compliance burdens for environmental impairment policies in the Permian Basin.
- Health Insurance:Employer-sponsored group benefits sustain recurring commission structures distinct from transactional personal lines. HR technology platforms enable semi-annual renewal cycles that compress traditional annual placement patterns.
Property Insurance handles the majority of throughput; Health Insurance is gaining share fastest as employers shift toward fee-for-service advisory models.
Distribution Channel:
Channel economics reflect divergent customer acquisition costs and technology integration requirements that favor scaled platforms over traditional interpersonal networks.
- Direct Sales:Carrier-captive agents bind standard admitted products without intermediary commission layers. Personal auto and homeowners volume concentrates through direct channels in low-complexity, price-sensitive segments.
- Online Platforms:Algorithmic placement engines automate coverage matching against carrier appetite matrices for small commercial BOP policies. Ohio and Illinois regional agencies deploy these tools to compress transactional margins and subsidize specialty lines expertise.
- Agents:Exclusive and independent producer networks maintain interpersonal relationships that sustain renewal stickiness in complex commercial programs. Legacy agency management systems resist API integration with modern data-analytics platforms.
- Brokers:Independent intermediaries with Bermuda and London market interfaces capture Fortune 500 cyber and environmental placement outside admitted carrier appetite. Marsh & McLennan and Aon anchor competitive posture through captive reinsurance capabilities and enterprise risk quantification platforms.
Brokers command the highest revenue per transaction; Online Platforms are expanding most quickly through algorithmic small-commercial automation.
Client Type:
Client sophistication and policy complexity create tiered service requirements that segment intermediary capabilities and compensation structures.
- Individuals:Personal lines auto, homeowners, and term life placement generates transactional commission income with limited renewal stickiness. Price comparison tools compress margins and accelerate commoditization.
- Small Businesses:Standard BOP and workers compensation programs require limited contractual sophistication but face increasing cyber coverage gaps. Algorithmic placement engines fragment this market by automating carrier matching.
- Corporates:Multi-line corporate programs with contractual sophistication demand full-service independent brokers capable of structuring and binding complex risks. Merged mid-market manufacturing entities require consolidated placement that only scaled intermediaries can deliver.
- Non-Profits:Directors and officers coverage combined with specialized liability programs creates niche placement requirements. Limited risk management staff elevates reliance on broker advisory services.
Corporates generate the dominant share of broker revenue; Small Businesses are climbing the fastest as embedded insurance APIs bypass traditional renewal cycles.
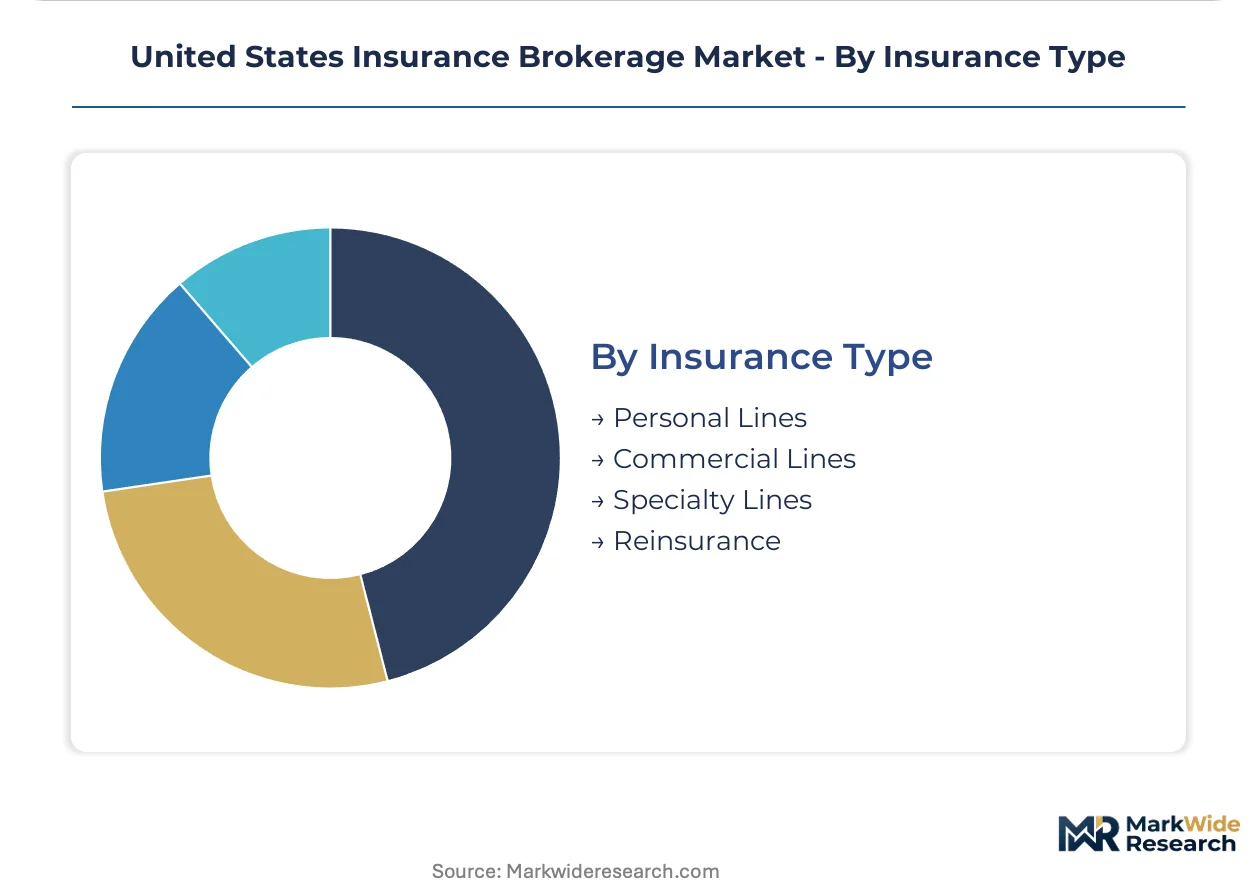
Insurance Type:
Admitted versus non-admitted regulatory treatment fragments market access and reshapes intermediary competitive positioning across personal, commercial, specialty, and reinsurance segments.
- Personal Lines:Standard auto and homeowners products flow through direct and agent channels with minimal surplus lines involvement. California and Florida regulatory divergence on rate filing requirements creates state-by-state pricing friction.
- Commercial Lines:Mid-market manufacturing consolidation drives demand for multi-line programs with contractual sophistication. Renewal stickiness sustains revenue pools that subsidize specialty lines investment.
- Specialty Lines:Cyber, directors and officers, and environmental impairment coverage attracts placement fees at premium multiples to standard commercial business. EPA enforcement acceleration under CERCLA creates pollution legal liability demand that admitted markets rarely underwrite.
- Reinsurance:Broker-mediated treaty and facultative placement connects primary carriers with Bermuda and London capacity. Florida hurricane catastrophe bonds open placement channels for insurance-linked securities that bypass traditional intermediation.
Commercial Lines anchors revenue concentration; Specialty Lines shows the steepest expansion trajectory as admitted carriers retreat from complex risks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level surplus lines reforms and FINRA licensing bifurcation are reshaping broker competitive positioning across major US jurisdictions. Regional demand concentrates where manufacturing density intersects with elevated liability exposures and non-admitted market access.
Texas
Mid-market manufacturers in the Permian Basin drive demand for environmental impairment coverage. Senate Bill 1075 streamlined surplus lines eligibility standards, reducing broker compliance burdens for non-admitted placement. Dallas-Fort Worth anchors specialty broker concentration serving energy sector risk managers.
California
Wildfire-exposed commercial property and cyber liability gaps push Fortune 500 risk managers toward E&S markets. Senate Bill 531 mandates enhanced fiduciary disclosures for broker-dealer hybrids, accelerating compliance spend among dually registered firms. Los Angeles and San Francisco benefit consultants segregate securities and insurance operations into distinct legal entities.
Florida
Post-hurricane reconstruction capital requirements create placement channels for catastrophe bonds and insurance-linked securities. State surplus lines tax treatment diverges from national norms, steering premium flow toward lower-tax jurisdictions. Miami-Dade and Tampa-St. Petersburg concentrate captive reinsurance brokerage capabilities serving Latin American risk transfer.
New York
Financial services sector concentration generates demand for directors and officers coverage at premium multiples to standard commercial lines. The state insurance commissioner enforces capital reserve requirements that exceed federal baselines, elevating barriers for regional entrants. Manhattan anchors Marsh & McLennan and Aon headquarters operations with Bermuda and London market interfaces.
Illinois
Algorithmic placement engines automate small commercial BOP policies across manufacturing and logistics sectors. Regional independent agencies deploy these tools to compress transactional margins and subsidize specialty lines expertise. Chicago concentrates employee benefits brokers transitioning from commission-based placement to fee-for-service advisory models.
United States Insurance Brokerage Market Competitive Landscape
Player mix skews toward scaled independent intermediaries with captive reinsurance capabilities and data-analytics platforms. Market structure concentrates revenue among tier-one brokers with Bermuda and London market access, while regional independents defend position through algorithmic small-commercial automation and interpersonal relationship networks. Strategic archetypes include global risk quantification platforms, specialty surplus lines access providers, and technology-enabled employee benefits consultants. Dominant competitive moves center on M&A consolidation of mid-market agencies and API integration with real-time risk telemetry systems.
Within the global platform tier, Marsh & McLennan Companies and Aon occupy positions defined by captive reinsurance brokerage capabilities and enterprise risk quantification infrastructure. Arthur J. Gallagher & Co. represents the specialty access archetype, with its structure exemplifying independent intermediary scale without securities brokerage hybridization. These three entities anchor competitive dynamics across commercial lines placement, where contractual sophistication and renewal stickiness sustain revenue pools that subsidize specialty lines investment.
| Leading Market Players |
|---|
| Marsh & McLennan Companies |
| Aon |
| Arthur J. Gallagher & Co. |
| Willis Towers Watson |
| Alliant Insurance Services |
| Hub International |
| Brown & Brown |
| Acrisure |
| Lockton Companies |
| Others |
Pricing and Supply Chain Analysis
Algorithmic placement engines displacing traditional broker intermediation in small commercial BOP policies simultaneously compress commission structures and reshape supply geography toward technology hubs in Ohio and Illinois, while elevating data-analytics capabilities as the primary pricing differentiator for complex commercial risks.
Pricing Analysis
Commission rate tiering creates the primary spread between transactional personal lines and specialty commercial placement, with standard auto and homeowners policies earning scaled percentages to premium volume while cyber, D&O, and environmental coverage commands placement fees at premium multiples. FINRA qualification costs for dually registered broker-dealer hybrids impose pricing pressure that pure property-casualty operations avoid, compressing margins among firms packaging investment advisory with insurance placement. Small businesses and individual purchasers exhibit highest price sensitivity through algorithmic comparison tools, while Fortune 500 risk managers prioritize risk quantification capabilities over commission minimization.
Supply Chain Analysis
Bermuda and London anchor captive reinsurance brokerage capabilities serving US Fortune 500 placement, while domestic surplus lines capacity concentrates in Texas, Florida, and California following state-level eligibility reforms. Raw material dependencies center on actuarial talent pools and proprietary data-analytics platforms that quantify enterprise risk for carrier appetite matching. Single-source vulnerability runs through legacy agency management systems at regional independents that resist API integration with modern telemetry feeds. Distribution runs through scaled intermediaries with Bermuda and London market interfaces, supplemented by algorithmic engines automating small-commercial carrier matching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States insurance brokerage market exhibits cyclical recovery characteristics as post-pandemic commercial lines hardening and specialty capacity constraints drive renewal rate momentum through mid-market manufacturing consolidation.
For Market Incumbents: Consolidate mid-market agency networks in Texas and California to capture Senate Bill 1075 surplus lines access advantages and Senate Bill 531 compliance cost efficiencies. Acquire specialty cyber and environmental placement teams to offset margin compression from algorithmic small-commercial automation. Vertical integration into captive reinsurance capabilities reinforces competitive positioning against Marsh & McLennan and Aon data-analytics platforms. For New Entrants and Emerging Players: FINRA Series 6 fast-track completion enables rapid entry into broker-dealer hybrid models before California fiduciary disclosure mandates fully phase in. Target environmental impairment white space in the Permian Basin where Texas streamlined eligibility standards reduce compliance burdens. Embedded insurance API partnerships with commercial auto fleets and construction equipment lessors bypass traditional annual renewal cycles and incumbent relationship networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional independents in Ohio and Illinois deploying algorithmic placement engines but lacking Bermuda and London market interfaces. Long-term viability rests on specialty lines expertise migration and data-analytics platform integration across the projection horizon. Watch state legislative momentum toward surplus lines modernization as inflection indicator for E&S market access valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Mid-Market Agency Acquisition | Captures Texas Senate Bill 1075 surplus lines access advantages for Permian Basin environmental placement. |
| Data-Analytics Platform Integration | Enables real-time enterprise risk quantification matching Aon and Marsh & McLennan competitive capabilities. |
| Embedded Insurance API Development | Bypasses traditional renewal cycles by integrating usage-based coverage at commercial fleet point-of-sale. |
| Specialty Lines Talent Acquisition | Addresses actuarial scarcity in cyber and climate risk modeling through compensation structure realignment. |
| Surplus Lines Compliance Segregation | Isolates California Senate Bill 531 fiduciary disclosure costs from core brokerage operations. |
Research Methodology
Cross-validation between primary interviews with commercial lines brokers, risk managers at mid-market manufacturers, state insurance commissioners, and FINRA compliance officers anchors the qualitative findings, supplemented by secondary validation against National Association of Insurance Commissioners regulatory filings, state legislative databases, SEC broker-dealer disclosure documents, and surplus lines premium tax records. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis frameworks test forecast robustness across regulatory reform scenarios, specialty capacity availability, and cyber claims frequency assumptions. Segmentation dimensions include service type, distribution channel, client tier, and insurance regulatory classification, with CAGRs derived from premium volume trajectory modeling and intermediary commission rate evolution. Forecast inputs incorporate state-level surplus lines eligibility standards and FINRA qualification cycle completion rates.
Underlying assumptions cover commercial lines hardening persistence, specialty carrier appetite stability, and state regulatory reform implementation timelines, with deviation risk concentrated in cyber catastrophe frequency and mid-market manufacturing consolidation velocity. Recalibration cycles align with material shifts in state legislative momentum and FINRA fiduciary standard debate outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
General Insurance Market
Insurance
India Travel Insurance Market
Insurance
Singapore Business Income Insurance Market
Insurance
Telematics-Based Auto Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Road Assistance Insurance Market
Insurance
Aircraft Insurance Market
Insurance
Europe Health Insurance Market
Insurance
India Liability Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
China Parametric Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Dental Insurance Market
Insurance
Insurance Brokerage Market
Insurance
Financial Guarantee Market
Insurance
India Life and Non-Life Insurance Market