
 Middle East and Africa Insurtech Market | 2026-2036
Middle East and Africa Insurtech Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Insurtech Market Foresight
Subscription-based policy administration is restructuring what insurers sell across the Middle East and Africa. Bayzat leverages embedded HR-insurance bundles to anchor corporate client retention in the Gulf. Lami Technologies sustains API-first distribution partnerships that extend microinsurance reach into East African agricultural communities. Yallacompare dominates price-comparison traffic for motor and health products, competing on digital acquisition efficiency rather than proprietary risk pools.
Insurtech denotes technology-enabled platforms that automate insurance functions through cloud-native architecture, API integrations, and data-driven risk scoring, primarily reducing distribution costs and accelerating claims settlement for traditionally underserved populations. Claims Processing and Customer Engagement solutions lead current deployment as insurers prioritize loss-ratio improvement and retention over front-end innovation. Artificial Intelligence and Big Data segments within the technology dimension are attracting disproportionate capital allocation as underwriters seek predictive models for pricing in markets with thin historical data.
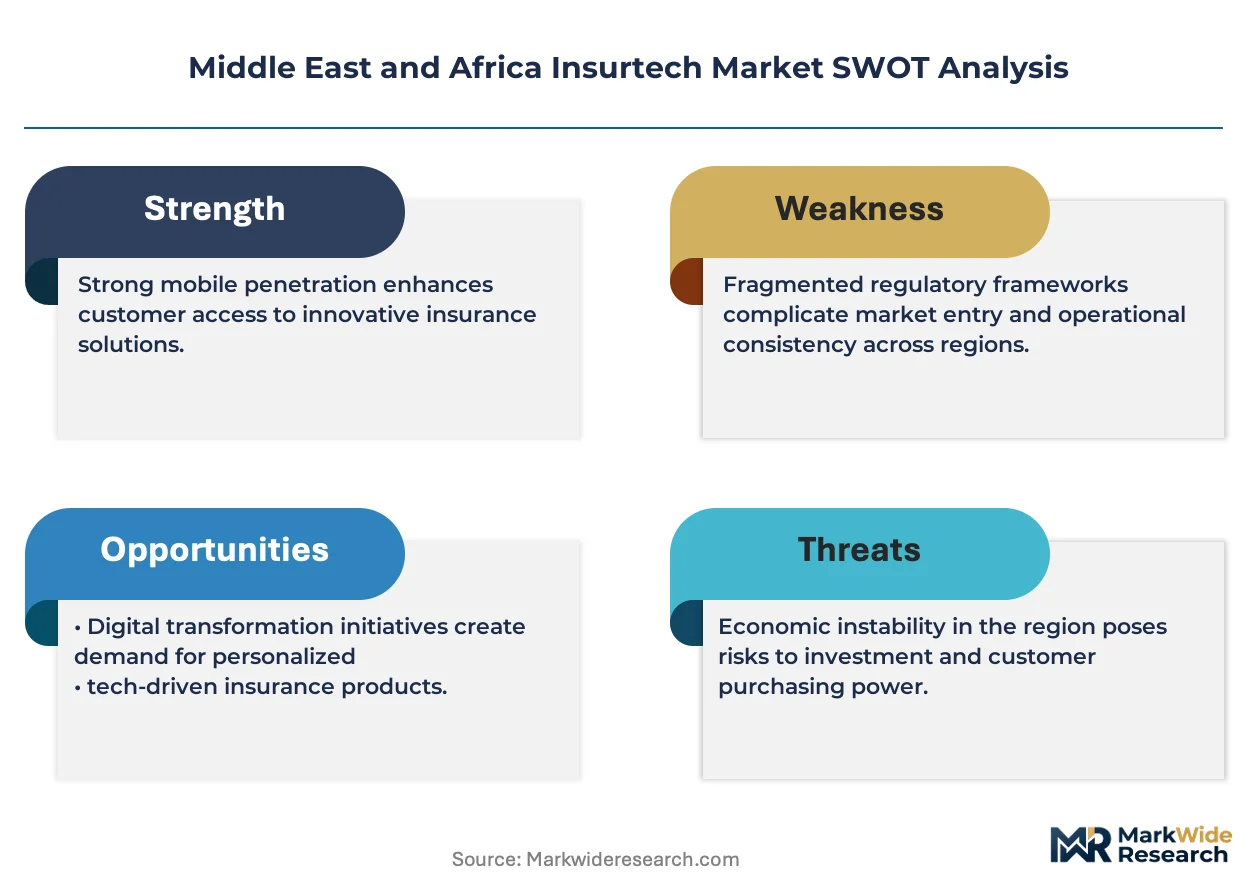
The UAE central bank's regulatory sandbox framework and South Africa's Financial Sector Conduct Authority licensing requirements shape product design and market entry timelines for foreign insurtech operators. Kenya's Insurance Regulatory Authority mandates interoperability standards that influence technology stack decisions for regional platforms. Stakeholders must monitor how shifting data-localization requirements across Gulf Cooperation Council member states and Sub-Saharan African jurisdictions affect cloud infrastructure costs and partnership structures.
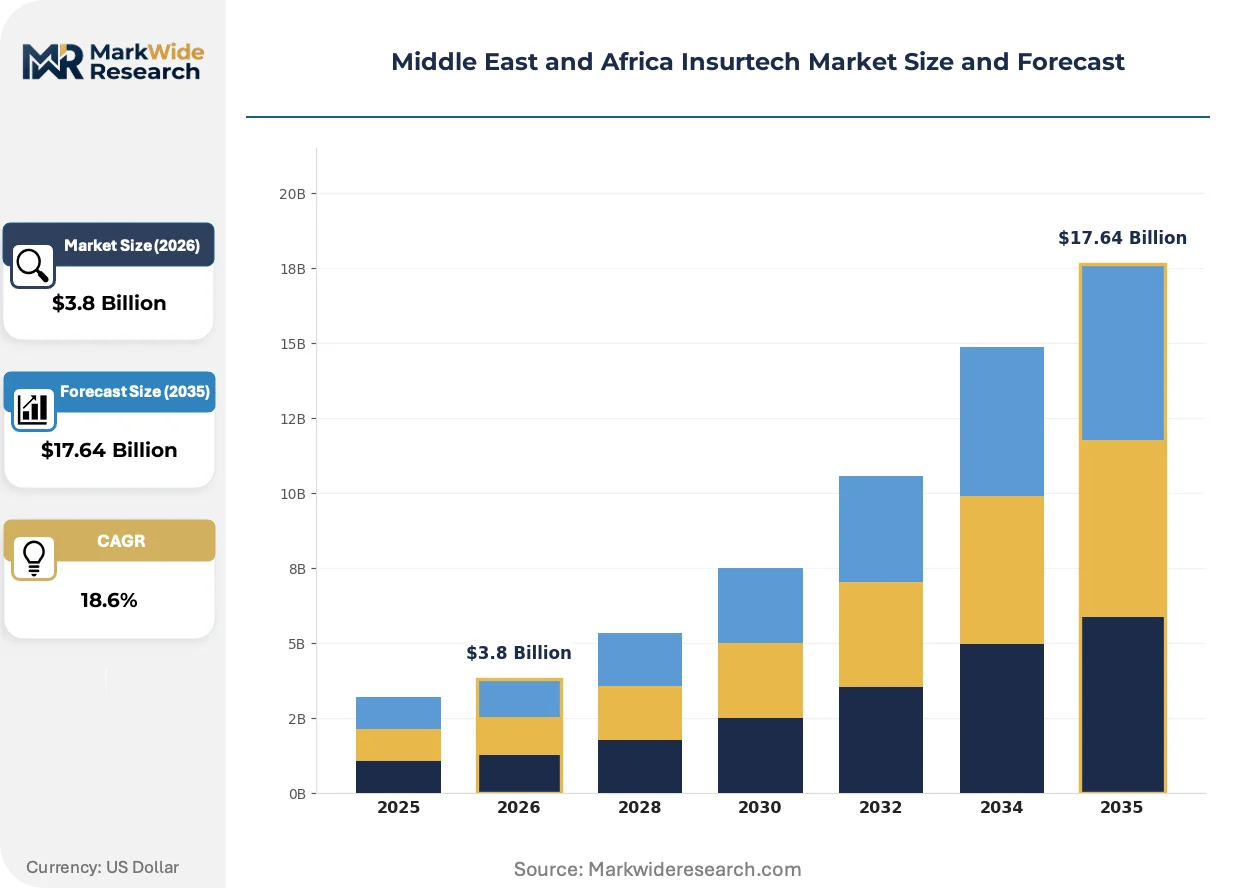
Market Dynamics
Regulatory sandboxes introduced by the UAE central bank and Kenya's Insurance Regulatory Authority are compressing product development cycles for technology-driven underwriting models across the Middle East and Africa.
Growth Catalysts
- Mobile penetration:Deepening smartphone adoption in Nigeria and South Africa extends insurance access to previously excluded populations through USSD and app-based enrollment.
- Interoperability mandates:Kenya's Insurance Regulatory Authority standards for data exchange reduce integration friction between legacy carriers and digital distribution platforms.
- Cloud-native architecture:API-first policy administration systems cut distribution costs for microinsurance products targeting agricultural and informal sector workers.
Market Restraints
- Data-localization compliance:Gulf Cooperation Council member states impose divergent cloud infrastructure requirements that fragment regional technology stack decisions.
- Thin historical data:Limited actuarial records in Sub-Saharan African markets constrain predictive model accuracy for pricing and risk selection.
- Legacy system dependency:Established insurers in South Africa maintain mainframe-based policy administration that resists real-time API integration.
Strategic Opportunities
- Embedded distribution:HR-tech platforms in the Gulf present white-space channels for group health and life products bundled with payroll services.
- Agricultural index insurance:Satellite imagery and weather data convergence enables parametric crop coverage for smallholder farmers in East Africa.
- Regulatory sandbox expansion:South Africa's Financial Sector Conduct Authority licensing pathways attract foreign operators seeking controlled market entry.
Industry Challenges
- Actuarial talent scarcity:Shortage of data scientists with insurance domain expertise delays model deployment in competitive pricing segments.
- Claims fraud detection:Digital-first distribution channels require real-time verification systems that strain operational technology budgets.
- Multi-jurisdiction compliance:Divergent consumer protection standards across Middle Eastern and African markets complicate single-platform regional expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Insurtech Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Policy Administration, Claims Processing, Underwriting Solutions, Customer Engagement Distribution Channel: Direct Sales, Brokers, Agents, Digital Platforms End User: Individuals, SMEs, Corporates, Startups Technology: Blockchain, Artificial Intelligence, Big Data, Internet of Things |
| Companies Covered | Bayzat, Yallacompare, Rasan, Policybazaar.ae, Aqeed, Lami Technologies, Souqalmal, Turaco, Naked Insurance, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Insurtech Market Shifts & Advancements
Artificial intelligence applications and embedded finance architectures are compressing the traditional insurance value chain from distribution through claims settlement across Middle Eastern and African markets.
Machine learning models trained on alternative data sources including mobile money transaction histories and satellite imagery are rewriting risk assessment methodologies for informal sector borrowers and agricultural producers. Microinsurance distributors in Kenya and Nigeria deploy these tools to automate underwriting decisions within seconds. The compression of traditional actuarial review cycles is enabling premium collection at price points viable for mass-market penetration.
The UAE central bank's regulatory sandbox framework permits controlled testing of technology-driven underwriting models without full licensing requirements. Foreign operators utilize this pathway to validate product-market fit before committing to permanent establishment costs. South Africa's Financial Sector Conduct Authority has responded with accelerated licensing tracks for insurtech entrants meeting specified capital and governance thresholds.
SME procurement of insurance is migrating from broker-mediated annual renewals toward subscription-based monthly administration embedded within enterprise software platforms. Corporate clients in the Gulf increasingly expect HR and benefits administration to converge on single vendor relationships. This channel consolidation pressures traditional intermediaries to develop API capabilities or cede mid-market accounts to technology-integrated competitors.
Middle East and Africa Insurtech Market Segmentation
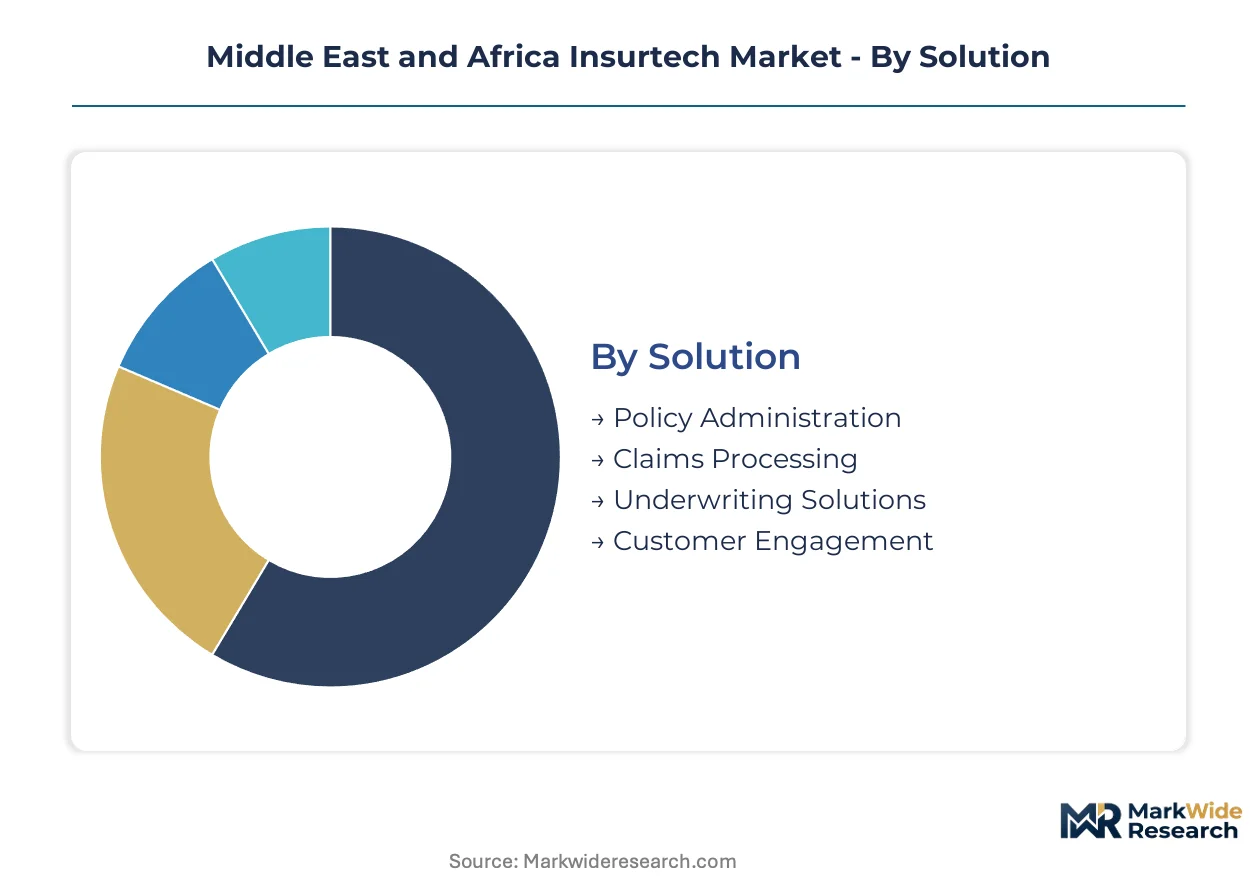
Insurtech vendors across the Middle East and Africa configure their platforms around distinct solution architectures, distribution mechanics, and underlying technology stacks. Each segmentation dimension carries specific implications for capital allocation, partnership structures, and regulatory compliance pathways.
Solution:
Replacement cycles for legacy core systems are accelerating as insurers confront margin compression and digital-native competitor entry.
- Policy Administration:Cloud-native policy engines automate quote-to-bind workflows and endorsements through API-connected rating algorithms. Gulf-based carriers prioritize these upgrades to embed products within HR-tech platforms and enterprise software suites.
- Claims Processing:Automated claims triage, document verification, and payment orchestration reduce loss adjustment expenses and settlement timelines. Kenyan and Nigerian insurers deploy these tools to manage high-frequency, low-value claims from mobile-distributed microinsurance portfolios.
- Underwriting Solutions:Predictive risk scoring models integrate alternative data streams including mobile money histories and satellite imagery.
- Customer Engagement:Omnichannel communication platforms unify policy servicing across USSD, mobile apps, and conversational interfaces.
Claims Processing sits at the top of the volume ranking, with Customer Engagement climbing the fastest.
Distribution Channel:
Cost-to-acquire variations across channels are restructuring commission structures and platform investment priorities.
- Digital Platforms:Price-comparison engines and embedded insurance APIs aggregate demand and automate policy issuance without intermediary markup. UAE and South African aggregators capture motor and health traffic through search-optimized acquisition funnels.
- Brokers:Traditional intermediaries defend corporate accounts through advisory relationships but face compression as SME procurement migrates to software-embedded channels.
- Direct Sales:Insurer-owned digital properties and call centers target renewals and upsells within existing policyholder bases.
- Agents:Individual producers leverage mobile-enabled point-of-sale tools to penetrate informal sector and rural demographics.
Digital Platforms command the steepest expansion trajectory, while Agent networks retain density in agricultural and peri-urban segments.
End User:
Customer lifetime value differentials are driving product design specialization and pricing granularity.
- SMEs:Mid-sized enterprises across the Gulf and South Africa procure bundled health, liability, and property coverage through subscription models integrated with payroll and accounting software.
- Corporates:Large employers negotiate customized group risk programs with dedicated account management and captive feasibility analysis.
- Individuals:Mass-market consumers access term life, motor, and personal accident products through mobile-first enrollment with premium financing options.
- Startups:Early-stage technology companies purchase directors and officers coverage and cyber liability through streamlined digital onboarding.
SMEs anchor current revenue concentration, with Individuals gaining share fastest through microinsurance penetration.
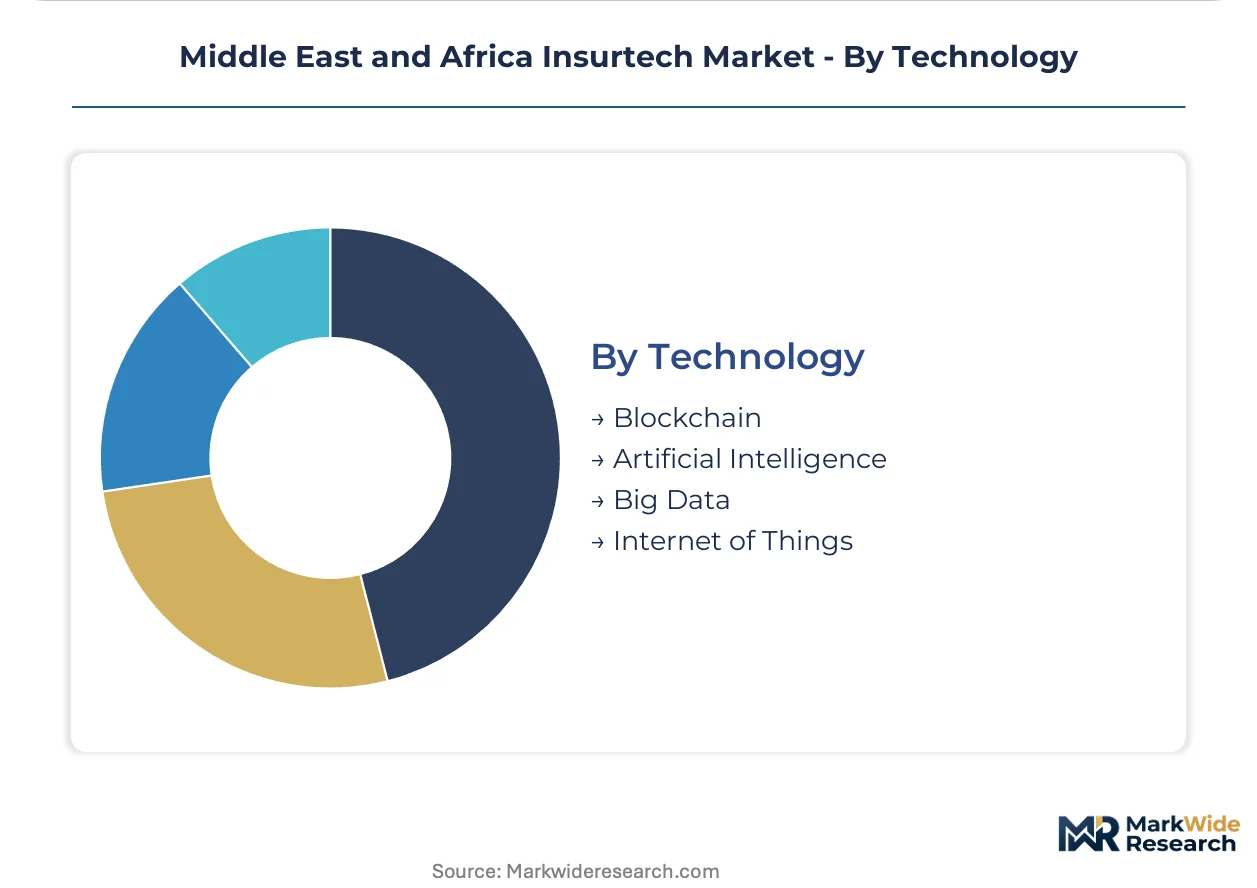
Technology:
Technology stack decisions determine model training costs, data infrastructure requirements, and regulatory sandbox eligibility.
- Artificial Intelligence:Machine learning pipelines automate underwriting decisions, fraud detection, and claims segmentation using alternative data sources where historical actuarial records remain thin.
- Big Data:Data lake architectures aggregate telematics, mobile transaction histories, and satellite imagery to refine risk segmentation and dynamic pricing models.
- Blockchain:Distributed ledger applications target parametric insurance smart contracts and reinsurance placement transparency.
- Internet of Things:Connected device data streams from vehicles, wearables, and agricultural sensors enable usage-based pricing and real-time risk monitoring.
Artificial Intelligence dominates capital allocation, with Big Data infrastructure expanding most quickly across East African agricultural insurance deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE and South Africa present contrasting maturity profiles within Middle East and Africa insurtech, with the former accelerating through regulatory sandbox pathways while the latter grapples with legacy system modernization constraints.
United Arab Emirates
Corporate demand for embedded HR-insurance bundles and motor price-comparison platforms drives platform investment in Dubai and Abu Dhabi. The UAE central bank's regulatory sandbox framework permits controlled testing of technology-driven underwriting models without full licensing requirements. Dubai International Financial Centre anchors foreign operator entry, with fintech clusters concentrating API-first policy administration ventures targeting Gulf Cooperation Council expansion.
South Africa
Established insurers in Johannesburg and Cape Town confront margin compression from digital-native competitors while maintaining mainframe-based policy administration systems. The Financial Sector Conduct Authority licensing requirements shape product design and market entry timelines for foreign insurtech operators. Cape Town's technology corridor hosts fraud detection and claims automation specialists serving both domestic carriers and regional expansion into Sub-Saharan markets.
Kenya
Mobile penetration in Nairobi and Mombasa extends insurance access to agricultural communities through USSD and app-based microinsurance enrollment. The Insurance Regulatory Authority mandates interoperability standards that reduce integration friction between legacy carriers and digital distribution platforms. Nairobi's technology hub concentrates API-first distributors partnering with mobile money providers for premium collection in informal sector segments.
Nigeria
Deepening smartphone adoption in Lagos and Abuja drives demand for term life and personal accident products through mobile-first enrollment channels. The country's national insurance regulator maintains capital adequacy requirements that influence technology stack decisions for regional platforms. Lagos anchors insurtech venture formation, with Yaba technology cluster hosting claims processing automation ventures targeting West African market expansion.
Saudi Arabia
Enterprise software integration demand in Riyadh and Jeddah accelerates subscription-based policy administration for SME health and liability coverage. The Saudi Arabian Monetary Authority supervises licensing pathways for digital insurance intermediaries operating within the Kingdom's financial sector. Riyadh's fintech hub attracts regional platform operators seeking controlled market entry before Gulf Cooperation Council-wide deployment.
Middle East and Africa Insurtech Market Competitive Landscape
Top-tier vendors anchor the API-first distribution segment, while mid-tier specialists concentrate on claims automation and embedded finance architectures. The competitive structure fragments across three primary tiers: Gulf-based corporate benefit platforms, East African microinsurance distributors, and price-comparison aggregators serving motor and health markets. Strategic archetypes include embedded distribution specialists, parametric agricultural underwriters, and legacy system modernization vendors. Dominant competitive moves encompass regulatory sandbox utilization for market entry validation and API partnership structures that bypass traditional intermediary channels.
Within the embedded distribution tier, Bayzat and Lami Technologies exemplify contrasting geographic specializations. Bayzat, a Dubai-based entity, occupies a position anchoring corporate client retention through HR-technology convergence in Gulf markets. Lami Technologies represents the API-first microinsurance archetype, with its structure enabling agricultural coverage extension into East African communities through mobile-enabled distribution partnerships. Yallacompare sits within the price-comparison aggregator category, competing on digital acquisition efficiency rather than proprietary risk pool development.
| Leading Market Players |
|---|
| Bayzat |
| Yallacompare |
| Rasan |
| Policybazaar.ae |
| Aqeed |
| Lami Technologies |
| Souqalmal |
| Turaco |
| Naked Insurance |
| Others |
Supply & Pricing Matrix
Cloud infrastructure spot pricing indices across Gulf Cooperation Council member states cascade through insurtech platform economics, compressing SaaS-tiered subscription rates for policy administration software while elevating data-localization compliance premiums for cross-border operators.
Pricing Analysis
Capacity additions in Kenya and Nigeria are reshaping price floors for API-first distribution platforms as mobile money infrastructure density improves. SaaS-tiered subscription models dominate SME procurement, with price differentiation driven by interoperability certification levels and embedded HR-tech integration depth. Cost compression in the microinsurance tier intensifies because satellite imagery underwriting tools reduce loss-adjustment overhead. Individual consumers exhibit highest price sensitivity, while corporate clients purchasing bundled health and liability coverage demonstrate lowest elasticity.
Supply Chain Analysis
Software engineering talent availability in Egypt and Jordan anchors policy administration system development, while data science specialization concentrates in South Africa and the UAE. Technology stack procurement draws from Irish-domiciled cloud providers, Indian IT services firms, and Chinese hardware manufacturers for edge computing deployments. Single-source vulnerability in satellite imagery data feeds from European providers presents concentration risk for agricultural index insurance underwriters. Distribution runs through API partnerships with mobile network operators and HR-tech platforms rather than traditional intermediary networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa insurtech market functions as a geographic-arbitrage play where regulatory sandbox access in the UAE costs substantially less than permanent establishment requirements in European jurisdictions, enabling capital-efficient product validation.
For Market Incumbents: Deploy legacy system API wrappers to neutralize cloud-native competitor threat from Bayzat and Lami Technologies. Accelerate interoperability certification with Kenya's Insurance Regulatory Authority to defend SME accounts against embedded distribution specialists. Channel control through exclusive mobile money partnerships represents the critical defensive lever.
For New Entrants and Emerging Players: Begin with agricultural index insurance in Ethiopia and Tanzania where mobile penetration deepens but regulatory frameworks remain permissive. White-space concentration sits with parametric crop coverage for smallholder farmers. Go-to-market execution should anchor in satellite imagery data partnerships rather than traditional actuarial hiring.
For Investors and Strategic Acquirers: Asymmetric upside sits with claims automation specialists possessing fraud detection IP applicable across multiple African regulatory jurisdictions. Long-term viability hinges on platform scalability through the analysis window rather than single-market dominance. Acquisition target archetype: API-first distributors with proven mobile network operator integration. The signal to watch is central bank sandbox expansion announcements in secondary African markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Utilization | UAE central bank framework permits controlled underwriting model testing without full licensing capital requirements. |
| API Partnership Structuring | Mobile network operator integrations bypass traditional agent commission structures in Nigerian and Kenyan markets. |
| Alternative Data Integration | Satellite imagery and mobile money histories enable underwriting in thin-actuarial-record Sub-Saharan African markets. |
| Embedded Distribution Development | HR-tech platform convergence captures SME health and life procurement migrating from broker-mediated channels. |
| Interoperability Certification Investment | Kenya's Insurance Regulatory Authority standards reduce friction for legacy carrier integration and accelerate deployment. |
Research Methodology
Bottom-up SME procurement modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core. Primary interviews with insurtech platform CTOs, insurance regulatory authority officials, mobile network operator partnership leads, and agricultural cooperative administrators combined with secondary validation. Secondary sources encompass central bank sandbox disclosure filings, Insurance Regulatory Authority interoperability standards documentation, mobile penetration statistics from national telecommunications regulators, and hyperscaler cloud region capex announcements. Top-down and bottom-up triangulation ensures segment-level consistency.
Historical trendline analysis of policy administration system replacement cycles and mobile insurance enrollment velocity informed projection frameworks. Segmentation modeling spans solution architecture, distribution channel mechanics, end-user organization size, and underlying technology stack across the projection horizon. CAGRs derive from fitted growth curves calibrated to mobile money transaction volume trajectories and regulatory sandbox expansion timelines. Industry-specific forecast inputs include satellite imagery data cost deflation curves and API integration friction indices.
Several conditions sit outside the modeled scope, including sovereign currency devaluation events, abrupt data-localization mandate changes, and catastrophic climate events disrupting agricultural index insurance loss ratios. Forecasts reflect underlying assumptions about regulatory sandbox continuity and mobile network operator partnership stability. Material deviation in central bank licensing timelines or cloud infrastructure cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
UK Insurtech Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Insurtech Market
Insurance Technology
Insurance Fraud Detection Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Insurance Software Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
Europe Insurtech Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Global Commercial Insurance Software Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Global Insurance Rating Software Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Japan AI in Insurance Market