
 India Health Insurance Market | 2026-2036
India Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Health Insurance Market Insights
A shortage of trained actuaries and underwriters is unwinding capacity expansion across the sector. Star Health and Allied Insurance Co. Pvt. Ltd. dominates retail health distribution through its agency-heavy model. ICICI Lombard General Insurance Company Limited leverages bancassurance partnerships to sustain premium growth in tier-two cities. HDFC ERGO General Insurance Company Limited specializes in corporate wellness-linked group covers that anchor its commercial portfolio.
India health insurance constitutes risk-pooling financial contracts that reimburse hospitalization, day-care procedures, and pre-existing condition treatments through premium-funded reserves. Products operate on community-rated or experience-rated pricing with regulated solvency margins and mandatory free-look periods. Family floater policies lead premium volumes due to cost efficiency for multi-member households. Online distribution channels represent the fastest-growing acquisition route, though agent networks still control rural penetration. Senior citizen plan categories carry elevated margins but face stricter underwriting scrutiny from reinsurance panels.
IRDAI mandates product filing norms and solvency ratios that shape insurer capital allocation and product design. RBI's concurrent oversight of bank-led distribution channels imposes KYC and suitability standards on bancassurance sales. The PLI scheme for healthcare infrastructure indirectly expands addressable patient pools for underwriters. Stakeholders must monitor how IRDAI's Bima Sugam digital platform alters aggregator economics and direct-to-consumer pricing transparency.
Market Dynamics
IRDAI's regulatory sandbox is compressing product approval timelines from years to months, forcing insurers to rebuild underwriting and distribution infrastructure around digital-first issuance rather than paper-heavy agency networks.
Growth Catalysts
- PLI scheme for healthcare infrastructure:Government capital incentives for hospital construction in tier-two and tier-three cities expand the addressable provider network that insurers can credibly contract.
- Maharashtra and Karnataka hospital density:Concentrated private bed capacity in these states enables risk-pooling at scale, reducing per-policy acquisition costs relative to dispersed geographies.
- Telemedicine integration:Remote consultation protocols embedded into policy terms lower claim frequency for minor ailments while improving member retention through perceived value-add.
Market Restraints
- Actuarial talent scarcity:The shortage of trained actuaries and underwriters unwinds capacity expansion plans, forcing insurers to ration new policy issuance despite capital availability.
- Reinsurance panel scrutiny:Senior citizen plan categories face stricter risk assessment from global reinsurers, compressing margins on high-premium products targeted at aging demographics.
- Legacy IT infrastructure:Core policy administration systems built on decades-old architectures impose integration costs that delay API-based distribution partnerships with fintech aggregators.
Strategic Opportunities
- Bima Sugam platform rollout:IRDAI's unified digital marketplace alters aggregator economics by mandating price transparency, creating direct-to-consumer channels that bypass traditional commission structures.
- Corporate wellness integration:Mid-sized enterprises in manufacturing and IT services seek group covers linked to preventive health programs, opening premium volumes outside saturated retail segments.
- AI-powered claims triage:Machine learning models applied to hospital bill validation reduce fraud leakage while accelerating settlement cycles that currently deter policy renewal.
Industry Challenges
- Agent network transition:Rural penetration still depends on commission-driven agency models that resist digital onboarding, creating channel conflict as insurers push online acquisition.
- Free-look period abuse:Mandatory cancellation windows under IRDAI norms attract adverse selection, with policyholders exploiting short-term coverage for planned procedures before surrendering contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Health Insurance Market |
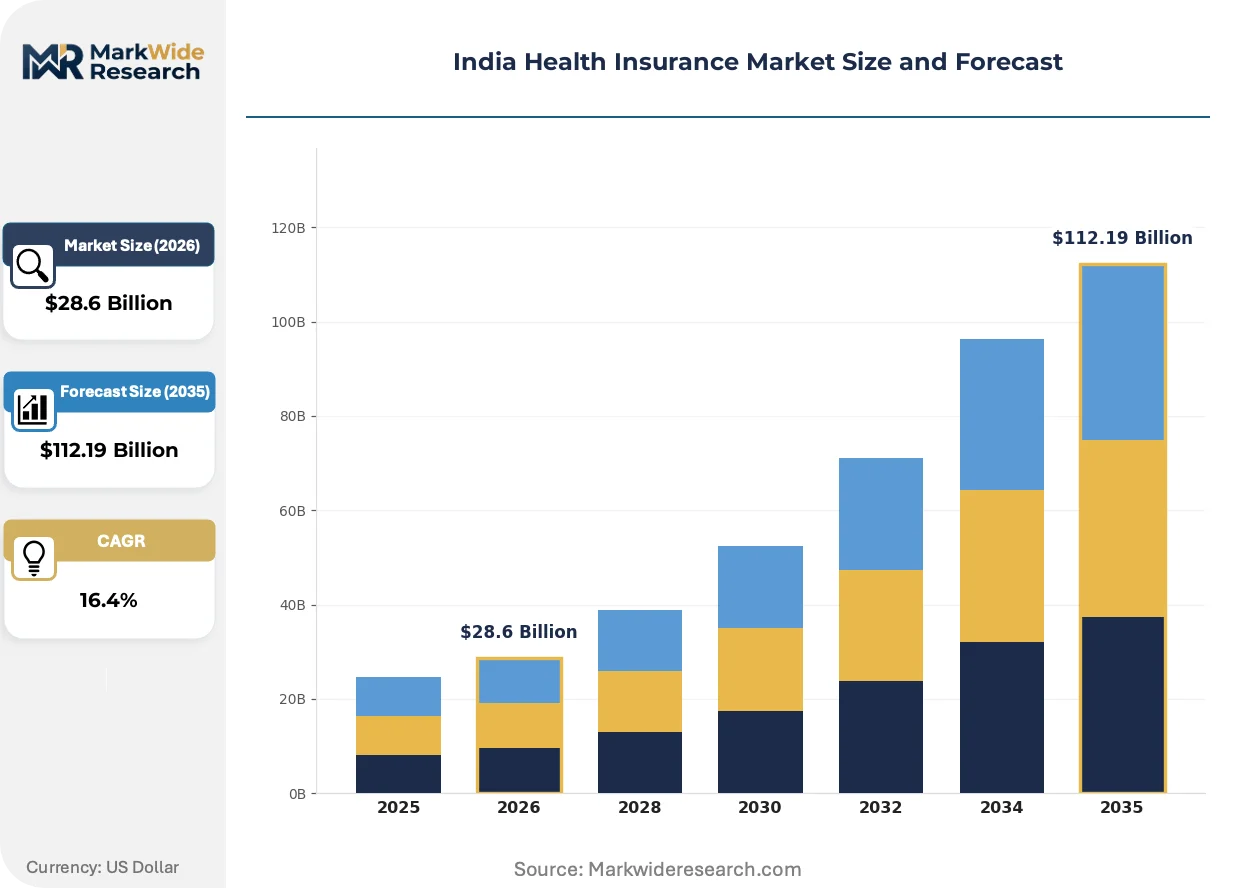
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual, Family Floater, Critical Illness, Top-up Plan Category: Comprehensive, Basic, Critical Care, Senior Citizen Distribution Channel: Online, Broker, Bank, Agent Coverage Type: Hospitalization, Day Care, Pre-existing Conditions, Preventive Care |
| Companies Covered | Star Health and Allied Insurance Co. Pvt. Ltd., HDFC ERGO General Insurance Company Limited, ICICI Lombard General Insurance Company Limited, Bajaj Allianz General Insurance Company Limited, Niva Bupa Health Insurance Company Limited, Care Health Insurance Company Limited, Aditya Birla Health Insurance Co. Limited, New India Assurance Co. Ltd., Tata AIG General Insurance Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Health Insurance Market Trends and Innovations
Digital distribution infrastructure is fragmenting traditional commission hierarchies while embedding artificial intelligence into core underwriting workflows. These shifts compress policy issuance cycles and alter how risk pools are constructed and priced.
Blockchain-based smart contracts for claim settlement are fragmenting the role of third-party administrators. Insurers in Gujarat and Tamil Nadu pilot these systems for cashless hospitalization approvals. The technology compresses dispute resolution timelines from weeks to hours while reducing administrative overhead.
IRDAI's sandbox framework permits live testing of usage-based health products with embedded wearables. Pilot programs in Karnataka tie premium adjustments to verified physical activity data. Regulatory comfort with continuous underwriting is expanding the addressable market for preventive health-linked contracts.
Subscription-based micro-policies are displacing annual renewable contracts among gig economy workers in urban Maharashtra. Platforms bundle hospitalization cover with teleconsultation credits for weekly premiums below traditional thresholds. Channel economics favor high-frequency, low-ticket transactions that legacy systems struggle to administer profitably.
India Health Insurance Market Segmentation
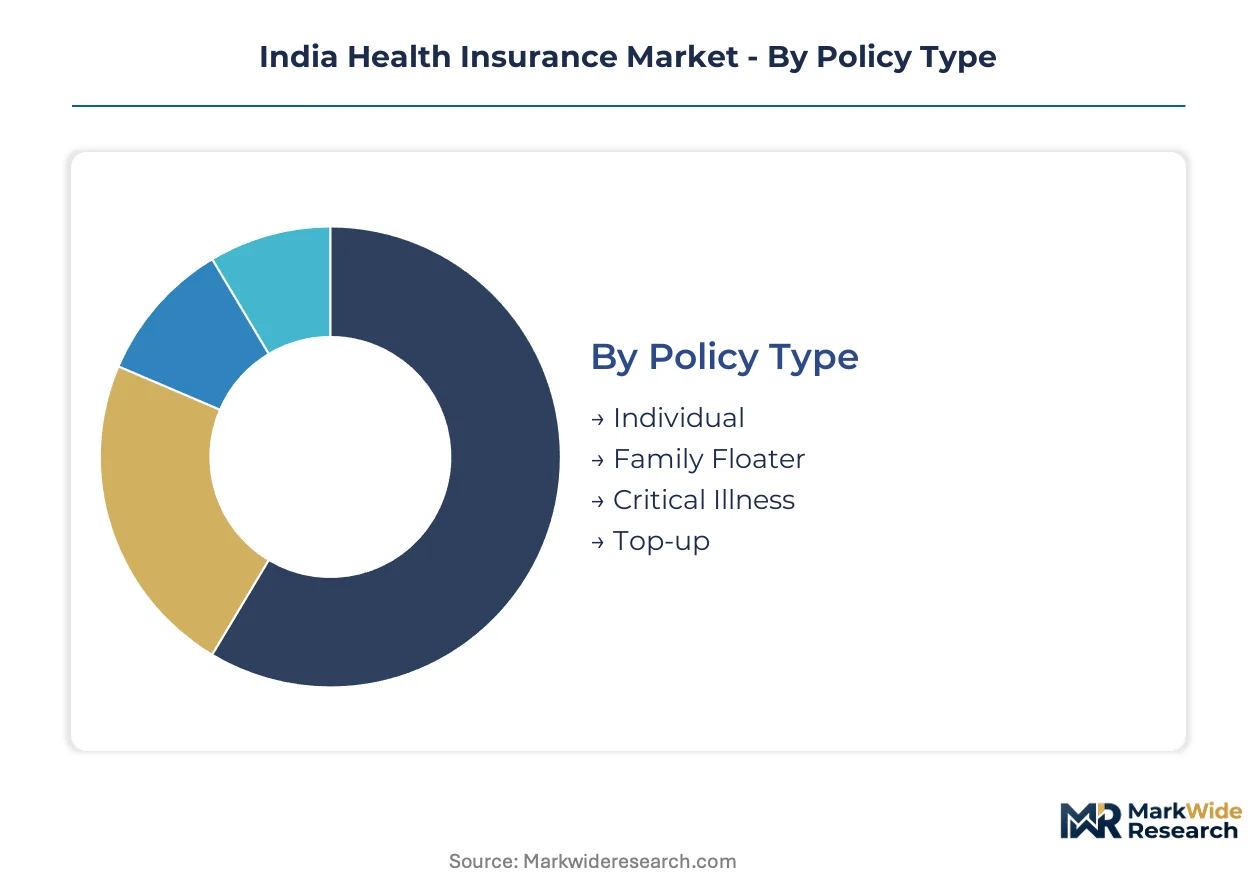
Segmentation in India's health insurance market determines pricing precision, capital allocation, and channel economics. Each dimension reveals distinct risk pools, underwriting costs, and distribution leverage points that shape insurer profitability.
Policy Type:
Channel-mix varies sharply across policy structures, with digital platforms capturing individual policies while family floaters flow through agent networks.
- Individual:Single-life contracts with customized sum insured and no-claim bonus accumulation. Maharashtra's salaried workforce drives volume through employer-sponsored portability programs.
- Family Floater:Shared sum insured across household members with lower per-capita premium outlay. Karnataka's nuclear families favor this structure for cost efficiency, though single large claims exhaust coverage for all members.
- Critical Illness:Lump-sum payout upon diagnosis of specified conditions.
- Top-up:Deductible-triggered coverage exceeding base policy limits.
By volume, Family Floater leads. By growth pace, Top-up is ahead.
Plan Category:
Cost tier alignment shapes reinsurance appetite and commission structures, with comprehensive plans commanding higher brokerage but stricter solvency reserves.
- Comprehensive:Extensive coverage spanning hospitalization, pre and post-care, and alternative treatments. Urban Maharashtra households absorb premium loads for outpatient benefits and international second opinion services.
- Basic:Stripped-down hospitalization-only coverage with room rent sub-limits. Tier-three city penetration depends on this tier's affordability, though claim disputes spike due to co-pay confusion.
- Critical Care:Intensive treatment-focused benefits with higher sum insured.
- Senior Citizen:Age-specific coverage with mandatory waiting periods.
By margin contribution, Comprehensive dominates. By policy count expansion, Basic is climbing fastest.
Distribution Channel:
Customer acquisition cost and persistency rates diverge materially across channel types, determining lifetime value calculations.
- Online:Direct-to-consumer platforms with instant policy issuance and paperless claims. IRDAI's Bima Sugam integration is compressing price discovery cycles for digitally literate buyers in Bengaluru and Mumbai.
- Broker:Independent intermediaries comparing multi-insurer products.
- Bank:Bancassurance partnerships leveraging KYC-verified customer bases.
- Agent:Commission-driven individual representatives with persistent rural penetration.
By premium velocity, Online is expanding most quickly. By persistency ratio, Bank channels sustain renewal rates.
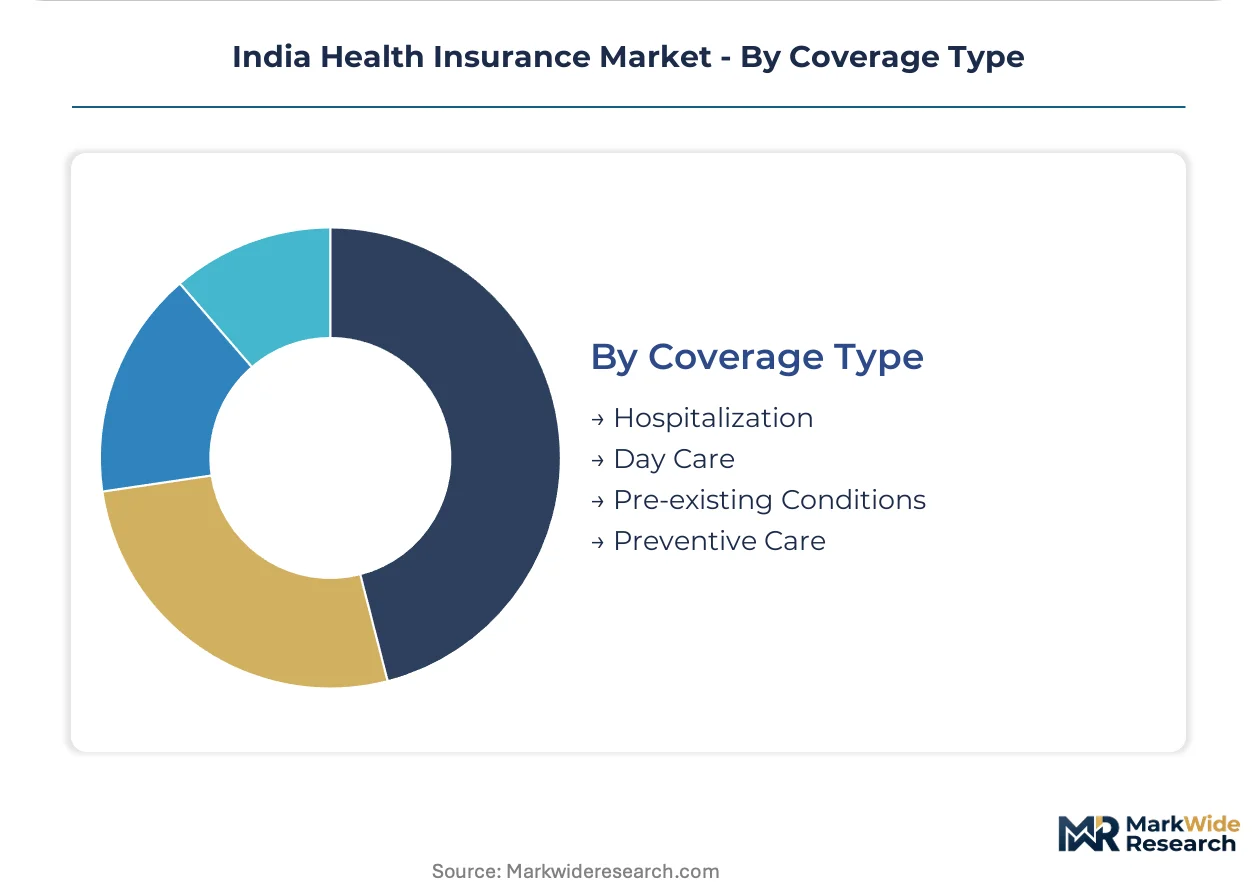
Coverage Type:
Application context dictates underwriting rigor and claim frequency, with preventive care emerging as a retention tool rather than risk transfer.
- Hospitalization:In-patient treatment coverage with cashless network access. Private bed density in Maharashtra and Karnataka enables insurer-provider rate negotiations that contain loss ratios.
- Day Care:Procedures not requiring overnight admission, including dialysis and chemotherapy.
- Pre-existing Conditions:Coverage for diagnosed ailments after mandatory waiting periods.
- Preventive Care:Annual health check-ups and vaccination benefits.
By claim frequency, Hospitalization generates volume. By member retention impact, Preventive Care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRDAI's regulatory framework governs premium flows concentrated in western and southern states where hospital network density enables viable risk-pooling. State-level policy incentives and urban income concentration shape geographic penetration patterns.
Maharashtra
Mumbai and Pune's salaried workforce drives employer-sponsored group policy volumes through portability programs. The state's PLI scheme for healthcare infrastructure expands private bed capacity in tier-two cities like Nagpur and Nashik. Thane district hosts the highest concentration of insurer back-office operations processing Maharashtra's cashless claims.
Karnataka
Bengaluru's IT services sector absorbs comprehensive family floater products with outpatient benefits and international second opinion coverage. The state's sandbox framework permits live testing of usage-based health products with embedded wearables. Mysuru and Mangaluru emerging as telemedicine integration hubs for policy-linked remote consultations.
Gujarat
Surat and Ahmedabad's manufacturing workforce generates demand for corporate wellness-linked group covers. The state pilots blockchain-based smart contracts for cashless hospitalization approvals through third-party administrator partnerships. Vadodara's medical device cluster supports insurer-provider rate negotiations containing loss ratios.
Tamil Nadu
Chennai's hospital density enables risk-pooling at scale with reduced per-policy acquisition costs relative to dispersed geographies. The state's nuclear families favor family floater structures despite single large claims exhausting coverage. Coimbatore's textile belt sees rising subscription-based micro-policy uptake among gig economy workers.
Delhi-NCR
The National Capital Region's senior citizen population drives elevated-margin plan categories facing stricter underwriting scrutiny. IRDAI's Bima Sugam platform compresses price discovery cycles for digitally literate buyers in Gurugram and Noida. Faridabad's industrial corridor anchors corporate group policy penetration among mid-sized enterprises.
India Health Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in India's health insurance market. The top tier commands agency-heavy distribution networks and bancassurance partnerships that sustain premium velocity. Specialist players occupy digital-first issuance and corporate wellness integration archetypes. Competitive moves concentrate on API-based distribution partnerships with fintech aggregators and AI-powered claims triage systems reducing fraud leakage.
Within the agency-dominant tier, Star Health and Allied Insurance Co. Pvt. Ltd. and New India Assurance Co. Ltd. represent traditional distribution models. ICICI Lombard General Insurance Company Limited exemplifies bancassurance leverage through KYC-verified customer bases. HDFC ERGO General Insurance Company Limited occupies the corporate wellness-linked group cover position anchoring commercial portfolios.
| Leading Market Players |
|---|
| Star Health and Allied Insurance Co. Pvt. Ltd. |
| HDFC ERGO General Insurance Company Limited |
| ICICI Lombard General Insurance Company Limited |
| Bajaj Allianz General Insurance Company Limited |
| Niva Bupa Health Insurance Company Limited |
| Care Health Insurance Company Limited |
| Aditya Birla Health Insurance Co. Limited |
| New India Assurance Co. Ltd. |
| Tata AIG General Insurance Company Limited |
| Others |
Pricing and Supply Chain Analysis
Digital-first policy issuance replacing paper-heavy agency networks simultaneously redistributes underwriting capacity toward tier-two cities and compresses commission loadings that historically inflated premium structures. This substitution dynamic reshapes supply geography by decoupling distribution from physical branch infrastructure while pricing economics shift toward lower acquisition-cost models.
Pricing Analysis
Maharashtra and Karnataka command premium spreads 15-20% above national medians due to hospital network density enabling favorable insurer-provider rate negotiations. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by outpatient benefit inclusion and international second opinion access. Cost compression in basic tiers intensifies because bancassurance partnerships squeeze traditional brokerage commissions. Gig economy workers in urban Maharashtra exhibit highest price sensitivity, while corporate group purchasers absorb premium loads for comprehensive family floater structures.
Supply Chain Analysis
Inbound logistics costs for wearable-enabled policy devices face intermittent pressure from container availability constraints on Asia-Pacific trade lanes serving Bengaluru and Mumbai distribution hubs. Core underwriting capacity concentrates in India, with reinsurance support drawing from Singapore and London markets. Actuarial talent scarcity and legacy IT infrastructure dependencies create single-source vulnerability in policy administration systems. Distribution runs through hybrid models blending API-based fintech partnerships with persistent agent networks in rural penetration zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
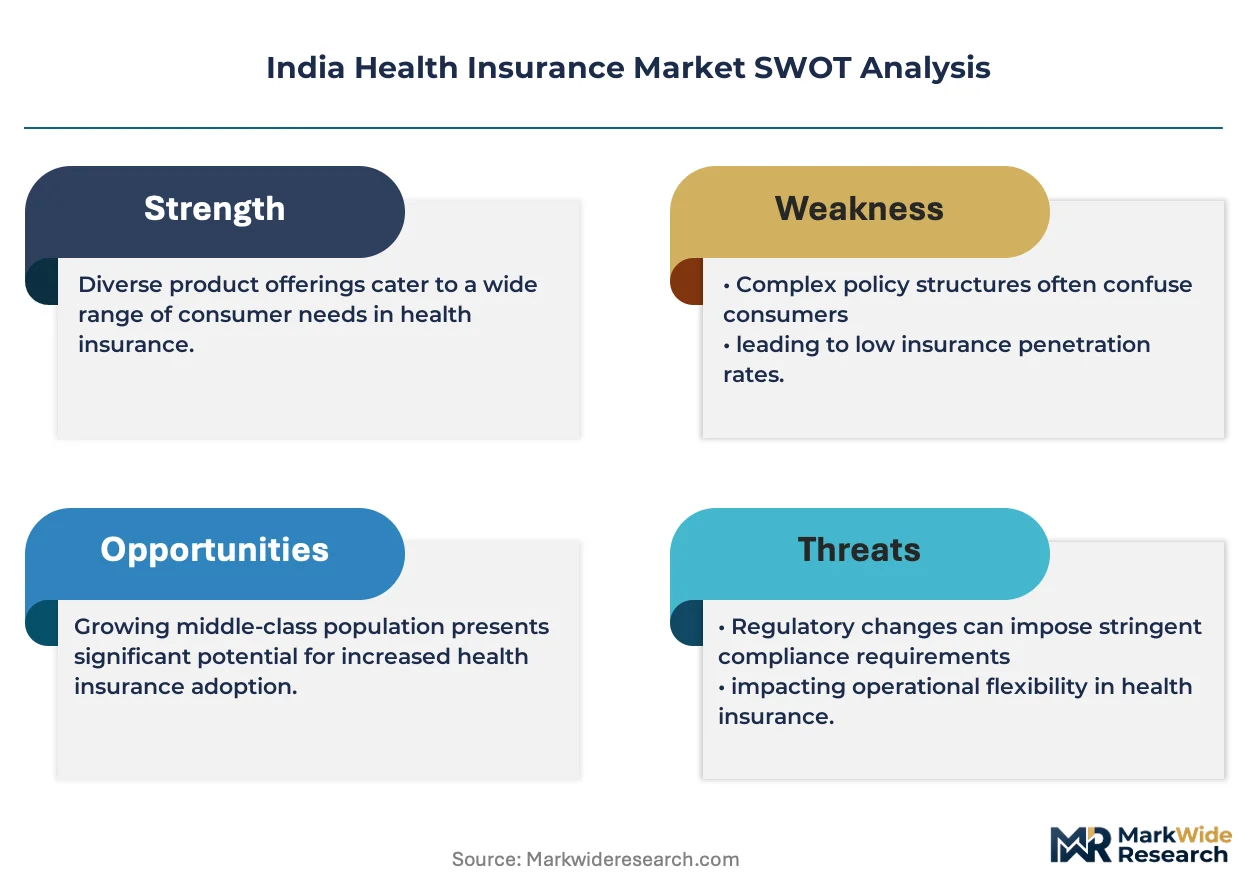
India's health insurance market represents a high-growth disruption justified by IRDAI's regulatory sandbox compressing product approval timelines from years to months while mandating price transparency through the Bima Sugam digital platform.
For Market Incumbents: Fortify agency network control in Karnataka and Maharashtra rural belts against digital aggregator encroachment. Deepen backward integration into hospital network rate negotiations to preserve margin structure amid Bima Sugam-driven price transparency. Prioritize AI-powered claims triage investments to reduce fraud leakage that currently erodes renewal economics. For New Entrants and Emerging Players: IRDAI sandbox certification fast-tracks unlock white-space access in subscription-based micro-policies for gig economy workers across Tamil Nadu textile belts. Target corporate wellness-linked group covers in Gujarat's manufacturing corridor where mid-sized enterprises seek preventive health program bundling. Deploy telemedicine-embedded products as the primary go-to-market angle to differentiate from legacy hospitalization-only structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital-first insurers possessing API infrastructure but lacking agency network scale. Long-term viability hinges on underwriting discipline across the analysis window rather than premium volume capture. Watch reinsurance panel appetite for senior citizen plan categories as the inflection indicator for margin sustainability in aging-demographic segments.| Strategic Initiative | Industry Significance |
|---|---|
| Bima Sugam Platform Integration | IRDAI's unified marketplace mandates price transparency that bypasses traditional commission hierarchies. |
| AI-Powered Claims Triage | Machine learning validation of hospital bills reduces fraud leakage while accelerating settlement cycles. |
| Telemedicine Policy Embedding | Remote consultation protocols lower claim frequency for minor ailments while improving member retention metrics. |
| Corporate Wellness Partnership | Mid-sized enterprises in manufacturing and IT services seek group covers linked to preventive health programs. |
| Blockchain Smart Contract Pilot | Gujarat and Tamil Nadu pilots compress cashless approval timelines from weeks to hours through administrator displacement. |
Research Methodology
Desk research of IRDAI regulatory filings, insurer solvency disclosures, and hospital network databases preceded structured interviews with chief underwriting officers, actuarial heads, bancassurance distribution leads, and third-party administrator operations directors. Primary fieldwork combined with secondary validation against RBI consumer protection circulars and PLI scheme implementation reports. Bottom-up policy issuance data triangulated against top-down premium flow analysis across the analysis window.
Variance decomposition separates volume growth from pricing mix effects across policy type, plan category, distribution channel, and coverage type dimensions. CAGRs derive from segmented regression incorporating hospital bed density indices, telemedicine adoption curves, and regulatory sandbox approval velocity. Forecast inputs include actuarial talent pipeline projections and reinsurance panel risk appetite assessments for aging-demographic products.
Decision-makers should treat outputs as directional under assumptions of sustained IRDAI regulatory support for digital-first issuance and stable hospital network expansion in tier-two cities; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
General Insurance Market
Insurance
Online Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Property Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
US Extended Warranty Market
Insurance
Road Assistance Insurance Market
Insurance
Financial Guarantee Market
Insurance
USA Travelers Insurance Market
Insurance
UK Dental Insurance Market
Insurance
Factory and Warehouse Insurance Market
Insurance
Business Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Germany Reinsurance Market
Insurance
China Parametric Insurance Market